
 Oxygenated Solvents Market | 2026-2036
Oxygenated Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygenated Solvents Market Analysis
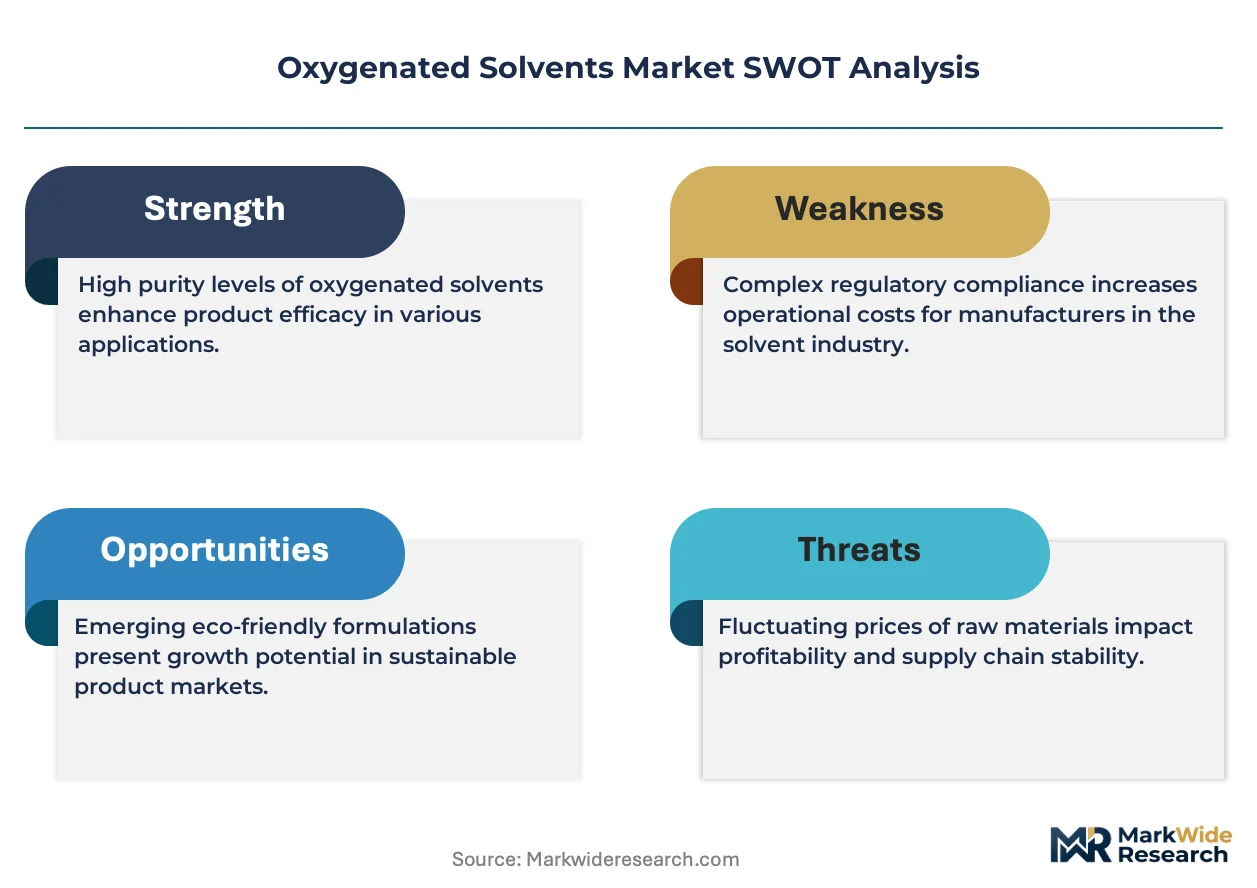
The EU Green Deal is broadening the addressable market for low-carbon oxygenated solvents across European coatings and adhesives supply chains. BASF SE leverages its integrated Verbund production network to sustain cost-advantaged supply of bio-based glycol ethers. Eastman Chemical Company anchors its position through specialized ester solvents for high-performance coatings. Arkema Group differentiates via fluorinated and oxygenated solvent blends serving semiconductor cleaning applications.
Oxygenated solvents are organic liquids containing oxygen atoms in their molecular structure, typically exhibiting polarity, moderate-to-high solvency power, and controlled evaporation rates measured by relative evaporation speed compared to n-butyl acetate. These compounds function primarily as active solvents, co-solvents, or diluents in formulations where they dissolve resins, adjust viscosity, or control drying characteristics. Alcohol-based oxygenated solvents occupy the largest volume share due to their versatility across waterborne and solvent-borne systems, while ester solvents command premium positioning in pharmaceutical extraction and electronics-grade cleaning where ultra-low residue specifications apply. Ketone solvents lead in paint thinning applications where strong solvency and fast evaporation prove essential.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain traditional hydrocarbon solvent use, directly expanding oxygenated solvent substitution in industrial cleaning and coating operations. REACH registration requirements in Europe enforce comprehensive toxicity testing that favors established oxygenated solvent producers with dedicated compliance infrastructure. FDA oversight of residual solvent limits in pharmaceutical manufacturing shapes specification requirements for USP-grade ester and alcohol products. Stakeholders must monitor evolving state-level VOC regulations and bio-preferred procurement mandates to anticipate specification shifts before they ripple through contract formulations.
Market Dynamics
Waterborne coating technologies are displacing solvent-based systems across automotive and architectural applications, forcing oxygenated solvent suppliers to reformulate for lower-VOC compatibility while maintaining solvency performance. This transition compresses margins for legacy hydrocarbon producers and rewards chemical innovators with bio-based glycol ether capabilities.
Growth Catalysts
- EPA National Emission Standards for Hazardous Air Pollutants:These regulations constrain traditional hydrocarbon solvent use in industrial cleaning and coating operations, directly expanding oxygenated solvent substitution.
- China's industrial production scale:Domestic chemical capacity and concentrated procurement patterns in manufacturing hubs create sustained volume demand for alcohol-based and ester oxygenated solvents.
- Semiconductor cleaning applications:Fluorinated and oxygenated solvent blends serve precision electronics manufacturing where ultra-low residue specifications apply, opening premium specification tiers.
Market Restraints
- Ethylene oxide feedstock volatility:Glycol ether production depends on ethylene oxide availability, exposing margins to petrochemical price swings and supply interruptions.
- REACH registration requirements:Comprehensive toxicity testing mandates in Europe favor established producers with dedicated compliance infrastructure, raising barriers for new entrants.
- Waterborne system substitution:Advances in waterborne coating performance reduce co-solvent loading requirements in some architectural paint formulations.
Strategic Opportunities
- EU Green Deal low-carbon mandates:Bio-preferred procurement policies and carbon border adjustments expand addressable market for bio-based oxygenated solvents across European coatings and adhesives supply chains.
- Pharmaceutical extraction grade esters:USP-grade specifications for residual solvent limits in drug manufacturing create premium positioning for ultra-purity ester products.
- Semiconductor fabrication expansion:Advanced node chip manufacturing in Taiwan and South Korea drives demand for electronics-grade oxygenated solvents with particulate and moisture controls.
Industry Challenges
- Specialized chemical engineering talent:Formulation chemists with expertise in VOC-compliant solvent design remain scarce relative to expansion needs in coating and cleaning segments.
- Multi-jurisdiction compliance synchronization:Divergent state-level VOC regulations across US markets force redundant testing and registration investments for national product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygenated Solvents Market |
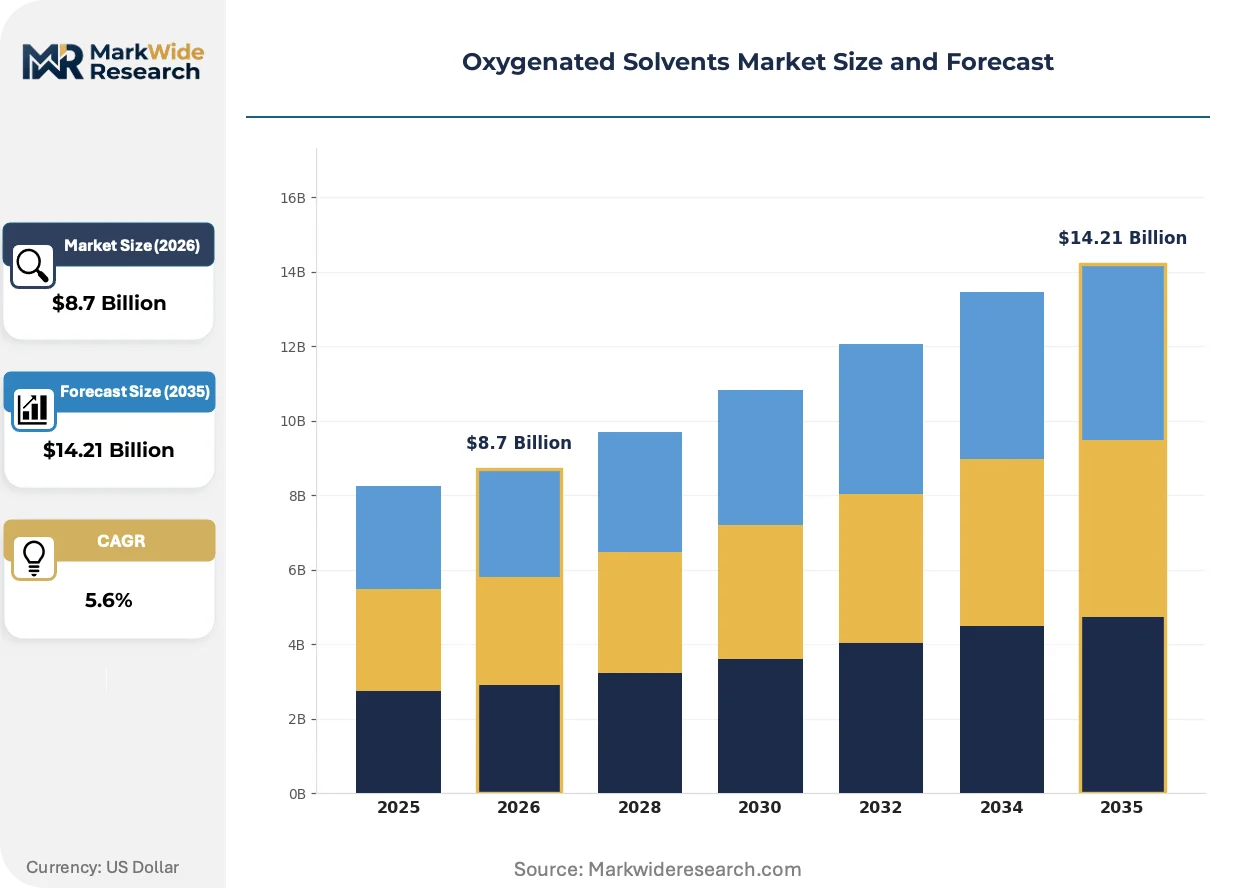
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohols, Ketones, Ethers, Esters End User: Paints, Coatings, Adhesives, Pharmaceuticals Application: Industrial Cleaning, Paint Thinning, Extraction, Degreasing Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | BASF SE, ExxonMobil Corporation, The Dow Chemical Company, Eastman Chemical Company, Arkema Group, LyondellBasell Industries N.V., Solvay SA, OQ Chemicals GmbH, Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygenated Solvents Market Emerging Trajectories
Bio-based feedstock integration and digital formulation tools are restructuring how oxygenated solvents are developed, tested, and specified across coating and cleaning supply chains. These shifts compress product development cycles while raising performance benchmarks.
Enzymatic catalysis for bio-based glycol ether production is integrating into commercial manufacturing, converting renewable feedstocks into oxygenated solvents with identical performance profiles to petrochemical equivalents. European coatings manufacturers are adopting these materials at accelerating rates to meet Scope 3 emissions targets. The technology is integrating carbon accounting directly into procurement specifications, forcing traditional producers to demonstrate feedstock provenance or lose specification status.
REACH authorization amendments are tightening restrictions on substances of very high concern in solvent formulations, compelling reformulation investments across industrial cleaning product lines. Manufacturers must submit substitution plans for legacy glycol ethers with reproductive toxicity profiles. Specialty coating segments in Germany and France are responding fastest, with automotive OEMs now requiring pre-approval of all solvent constituents in supplier coatings.
Specification-driven procurement now dominates large coating contracts, with buyers mandating full chemical disclosure and lifecycle assessment documentation before supplier qualification. Distributor networks are consolidating technical service capabilities to support this transition, displacing traditional price-volume relationships. This pattern is most visible in North American automotive refinish and OEM coating supply chains, where Tier 1 suppliers enforce solvent transparency down to raw material sources.
Oxygenated Solvents Market Segmentation
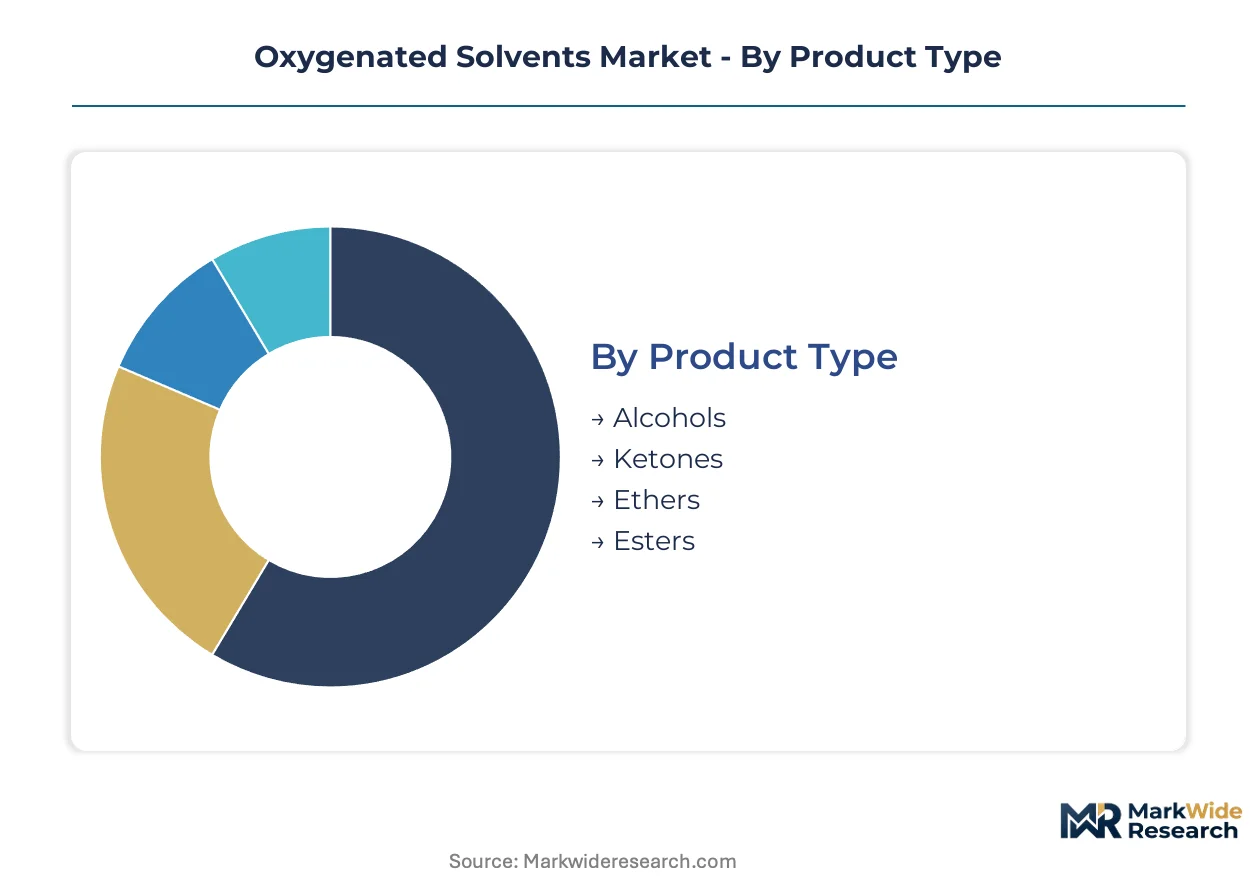
Oxygenated solvent procurement patterns diverge sharply across product chemistries and end-use specifications. Formulation requirements for VOC compliance, residue limits, and evaporation profiles create distinct demand clusters that reshape supplier priorities.
Product Type:
Technical specification hierarchies separate commodity alcohols from specialty esters and fluorinated ethers. Molecular polarity, boiling point ranges, and feedstock provenance determine pricing tiers and qualification barriers.
- Alcohols:These solvents contain hydroxyl functional groups delivering moderate polarity and water miscibility for waterborne coating systems. Methanol, ethanol, and propanol variants dominate architectural paint formulations in China and the United States where EPA VOC limits constrain hydrocarbon alternatives. Alcohols lead on scale; esters lead on momentum.
- Esters:Carboxylic acid esters provide strong resin solvency with controlled evaporation rates for high-performance coatings and pharmaceutical extraction. Electronics-grade butyl acetate and specialty glycol esters command premium positioning in semiconductor cleaning applications across Taiwan and South Korea where particulate specifications exceed 99.99% purity thresholds.
- Ketones:Carbonyl-functional solvents deliver aggressive solvency for nitrocellulose lacquers and epoxy thinners.
- Ethers:Glycol ethers balance water solubility with organic compatibility, serving as co-solvents in waterborne industrial coatings.
Alcohols dominate volume procurement; esters capture value expansion.
End User:
Customer sophistication levels range from specification-driven pharmaceutical manufacturers to price-sensitive architectural coating blenders. Regulatory exposure varies dramatically across these segments.
- Paints:Architectural and decorative coating manufacturers drive bulk alcohol consumption for interior and exterior emulsion systems. Chinese construction activity and U.S. housing renovation cycles concentrate demand in these formulations where cost efficiency outweighs performance premiums.
- Coatings:Industrial OEM and automotive refinish segments impose stringent VOC and hazardous air pollutant compliance requirements. Automotive OEMs in Germany and France now mandate full solvent constituent disclosure through REACH-compliant supply chains, favoring established oxygenated solvent producers with dedicated registration infrastructure.
- Adhesives:Pressure-sensitive and structural adhesive formulations utilize ester and ether solvents for tack control and open-time adjustment.
- Pharmaceuticals:Active pharmaceutical ingredient extraction and residual solvent compliance under FDA and EMA guidelines require USP-grade ester products with documented purity certificates.
Coatings anchor revenue concentration; pharmaceuticals drive margin expansion.
Application:
Functional performance requirements separate precision cleaning applications from bulk paint modification uses. Residue tolerance, evaporation speed, and substrate compatibility define specification boundaries.
- Industrial Cleaning:Precision electronics and metal finishing operations demand oxygenated solvents with ultra-low residue and controlled moisture content. Semiconductor fabrication facilities in Taiwan and South Korea specify electronics-grade glycol ethers and fluorinated blends for wafer cleaning where particle counts must remain below Class 100 standards.
- Paint Thinning:Architectural and industrial coating viscosity adjustment consumes alcohol and ketone solvents in high volumes. EPA National Emission Standards for Hazardous Air Pollutants accelerate oxygenated solvent substitution for traditional mineral spirits in U.S. industrial maintenance coating operations.
- Extraction:Pharmaceutical and natural product processing utilizes ester solvents for selective compound isolation.
- Degreasing:Metal preparation and machinery maintenance applications employ oxygenated solvents for oil and lubricant removal.
Industrial cleaning commands specification premiums; paint thinning drives volume throughput.
Distribution Channel:
Supply chain configuration reflects customer scale, technical service requirements, and geographic concentration of demand. Direct relationships dominate large coating manufacturers while fragmented markets sustain distributor networks.
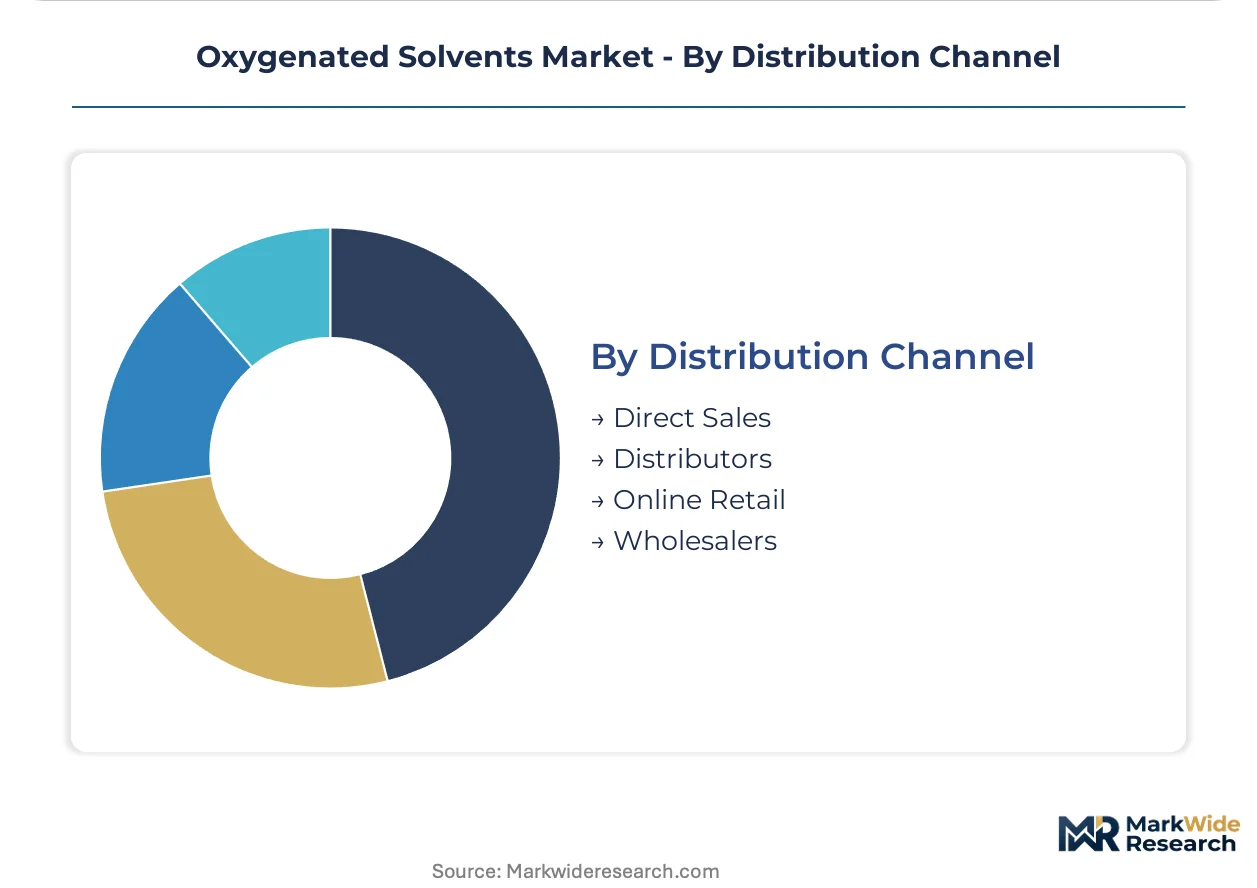
- Direct Sales:Large coating manufacturers and pharmaceutical producers negotiate annual contracts with integrated solvent suppliers for dedicated tanker deliveries. BASF SE and Eastman Chemical Company leverage direct channels to secure formulation partnerships with automotive OEMs requiring technical service support and just-in-time inventory management.
- Distributors:Regional chemical distributors consolidate small-to-mid volume procurement for independent paint manufacturers and industrial cleaning operators. These intermediaries increasingly bundle technical compliance documentation to support customer REACH and EPA registration requirements.
- Online Retail:E-commerce platforms serve maintenance, repair, and operations procurement for small industrial users.
- Wholesalers:Bulk volume aggregators supply commodity alcohols to downstream blenders and repackagers.
Direct sales capture strategic accounts; distributors defend geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineering established the foundational production methods for oxygenated solvents during the early industrial period. Contemporary demand patterns reflect this heritage while shifting toward Asia-Pacific manufacturing centers and North American regulatory-driven substitution cycles.
China
Industrial coating production and pharmaceutical manufacturing anchor oxygenated solvent consumption across the Yangtze River Delta. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate bio-based solvent adoption in state-owned chemical enterprises. Shanghai and Jiangsu province concentrate glycol ether manufacturing capacity serving domestic automotive OEMs.
Germany
Automotive OEM coating specifications and REACH compliance infrastructure drive premium ester solvent demand. The Federal Environment Agency implements EU Green Deal carbon border adjustments that favor low-carbon oxygenated solvents in supplier qualifications. The Rhine-Ruhr industrial corridor hosts integrated Verbund production networks supplying coatings manufacturers across Bavaria and Baden-Württemberg.
United States
Architectural paint renovation cycles and industrial maintenance coating operations sustain alcohol-based solvent volumes. EPA National Emission Standards for Hazardous Air Pollutants constrain traditional hydrocarbon use in metal finishing and aerospace applications. Texas Gulf Coast petrochemical complexes and Ohio River Valley manufacturing hubs concentrate blending and distribution infrastructure.
South Korea
Semiconductor fabrication expansion and electronics-grade cleaning specifications propel ultra-purity glycol ether demand. The Ministry of Environment enforces VOC emission caps in industrial zones that displace conventional solvents. The Gyeonggi-Seoul corridor and Busan-Ulsan industrial complex host precision chemical suppliers serving Samsung and SK Hynix fabrication facilities.
India
Pharmaceutical API extraction and generic drug manufacturing create USP-grade ester solvent requirements. The Central Pollution Control Board implements revised solvent emission norms under the National Clean Air Programme. Gujarat's chemical manufacturing belt and Maharashtra's pharmaceutical clusters concentrate import-dependent oxygenated solvent consumption.
Oxygenated Solvents Market Vendor Landscape
Premium-margin players sit above commodity-margin players across specification tiers, with electronics-grade and pharmaceutical-grade products commanding substantial price premiums over industrial coating grades. The market exhibits moderate consolidation among integrated petrochemical producers while specialty ester and bio-based segments sustain fragmented specialist competition. Three archetypes dominate: integrated chemical conglomerates with Verbund advantages, regional specialists in high-purity grades, and bio-based technology licensors. Capacity expansion in Asia-Pacific and strategic partnerships for bio-feedstock sourcing represent the dominant competitive vectors.
Within the integrated chemical conglomerate tier, BASF SE and Eastman Chemical Company exemplify archetypes with differentiated positioning. BASF SE anchors the European supply base through its Ludwigshafen production network. Eastman Chemical Company occupies a position emphasizing specialty ester capabilities. Arkema Group represents the fluorinated and oxygenated blend specialist archetype serving precision electronics applications. These three entities illustrate how geographic origin and implied structural form shape competitive positioning without dictating specific strategic actions.
| Leading Market Players |
|---|
| BASF SE |
| ExxonMobil Corporation |
| The Dow Chemical Company |
| Eastman Chemical Company |
| Arkema Group |
| LyondellBasell Industries N.V. |
| Solvay SA |
| OQ Chemicals GmbH |
| Shell plc |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon border adjustments gate qualified supply access and premium-tier pricing power for oxygenated solvent producers serving European coatings manufacturers. This environmental mandate forces documentation of feedstock provenance and lifecycle emissions, creating a bifurcated market where certified low-carbon products command substantial premiums over uncertified alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electronics-grade esters from industrial coating alcohols and commodity glycol ethers. Price differentiation hinges on purity certification and volume scale, with pharmaceutical USP-grade products least sensitive to cost pressure. Pricing pressure stems from ethylene oxide feedstock volatility compressing margins for glycol ether producers. Architectural coating blenders exhibit highest price sensitivity, while semiconductor fabricators prioritize specification compliance over unit cost.
Supply Chain Analysis
Freight cost differentials between China and Europe are reshaping regional sourcing strategies for oxygenated solvent buyers. Supply concentrates in China, Germany, and the United States, with production anchored in petrochemical corridors along the Yangtze River Delta, Rhine-Ruhr industrial corridor, and Texas Gulf Coast. Raw material dependencies draw from ethylene oxide, bio-based feedstocks, and acetic acid derivatives. Single-source vulnerability around ethylene oxide supply creates structural risk for glycol ether manufacturers. Distribution runs through direct tanker deliveries for large coating OEMs and regional distributors for fragmented industrial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where regulatory divergence between EU carbon border adjustments and US state-level VOC mandates creates cost and compliance differentials for multi-jurisdiction suppliers.
For Market Incumbents: To counter waterborne coating substitution threatening co-solvent volumes, BASF SE and Eastman Chemical Company should deepen backward integration into bio-based feedstock supply while expanding technical service capabilities to defend formulation partnerships with automotive OEMs requiring REACH-compliant solvent disclosure. For New Entrants and Emerging Players: Regional distributors represent the most accessible channel partner type for penetrating India's pharmaceutical API extraction segment, where import-dependent USP-grade ester demand outpaces domestic supply. Target Gujarat's chemical manufacturing belt with technical documentation bundles supporting Central Pollution Control Board compliance. For Investors and Strategic Acquirers: Roll-up economics work for specialty ester and bio-based technology licensors because fragmented high-purity segments lack scaled competitors with integrated compliance infrastructure. Monitor semiconductor fabrication expansion in Taiwan and South Korea as the inflection signal for electronics-grade oxygenated solvent demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures Scope 3 emissions compliance for EU Green Deal supplier qualifications. |
| Electronics-Grade Capacity Expansion | Captures premium positioning in Taiwan and South Korea semiconductor cleaning markets. |
| Long-Term Supply Agreement with Automotive OEMs | Locks in formulation partnerships requiring full solvent constituent disclosure. |
| Joint Venture for Regional Distribution | Penetrates India's import-dependent pharmaceutical ester market through local compliance infrastructure. |
| Green Manufacturing Transition | Enzymatic catalysis for bio-based glycol ethers meets accelerating European coatings procurement specifications. |
Methodological Framework
Direct dialogue with plant managers, procurement leads at downstream coating OEMs, distribution channel partners, and technical R&D directors grounded the qualitative foundation of this analysis. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA regulatory documentation. Bottom-up volume estimates from individual production facilities triangulated against top-down demand assessments from end-use industries.
Segment-level value and volume outputs across the analysis window reflect disaggregation by grade tier, end-use industry, regional production hub, and feedstock provenance. CAGRs were derived from regression analysis of historical consumption patterns and projected regulatory-driven substitution rates. Key forecast inputs included EPA National Emission Standards compliance timelines and China's dual carbon policy implementation pace.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ethylene oxide supply disruptions and REACH authorization amendments affecting glycol ether formulations. Forecasts reflect documented assumptions about regulatory enforcement intensity and waterborne coating performance advances. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Hydrofluoroether Market
Solvents
Isopropylamine Market
Solvents
Butane Market
Solvents
Hydrosol Market
Solvents
Alpha-Methylstyrene Market
Solvents
Diethanolamide Market
Solvents
Ortho-Xylene Market
Solvents
Ketene Market
Solvents
Wax Dispersion Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Toluene Market
Solvents
North America Acetonitrile Market
Solvents
Global Acetonitrile Market
Solvents
Global Solvents Market
Solvents
Methyl Isopropyl Ketone Market
Solvents
Solvent Cement Market