
 Dimethyl Formamide Market | 2026-2036
Dimethyl Formamide Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethyl Formamide Market Outlook
Pharmaceutical synthesis is expanding as the fastest-growing end-use vertical for dimethyl formamide, displacing traditional textile dominance in volume terms. BASF SE leverages its integrated Ludwigshafen complex to sustain captive supply advantages across European pharma corridors. Mitsubishi Gas Chemical Company anchors Asian supply through its Yokkaichi operations, while Jiutian Chemical Group dominates Chinese domestic distribution via its coal-based production backbone.
Dimethyl formamide is a polar aprotic solvent with the chemical formula (CH3)2NCHO, manufactured primarily through the reaction of dimethylamine with carbon monoxide in a methyl formate process, valued for its high solvency power and low evaporation rate in industrial applications. The solvent product type occupies the largest volume share, reflecting entrenched demand from polyurethane coating systems and acrylic fiber spinning baths. Reagent-grade DMF for pharmaceutical peptide synthesis represents the fastest-growing segment, where margin pools concentrate due to stringent purity certifications and batch traceability requirements.
EPA regulations in the United States classify DMF as a hazardous air pollutant under the Clean Air Act, forcing domestic producers to install carbon adsorption recovery systems or face permit restrictions. REACH registration requirements in Europe mandate comprehensive toxicological dossiers, elevating compliance costs for importers and favoring established registrants like Merck KGaA. China's MEE enforces dual carbon-aligned emissions intensity targets that reshape capacity expansion decisions. Stakeholders must monitor regulatory divergence between jurisdictions to optimize production location and product grade portfolios.
Market Dynamics
Pharmaceutical synthesis demand is concentrating around high-purity DMF grades, while China's MEE emissions intensity targets force coal-based producers toward carbon capture retrofits or capacity consolidation.
Growth Catalysts
- Peptide synthesis expansion:Contract development and manufacturing organizations in Switzerland and Singapore are scaling peptide drug pipelines that require reagent-grade DMF with batch-level impurity tracking.
- REACH registration moats:Established dossiers under ECHA toxicological requirements create compliance barriers that protect incumbent European suppliers from price-driven import competition.
- East Asian manufacturing clustering:Chemical corridors around Shanghai and Jiangsu province concentrate polyurethane coating demand from automotive OEMs and electronics assemblers.
Market Restraints
- Methanol feedstock volatility:Coal-to-methanol economics in China swing with thermal coal pricing, transmitting cost instability to DMF contract structures.
- Substitution pressure from NMP:N-methyl-2-pyrrolidone competes for lithium-ion battery electrode coating applications where DMF historically dominated.
- EPA hazardous air pollutant classification:Carbon adsorption recovery mandates under the Clean Air Act add capital intensity to US production economics.
Strategic Opportunities
- Bio-based DMF pathways:Carbohydrate-derived dimethylamine feedstocks align with EU Green Deal carbon border adjustment mechanisms for export-oriented European producers.
- India pharmaceutical manufacturing:CDSCO bulk drug park incentives in Gujarat and Andhra Pradesh attract solvent suppliers to co-locate with generic API producers.
- Digital batch traceability:Blockchain-anchored certificates of analysis open premium pricing tiers for pharma-grade DMF through audit-ready documentation.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry operators with residual solvent quantification expertise command wage premiums that inflate quality control overhead.
- Legacy reactor retrofit timelines:Continuous flow process conversions from batch methanol carbonylation require 18-24 month engineering cycles that defer margin recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethyl Formamide Market |
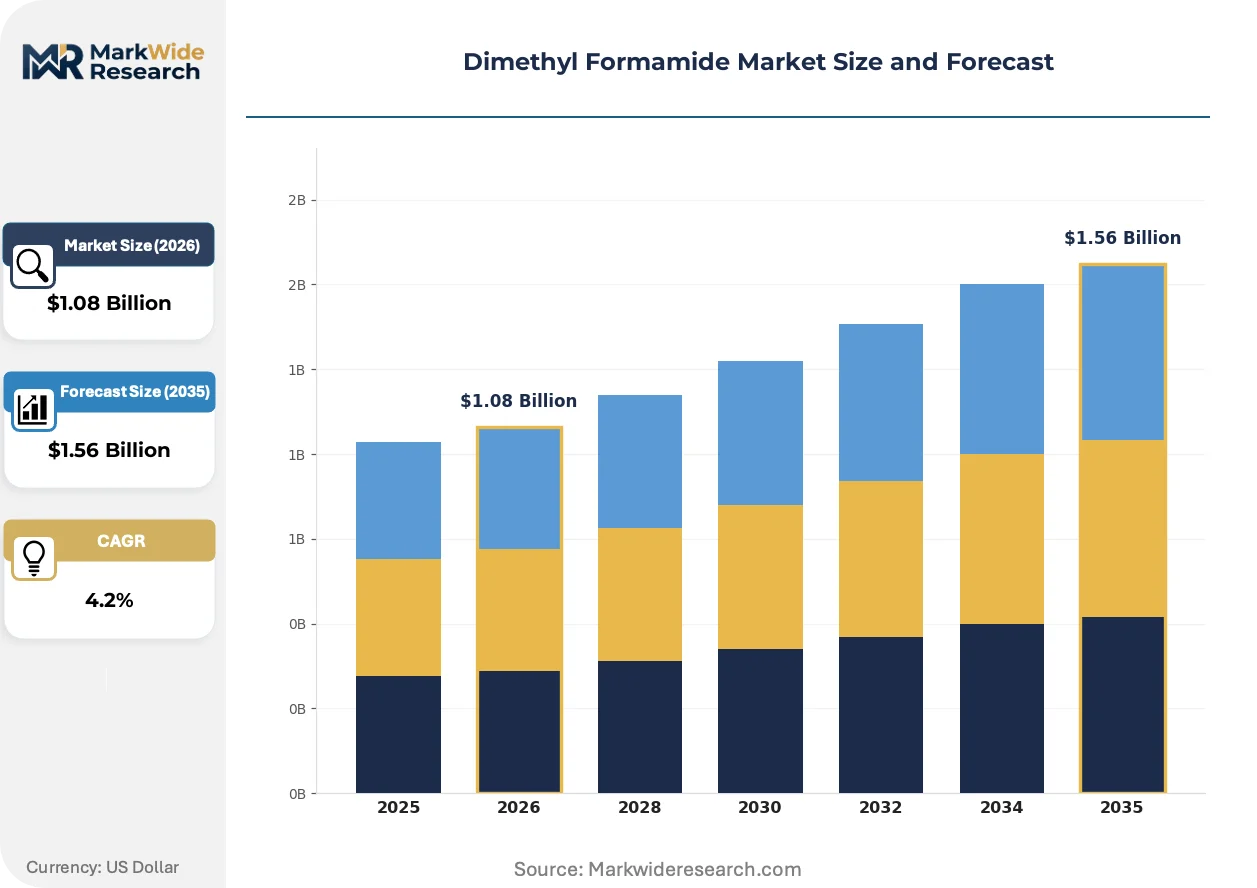
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.56 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Reagent, Intermediate, Additive End Use Industry: Textiles, Pharmaceuticals, Chemicals, Electronics Application: Coatings, Adhesives, Inks, Seals Distribution Channel: Direct Sales, Online, Distributors, Retail |
| Companies Covered | BASF SE, Eastman Chemical Company, Mitsubishi Gas Chemical Company, Inc., Honeywell International Inc., Jiutian Chemical Group Limited, Luxi Chemical Group Co., Ltd., Shandong Hualu Hengsheng Chemical Co., Ltd., Merck KGaA, The Chemours Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethyl Formamide Market Strategic Shifts
Process intensification and purity-grade stratification are compressing the technology frontier for DMF manufacturing, while regulatory alignment across jurisdictions emerges as a competitive differentiator.
Membrane separation technology for DMF recovery is consolidating solvent recycling economics in textile spinning operations. Acrylic fiber producers in Turkey and Indonesia are retrofitting nanofiltration units that cut fresh solvent purchases by half. This technology is consolidating captive recycling as the dominant supply model for integrated fiber-spinning complexes.
China's dual carbon goals under MEE oversight are tightening emissions intensity benchmarks for chemical production. Coal-based DMF manufacturers face 15-20% carbon intensity reduction mandates that favor natural gas feedstock switches or carbon capture investments. Jiangsu province producers are responding with amine scrubbing retrofits to preserve operating permits.
Specification-driven procurement now dominates pharmaceutical solvent buying. CDMOs in Switzerland and Singapore are unbundling solvent supply from toll manufacturing agreements to secure direct batch traceability. This shift concentrates volume with registrants holding ECHA-compliant toxicological dossiers and ISO 17025-accredited testing laboratories.
Dimethyl Formamide Market Segmentation
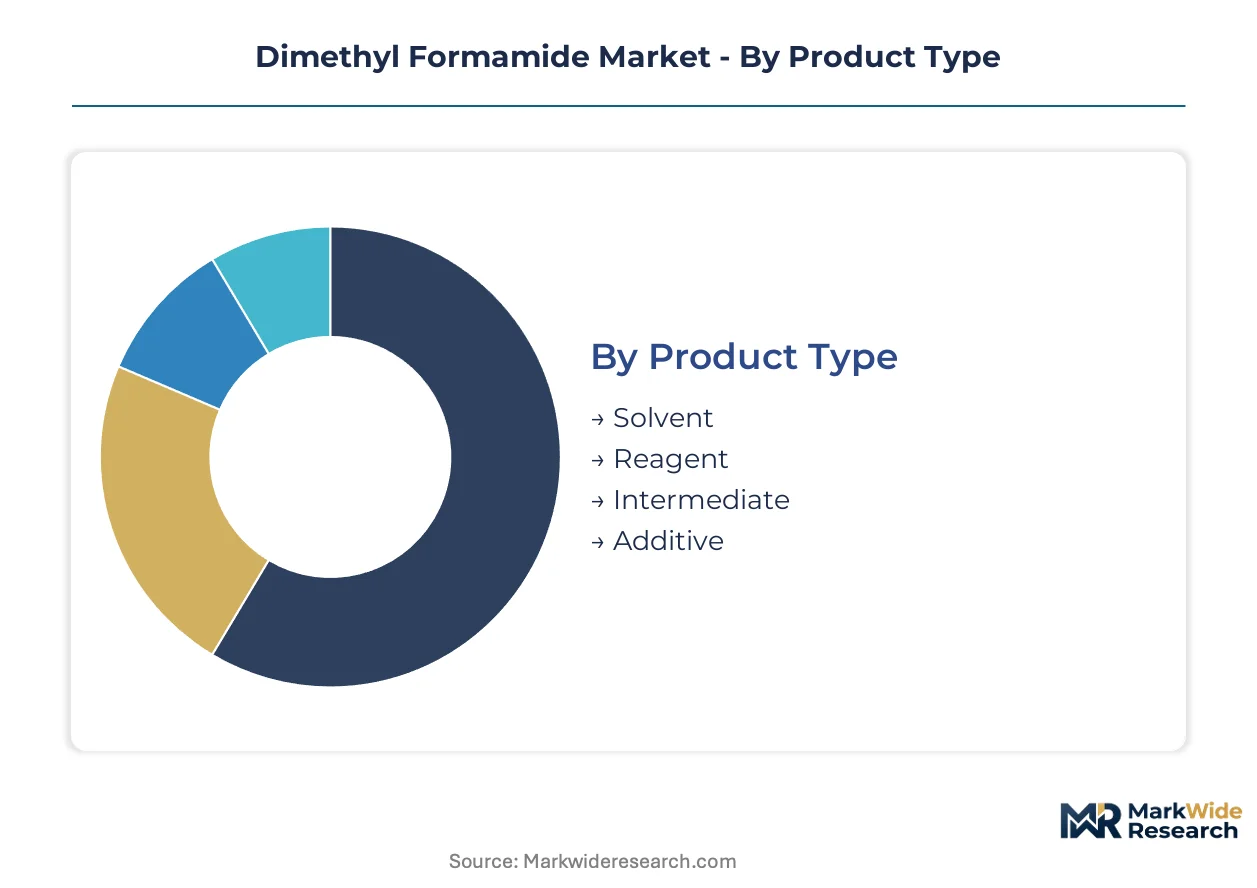
Dimethyl formamide grades vary sharply in purity specifications and certification burdens, creating distinct margin pools that reward precise portfolio positioning. Buyers in peptide synthesis and battery electrode coating impose divergent impurity thresholds that fragment procurement across technical tiers.
Product Type:
Replacement cycles for DMF-containing formulations drive upgrade demand toward higher-purity grades as regulatory dossiers expire and customer specifications tighten.
- Solvent:Industrial-grade DMF serves polyurethane coating systems and acrylic fiber spinning with 99.5% minimum purity. Textile corridors in Turkey and Indonesia anchor volume offtake, though membrane recovery retrofits are compressing fresh solvent purchases by integrated spinners.
- Reagent:Peptide synthesis and pharmaceutical API manufacturing demand 99.9%+ purity with full batch traceability under ECHA REACH dossier requirements. Swiss and Singaporean CDMOs concentrate procurement with registrants holding ISO 17025-accredited laboratories, paying premiums for audit-ready documentation.
- Intermediate:Captive consumption in integrated chemical complexes for pesticide and pharmaceutical precursor synthesis.
- Additive:Minor formulations in polymer processing aids and specialty coating modifiers.
Volume placements concentrate in Solvent; the faster expansion belongs to Reagent.
End Use Industry:
Customer procurement maturity separates industries with specification-driven buying from those with commodity spot purchasing.
- Textiles:Acrylic fiber spinning baths and polyurethane synthetic leather production consume standard-grade solvent. Turkish and Indonesian integrated spinners are retrofitting nanofiltration recovery units that halve fresh DMF intake.
- Pharmaceuticals:Peptide synthesis, API crystallization, and injectable formulation require reagent-grade material with residual solvent validation per ICH Q3C guidelines. ECHA-registered suppliers capture preferential contracting from Swissmedic-inspected facilities.
- Chemicals:Agrochemical intermediate production and specialty chemical synthesis drive intermediate-grade offtake.
- Electronics:Lithium-ion battery electrode coating and photoresist stripping compete with N-methyl-2-pyrrolidone substitution pressure.
Textiles still absorb the largest solvent tonnage; Pharmaceuticals is climbing the fastest on peptide pipeline expansion.
Application:
Performance requirements in film formation and substrate adhesion stratify formulation specifications across industrial segments.
- Coatings:Automotive OEM clearcoats and electronics conformal coatings demand controlled evaporation rates. Jiangsu province chemical corridors around Shanghai concentrate polyurethane system demand from automotive and electronics assemblers.
- Adhesives:Structural bonding in aerospace and automotive applications requires moisture-resistant formulations.
- Inks:Gravure and flexographic printing for flexible packaging.
- Seals:Gasket and O-ring manufacturing for chemical processing equipment.
Coatings dominates volume; Adhesives shows steepest expansion trajectory on lightweighting assembly demand.
Distribution Channel:
Supply chain configuration determines which channel tier captures margin on certification burden and lot traceability.
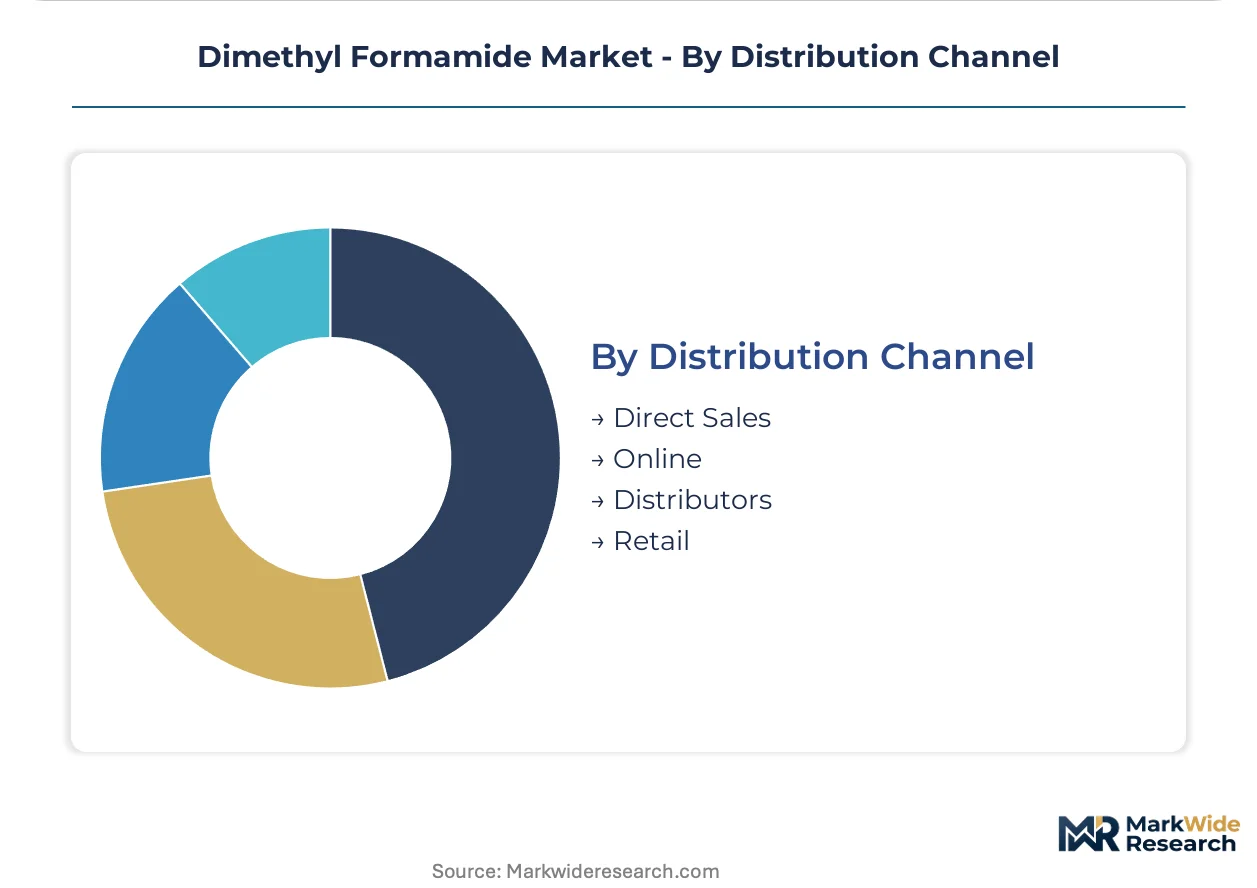
- Direct Sales:Pharmaceutical and electronics manufacturers with validated supplier programs bypass intermediaries for batch-level documentation. ECHA-registered producers like Merck KGaA and Mitsubishi Gas Chemical anchor long-term supply agreements with audit rights.
- Distributors:Regional chemical distributors serve fragmented textile and coatings formulators with stocking inventory and blended truckload logistics.
- Online:E-procurement platforms for standard-grade solvent in research and small-batch industrial applications.
- Retail:Laboratory supply houses for analytical and R&D quantities.
Direct Sales commands the premium tier; Distributors still handle the largest aggregate volume across dispersed industrial accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Lingang Special Area and Jiangsu province's chemical industrial parks concentrate East Asian DMF demand through integrated polyurethane and pharmaceutical manufacturing ecosystems.
China
Coal-based methanol feedstock economics dominate domestic production, with Jiangsu province producers installing amine scrubbing retrofits to meet MEE dual carbon intensity reduction mandates. The Yangtze River Delta chemical corridor around Shanghai anchors polyurethane coating demand from automotive OEMs and electronics assemblers. Shandong province coal-chemical complexes face consolidation pressure as emissions benchmarks tighten.
United States
EPA hazardous air pollutant classification under the Clean Air Act forces domestic producers toward carbon adsorption recovery systems or permit restrictions. Pharmaceutical peptide synthesis demand concentrates around Massachusetts and New Jersey biomanufacturing clusters. The Gulf Coast petrochemical corridor maintains solvent-grade production for coatings and adhesives applications.
Germany
REACH registration requirements under ECHA mandate comprehensive toxicological dossiers that elevate compliance costs for importers. The Ludwigshafen chemical complex sustains integrated DMF production for captive pharmaceutical and agrochemical intermediate consumption. Bavaria-based CDMOs source reagent-grade material with full batch traceability for peptide drug pipelines.
Switzerland
Swissmedic-inspected pharmaceutical manufacturing facilities drive premium-grade solvent procurement with ISO 17025-accredited testing requirements. Basel-area contract development organizations unbundle solvent supply from toll agreements to secure direct documentation chains. The country's precision chemical sector concentrates peptide synthesis demand from global biopharma clients.
India
CDSCO bulk drug park incentives in Gujarat and Andhra Pradesh attract solvent suppliers to co-locate with generic API producers. The country's pharmaceutical manufacturing expansion targets import substitution for reagent-grade DMF currently sourced from European registrants. Maharashtra chemical clusters around Mumbai serve textile spinning and coatings formulation demand.
Dimethyl Formamide Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical complexes holding captive supply advantages in solvent-grade volumes while independent registrants capture pharmaceutical premium tiers. Market structure tilts toward consolidation at the high-purity end where ECHA dossier investments create compliance moats, and fragmentation in standard-grade supply where coal-based Chinese producers compete on feedstock economics. Three archetypes dominate: integrated petrochemical majors with backward methanol control, specialty chemical houses with pharma-grade certification infrastructure, and regional coal-chemical operators serving Asian industrial demand. Competitive moves concentrate on carbon capture retrofits for permit compliance and direct sales relationships with audited pharmaceutical customers.
Among European-anchored registrants, BASF SE and Merck KGaA exemplify the integrated and specialty archetypes respectively, with the former leveraging Ludwigshafen complex economics and the latter holding ECHA-compliant toxicological dossiers for Swiss and Singaporean CDMO supply. Mitsubishi Gas Chemical Company, Inc. occupies a position bridging Asian industrial solvent demand with pharmaceutical-grade export capability from its Yokkaichi operations. Jiutian Chemical Group represents the coal-based Chinese producer archetype, dominating domestic distribution through feedstock integration while facing MEE emissions retrofit requirements.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Mitsubishi Gas Chemical Company, Inc. |
| Honeywell International Inc. |
| Jiutian Chemical Group Limited |
| Luxi Chemical Group Co., Ltd. |
| Shandong Hualu Hengsheng Chemical Co., Ltd. |
| Merck KGaA |
| The Chemours Company |
| Others |
Value Chain & Pricing Dynamics
Captive methanol production in Shandong and Jiangsu province coal-chemical complexes anchors both supply security and pricing power for Chinese DMF manufacturers facing MEE emissions retrofit costs. This backward integration into syngas and methyl formate intermediates insulates integrated producers from methanol spot volatility while forcing merchant buyers to absorb carbon capture capital recovery through contract premiums.
Pricing Analysis
Short lead-time premiums for reagent-grade DMF with ECHA-compliant batch documentation command substantial markups over standard solvent contract structures. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and spot solvent levels reflects certification burden and testing infrastructure investment. Cost compression in standard-grade solvent is intensifying because Turkish and Indonesian textile spinners are retrofitting membrane recovery systems that halve fresh DMF intake. Pharmaceutical CDMOs show least price sensitivity due to regulatory validation requirements, while coatings formulators in dispersed industrial accounts drive hardest bargain negotiations.
Supply Chain Analysis
Specialized analytical chemists with gas chromatography-mass spectrometry expertise command wage premiums in Ludwigshafen, Yokkaichi, and Shanghai chemical corridors, inflating quality control overhead for ECHA-registered producers. Manufacturing concentrates in China, Germany, and Japan through integrated petrochemical complexes and specialty chemical houses. Feedstock draws from coal-based methanol in China, natural gas-derived syngas in Europe, and imported methyl formate streams in select Asian operations. Single-source vulnerability concentrates around Jiangsu province amine scrubbing retrofits required for MEE permit compliance. Distribution runs through direct sales agreements with audited pharmaceutical customers and regional chemical distributors serving fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DMF market functions as a vertical-integration race where control over methanol feedstock and carbon capture infrastructure determines permit retention and margin sustainability. Players are pursuing backward integration into syngas production to escape coal price volatility and emissions compliance cost pass-through.
For Market Incumbents: Acquire carbon capture retrofit assets in Jiangsu and Shandong provinces to preserve MEE operating permits against consolidation pressure. Secure ECHA dossier extensions for reagent-grade certification to defend against emerging bio-based DMF pathways. Lock in direct sales relationships with Swissmedic-inspected CDMOs through ISO 17025-accredited laboratory investments that create audit-ready documentation barriers. For New Entrants and Emerging Players: Generic API manufacturers in Gujarat and Andhra Pradesh bulk drug parks represent an underserved buyer archetype seeking import substitution for European reagent-grade supply. Establish toll manufacturing partnerships with existing ECHA-registered facilities rather than building de novo certification infrastructure. Target digital batch traceability capabilities as differentiation wedge against incumbent documentation gaps. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical houses holding pharmaceutical-grade certification infrastructure with Swiss and Singaporean CDMO relationships. Long-term viability hinges on natural gas feedstock positioning and carbon capture deployment timing relative to MEE enforcement trajectories. Watch for amine scrubbing retrofit completion rates across Jiangsu province as inflection indicator for Chinese supply rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | MEE permit retention in Jiangsu province requires amine scrubbing installation at coal-based complexes. |
| REACH Dossier Extension | ECHA toxicological compliance protects European registrants from price-driven import competition. |
| Direct CDMO Partnership | Swissmedic-inspected facilities unbundle solvent supply to secure batch traceability documentation. |
| Membrane Recovery Deployment | Nanofiltration units at Turkish and Indonesian spinners compress fresh solvent demand by half. |
| Bio-based Feedstock Pivot | Carbohydrate-derived dimethylamine aligns with EU Green Deal carbon border adjustment mechanisms. |
Study Parameters
Independent corroboration across plant managers at coal-chemical complexes, procurement leads at polyurethane coating OEMs, and distribution channel partners in East Asian chemical corridors underwrites the qualitative findings. Secondary validation draws from MEE emissions filings, REACH registration databases, customs trade data, and SEC disclosures from listed chemical producers. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the analysis window.
Historical reference periods anchored the forecast framework to pre-dual carbon policy baselines and post-MEE enforcement trajectories. Segmentation modeling spans grade tier, end-use industry, and regional production hub dimensions. CAGRs derive from elasticity-adjusted demand projections and capacity expansion schedules. Key inputs include peptide synthesis pipeline announcements from Swiss and Singaporean CDMOs and coal-to-methanol economics sensitivity.
Revisions become necessary when MEE enforcement intensity deviates from announced dual carbon timelines or when N-methyl-2-pyrrolidone substitution accelerates in lithium-ion battery electrode coating. Forecasts reflect assumptions about ECHA dossier renewal rates and membrane recovery adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Pharmaceutical Solvent Market
Solvents
Global Nitrochlorobenzene Market
Solvents
United States Acetonitrile Market
Solvents
Isopropylamine Market
Solvents
N-Hexane Market
Solvents
Solvent Recovery Systems Market
Solvents
Phenylacetonitrile Market
Solvents
Mesitylene Market
Solvents
Methyl Diethanolamine Market
Solvents
Global Acetonitrile Market
Solvents
Methyl Undecylenate Market
Solvents
Diethyl Ether Market
Solvents
Decanol Market
Solvents
1, 1-Difluoroethane Market
Solvents
Benzyl Alcohol Market