
 Fluorinated Solvents Market | 2026-2036
Fluorinated Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorinated Solvents Market Analysis
Aftermarket solvent recovery and reclamation revenue is narrowing as original equipment manufacturers push closed-loop systems. 3M Company leverages its Novec fluid portfolio to anchor positions in precision electronics cleaning. Honeywell International sustains supply relationships with aerospace MRO networks through Solstice-branded fluorinated offerings. Chemours differentiates via vertical integration from fluorochemical feedstocks through formulated solvent blends.
Fluorinated solvents are organofluorine compounds characterized by partial or full substitution of hydrogen with fluorine, typically exhibiting boiling points between 50°C and 128°C and dielectric strengths exceeding 40 kV; they serve primarily as non-flammable, low-toxicity cleaning and carrier media in contamination-sensitive industrial processes. Hydrofluoroether formulations lead product type demand due to their favorable toxicity profiles and compatibility with sensitive substrates, while fluorinated ketones represent the fastest-expanding category driven by their zero ozone depletion potential and reduced global warming potential relative to perfluorocarbon alternatives. Electronics manufacturing dominates application-level consumption, with cleaning and degreasing commanding the largest share of volume as wafer fabrication nodes advance below 7 nanometers.
The EPA Significant New Alternatives Policy program restricts high-GWP fluorinated solvent use in the United States, while the EU F-Gas Regulation mandates phasedown of hydrofluorocarbon content in industrial applications; Japan's METI guidelines further shape product registration requirements for fluorinated chemistries imported for electronics use. REACH compliance in Europe adds substance authorization burdens that favor established suppliers with dedicated regulatory affairs capabilities. Stakeholders must monitor emerging state-level PFAS restrictions in the United States and corresponding European polymer exemption debates that could redefine solvent classification boundaries.
Market Dynamics
Semiconductor fabrication node advancement below 7 nanometers is compressing cleaning chemistry specifications and concentrating purchasing power among East Asian foundry operators. This structural force is reshaping supplier qualification timelines and reformulation priorities across the fluorinated solvent value chain.
Growth Catalysts
- EPA Significant New Alternatives Policy:Restrictions on legacy chlorinated solvents are accelerating fluorinated chemistry adoption in precision electronics cleaning applications across US-based manufacturing facilities.
- Wafer node shrinkage:Sub-7 nanometer fabrication processes in Taiwan and South Korea demand ultra-high-purity carrier media with dielectric strengths exceeding 40 kV.
- Hydrofluoroether toxicity profiles:Favorable occupational exposure characteristics relative to perchloroethylene are driving substitution in contamination-sensitive substrate handling.
Market Restraints
- Fluorochemical feedstock concentration:Captive supply of tetrafluoroethylene and hexafluoropropylene oligomers resides with integrated chemical majors, limiting formulation flexibility for independent blenders.
- EU F-Gas Regulation phasedown:Hydrofluorocarbon content restrictions are forcing reformulation cycles and substance authorization burdens under REACH compliance protocols.
- Aqueous cleaning technology:Closed-loop water-based systems with ionic contamination control below 10 parts per trillion are capturing select degreasing applications in automotive component manufacturing.
Strategic Opportunities
- India semiconductor fabrication:PLI scheme incentives for display and specialty fab construction in Gujarat and Tamil Nadu are creating qualification windows for imported fluorinated chemistries.
- Fluorinated ketone zero-ODP positioning:Reduced global warming potential relative to perfluorocarbon alternatives aligns with Japan METI guidelines for electronics chemistry registration.
- Closed-loop reclamation services:On-site solvent recovery systems at aerospace MRO facilities in Singapore and Dubai are opening recurring revenue streams beyond virgin product sales.
Industry Challenges
- Sub-10 part-per-trillion ionic contamination control:Semiconductor customers demand batch-to-batch consistency that exceeds current analytical detection limits at many independent testing laboratories.
- PFAS substance authorization timelines:European polymer exemption debates and emerging US state-level restrictions are creating classification uncertainty that extends product registration cycles by 18-36 months.
- Specialized fluorine handling infrastructure:New entrant blenders face capital requirements for corrosion-resistant storage and azeotropic distillation equipment that exceed $15 million per facility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorinated Solvents Market |
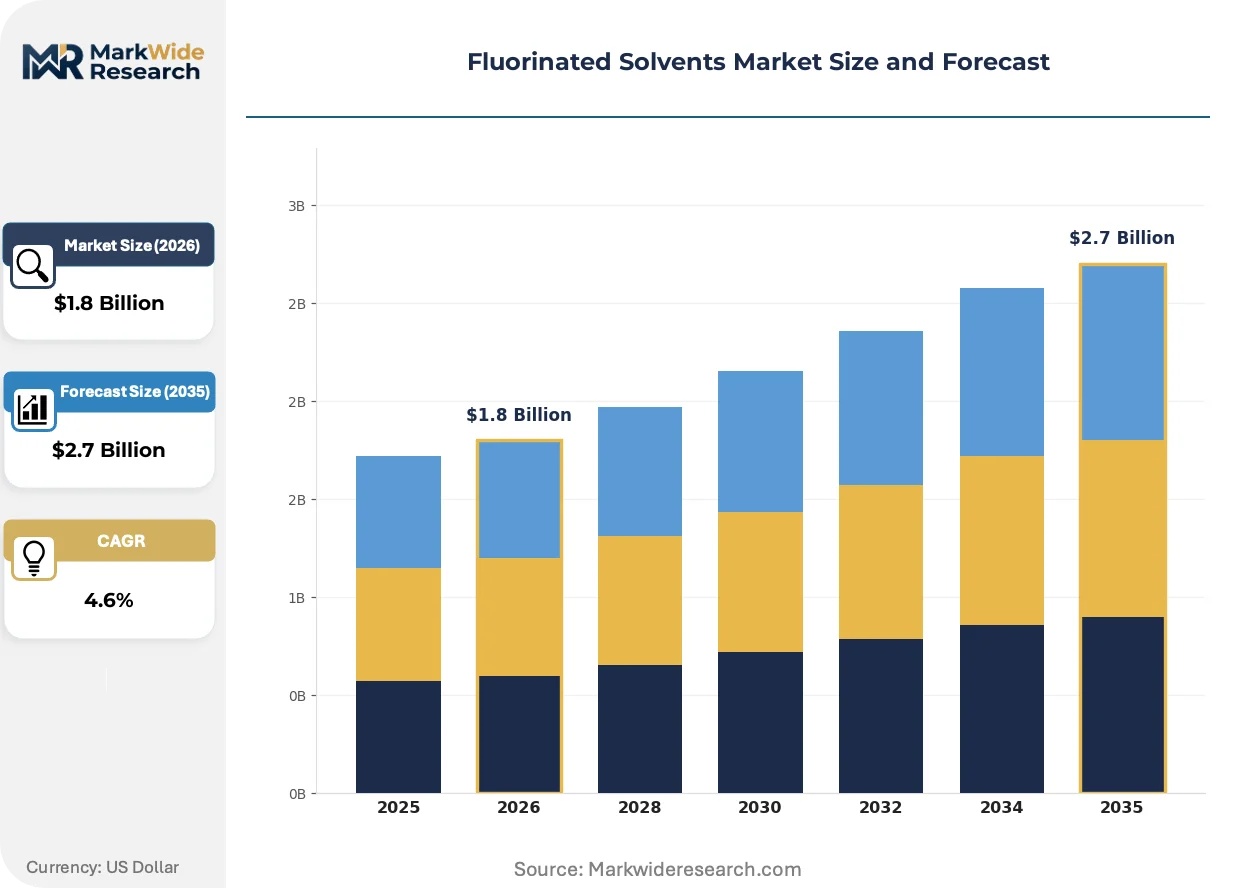
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trichloroethylene, Perfluorocarbon, Hydrofluoroether, Fluorinated Ketones Application: Cleaning, Degreasing, Electronics Manufacturing, Cold Chain End User: Aerospace, Automotive, Electronics, Pharmaceuticals Form: Liquid, Gas, Aerosol, Concentrate |
| Companies Covered | 3M Company, Honeywell International, Chemours, Solvay, Daikin Industries, Arkema, Asahi Glass, Dongyue Group, Navin Fluorine International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorinated Solvents Market Emerging Trajectories
Digital twin simulation of solvent vapor degreasing processes is compressing equipment commissioning timelines and enabling predictive maintenance protocols. This virtualization wave is intersecting with regulatory chemistry restrictions and procurement centralization among multinational electronics assemblers.
Hydrofluoroether azeotropic formulations with controlled vapor pressure curves are virtualizing traditional solvent blends in precision cleaning applications. Advanced packaging facilities in Taiwan are adopting these chemistries for flip-chip underfill residue removal. The technology is virtualizing equipment footprints by enabling single-chamber processing of previously multi-stage cleaning sequences.
EU F-Gas Regulation amendment proposals are tightening hydrofluorocarbon quota allocations for industrial solvent applications. Blend suppliers are accelerating fluorinated ketone and hydrofluoroether-amine co-solvent development to maintain dielectric performance within tightening global warming potential thresholds. German automotive electronics suppliers are front-loading inventory positions ahead of anticipated 2027 quota reductions.
Consolidated procurement through regional chemical management contracts is displacing spot purchasing at multinational semiconductor foundries. Singapore-based logistics providers are capturing solvent inventory ownership and just-in-time delivery obligations previously held by manufacturing site warehouses. This concentration is most visible in Hsinchu Science Park operations where three contract chemical managers now serve eighty percent of fluorinated solvent volume.
Fluorinated Solvents Market Segmentation
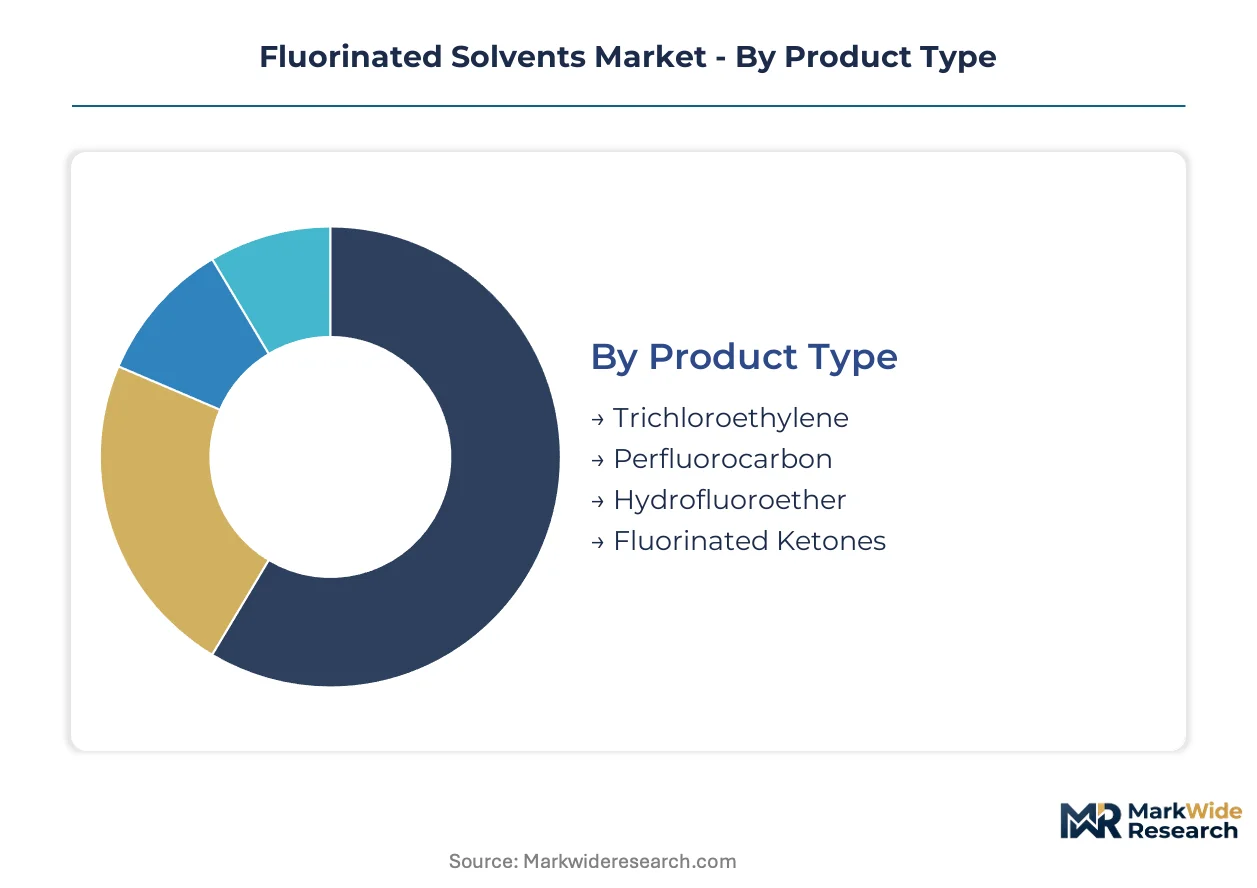
Segmentation in fluorinated solvents reveals how regulatory chemistry restrictions and fabrication node advancement create divergent demand profiles across product types and end-use verticals. Each category maps distinct technical specifications to contamination-sensitive industrial processes.
Product Type:
Cleaning chemistry specifications span precision electronics degreasing to aerospace vapor degreasing, with dielectric strength and toxicity profiles determining substitution patterns.
- Hydrofluoroether:Partial fluorination creates favorable occupational exposure characteristics with boiling points between 50°C and 128°C. Taiwan's Hsinchu Science Park fabs specify HFE formulations for sub-7 nanometer wafer cleaning where ionic contamination must stay below 10 parts per trillion.
- Fluorinated Ketones:Zero ozone depletion potential and reduced global warming potential position these chemistries favorably under Japan METI registration guidelines. Seoul-area advanced packaging facilities are adopting fluorinated ketones for flip-chip underfill residue removal ahead of EU F-Gas Regulation phasedown deadlines.
- Perfluorocarbon:Full fluorination delivers dielectric strengths exceeding 40 kV for legacy semiconductor etching applications.
- Trichloroethylene:Chlorinated chemistry facing accelerated phaseout under EPA Significant New Alternatives Policy restrictions.
The dominant share belongs to Hydrofluoroether, while Fluorinated Ketones is closing the gap fastest.
Application:
Volume concentrates where substrate sensitivity prohibits aqueous or hydrocarbon alternatives.
- Electronics Manufacturing:Wafer fabrication node advancement below 7 nanometers compresses cleaning chemistry specifications. South Korean foundry operators in Seoul and Pyeongtaek consolidate procurement through regional chemical management contracts, displacing spot purchasing.
- Cleaning:Precision substrate handling demands non-flammable carrier media with controlled vapor pressure curves. German automotive electronics suppliers front-load inventory positions ahead of anticipated EU quota reductions.
- Degreasing:Aerospace MRO networks in Singapore and Dubai specify fluorinated solvents for turbine component cleaning where closed-loop reclamation services generate recurring revenue.
- Cold Chain:Specialized heat transfer applications in pharmaceutical logistics leverage fluorinated chemistry thermal stability.
Electronics Manufacturing commands the largest volume position, though Cleaning applications are expanding most quickly into automotive sensor packaging.
End User:
Customer technical requirements range from batch-to-batch analytical consistency to specialized fluorine handling infrastructure compliance.
- Electronics:East Asian foundry operators concentrate purchasing power through consolidated procurement. Taiwan and South Korea facilities specify ultra-high-purity grades with dielectric strengths exceeding 40 kV for contamination-sensitive processes.
- Aerospace:MRO networks sustain supply relationships through Solstice-branded fluorinated offerings, with on-site recovery systems opening service revenue streams beyond virgin product sales.
- Automotive:German suppliers adopt fluorinated ketones for electric powertrain electronics cleaning under tightening EU F-Gas Regulation thresholds.
- Pharmaceuticals:Cold chain logistics applications demand thermal stability specifications distinct from precision cleaning use cases.
Electronics end users generate the dominant revenue share, while Aerospace adoption is climbing the fastest through closed-loop reclamation service attachments.
Form:
Physical state determines equipment compatibility and distribution economics across contamination-sensitive processes.
- Liquid:Bulk delivery to semiconductor fabrication facilities in Taiwan and South Korea dominates volume. Singapore-based logistics providers capture inventory ownership and just-in-time delivery obligations previously held by manufacturing site warehouses.
- Aerosol:Precision application in aerospace component maintenance requires specialized dispensing equipment.
- Gas:Vapor degreasing processes utilize fluorinated solvent vapor for substrate cleaning.
- Concentrate:Dilution-at-use models reduce transportation costs for high-volume industrial degreasing operations.
Liquid form holds the dominant position, while Aerosol formulations are gaining share fastest in maintenance-repair-operations segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian fabrication clusters consume fluorinated solvents primarily for sub-7 nanometer wafer cleaning, while North American and European demand concentrates in aerospace MRO and automotive electronics applications with distinct purity specifications.
United States
Domestic semiconductor fabrication expansion in Arizona and Texas is accelerating hydrofluoroether qualification timelines. The EPA Significant New Alternatives Policy restricts legacy chlorinated solvents in precision electronics cleaning. Phoenix-area fabs specify ultra-high-purity grades with dielectric strengths exceeding 40 kV for advanced node production.
Taiwan
Hsinchu Science Park operators consolidate fluorinated solvent procurement through regional chemical management contracts serving eighty percent of volume. METI-equivalent registration requirements govern imported electronics chemistry specifications. Foundry concentration around Hsinchu and Tainan Science Parks compresses supplier qualification cycles to sub-12 month windows.
South Korea
Seoul and Pyeongtaek fabrication facilities drive demand for fluorinated ketones in flip-chip underfill residue removal. The MFDS maintains substance notification protocols for fluorinated chemistries used in pharmaceutical-adjacent electronics manufacturing. Samsung and SK Hynix operations in Yongin and Icheon anchor regional consumption patterns.
Germany
Automotive electronics suppliers in Bavaria and Baden-Württemberg front-load fluorinated ketone inventory ahead of anticipated EU F-Gas Regulation quota reductions. REACH substance authorization burdens favor established suppliers with dedicated regulatory affairs capabilities. Stuttgart-area powertrain electronics manufacturers specify reduced global warming potential formulations for electric vehicle component cleaning.
Japan
Osaka and Nagoya industrial corridors sustain demand for perfluorocarbon alternatives in legacy semiconductor etching applications. METI guidelines shape product registration requirements for fluorinated chemistries imported for electronics use. Tokyo-based material suppliers coordinate reformulation priorities with Kyushu fabrication facilities advancing packaging node transitions.
Fluorinated Solvents Market Vendor Landscape
Capability concentration sits with integrated fluorochemical producers; scale advantage sits with diversified chemical majors with captive feedstock positions. The supplier base organizes around three strategic archetypes: integrated fluorochemical producers controlling tetrafluoroethylene and hexafluoropropylene oligomer supply, formulated solvent blenders dependent on external feedstock procurement, and regional distributors capturing logistics ownership through just-in-time delivery contracts. Dominant competitive moves include backward integration into fluorochemical feedstocks and strategic partnerships with East Asian foundry operators for qualification co-development.
Among integrated fluorochemical producers, 3M Company, Honeywell International, and Chemours exemplify the capability-concentrated tier. 3M anchors positions through its Novec fluid portfolio in precision electronics cleaning applications. Honeywell sustains supply relationships with aerospace MRO networks through Solstice-branded offerings. Chemours differentiates via upstream control over fluorochemical feedstocks extending through formulated solvent blends.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International |
| Chemours |
| Solvay |
| Daikin Industries |
| Arkema |
| Asahi Glass |
| Dongyue Group |
| Navin Fluorine International |
| Others |
Supply Flow & Price Mechanics
Overcapacity signals in Chinese fluorochemical feedstock production are compressing margins for independent blenders while integrated producers exploit captive tetrafluoroethylene supply to maintain pricing discipline. This utilization asymmetry concentrates bargaining power with East Asian foundry operators and forces reformulation cost absorption onto secondary suppliers.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated fluorochemical producers and East Asian semiconductor foundries, locking in volume commitments that insulate suppliers from spot price volatility. Premium-mid-economy pricing differentiation separates ultra-high-purity grades for sub-7 nanometer wafer cleaning from standard formulations used in legacy packaging. Cost compression in standard grades is intensifying because aqueous cleaning systems are capturing automotive component applications. Tier 2 foundry operators in India exhibit the highest price sensitivity, while Taiwan's Hsinchu Science Park fabs prioritize batch consistency over unit cost.
Supply Chain Analysis
Tetrafluoroethylene and hexafluoropropylene oligomer production concentrates in China, Japan, and the United States, with integrated majors controlling captive supply chains from fluorochemical feedstocks through formulated blends. Fluorinated solvent formulation draws from fluorochemical feedstocks, corrosion-resistant storage infrastructure, and azeotropic distillation equipment. Single-source vulnerability in hexafluoropropylene oligomer supply creates exposure to export licensing disruptions. Distribution runs through Singapore-based logistics providers that have captured inventory ownership and just-in-time delivery obligations previously held by manufacturing site warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorinated solvent demand tracks semiconductor capital expenditure cycles, with foundry buildouts in India and Arizona signaling recovery momentum that will absorb excess formulation capacity.
For Market Incumbents: Insulate qualification relationships with East Asian foundry operators through co-development partnerships for sub-5 nanometer cleaning chemistries. Deepen backward integration into fluorochemical feedstocks to offset margin compression from aqueous cleaning substitution in automotive segments. Prioritize REACH substance authorization investments ahead of EU F-Gas Regulation quota reductions. For New Entrants and Emerging Players: Pursue qualification windows at India's Gujarat and Tamil Nadu display fabs where PLI scheme incentives are accelerating construction timelines. Target aerospace MRO closed-loop reclamation services in Singapore and Dubai, where on-site recovery systems generate recurring revenue beyond virgin product sales. Lead with fluorinated ketone formulations that align with Japan METI registration guidelines for zero-ODP positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fluorinated ketone production lines as EU F-Gas Regulation amendments tighten hydrofluorocarbon quota allocations. Mid-scale blenders with established regulatory affairs capabilities and East Asian foundry qualifications represent the most viable acquisition targets over the 5-10 year horizon. Monitor EU polymer exemption debates as the signal for PFAS substance authorization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorochemical Feedstocks | Captive tetrafluoroethylene supply insulates margins from Chinese overcapacity and secures formulation flexibility. |
| Long-term Supply Agreement with East Asian Foundries | Consolidated procurement through regional chemical management contracts locks in volume commitments at Hsinchu and Seoul. |
| Joint Venture for India Semiconductor Fab Qualification | PLI scheme construction in Gujarat creates first-mover advantage for imported fluorinated chemistry registration. |
| Green Manufacturing Transition to Fluorinated Ketones | Zero-ODP formulations align with Japan METI guidelines and EU F-Gas Regulation phasedown thresholds. |
| Capacity Expansion in Corrosion-Resistant Storage Infrastructure | Azeotropic distillation equipment investments exceed fifteen million dollars per facility, creating barriers for unqualified entrants. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with fluorochemical plant managers, procurement leads at Taiwan and South Korean foundries, distribution channel partners in Singapore, and technical R&D directors at integrated producers; and secondary validation through customs and trade data, SEC 10-K filings, EPA Significant New Alternatives Policy documentation, and EU F-Gas Regulation amendment proposals. Bottom-up and top-down triangulation cross-checked volume estimates against capacity utilization signals and foundry capital expenditure disclosures.
Forecast inputs considered product type segmentation across hydrofluoroether, fluorinated ketone, perfluorocarbon, and legacy chlorinated chemistries; application segmentation spanning electronics manufacturing, precision cleaning, aerospace degreasing, and cold chain logistics; and end-user segmentation across foundry operators, aerospace MRO networks, and automotive electronics suppliers. CAGRs were derived through regression analysis of historical consumption patterns against semiconductor node advancement timelines and regulatory chemistry substitution curves. Fluorochemical feedstock price trajectories and REACH substance authorization pipeline status served as industry-specific forecast modifiers.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, EU F-Gas Regulation quota implementation schedules, or PFAS classification boundaries would shift the trajectory. Forecasts reflect documented assumptions regarding foundry buildout completion rates and regulatory chemistry registration timelines. Quarterly review of EPA SNAP program updates, EU polymer exemption debate outcomes, and India PLI scheme disbursement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Mixed Xylene Market
Solvents
N-Pentyl Chloride Market
Solvents
Global Solvent Evaporation Market
Solvents
Global Glycol Market
Solvents
Global Dipropylene Glycol N-Butyl Ether Market
Solvents
Global Nitrochlorobenzene Market
Solvents
Global Ink Solvents Market
Solvents
Aliphatic Solvents and Thinners Market
Solvents
Electronic Cleaning Solvents Market
Solvents
Fluid Neutralizing Market
Solvents
Ethoxydiglycol Market
Solvents
Mesitylene Market
Solvents
Potassium Formate Market
Solvents
Benzylamine Market
Solvents
Hydrofluoroether Market
Solvents
Green Solvents and Bio-Solvents Market