
 Nitroglycerin Market | 2026-2036
Nitroglycerin Market Size, Share, and Industry Trends Forecast 2026-2036
Nitroglycerin Market Outlook
Market Context
USP-grade nitroglycerin API is rotating toward higher-purity specifications as generic manufacturers face stricter bioequivalence thresholds. Pfizer Inc. anchors the branded cardiovascular segment with established hospital formulary access across North America. Mylan N.V. (Viatris) leverages vertical integration into active pharmaceutical ingredient production to control cost volatility in tablet manufacturing. Sun Pharmaceutical Industries Ltd. dominates the emerging-market supply of sublingual formulations through aggressive tender participation in Asia-Pacific and Latin America.
Technical Definition and Segments
Nitroglycerin is an organic nitrate compound (C₃H₅N₃O₉) synthesized through nitration of glycerol with mixed acid, functioning primarily as a vasodilator that relaxes vascular smooth muscle to relieve acute angina pectoris and manage hypertensive emergencies. The sublingual spray delivery mode captures premium pricing due to rapid onset kinetics and patient preference in acute episodes, while tablet formulations occupy the volume-dominant maintenance therapy position. Injectable nitroglycerin concentrates margin pools in perioperative and intensive care settings where precise titration commands higher unit economics.
Regulatory Frame and Outlook
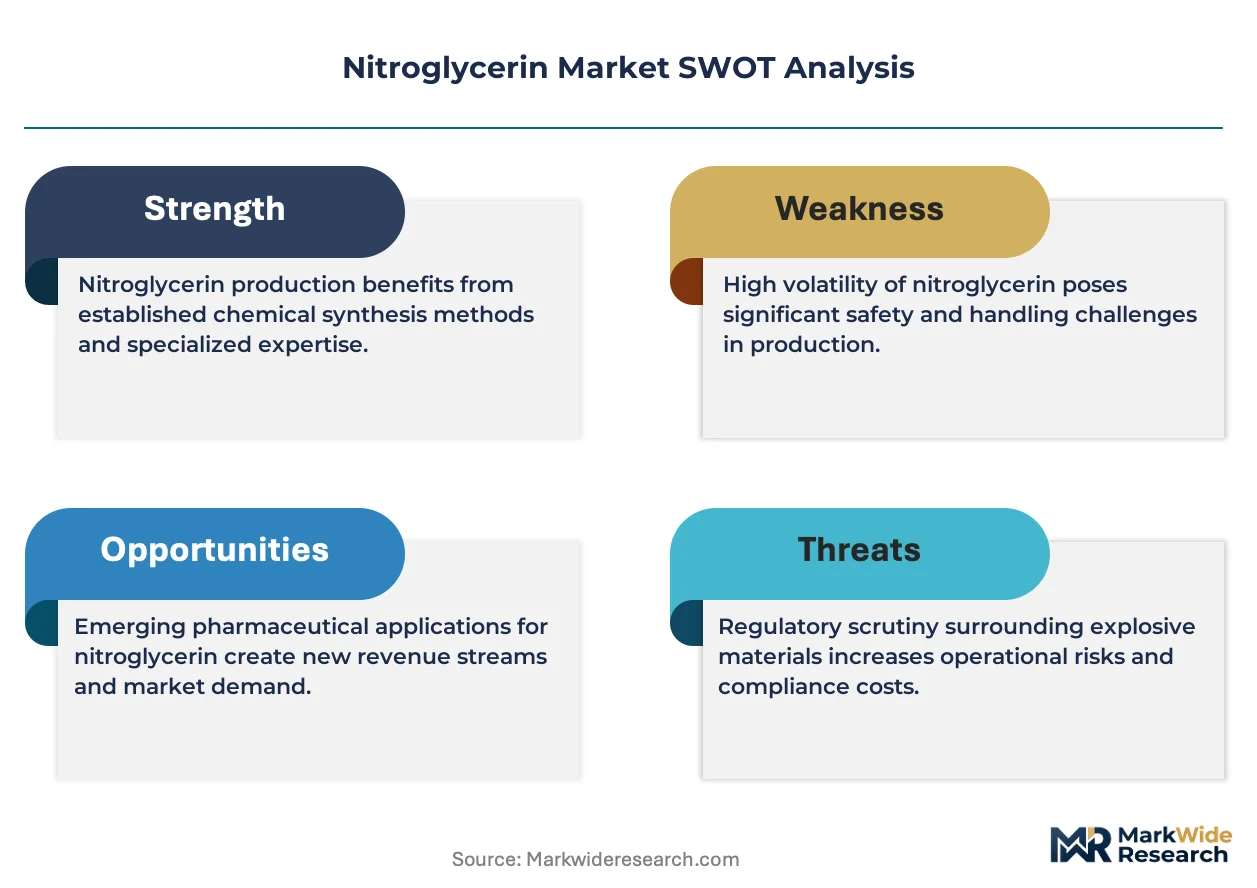
FDA bioequivalence guidance for nitroglycerin sublingual tablets, EMA quality standards under the European Pharmacopoeia, and WHO prequalification requirements collectively elevate manufacturing compliance costs and filter subscale producers from tender eligibility. These frameworks compel manufacturers to invest in process analytical technology and stability testing infrastructure. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional tender consolidation to anticipate where formulation specialization or geographic diversification will yield sustainable returns.
Market Dynamics
FDA bioequivalence guidance revisions for nitroglycerin sublingual tablets are compressing generic manufacturer margins while elevating API purity specifications across the supply base.
Growth Catalysts
- EMA European Pharmacopoeia Chapter 2.9.47:Updated dissolution testing protocols for nitrate vasodilators are accelerating reformulation investments by European generic sponsors seeking pan-EU tender eligibility.
- Emergency department protocol standardization:Hospital systems in the United States are mandating sublingual spray stocking for acute chest pain triage, expanding institutional procurement volumes.
- Glycerol nitration process intensification:Continuous-flow reactor adoption is reducing batch-to-batch API variability and qualifying manufacturers for WHO prequalification tenders in low-income markets.
Market Restraints
- Glycerol feedstock price volatility:Biodiesel co-product supply fluctuations from Southeast Asian palm oil processing are transmitting cost instability to nitroglycerin API production economics.
- Indian API supplier concentration:Over half of USP-grade nitroglycerin active pharmaceutical ingredient originates from facilities in Gujarat and Maharashtra, creating single-source exposure for Western formulation houses.
- Explosives precursor licensing:DEA and ATF controlled-substance tracking requirements for nitrate ester storage are extending warehouse compliance timelines and limiting distributor participation.
Strategic Opportunities
- Perioperative infusion pump integration:ICU automation vendors are developing closed-loop nitroglycerin titration modules, creating device-pharma partnership revenue pools in German and Japanese hospital networks.
- India PLI scheme for critical APIs:Domestic production-linked incentives for nitroglycerin intermediates are attracting greenfield investment in Andhra Pradesh and Telangana manufacturing corridors.
- Telemedicine-triggered emergency prescribing:Cardiology virtual visit platforms in the United States are embedding e-prescription workflows for sublingual spray rescue dosing, bypassing traditional retail pharmacy channels.
Industry Challenges
- Process analytical technology validation:Real-time release testing for nitroglycerin content uniformity requires spectroscopic method qualification timelines that extend regulatory filing schedules by 12-18 months.
- Cold chain integrity for spray formulations:Propellant-based delivery systems demand temperature-controlled distribution infrastructure that remains underdeveloped in Latin American and African tender markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitroglycerin Market |
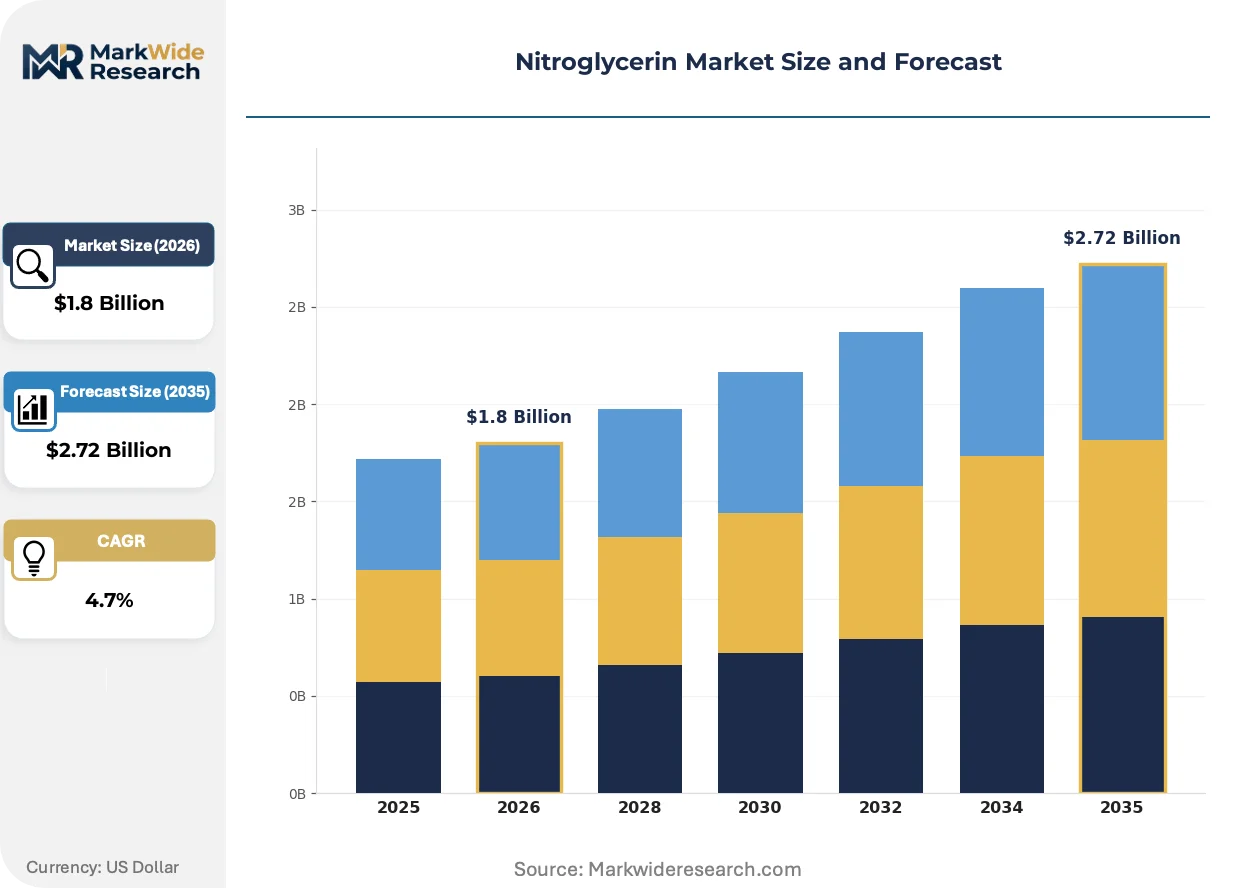
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Ointments, Injectables, Sprays Application: Cardiovascular Disorders, Angina Pectoris, Heart Attack, Hypertension End User: Hospitals, Clinics, Home Care, Pharmacies Delivery Mode: Oral, Sublingual, Topical, Intravenous |
| Companies Covered | Mylan N.V. (Viatris), Sun Pharmaceutical Industries Ltd., Pfizer Inc., Espero BioPharma, Cambrex Corporation, Novartis AG, Glenmark Pharmaceuticals, Zydus Lifesciences, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitroglycerin Market Strategic Shifts
Continuous manufacturing platforms and digital therapeutics integration are reconfiguring how nitroglycerin formulations reach acute care settings and chronic disease management programs.
Hot-melt extrusion for nitroglycerin solid dispersions is fragmenting traditional tablet compression supply chains. Generic manufacturers in Germany and the United States are retrofitting twin-screw extrusion lines to achieve the polymorphic stability required by FDA bioequivalence guidance. This thermal processing route is compressing batch release timelines from weeks to days while disqualifying conventional wet-granulation equipment from new facility designs.
REACH Annex XVII restrictions on volatile organic compound emissions from pharmaceutical manufacturing are compelling solvent recovery system upgrades at nitroglycerin API plants across Belgium and the Netherlands. ECHA enforcement of residual solvent limits in final drug products is redirecting capital toward membrane separation technologies. Sublingual spray manufacturers with aqueous-based propellant alternatives are capturing tender preference in Nordic hospital systems.
Hospital procurement consortia in the United States are consolidating nitroglycerin formulary decisions through group purchasing organization frameworks that displace individual pharmacy committee autonomy. Three-tier pricing stratification across premium, standard, and economy levels now governs contract tier placement, with FDA-approved generic sprays commanding mid-tier positioning against branded legacy tablets. This purchasing concentration is most visible in the Kaiser Permanente and Veterans Health Administration networks, where annual volume commitments determine sole-source awards.
Nitroglycerin Market Segmentation
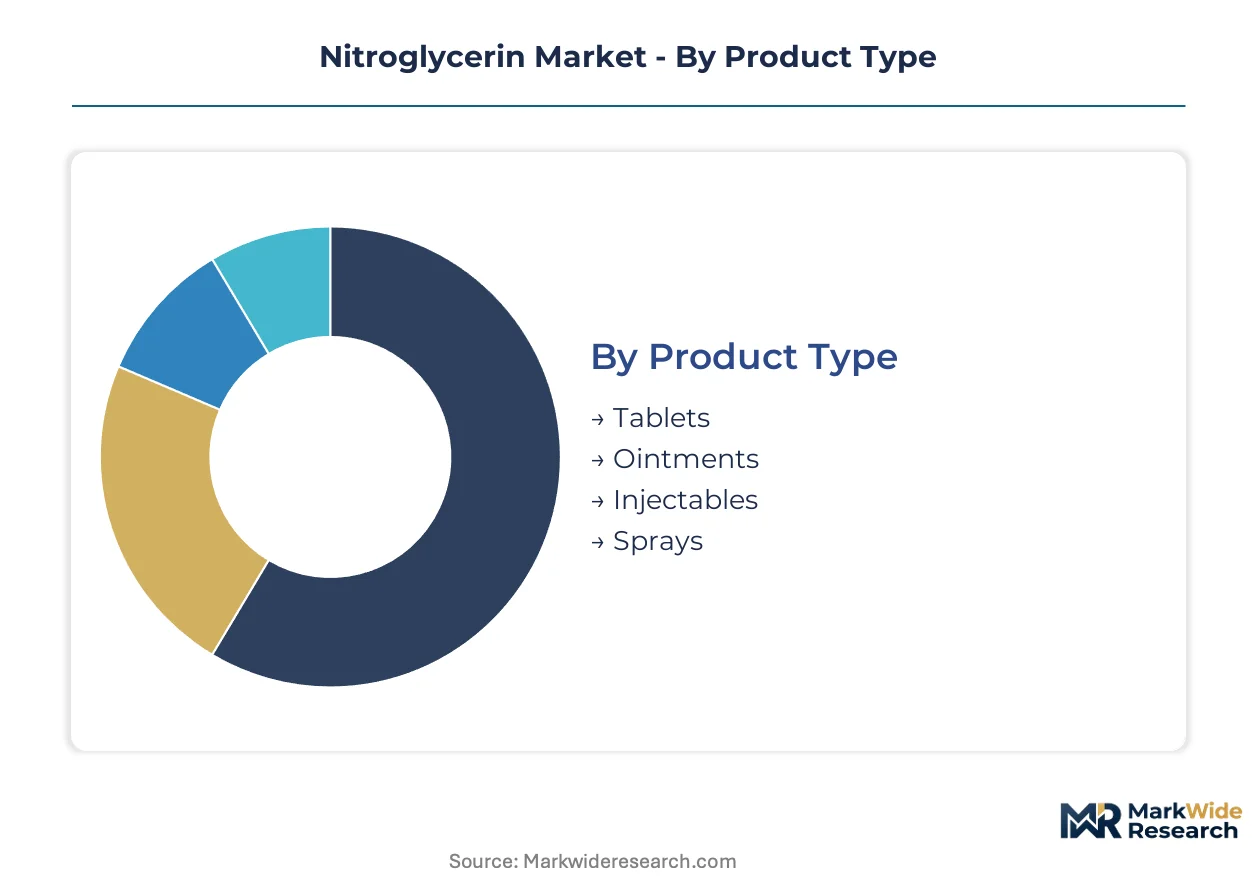
Nitroglycerin formulation diversity creates distinct competitive arenas where delivery kinetics, reimbursement tiers, and regulatory pathways determine margin durability. Manufacturers must align R&D portfolios with segment-specific bioequivalence hurdles and procurement consolidation patterns.
Product Type:
Sublingual sprays face the most acute substitution pressure from rapidly dissolving oral films and buccal tablets, forcing incumbent suppliers to defend hospital formulary slots through device innovation.
- Tablets:Compressed nitroglycerin formulations with standardized USP dissolution profiles dominate maintenance therapy scripts. Demand concentrates in Medicare Part D channels across Florida and Arizona retirement corridors, where monthly refill patterns generate predictable volume.
- Sprays:Metered-dose aerosol systems deliver rapid vasodilation through buccal mucosa absorption. Kaiser Permanente and Veterans Health Administration networks are mandating spray stocking for acute chest pain protocols, displacing legacy tablet rescue dosing in institutional procurement.
- Ointments:Topical nitroglycerin pastes for Raynaud's phenomenon and anal fissures occupy niche dermatology and proctology indications with limited generic competition.
- Injectables:Perioperative infusion concentrates serve ICU titration requirements with exacting stability specifications.
Tablets retain volume leadership; sprays hold the steepest expansion curve.
Application:
Cost tier stratification separates acute rescue indications from chronic maintenance, with reimbursement intensity varying threefold across the spectrum.
- Angina Pectoris:Stable and variant angina episodes drive the majority of sublingual consumption, with prescription frequency correlating to regional cardiac catheterization volumes.
- Cardiovascular Disorders:Broader coronary artery disease management encompasses nitroglycerin as adjunctive therapy alongside beta-blockers and statins.
- Heart Attack:Acute myocardial infarction protocols in German and Japanese emergency departments specify intravenous nitroglycerin for afterload reduction.
- Hypertension:Hypertensive emergency applications command premium pricing in perioperative settings where minute-to-minute control justifies infusion pump integration.
Angina Pectoris captures the deepest prescription volume; Heart Attack applications are climbing fastest on protocol standardization.
End User:
Customer type determines packaging specifications, with institutional buyers demanding unit-dose compliance and retail channels favoring patient-friendly rescue kits.
- Hospitals:Formulary committees in United States health systems are consolidating nitroglycerin sourcing through group purchasing organization frameworks.
- Home Care:Aging-in-place programs in Germany and Japan are expanding reimbursable home infusion services for palliative cardiac care.
- Clinics:Cardiology ambulatory settings generate high-margin spray prescriptions through direct dispensing models.
- Pharmacies:Retail chains face margin compression on generic tablet refills amid DIR fee restructuring.
Hospitals dominate procurement value; Home Care is gaining share fastest on demographic tailwinds.
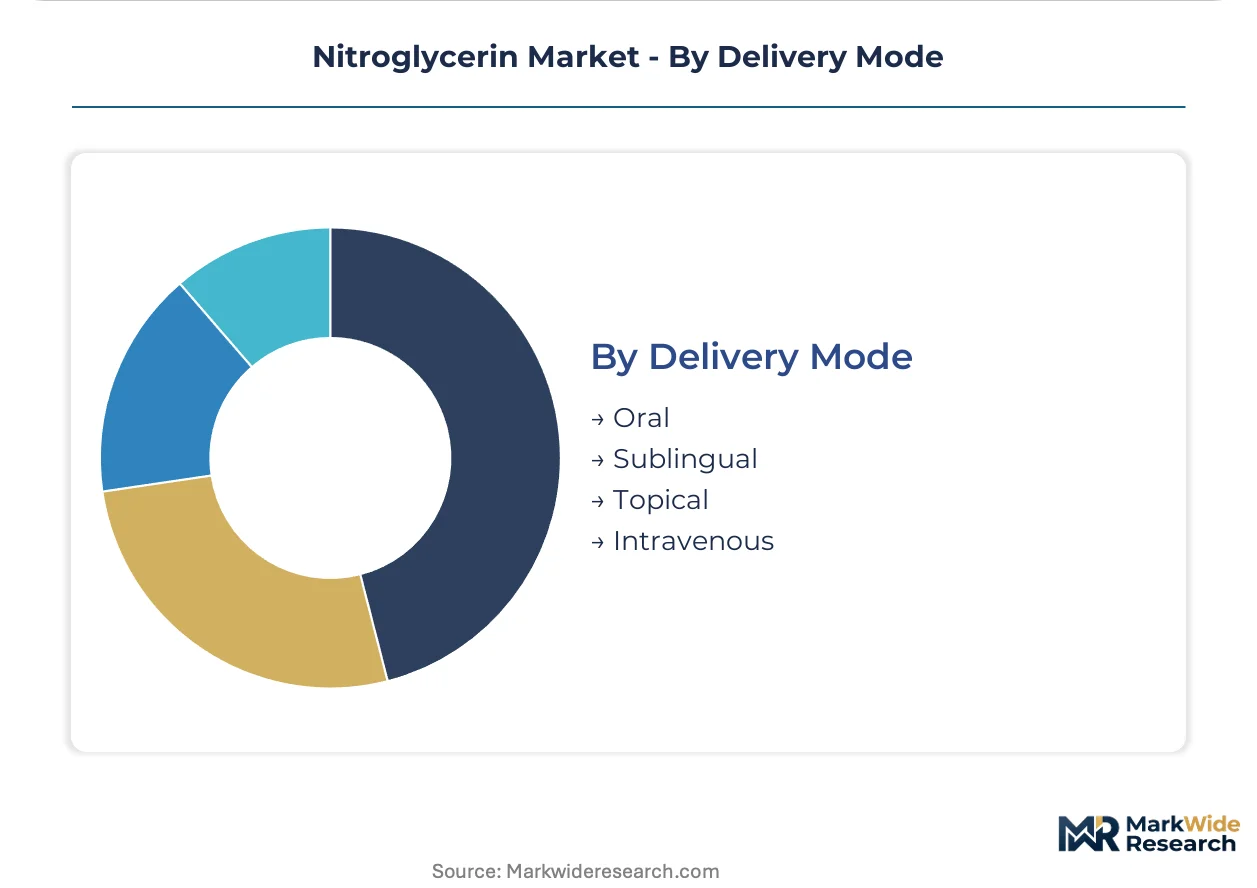
Delivery Mode:
Geography shapes delivery preference, with sublingual absorption dominating Western markets and intravenous routes prevailing in intensive care infrastructure.
- Sublingual:Buccal mucosa absorption bypasses hepatic first-pass metabolism for rapid onset. FDA bioequivalence guidance revisions are disqualifying conventional tablet formulations from abbreviated new drug application pathways.
- Intravenous:Continuous infusion enables precise titration in surgical and critical care environments. Japanese and German ICU automation vendors are developing closed-loop control modules.
- Oral:Swallowed tablets for prophylactic angina prevention suffer from extensive presystemic metabolism and declining clinical preference.
- Topical:Transdermal patches and ointments serve Raynaud's and anal fissure indications with localized vasodilation.
Sublingual administration retains volume leadership; Intravenous delivery holds the steepest expansion trajectory on ICU automation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for nitroglycerin API reveal asymmetric dependencies, with formulation houses in Western markets sourcing bulk active pharmaceutical ingredient from concentrated Asian manufacturing clusters while finished dosage forms flow back through regulated distribution channels.
United States
Medicare Part D reimbursement expansion for acute angina therapies sustains prescription volumes in Florida and Arizona retirement corridors. FDA bioequivalence guidance revisions for sublingual tablets are disqualifying legacy generic sponsors from abbreviated new drug application pathways. New Jersey and North Carolina formulation clusters are retrofitting continuous manufacturing lines to meet tightened dissolution specifications.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia are consolidating nitroglycerin sourcing through group purchasing organization frameworks. EMA European Pharmacopoeia Chapter 2.9.47 dissolution protocols are accelerating reformulation investments by domestic generic sponsors seeking pan-EU tender eligibility. Frankfurt and Munich distribution hubs are upgrading solvent recovery systems to meet REACH Annex XVII volatile organic compound emission limits.
India
Domestic production-linked incentive schemes for critical APIs are attracting greenfield nitroglycerin intermediate investment in Andhra Pradesh and Telangana manufacturing corridors. CDSCO tightened stability testing requirements for sublingual sprays are filtering subscale producers from government tender eligibility. Gujarat and Maharashtra API facilities supply over half of USP-grade nitroglycerin to Western formulation houses, creating concentrated export dependency.
Japan
PMDA accelerated review pathways for emergency cardiovascular therapies are shortening market entry timelines for spray formulation sponsors. METI subsidies for continuous-flow reactor adoption are reducing batch-to-batch API variability at Osaka and Nagoya manufacturing sites. Japanese ICU automation vendors are developing closed-loop nitroglycerin titration modules for perioperative infusion pump integration.
Brazil
ANVISA bioequivalence requirements for imported generic nitroglycerin are extending registration timelines for Asian API-dependent sponsors. São Paulo and Rio de Janeiro hospital networks are standardizing sublingual spray stocking for acute chest pain triage protocols. Cold chain infrastructure gaps for propellant-based delivery systems limit spray formulation penetration in northern and northeastern state tenders.
Nitroglycerin Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and regulatory sophistication, producing a tiered structure where publicly traded pharmaceutical conglomerates anchor hospital formulary access while mid-cap API houses capture tender volume through cost positioning. The competitive arena segments into three archetypes: vertically integrated multinational sponsors with captive active pharmaceutical ingredient supply, regional formulation specialists leveraging geographic tender knowledge, and contract development and manufacturing organizations serving orphan indications. Dominant competitive moves include backward integration into nitroglycerin intermediate production and strategic partnerships with ICU automation vendors for closed-loop infusion system co-development.
Within the multinational integrated tier, Pfizer Inc. and Novartis AG occupy positions defined by established hospital formulary access across North America and European markets. Among emerging-market formulation specialists, Sun Pharmaceutical Industries Ltd. and Zydus Lifesciences exemplify aggressive tender participation strategies in Asia-Pacific and Latin American procurement channels. Mylan N.V. (Viatris) anchors the generic consolidation archetype through upstream control over active pharmaceutical ingredient production.
| Leading Market Players |
|---|
| Mylan N.V. (Viatris) |
| Sun Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Espero BioPharma |
| Cambrex Corporation |
| Novartis AG |
| Glenmark Pharmaceuticals |
| Zydus Lifesciences |
| Teva Pharmaceutical Industries |
| Others |
Value Chain & Pricing Dynamics
FDA bioequivalence guidance revisions for sublingual tablets gate both supply qualification and price differentiation simultaneously, compressing margins for manufacturers lacking process analytical technology infrastructure while rewarding sponsors with validated continuous manufacturing lines.
Pricing Analysis
Hospital procurement managers anchor pricing negotiations through group purchasing organization frameworks that stratify contracts across premium, standard, and economy tiers. Price differentiation hinges on FDA bioequivalence certification tier and volume scale commitments, with spray formulations commanding premiums over tablets. Cost compression in the generic tablet segment intensifies due to DIR fee restructuring in Medicare Part D channels. Retail pharmacy chains exhibit the highest price sensitivity, while ICU automation-integrated infusion systems face minimal bargaining pressure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for Western formulation houses dependent on Indian API shipments. Nitroglycerin active pharmaceutical ingredient production concentrates in India, China, and the United States, drawing from glycerol feedstock, mixed acid reagents, and specialized nitration equipment. Single-source vulnerability pervades the Gujarat-Maharashtra API cluster, where over half of USP-grade supply originates. Distribution runs through hospital procurement consortia and retail pharmacy chains, with cold chain infrastructure gaps limiting spray penetration in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nitroglycerin represents an early-cycle expansion story as telemedicine-triggered emergency prescribing workflows bypass traditional retail channels and expand addressable patient touchpoints.
For Market Incumbents: Shield hospital formulary slots through device innovation partnerships with ICU automation vendors developing closed-loop titration modules. Deepen upstream control over nitroglycerin intermediate production to offset glycerol feedstock volatility. Prioritize certification investment in WHO prequalification to maintain tender eligibility across low-income procurement channels.
For New Entrants and Emerging Players: Differentiate on aqueous-based propellant alternatives that capture tender preference in Nordic hospital systems facing REACH Annex XVII solvent restrictions. Target the perioperative infusion segment in German and Japanese ICU networks where automation integration creates device-pharma partnership revenue pools. Pursue direct dispensing models in cardiology ambulatory settings as the primary go-to-market angle.
For Investors and Strategic Acquirers: CDSCO tightened stability testing requirements for sublingual sprays reshape the acquisition landscape by filtering subscale producers from government tender eligibility. Long-term viability centers on sponsors with validated continuous manufacturing infrastructure and captive API supply. Monitor EMA European Pharmacopoeia Chapter 2.9.47 dissolution protocol adoption as the signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Mylan N.V. (Viatris) controls cost volatility through captive nitroglycerin intermediate supply. |
| Continuous Manufacturing Retrofit | New Jersey and North Carolina formulation clusters upgrade lines to meet FDA dissolution specifications. |
| ICU Automation Partnership | German and Japanese hospital networks develop closed-loop nitroglycerin titration modules with device vendors. |
| Telemedicine E-Prescription Integration | Cardiology virtual visit platforms embed sublingual spray rescue dosing workflows. |
| WHO Prequalification Certification | Continuous-flow reactor adoption qualifies manufacturers for low-income market tenders. |
Study Parameters
A spread of perspectives from regulatory affairs leads, hospital procurement managers, formulary directors, and API plant managers converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up volume modeling and top-down market sizing triangulated across data sources to establish forecast boundaries.
Segmentation dimensions modeled include product type, application, end user, and delivery mode across the projection horizon. Analytical frameworks derived CAGRs through patient population epidemiology, prescription volume trends, and tender participation patterns. Forecast inputs incorporated bioequivalence guidance revision timelines and continuous manufacturing adoption curves specific to nitroglycerin formulation sponsors.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of bioequivalence standards or abrupt glycerol feedstock supply disruptions would require recalibration. Forecasts reflect assumptions about hospital procurement consolidation and telemedicine platform penetration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
2-Butanone Market
Solvents
Vapor Degreasing Solvents Market
Solvents
Aprotic Solvents Market
Solvents
Green Solvents Market
Solvents
3-Butylene Glycol Market
Solvents
Europe Acetonitrile Market
Solvents
Ortho-Xylene Market
Solvents
Hydrogen Cyanamide Market
Solvents
Solvent Cement Market
Solvents
Benzene Market
Solvents
Benzene and Its Derivatives Market
Solvents
Global Droppers Market
Solvents
Global Solvents Market
Solvents
North America Acetonitrile Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
N-Methyl Pyrrolidone Market