
 Ketone-Based Solvents Market | 2026-2036
Ketone-Based Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Ketone-Based Solvents Market Analysis
Specialty chemical producers in the US Gulf Coast is realigning ketone solvent output toward higher-purity grades for pharmaceutical and electronics applications. Eastman Chemical Company leverages its integrated acetyl chain to secure feedstock cost advantages across acetone and MIBK production. BASF SE anchors European supply through Ludwigshafen-based ketone derivative complexes serving coatings and adhesives formulators. Shell plc competes on global acetone merchant volumes tied to phenol co-production economics.
Ketone-based solvents comprise oxygenated organic compounds characterized by a carbonyl group bonded to two carbon atoms, typically exhibiting evaporation rates between 1.0 and 3.5 relative to n-butyl acetate and solubility parameters in the 9.0-10.0 cal/cm³ range, making them essential for dissolving resins in high-performance coatings and precision cleaning operations. Acetone dominates volume flows as the lowest-cost ketone feedstock, while MIBK commands premium positioning in automotive clearcoats where controlled evaporation prevents surface defects. Paints and coatings applications sustain the largest value pool, though electronics cleaning represents the fastest-expanding demand segment driven by semiconductor fabrication standards.
EPA National Emission Standards for Hazardous Air Pollutants restrict MEK emissions in coating operations, while REACH registration requirements govern ketone solvent placement in EU formulations, and China's MEE enforces volatile organic compound limits that favor lower-emission ketone blends in industrial coatings. Stakeholders must monitor regulatory divergence between jurisdictions where emission thresholds tighten and those where industrial growth sustains conventional solvent demand.
Market Dynamics
Waterborne coating formulations are displacing solvent-based systems across automotive and industrial applications, forcing ketone suppliers to engineer lower-VOC blends that maintain solvency performance while complying with tightening emission limits in China, the EU, and the US.
Growth Catalysts
- MEE Emission Standards:China's Ministry of Ecology and Environment mandates VOC reductions in industrial coatings, accelerating procurement of acetone-MEK blends that evaporate faster and emit less during application.
- Semiconductor Fabrication:Electronics cleaning protocols for advanced node chips require ultra-high-purity ketones with sub-ppb metal contamination levels, expanding specification-driven demand from foundries in Taiwan and South Korea.
- Automotive Refinishing:Collision repair shops in India and Southeast Asia are upgrading to two-component polyurethane clearcoats that rely on MIBK's controlled evaporation profile to prevent orange peel defects.
Market Restraints
- Propylene Feedstock Volatility:Acetone derives from cumene oxidation tied to phenol co-production economics; propylene price swings in the US Gulf Coast directly compress ketone solvent margins.
- REACH Registration Burden:ECHA's substance evaluation dossier requirements impose compliance costs that disadvantage smaller European formulators seeking to maintain ketone-based product lines.
- Waterborne Substitution:Latex and acrylic emulsion technologies are capturing share in architectural coatings, particularly in Western Europe where decorative paint VOC limits are most stringent.
Strategic Opportunities
- Pharmaceutical-Grade Purification:cGMP-compliant ketone solvents for active pharmaceutical ingredient crystallization command 40-60% price premiums over technical grades, with demand concentrated in India and Ireland contract manufacturing.
- Bio-Based Acetone Pathways:Fermentation-derived acetone from lignocellulosic feedstocks qualifies for EU Green Deal sustainable chemistry procurement preferences in cosmetics and personal care formulations.
- Direct-to-Formulator E-Commerce:Specialty chemical distributors are launching digital platforms that bypass traditional regional stocking points, reducing lead times for mid-size coatings producers in Brazil and Mexico.
Industry Challenges
- High-Purity Distillation Expertise:Electronics-grade ketone production requires molecular sieve and extractive distillation capabilities that few contract manufacturers outside Japan and Germany have mastered.
- Cross-Border Harmonization Delays:Divergent VOC test methods between EPA Method 24 and ISO 11890 create formulation requalification costs for multinational coatings suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ketone-Based Solvents Market |
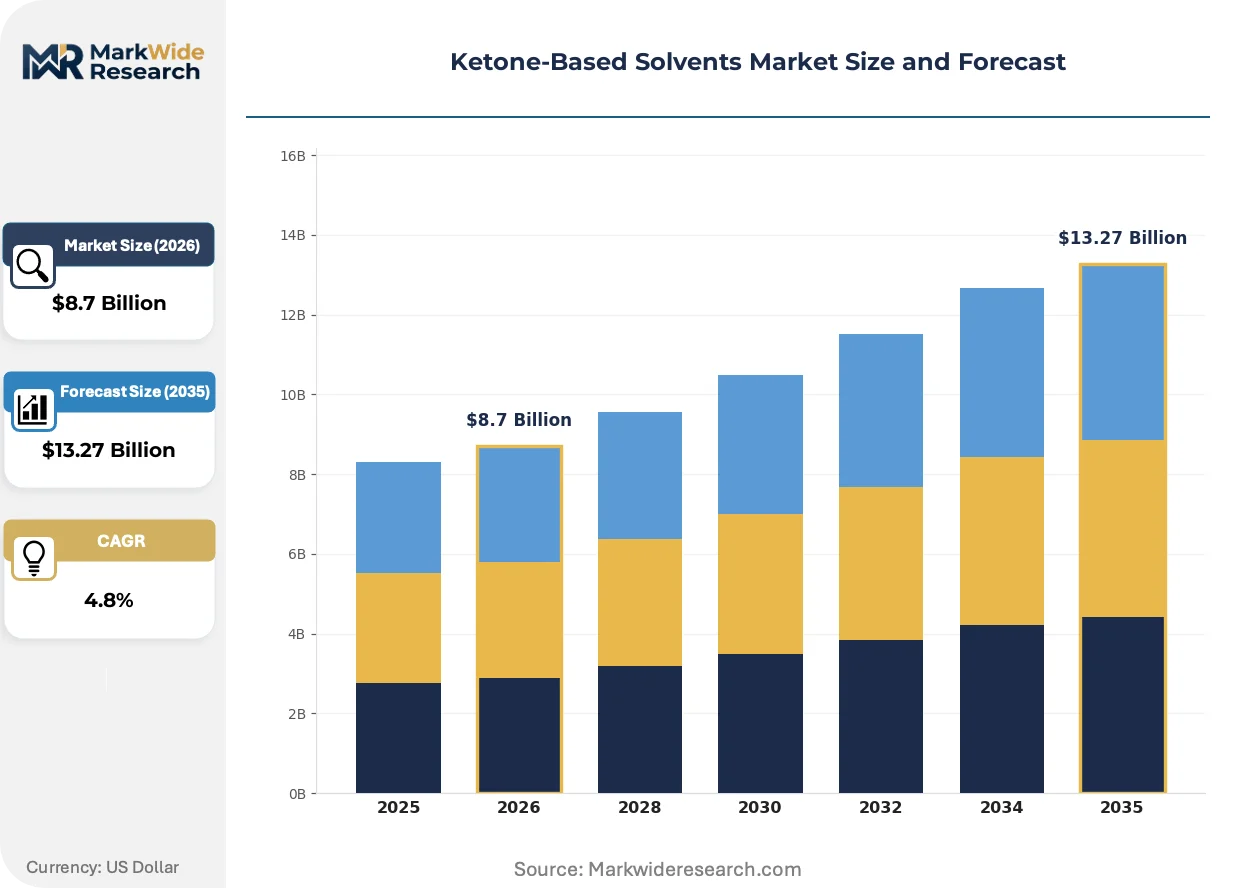
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetone, MEK, MIBK, DIK Application: Paints, Coatings, Adhesives, Cleaning Agents End User: Automotive, Electronics, Pharmaceuticals, Construction Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | Eastman Chemical Company, Shell plc, ExxonMobil Corporation, BASF SE, Dow Chemical Company, Celanese Corporation, Arkema, Sasol, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ketone-Based Solvents Market Emerging Trajectories
Reactive diluent technologies and closed-loop solvent recovery systems are compressing virgin ketone consumption intensity per unit of coating output, while digital formulation tools accelerate product development cycles.
Membrane separation technology is integrating into ketone purification trains, enabling single-stage concentration of spent solvents from electronics cleaning operations to 99.5% purity without thermal degradation. Semiconductor fabs in Hsinchu and Pyeongtaek are piloting these units to reduce hazardous waste disposal volumes. The technology is compressing operating costs for solvent recovery service providers while tightening virgin ketone demand growth.
REACH's restriction proposal for N-methyl-2-pyrrolidone is redirecting formulators toward NEP and DMSO alternatives, though ketone blends retain advantage in epoxy curing applications where polarity matching is critical. German automotive OEMs are accelerating qualification of MIBK-free refinish systems ahead of anticipated SVHC listing. The shift is forcing coatings suppliers to maintain dual formulation portfolios across EU and non-EU production.
Specification-driven procurement now dominates electronics and pharmaceutical segments, with buyers demanding lot-specific certificates of analysis and chain-of-custody documentation. Large coatings producers are consolidating supplier bases to three approved ketone sources per region, replacing the previous six-to-eight vendor model. This concentration is most visible in North America, where Sherwin-Williams and PPG have implemented unified global sourcing standards.
Ketone-Based Solvents Market Segmentation
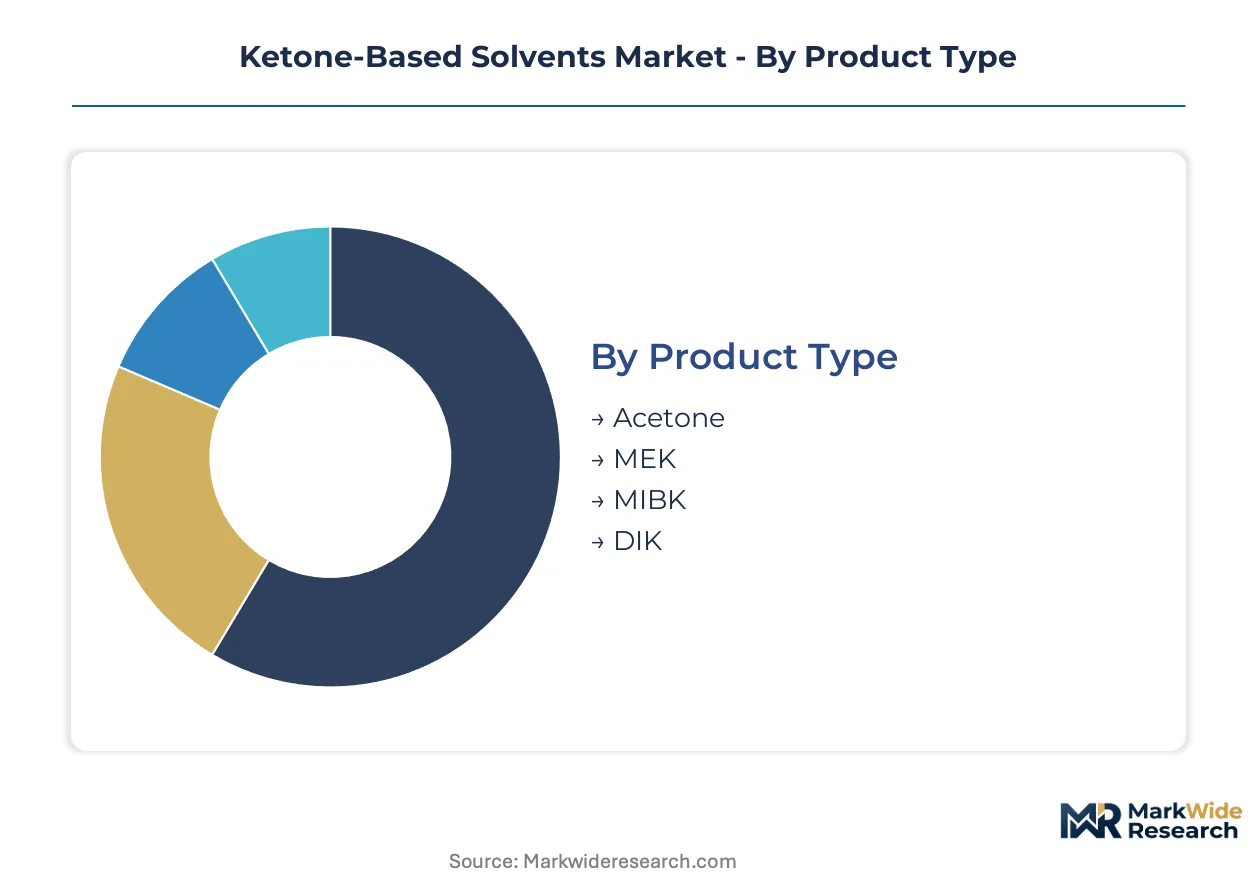
Ketone solvent procurement patterns diverge sharply across specification grades, end-use purity requirements, and channel economics. Understanding these fracture lines exposes where margin pools concentrate and which customer relationships command strategic investment.
Product Type:
Specification purity and evaporation control define competitive positioning across the ketone product spectrum.
- Acetone:The lowest-cost ketone feedstock with evaporation rates near 5.6 relative to n-butyl acetate. Coatings formulators in China leverage acetone-MEK blends to meet MEE VOC compliance thresholds while maintaining film formation speed.
- MEK:Methyl ethyl ketone delivers intermediate evaporation control at 2.7 relative to n-butyl acetate with superior solvency for vinyl and nitrocellulose resins. EPA National Emission Standards for Hazardous Air Pollutants restrict MEK emissions in US coating operations, forcing suppliers toward closed-loop recovery systems.
- MIBK:Methyl isobutyl ketone commands premium positioning in automotive clearcoats where controlled evaporation prevents surface defects.
- DIK:Diisobutyl ketone serves niche applications requiring very slow evaporation rates for high-build coatings.
Acetone leads on scale; MIBK leads on momentum.
Application:
End-use performance requirements segment the market into distinct formulation ecosystems with incompatible purity standards.
- Paints:Architectural and decorative formulations consume acetone and MEK for alkyd and acrylic resin dissolution. Waterborne substitution pressures in Western Europe compress solvent-based paint demand.
- Coatings:Industrial protective and automotive refinish coatings rely on MIBK's controlled evaporation profile for defect-free film formation. Collision repair shops in India upgrade to two-component polyurethane clearcoats specifying MIBK grades.
- Adhesives:Solvent-borne adhesives for flexible packaging and footwear assembly utilize MEK for polyurethane and synthetic rubber dissolution.
- Cleaning Agents:Electronics cleaning for semiconductor fabrication demands ultra-high-purity ketones with sub-ppb metal contamination levels. Foundries in Taiwan and South Korea drive specification-driven procurement.
Coatings dominate volume contribution; cleaning agents expand most quickly.
End User:
Customer technical capabilities and regulatory exposure create tiered service requirements.
- Automotive:OEM and refinish operations specify MIBK for premium clearcoat performance. German automotive manufacturers accelerate qualification of MIBK-free systems ahead of anticipated SVHC listings.
- Electronics:Semiconductor fabs require electronics-grade ketones with molecular sieve purification and extractive distillation capabilities. Hsinchu and Pyeongtaek facilities pilot membrane separation for spent solvent recovery.
- Pharmaceuticals:Active pharmaceutical ingredient crystallization demands cGMP-compliant ketone solvents with lot-specific certificates of analysis. Contract manufacturers in India and Ireland command 40-60% price premiums over technical grades.
- Construction:Architectural coatings and adhesives for building materials utilize technical-grade acetone and MEK with less stringent purity requirements.
Automotive anchors current value; electronics claims the steepest expansion trajectory.
Distribution Channel:
Customer scale and geographic concentration determine channel economics and service intensity.
- Direct Sales:Large coatings producers consolidate supplier bases to three approved ketone sources per region. Sherwin-Williams and PPG implement unified global sourcing standards with lot-specific chain-of-custody documentation.
- Distributors:Regional stocking points serve mid-size formulators with technical support and blended formulations. Traditional distributors face compression from digital platforms.
- E-commerce:Specialty chemical distributors launch direct-to-formulator platforms reducing lead times for coatings producers in Brazil and Mexico. Digital procurement gains traction for standardized technical grades.
- Retail:Small-volume sales to collision repair shops and maintenance operations through hardware and automotive aftermarket channels.
Direct sales capture premium relationships; e-commerce gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE enforcement accelerates ketone solvent procurement faster than India's automotive refinishing expansion, yet both markets diverge sharply from Europe's REACH-driven substitution pressures.
China
Waterborne paint formulations gain regulatory traction under MEE emission standards, forcing coatings manufacturers to expand acetone-MEK blend procurement. The Ministry of Ecology and Environment mandates VOC reductions that favor faster-evaporating ketone systems. Industrial clusters in Shanghai and Jiangsu province host expanding automotive refinishing operations specifying controlled-evaporation solvents.
United States
Specialty chemical producers in the Gulf Coast realign output toward pharmaceutical-grade and electronics-grade ketone purification. EPA National Emission Standards for Hazardous Air Pollutants restrict MEK emissions in coating operations, pushing suppliers toward closed-loop recovery infrastructure. Houston-area petrochemical complexes leverage integrated acetyl chains for feedstock cost positioning.
Germany
Automotive OEMs accelerate qualification of MIBK-free refinish systems ahead of anticipated SVHC listings under REACH. ECHA substance evaluation dossier requirements impose compliance costs that disadvantage smaller formulators. The Ludwigshafen chemical complex anchors European ketone derivative supply serving coatings and adhesives producers.
South Korea
Semiconductor fabrication protocols drive specification-driven demand for ultra-high-purity ketones with sub-ppb metal contamination levels. Foundries in Pyeongtaek pilot membrane separation technology for spent solvent recovery, compressing virgin ketone consumption growth. National industrial policy supports electronics materials self-sufficiency.
India
Collision repair shops upgrade to two-component polyurethane clearcoats requiring controlled evaporation profiles. Central pollution control board directives gradually tighten VOC limits in industrial coatings. Maharashtra and Gujarat host expanding automotive refinishing clusters importing technical-grade ketone blends.
Ketone-Based Solvents Market Vendor Landscape
US Gulf Coast producers anchor the integrated petrochemical tier; European and Asian specialists hold differentiated positions in high-purity grades. Market structure concentrates around three strategic archetypes: integrated petrochemical majors with captive feedstock, regional pure-play ketone refiners, and contract purification specialists serving electronics and pharmaceutical specifications. Capacity expansion and backward integration into propylene feedstock represent the dominant competitive moves.
Within the integrated major tier, Eastman Chemical Company and Shell plc exemplify divergent strategic positions. Eastman leverages its acetyl chain integration across acetone and MIBK production. Shell competes on global acetone merchant volumes tied to phenol co-production economics. BASF SE occupies a position anchoring European supply through Ludwigshafen-based derivative complexes.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Shell plc |
| ExxonMobil Corporation |
| BASF SE |
| Dow Chemical Company |
| Celanese Corporation |
| Arkema |
| Sasol |
| Solvay |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between electronics-grade and technical-grade ketones manifests in pricing spreads exceeding 40-60% and supply chain configurations that segregate molecular-sieve purification capacity in Japan and Germany from commodity acetone flows in the US Gulf Coast and China. Buyers in Taiwan and South Korea absorb premium logistics costs for sub-ppb metal contamination guarantees, while Indian automotive refinishers source technical-grade MIBK through regional distributors without chain-of-custody documentation.
Pricing Analysis
Distributor margins compress the spread between ex-works Gulf Coast acetone and delivered prices to Brazilian coatings producers, while direct-to-OEM contracts for semiconductor fabs eliminate intermediary markups entirely. Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and technical-grade levels anchors on purity certification and extractive distillation capability. Cost compression in technical-grade acetone is intensifying because propylene feedstock volatility in the US Gulf Coast squeezes merchant producer margins. Small-scale Indian collision repair shops exhibit highest price sensitivity, while Taiwan foundries prioritize specification compliance over unit cost.
Supply Chain Analysis
China's MEE enforcement and India's phased manufacturing program reshape sourcing toward domestic ketone derivative capacity in Shanghai and Jiangsu provinces. Feedstock supply concentrates in the United States, China, and South Korea, where cumene oxidation units tie acetone output to phenol co-production economics. Raw material flows draw from propylene, benzene, and hydrogen feedstocks. Single-source vulnerability concentrates in electronics-grade purification, where molecular sieve expertise clusters outside the consuming regions. Distribution runs through direct sales for large coatings producers and regional stocking points for mid-size Latin American formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ketone solvent procurement operates as a geographic-arbitrage play: REACH registration burdens in Europe inflate compliance costs that Asian producers avoid, while MEE standards in China accelerate demand for faster-evaporating blends that European suppliers struggle to qualify.
For Market Incumbents: Extend backward integration into propylene feedstock to defend margin compression from Gulf Coast price volatility. Lock in long-term offtake agreements with Taiwan foundries before membrane separation technology matures and compresses virgin ketone demand. Reinforce certification investment in cGMP-compliant purification to offset waterborne substitution threats in Western European architectural coatings. For New Entrants and Emerging Players: MEE emission standards in China open a window for acetone-MEK blend specialists with faster-evaporating formulations that state-owned incumbents lack agility to commercialize. Target India's automotive refinishing expansion in Maharashtra and Gujarat, where collision repair shop density outpaces qualified solvent distributors. Pursue direct-to-formulator e-commerce platforms in Brazil and Mexico, bypassing traditional regional stocking points that add 15-20 days to lead times. For Investors and Strategic Acquirers: Consolidation pressure builds where electronics-grade purification capability clusters in Japan and Germany while demand concentrates in Taiwan and South Korea. Contract manufacturers with molecular sieve and extractive distillation expertise represent acquisition targets with defensive moats against commodity acetone cycles. Watch membrane separation pilot results in Hsinchu and Pyeongtaek as inflection indicators for virgin ketone demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | Captive supply of cumene oxidation feedstock insulates acetone margins from Gulf Coast price volatility. |
| Pharmaceutical-Grade Purification Investment | cGMP-compliant ketone production commands 40-60% price premiums from Indian and Irish contract manufacturers. |
| Membrane Separation Technology Deployment | Single-stage concentration to 99.5% purity reduces hazardous waste disposal for Pyeongtaek semiconductor fabs. |
| Direct-to-Formulator E-Commerce Launch | Digital platforms compress lead times for mid-size coatings producers in São Paulo and Mexico City. |
| Long-Term Supply Agreement with Taiwan Foundries | Lot-specific certificates of analysis lock in specification-driven procurement from Hsinchu semiconductor clusters. |
Methodological Framework
Direct dialogue with plant managers at Gulf Coast petrochemical complexes, procurement leads at automotive OEMs and semiconductor foundries, distribution channel partners in Latin America, and technical R&D directors at coatings formulators grounded qualitative insights. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, EPA and ECHA regulatory filings, and SEC 10-K disclosures from listed chemical producers. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Segmentation outputs across product type, application, end-use industry, and regional production hub fed into analytical framework spanning the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating propylene feedstock pricing, regulatory enforcement timelines, and substitution technology penetration rates. Electronics cleaning intensity per semiconductor wafer start and pharmaceutical batch size assumptions informed sector-specific growth trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH restriction expansion or breakthrough membrane separation adoption in East Asian foundries. Forecasts reflect documented assumptions around MEE enforcement consistency, phenol co-production economics, and waterborne coating substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Mesitylene Market
Solvents
Methyl Formate Market
Solvents
Dibutyl Ether Market
Solvents
Mineral Turpentine Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
Triacetin Market
Solvents
Xylene Market
Solvents
Butyl Acetate (BAC) Market
Solvents
Nitrobenzene Market
Solvents
1,2-Ethanedithiol Market
Solvents
Hexylene Glycol Market
Solvents
Global Ethyl Lactate Market
Solvents
Global Nitrochlorobenzene Market
Solvents
Ethyl Pyruvate Market
Solvents
Ionic Liquids Market
Solvents
Hydrophobic Solvents Market