
 High-Purity Boehmite Market | 2026-2036
High-Purity Boehmite Market Size, Share, and Industry Trends Forecast 2026-2036
High-Purity Boehmite Market Outlook
Battery separator coating revenue is rewriting margin distribution across the value chain. Sasol leverages its integrated alumina feedstock position to control purity consistency from mine to final calcination. Nabaltec AG anchors European supply through its flame-hydrolysis expertise, while TAIMEI CHEMICALS Co. Ltd dominates Asia-Pacific pharmaceutical-grade segments with sub-50 ppm trace-metal specifications.
High-purity boehmite is an aluminum oxyhydroxide (AlOOH) crystallized in alpha, gamma, or beta polymorphs with sodium content typically below 100 ppm and controlled particle morphology for thin-film deposition. It functions primarily as a ceramic precursor, adsorbent substrate, and thermal barrier in applications requiring chemical inertness above 1,200°C. Alpha Boehmite leads volume due to its thermodynamic stability in battery separator coatings, while the Electronics end user segment records the fastest expansion as solid-state electrolyte research intensifies. Adsorption applications retain mature margin pools in petrochemical refining, though Catalysis is displacing share in hydrogen production catalyst supports.
REACH in Europe and China's GB/T standards for battery materials are mandating stricter heavy-metal thresholds, forcing producers to retool purification circuits or exit supply chains. Japan's METI has classified high-purity alumina derivatives as critical battery supply-chain inputs, triggering domestic stockpiling incentives. Stakeholders must monitor polymorph-specific qualification timelines at cell manufacturers, as alpha-phase certification cycles now determine market access speed more than raw capacity.
Market Dynamics
Battery separator qualification timelines have compressed from 18 months to 8 months, forcing feedstock suppliers to synchronize polymorph purity with cell manufacturer release cycles rather than legacy refractory specifications.
Growth Catalysts
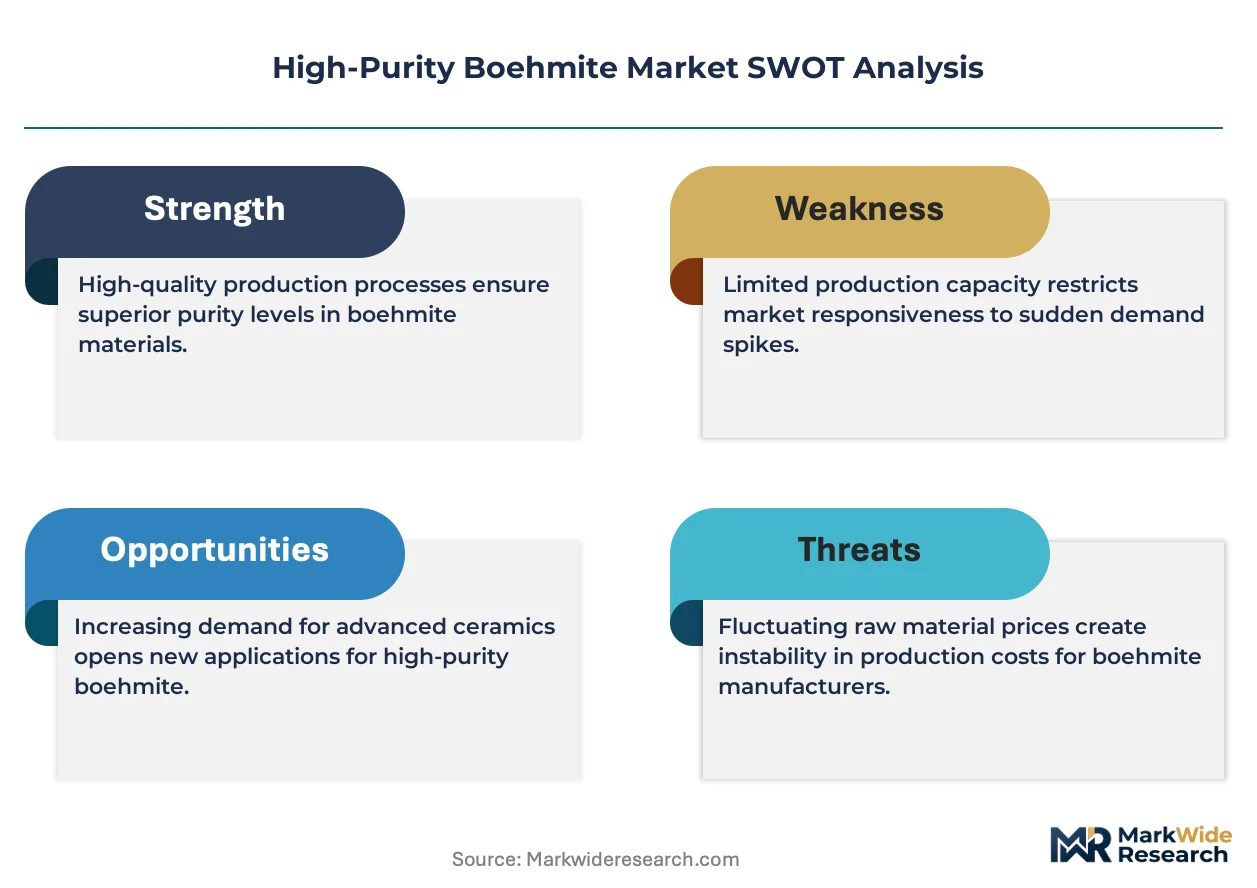
- EU REACH heavy-metal thresholds:Sub-50 ppm sodium mandates for battery-grade boehmite are filtering out legacy producers and consolidating qualified supply among integrated alumina refiners.
- Solid-state electrolyte prototyping:Alpha-phase boehmite serves as the preferred ceramic precursor for sulfide and oxide solid-state cell architectures under development in Japan and South Korea.
- Germany's domestic cell manufacturing:Northvolt and CATL European operations are localizing separator coating supply chains, pulling high-purity alumina derivatives away from Asian import dependence.
Market Restraints
- Feedstock concentration:Metallurgical-grade alumina supply from Guinea and Australia constrains high-purity derivative output when bauxite quality fluctuates.
- Flame-hydrolysis capex barriers:Sub-micron particle production requires reactor investments exceeding $40 million per line, freezing out mid-scale entrants.
- Gamma-phase substitution:Lower-cost gamma boehmite from Chinese producers competes for adsorption applications where thermal stability requirements are less stringent.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic boehmite purification capacity remains undeveloped, creating first-mover advantage for technology licensors.
- Hydrogen catalyst support convergence:Boehmite-alumina composites are hybridizing with perovskite structures for proton-exchange membrane electrolyzer electrodes.
- Direct-to-cell-manufacturer contracting:Separator coaters are bypassing traditional distributor networks to lock in polymorph-specific supply agreements.
Industry Challenges
- Polymorph certification timelines:Alpha-phase qualification at Korean cell manufacturers requires 12-18 months of lot-by-lot validation, freezing inventory capital.
- Trace-metal analytical capability gaps:ICP-MS expertise for sub-10 ppm detection resides at fewer than 20 certified laboratories worldwide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Purity Boehmite Market |
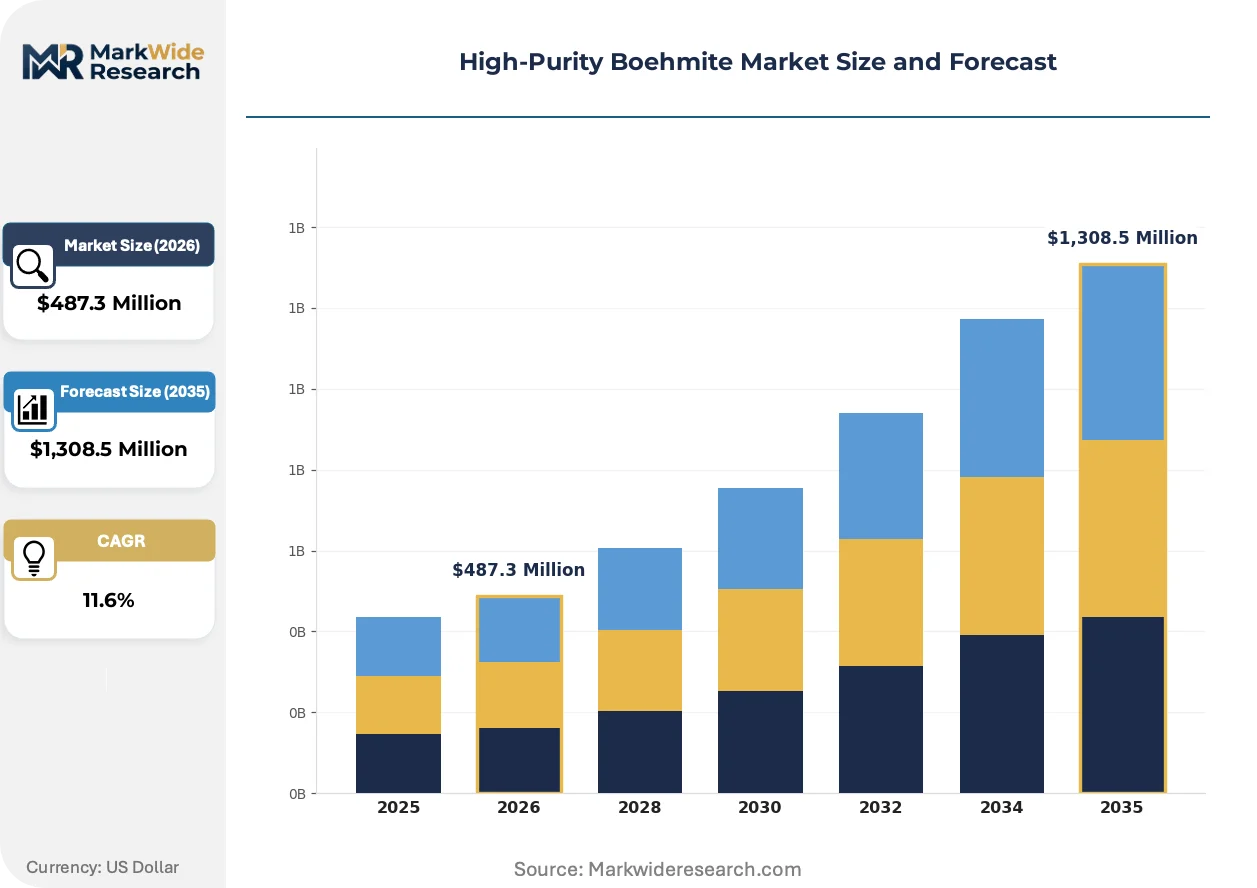
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha Boehmite, Gamma Boehmite, Beta Boehmite, Other Types End User: Ceramics, Coatings, Pharmaceuticals, Electronics Application: Adsorption, Catalysis, Electrical Insulation, Reinforcement Grade: Analytical Grade, Industrial Grade, Technical Grade, Others |
| Companies Covered | Sasol, Nabaltec AG, Osang Group, TOR Minerals, Silkem, TAIMEI CHEMICALS Co. Ltd, Zibo Honghe Chemical, AnHui Estone Materials Technology, CHALCO Shandong Advanced Material Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Purity Boehmite Market Strategic Shifts
Process intensification and regulatory precision are converging to redefine purity benchmarking. Manufacturers now optimize for battery-specific ionic conductivity rather than generic ceramic performance metrics.
Sol-gel synthesis routes are hybridizing with continuous hydrothermal methods to achieve sub-100 nanometer platelet morphology without batch-to-batch variation. Solid-state battery developers in Japan and South Korea have adopted these materials for pilot-line separator coatings. The structural consequence is a compression of acceptable particle-size distribution bands from ±15% to ±5%, disqualifying legacy precipitation-based producers.
China's GB/T standards for lithium-ion battery materials now mandate disclosure of 18 trace elements down to 1 ppm, exceeding REACH disclosure requirements. Domestic producers must retrofit purification circuits or surrender battery-grade certification. European importers face parallel compliance costs as ECHA aligns its battery passport requirements with these thresholds.
Cell manufacturers now specify polymorph phase purity in procurement contracts rather than accepting supplier certificates. Korean and German buyers conduct in-house XRD verification, shifting quality assurance liability upstream. This behavioral change is most visible in separator coating supply chains, where lot rejection rates have doubled and supplier qualification periods extended by six months.
High-Purity Boehmite Market Segmentation
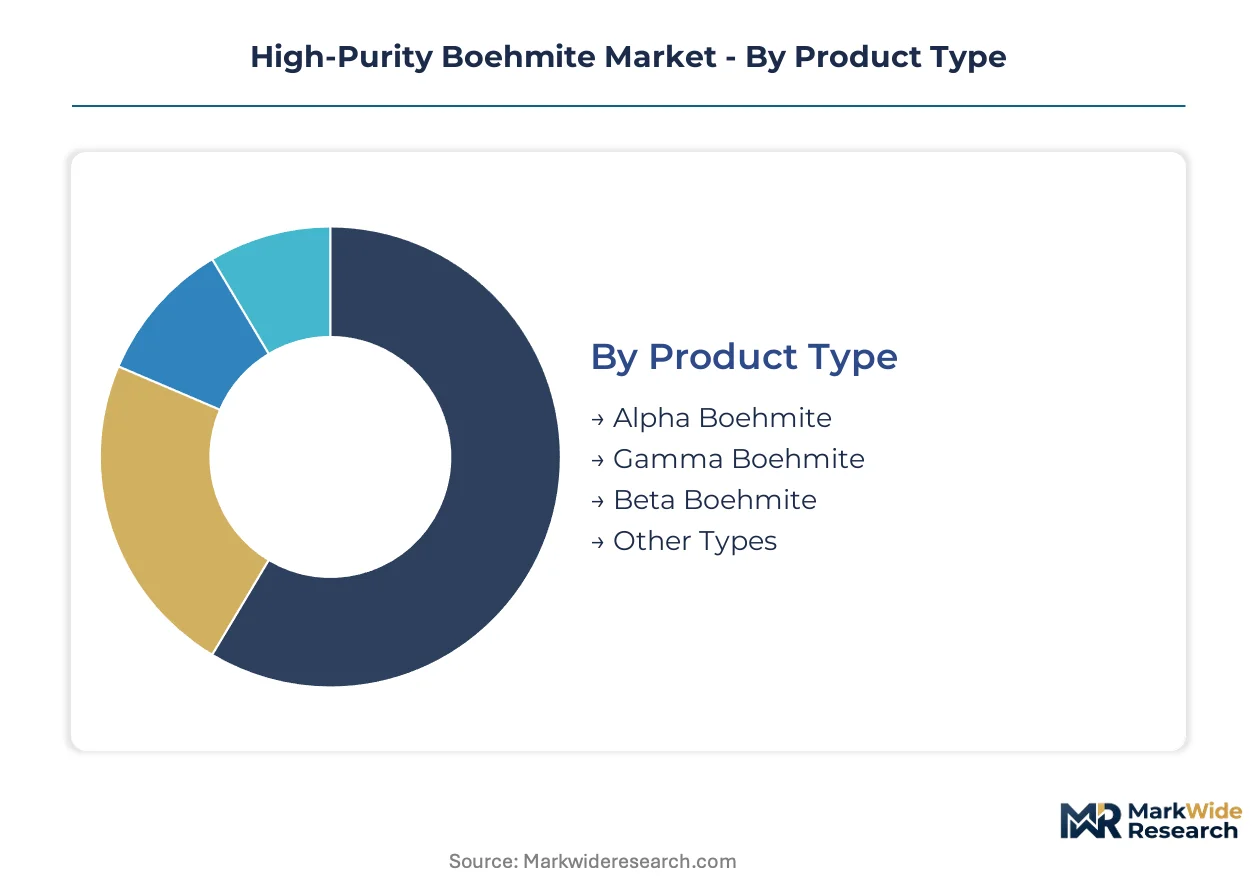
Polymorph phase purity and trace-metal thresholds determine supplier qualification speed in battery separator coatings. Segment boundaries are hardening as cell manufacturers conduct in-house XRD verification rather than accepting certificates. Procurement contracts now specify alpha-phase content percentages, not generic alumina grades.
Product Type:
Cost tier separation between polymorphs has widened as battery-grade specifications tighten alpha-phase premiums against gamma alternatives.
- Alpha Boehmite:Thermodynamically stable AlOOH polymorph with sodium content below 50 ppm and controlled platelet morphology for thin-film ceramic deposition. Korean and German cell manufacturers anchor procurement volumes here, compressing qualification timelines from 18 months to 8 months.
- Gamma Boehmite:Metastable orthorhombic structure with higher surface area but lower thermal stability above 800°C. Chinese producers supply adsorption and lower-tier coating applications where REACH thresholds are less stringent.
- Beta Boehmite:Rare triclinic polymorph with niche applications in specialized catalyst supports requiring intermediate surface acidity.
- Other Types:Mixed-phase or amorphous precursors used in refractory binders and legacy ceramic processing.
Alpha Boehmite holds installed capacity. Gamma Boehmite is rotating up the share rankings in cost-sensitive adsorption markets.
End User:
Application maturity spans from qualified battery supply chains to commodity refractory markets with diverging purity requirements.
- Electronics:Solid-state electrolyte research in Japan and South Korea drives sub-100 nanometer platelet demand for sulfide and oxide cell architectures. METI stockpiling incentives accelerate domestic qualification cycles.
- Coatings:Ceramic separator coatings for lithium-ion cells require polymorph-specific procurement contracts with lot-by-lot XRD verification. Northvolt and CATL European operations localize supply chains away from Asian import dependence.
- Pharmaceuticals:Sub-50 ppm trace-metal specifications for excipient and controlled-release applications. TAIMEI CHEMICALS anchors Asia-Pacific supply with dedicated purification circuits.
- Ceramics:Legacy refractory and structural ceramic applications with mature margin pools and less stringent sodium thresholds.
Electronics is climbing the fastest as solid-state prototyping intensifies. Coatings retains volume concentration.
Application:
Functional performance requirements segment the market between ionic conductivity optimization and thermal barrier specifications.
- Electrical Insulation:Thin-film deposition for battery separator coatings requires particle-size distribution bands compressed to ±5%. Sol-gel and continuous hydrothermal methods displace legacy precipitation.
- Catalysis:Boehmite-alumina composites hybridize with perovskite structures for proton-exchange membrane electrolyzer electrodes. Hydrogen production catalyst supports displace mature petrochemical refining applications.
- Adsorption:Petrochemical refining retains established margin pools with gamma-phase acceptance where thermal stability requirements permit.
- Reinforcement:Polymer composite and ceramic matrix applications with intermediate purity requirements between battery-grade and industrial specifications.
Electrical Insulation commands qualification priority. Catalysis is gaining share fastest in hydrogen economy supply chains.
Grade:
Certification grade determines laboratory access and regulatory disclosure obligations across battery passport and pharmaceutical dossier requirements.
- Analytical Grade:Sub-10 ppm trace-metal detection validated through ICP-MS at fewer than 20 certified laboratories worldwide. China's GB/T standards mandate disclosure of 18 trace elements down to 1 ppm, exceeding REACH thresholds.
- Technical Grade:Intermediate purity for industrial catalyst supports and ceramic precursors with sodium content between 50-100 ppm.
- Industrial Grade:Legacy refractory and adsorption applications with sodium content above 100 ppm, now excluded from battery-grade certification.
- Others:Custom specifications for research quantities and specialized coating formulations.
Analytical Grade holds certification infrastructure. Technical Grade is rotating up the share rankings as hydrogen catalyst applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes high-purity boehmite primarily for battery separator coatings, while Japan directs volumes toward solid-state electrolyte research and China still channels significant share into legacy adsorption applications.
Germany
Northvolt's gigafactory in Heide and CATL's Erfurt operation localize separator coating supply chains. ECHA's REACH sub-50 ppm sodium mandates filter out non-compliant imports. The North Rhine-Westphalia chemical corridor hosts flame-hydrolysis purification facilities serving cell manufacturers directly.
Japan
Solid-state battery prototyping at Toyota and Panasonic drives sub-100 nanometer platelet procurement. METI's critical materials stockpiling incentives accelerate domestic qualification cycles. The Kansai region around Osaka concentrates pharmaceutical-grade specialists with sub-50 ppm trace-metal capabilities.
China
Domestic lithium-ion cell expansion by CATL and BYD pulls battery-grade volumes from legacy refractory channels. GB/T standards mandate disclosure of 18 trace elements down to 1 ppm, forcing purification circuit retrofits. The Shandong Peninsula hosts integrated alumina refiners upgrading to separator coating specifications.
South Korea
LG Energy Solution and Samsung SDI compress alpha-phase qualification timelines from 18 months to 8 months. MFDS alignment with REACH thresholds tightens import scrutiny. The Gyeonggi-Seoul corridor concentrates separator coater operations conducting in-house XRD verification.
United States
IRA domestic content incentives pull battery material supply chains toward North American sourcing. EPA toxics tracking adds disclosure layers beyond REACH. The Michigan-Ohio automotive belt hosts emerging separator coating facilities qualifying alpha-phase feedstock.
High-Purity Boehmite Market Competitive Environment
Capability concentration sits with integrated alumina refiners; scale advantage sits with diversified chemical conglomerates. The vendor base stratifies into three tiers: captive feedstock controllers, flame-hydrolysis specialists, and regional purification operators. Strategic moves center on polymorph-specific certification racing and direct-to-cell-manufacturer contracting bypassing traditional distribution.
Among integrated feedstock controllers, Sasol exemplifies upstream-to-downstream purity consistency. Flame-hydrolysis specialists include Nabaltec AG, which occupies a position within European battery-grade supply chains. TAIMEI CHEMICALS Co. Ltd represents the Asia-Pacific pharmaceutical-grade tier with sub-50 ppm trace-metal positioning.
| Leading Market Players |
|---|
| Sasol |
| Nabaltec AG |
| Osang Group |
| TOR Minerals |
| Silkem |
| TAIMEI CHEMICALS Co. Ltd |
| Zibo Honghe Chemical |
| AnHui Estone Materials Technology |
| CHALCO Shandong Advanced Material Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
The North Rhine-Westphalia chemical corridor concentrates flame-hydrolysis purification capacity serving German cell manufacturers directly, translating feedstock scarcity into pricing power for qualified alpha-phase suppliers. Battery-grade certification compresses acceptable supplier pools, amplifying margin capture at the analytical grade tier while gamma alternatives face cost competition from Chinese refractory channels.
Pricing Analysis
Long-term offtake contracts dominate procurement between separator coaters and integrated alumina refiners, with spot transactions limited to qualification samples and emergency supply. Price differentiation rests on polymorph phase purity and trace-metal certification grade, with alpha-phase premiums widening against gamma alternatives. Cost compression in technical-grade segments intensifies as Chinese producers expand flame-hydrolysis capacity. Battery manufacturers exhibit lowest price sensitivity due to qualification lock-in, while refractory buyers rotate toward lowest-cost gamma supply.
Supply Chain Analysis
Export-control regimes on sub-micron particle production technology limit equipment flows to unlicensed producers, constraining capacity expansion outside established hubs. Supply concentrates in Germany, Japan, and South Korea for battery-grade material, with China retaining gamma-phase dominance. The chain draws from metallurgical-grade alumina feedstock sourced from Guinea and Australian bauxite refiners. Single-source vulnerability sits with ICP-MS analytical capacity concentrated at fewer than twenty certified laboratories worldwide. Distribution runs through direct-to-cell-manufacturer contracting bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat. Polymorph-specific qualification timelines create switching costs that freeze out unqualified competitors for eighteen-month certification cycles.
For Market Incumbents:Harden supply security through backward integration into metallurgical-grade alumina refining or captive bauxite offtake agreements. Expand flame-hydrolysis reactor capacity in the North Rhine-Westphalia corridor to capture Northvolt and CATL European demand localization. Gamma-phase substitution from Chinese producers threatens refractory-tier margins.
For New Entrants and Emerging Players:Pursue India's PLI scheme for advanced chemistry cells as the most penetrable geography, where domestic boehmite purification capacity remains undeveloped. Target hydrogen catalyst support applications as the fastest-expanding white-space segment with less stringent qualification barriers than battery separators. License continuous hydrothermal technology from established equipment vendors to bypass flame-hydrolysis capex barriers.
For Investors and Strategic Acquirers:Long-term, this sits as a critical-materials infrastructure play because battery passport requirements and REACH threshold tightening consolidate qualified supply among integrated refiners with analytical-grade certification infrastructure. Acquisition targets should display captive alumina feedstock positions and existing alpha-phase qualification at Korean or German cell manufacturers. Watch polymorph certification timeline compression as the inflection signal—further acceleration from eighteen to six months would intensify working-capital pressure on unqualified entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | Sasol's captive bauxite-to-calcination control secures purity consistency for battery-grade certification. |
| Flame-Hydrolysis Capacity Expansion | Nabaltec AG's reactor investments anchor European supply as ECHA REACH thresholds tighten import scrutiny. |
| Direct-to-Cell-Manufacturer Contracting | Separator coaters bypass distributor networks to lock polymorph-specific supply agreements with Northvolt. |
| Continuous Hydrothermal Technology Licensing | Sol-gel hybrid routes achieve sub-100 nanometer platelets without batch-to-batch variation for solid-state prototypes. |
| Hydrogen Catalyst Support Qualification | Boehmite-alumina composites hybridize with perovskite structures for proton-exchange membrane electrolyzer electrodes. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, combining procurement directors at Korean and German cell manufacturers with flame-hydrolysis plant managers and alumina refinery technical leads. Secondary validation drew from customs trade data, SEC filings of integrated chemical conglomerates, ECHA REACH registration dossiers, and METI critical materials stockpiling disclosures. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile polymorph-specific volume estimates.
Calibration against historical qualification timeline compression and regulatory threshold evolution anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include polymorph phase, certification grade tier, end-use application, and regional production hub classification. CAGRs were derived from installed capacity expansion schedules cross-referenced with cell manufacturer procurement disclosures. Industry-specific inputs incorporated flame-hydrolysis reactor commissioning timelines and ICP-MS laboratory certification bottlenecks.
Sensitivities concentrate around bauxite quality fluctuation in Guinea and Australia, REACH threshold alignment with China's GB/T standards, and solid-state battery prototyping scale-up rates. Forecasts reflect assumptions on polymorph certification timeline stability and analytical-grade laboratory capacity expansion. Material shifts in export-control enforcement on sub-micron particle production technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
L-Lysine Hydrochloride (HCL) Market
High-Value Chemicals
Sodium Hexametaphosphate Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
High Methoxyl Pectin Market
High-Value Chemicals
High Performance Mercury Sorbent Market
High-Value Chemicals
Hydrogen Isotope Market
High-Value Chemicals
High-Temperature Epoxy Market
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
Asia-Pacific Hydrogen Bromide Market
High-Value Chemicals
Ultra-High Purity Materials Market
High-Value Chemicals
High Molecular Weight Polyisobutylene Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
High-Purity Hydrogen Fluoride Market
High-Value Chemicals
Hydroxocobalamin Chloride Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
High-Heat Melamine Foam Market