
 1, 1-Difluoroethane Market | 2026-2036
1, 1-Difluoroethane Market Size, Share, and Industry Trends Forecast 2026-2036
1, 1-Difluoroethane Market Insights
The EU F-Gas Regulation is hardening phase-down mandates for hydrofluorocarbon refrigerants, compelling formulators to qualify lower-global-warming-potential blends. Honeywell International Inc. leverages its fluorochemical R&D infrastructure to develop next-generation refrigerant platforms that comply with tightening quota systems. Arkema S.A. anchors its position through backward integration into hydrofluoric acid and controlled fluorination chemistry. The Chemours Company competes on manufacturing scale at its Texas and Louisiana production complexes, sustaining cost positions in North American refrigerant supply.
1,1-Difluoroethane (HFC-152a, CH₃CHF₂) functions as a low-global-warming-potential fluorocarbon with a molecular weight of 66.05 g/mol and a boiling point of −24.7 °C, manufactured via catalytic fluorination of acetylene or ethylene with hydrogen fluoride. Its primary commercial purpose centers on refrigerant formulations, aerosol propellants, and polyurethane foam blowing where ozone-depletion potential is zero but global-warming-potential trade-offs still matter. The refrigerants segment leads current volume off-take as cold-chain operators and building HVAC contractors replace phased-out R-404A and R-507A systems. Propellants represent the fastest-growing structural category, driven by personal care and household aerosol brands seeking to displace higher-GWP HFC-134a in spray formulations. Solvents remain a mature, smaller-margin pool serving electronics defluxing and precision cleaning niches where hydrocarbon alternatives fail on flammancy or residue specifications.
EPA SNAP rulings in the United States restrict the use of high-GWP hydrofluorocarbons in specific end-uses, directly shaping which 1,1-difluoroethane blends gain market access. EMA and ECHA frameworks in Europe govern chemical registration and occupational exposure limits for fluorinated gases, adding compliance layers to import and formulation activities. China's MEE enforces dual carbon goals that filter down to provincial refrigerant consumption controls, affecting export demand patterns from domestic blenders. Stakeholders must monitor how national inventory methodologies treat HFC-152a's global-warming-potential values, since methodological revisions could abruptly reclassify its competitive standing against hydrocarbon and natural refrigerant alternatives.
Market Dynamics
The EU F-Gas Regulation's accelerating phase-down schedule is compressing the window for high-GWP refrigerant use, forcing formulators to requalify equipment platforms around lower-impact molecules like HFC-152a before quota restrictions harden in 2027-2030.
Growth Catalysts
- Cold-chain retrofit mandates:Warehouse operators across Germany and the Netherlands are replacing R-404A systems with HFC-152a blends to preempt F-Gas quota penalties. Equipment OEMs report accelerated specification timelines for compliant rack systems.
- Aerosol propellant reformulation:Personal care brands in France and Spain are disqualifying HFC-134a from spray formulations due to GWP disclosure requirements under CSRD reporting frameworks.
- Catalytic fluorination advances:Improved vapor-phase hydrogen fluoride reactors are yielding higher selectivity toward HFC-152a, reducing acetylene feedstock waste and improving unit economics at integrated fluorochemical sites.
Market Restraints
- Anhydrous hydrogen fluoride supply concentration:Chinese producers control roughly two-thirds of global AHHF output, exposing European and North American HFC-152a manufacturers to freight cost volatility and export license uncertainty.
- Flammability classification barriers:HFC-152a's ASHRAE A2L rating triggers stricter building code requirements in California and New York, limiting retrofit eligibility in densely occupied commercial spaces without secondary safety systems.
- Natural refrigerant substitution:R-290 propane and R-744 CO₂ systems are capturing share in small-format retail refrigeration, displacing HFC-152a from the sub-50kW equipment segment where charge size limits favor hydrocarbons.
Strategic Opportunities
- India cold-chain buildout:The country's PLI scheme for food processing infrastructure is funding integrated cold storage networks where HFC-152a offers a compliance pathway ahead of anticipated HFC consumption controls.
- Medical aerosol segment:Metered-dose inhaler manufacturers are evaluating HFC-152a as a lower-GWP alternative to HFC-134a in propellant formulations, pending toxicology data acceptance by FDA and EMA.
- Heat pump compatibility:Japanese equipment makers are testing HFC-152a in residential heat pump circuits as METI efficiency standards tighten, creating a new volume channel beyond traditional refrigeration applications.
Industry Challenges
- Fluorochemical process engineering talent scarcity:The specialized skill set for catalytic fluorination reactor design and HF handling safety is concentrated among retiring cohorts at legacy chemical sites in Texas and Louisiana.
- Blend certification timeline compression:OEMs must complete ASHRAE Standard 34 safety classification and ISO 817 flammability testing within 18-24 month windows to maintain equipment model eligibility under evolving F-Gas quota years.
- Refrigerant recovery infrastructure gaps:The absence of dense HFC-152a reclamation networks outside Germany and California forces reliance on virgin material, complicating circular economy claims under EU CSRD disclosure rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1, 1-Difluoroethane Market |
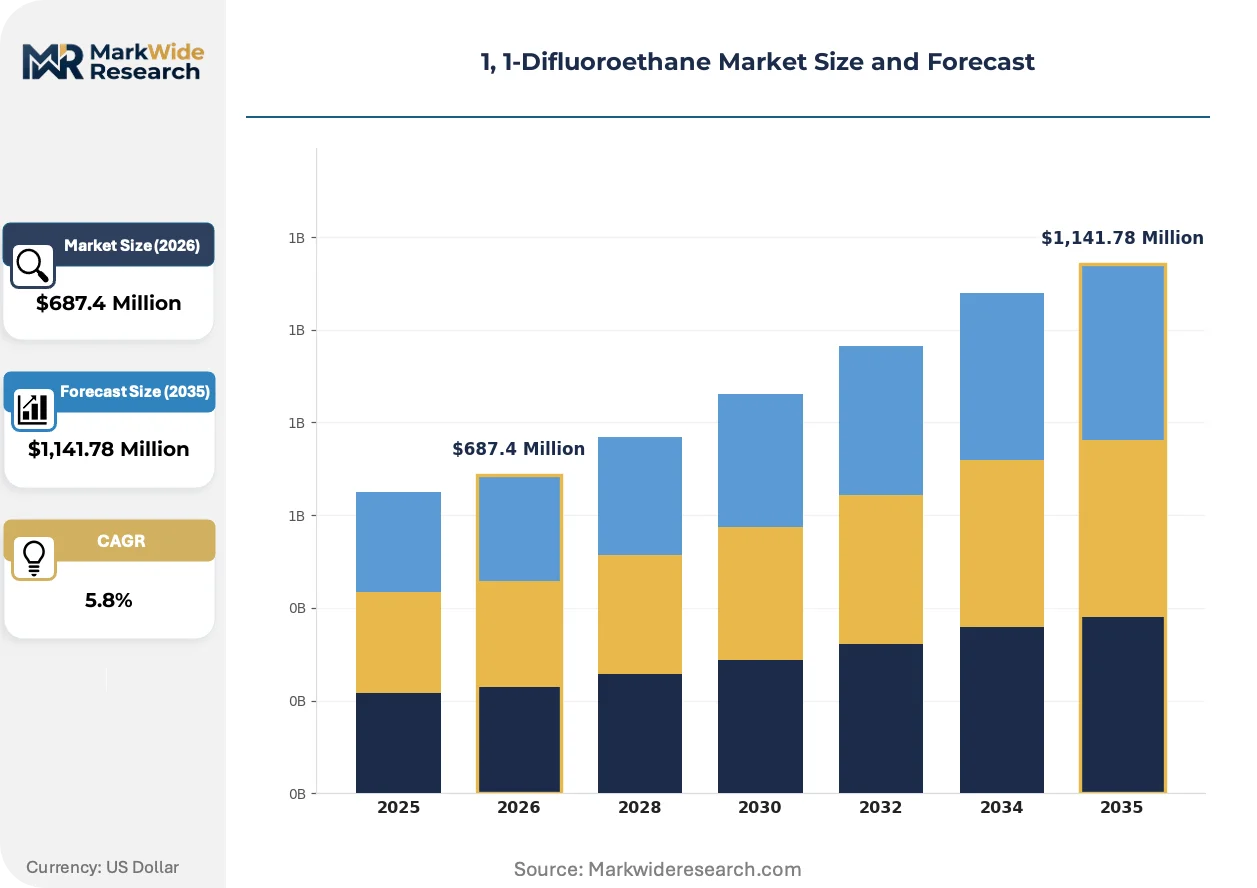
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,141.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerants, Propellants, Solvents, Blowing Agents Application: Thermal Insulation, Automotive, Aerosols, Household Products End User: Manufacturers, Retailers, Service Providers, Distributors Packaging Type: Cylinders, Drums, Totes, Bulk |
| Companies Covered | o2si, Dräger, Biosynth Carbosynth, AccuStandard, Restek, Merck, Honeywell International Inc., Arkema S.A., The Chemours Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1, 1-Difluoroethane Market Trends and Innovations
Refrigerant formulators are converging on modular blend architectures that swap molecular components without full system redesign, compressing product development cycles and reducing qualification risk for equipment OEMs.
Modular refrigerant platforms are decentralizing supply chain control from integrated chemical majors toward regional blending operations. Independent compounders in Poland and Texas are licensing base fluid formulations, then customizing final blends for local HVAC contractors. This shift compresses lead times from 12 weeks to 3 weeks for specialty low-GWP mixtures.
The EU F-Gas Regulation's 2024 quota cut is forcing refrigerant distributors to restructure inventory positions. Wholesale operators in Italy and Belgium are liquidating high-GWP stocks ahead of phasedown deadlines while securing forward contracts for HFC-152a and HFO-1234yf volumes. Cold-chain contractors in Scandinavia report 40% longer procurement cycles as allocation systems replace spot purchasing.
Personal care procurement teams are consolidating aerosol propellant specifications across brand portfolios to simplify CSRD carbon accounting. Unilever and Henkel operations in Germany are standardizing on HFC-152a for deodorant and hair care lines previously split between hydrocarbons and HFC-134a. This consolidation eliminates SKU-level emissions tracking complexity but concentrates volume risk with fewer qualified chemical suppliers.
1, 1-Difluoroethane Market Segmentation
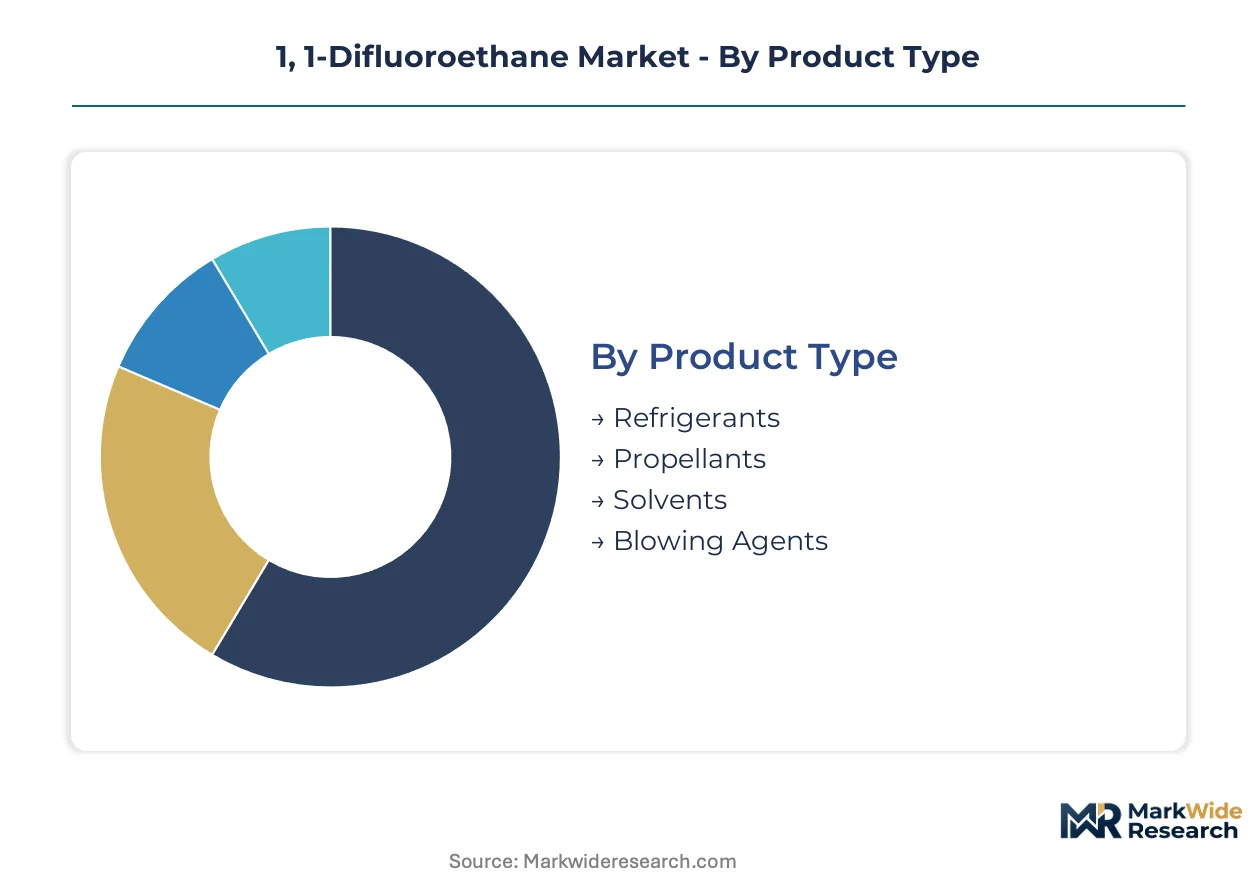
Segmentation in the 1,1-difluoroethane market tracks how regulatory pressure and end-use specifications fragment demand across incompatible technical requirements. Buyers prioritize GWP compliance, flammability ratings, and equipment compatibility when selecting grades.
Product Type:
Buyers segment by global-warming-potential thresholds and equipment compatibility constraints, not molecular purity alone.
- Refrigerants:Formulated blends containing HFC-152a serve as drop-in replacements for R-404A in supermarket rack systems. Cold-chain operators in Germany and the Netherlands specify these blends to preempt F-Gas quota penalties before 2027 deadlines.
- Propellants:High-purity HFC-152a functions as a lower-GWP alternative to HFC-134a in aerosol formulations. Personal care brands under France's CSRD disclosure mandates are disqualifying higher-GWP propellants from spray product lines.
- Solvents:Electronics manufacturers employ HFC-152a for precision defluxing where hydrocarbon flammability risks exclude alternatives.
- Blowing Agents:Polyurethane foam producers integrate HFC-152a into insulation formulations for appliances and construction panels.
Volume sits with refrigerants; growth tilts toward propellants.
Application:
Application selection tracks thermal performance requirements and regulatory exposure across building, transport, and consumer sectors.
- Thermal Insulation:Spray foam and panel manufacturers specify HFC-152a blowing agents for residential and commercial building envelopes where energy codes tighten.
- Automotive:Mobile air conditioning systems in electric vehicles test HFC-152a blends for weight and efficiency advantages over R-134a.
- Aerosols:Deodorant and hair care formulations in Spain and France convert from HFC-134a to meet corporate sustainability reporting thresholds.
- Household Products:Cleaning spray and air freshener brands evaluate HFC-152a for flammability compliance in warehouse storage regulations.
Current volume concentrates in thermal insulation; aerosols climb the fastest on brand sustainability commitments.
End User:
End-user type determines contract structure, with formulators seeking long-term offtake and distributors managing quota allocation risk.
- Manufacturers:Integrated chemical producers and independent compounders purchase bulk HFC-152a for captive blend production or tolling arrangements.
- Retailers:Big-box home improvement chains stock cylinder formats for contractor pickup, exposing them to refrigerant handling certification requirements.
- Service Providers:HVAC contractors and cold-chain maintenance firms buy packaged quantities for retrofit installations and leak repair.
- Distributors:Wholesale operators manage inventory positions across high-GWP liquidation and low-GWP forward contracting under F-Gas allocation systems.
Procurement scale favors manufacturers; service providers expand quickest on retrofit mandate timing.
Packaging Type:
Packaging selection balances inventory carrying cost against handling efficiency and site storage constraints.
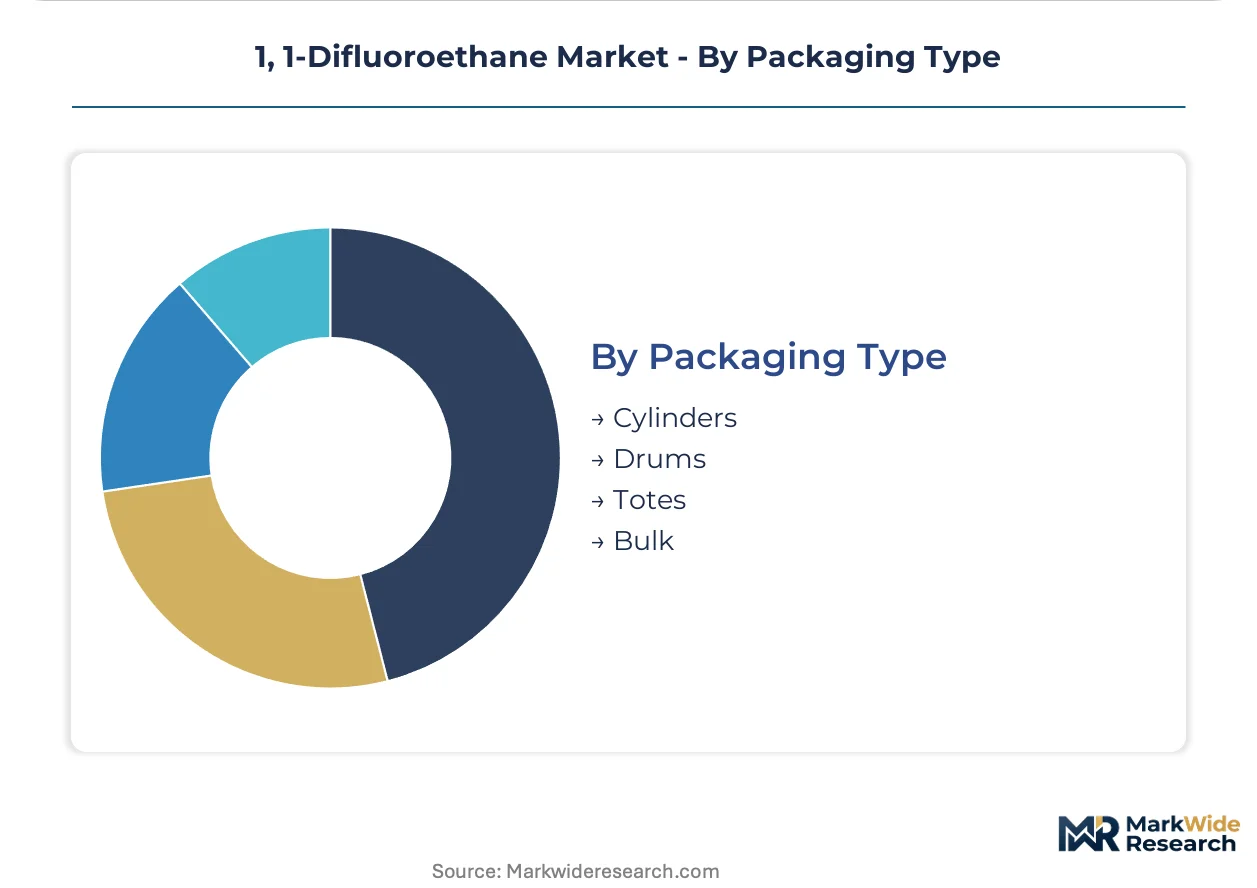
- Cylinders:Portable 10-50 lb containers serve field technicians and small contractors for spot refrigeration service and aerosol filling operations.
- Drums:55-gallon steel drums supply mid-scale foam blowing operations and regional aerosol compounders with manageable forklift access.
- Totes:Intermediate bulk containers reduce drum handling labor for continuous-process manufacturers with dedicated storage infrastructure.
- Bulk:Tank truck and railcar deliveries feed integrated refrigerant blenders and large polyurethane producers at Texas and Louisiana chemical complexes.
Shipment volume concentrates in bulk; totes gain share fastest among mid-tier compounders seeking logistics efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston's petrochemical corridor anchors North American 1,1-difluoroethane production capacity, with integrated fluorochemical complexes supplying refrigerant blenders across the continent. Cold-chain logistics networks in Rotterdam and Antwerp drive European demand for low-GWP formulations. Asian manufacturing clusters in Shanghai and Osaka are retrofitting industrial refrigeration systems ahead of tightening environmental controls.
United States
Warehouse operators in California and Texas are accelerating R-404A system replacements to comply with EPA SNAP rulings restricting high-GWP hydrofluorocarbons. The Inflation Reduction Act's efficiency incentives are redirecting federal procurement toward lower-impact refrigerant platforms. Gulf Coast chemical complexes in Louisiana and Texas sustain integrated production of HFC-152a feedstock for domestic blenders.
Germany
Supermarket chains in Bavaria and North Rhine-Westphalia are specifying HFC-152a blends for rack refrigeration systems ahead of 2027 F-Gas quota deadlines. The EU F-Gas Regulation's accelerating phase-down schedule is compressing equipment requalification timelines for OEMs. Industrial refrigerant distributors in Frankfurt and Hamburg are restructuring inventory positions toward low-GWP forward contracts.
China
Provincial cold-storage buildouts in Jiangsu and Shandong are absorbing refrigerant-grade HFC-152a volumes as food processing infrastructure expands. The Ministry of Ecology and Environment's dual carbon goals are filtering down to consumption controls affecting domestic blenders. Yangtze River Delta chemical producers dominate global anhydrous hydrogen fluoride supply, exposing downstream manufacturers to export license uncertainty.
Japan
Residential heat pump manufacturers in Osaka and Nagoya are testing HFC-152a circuits as METI efficiency standards tighten for climate control equipment. The country's fluorochemical sector maintains captive fluorination capacity for specialty refrigerant production. Industrial gas distributors in Tokyo Bay are consolidating aerosol propellant supply chains for personal care brand portfolios.
India
Integrated cold storage networks in Maharashtra and Gujarat are expanding under the PLI scheme for food processing infrastructure. State-level electricity regulators are tightening commercial building efficiency codes that favor lower-GWP refrigerant specifications. Mumbai-based chemical distributors are establishing regional blending operations to serve South Asian HVAC contractors.
1, 1-Difluoroethane Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fluorochemical integration depth, with backward-integrated manufacturers capturing value from hydrogen fluoride through finished refrigerant formulations. The vendor base stratifies into three archetypes: integrated chemical majors controlling catalytic fluorination infrastructure, regional compounders licensing base fluid formulations, and specialty gas distributors managing quota allocation logistics. Dominant competitive moves include capacity expansion at Gulf Coast production complexes and technology licensing agreements enabling independent blenders to qualify low-GWP mixtures under compressed certification timelines.
Within the integrated chemical tier, Honeywell International Inc. and Arkema S.A. exemplify archetypes of fluorochemical R&D infrastructure and controlled fluorination chemistry respectively. The Chemours Company occupies a position representing manufacturing scale at North American production complexes. These entities anchor competitive positioning through captive supply of hydrofluoric acid feedstock, while specialty gas firms like o2si and Dräger sit within the distribution and calibration tier serving analytical and safety equipment markets. Merck represents the diversified chemical conglomerate archetype with cross-segment fluorochemical exposure.
| Leading Market Players |
|---|
| o2si |
| Dräger |
| Biosynth Carbosynth |
| AccuStandard |
| Restek |
| Merck |
| Honeywell International Inc. |
| Arkema S.A. |
| The Chemours Company |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation's tightening quota schedule gates qualified supply for low-GWP refrigerant grades while simultaneously anchoring premium-tier pricing access for compliant blenders serving cold-chain retrofit mandates.
Pricing Analysis
Value-based pricing anchors on F-Gas quota compliance outcomes, with refrigerant blenders commanding premiums for ASHRAE Standard 34 certified formulations that preempt regulatory penalties. Three-tier pricing structure across premium, standard, and economy levels separates quota-compliant specialty blends from commodity-grade propellants and uncertified solvent grades. Cost compression in standard-tier propellants is intensifying because personal care brands are consolidating specifications under CSRD disclosure rules. Regional HVAC contractors show highest price sensitivity due to thin retrofit margins, while integrated chemical majors absorb premiums for backward-integrated supply security.
Supply Chain Analysis
Single-source vulnerability sits with Chinese producers controlling roughly two-thirds of global anhydrous hydrogen fluoride output, exposing European and North American HFC-152a manufacturers to export license uncertainty. Manufacturing concentrates in China, the United States, and Germany, with Yangtze River Delta chemical complexes feeding downstream fluorination operations. Feedstock dependencies rest on acetylene or ethylene, hydrogen fluoride, and specialized vapor-phase reactor catalysts. Tariff exposure on AHHF imports from China threatens margin stability for non-integrated blenders. Distribution runs through regional refrigerant distributors managing F-Gas allocation logistics and forward contracting positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where the EU F-Gas Regulation's accelerating phase-down schedule is forcing sub-scale compounders and non-integrated blenders toward exit or acquisition.
For Market Incumbents: To counter natural refrigerant substitution in small-format retail refrigeration, integrated chemical majors should deepen backward integration into hydrogen fluoride supply while expanding catalytic fluorination capacity at Gulf Coast complexes. Certification investment in ASHRAE Standard 34 and ISO 817 testing infrastructure preserves equipment OEM relationships under compressed requalification timelines. For New Entrants and Emerging Players: Mid-tier aerosol compounders in Poland and Texas represent an underserved buyer archetype seeking licensed base fluid formulations for local customization. White-space targets include regional HVAC contractors in India's PLI-funded cold storage buildout and medical aerosol formulators awaiting FDA toxicology clearance. A toll-blending go-to-market angle minimizes capital intensity while building formulation expertise. For Investors and Strategic Acquirers: The 2024 F-Gas quota cut triggering wholesale inventory restructuring is the leading indicator that distributor consolidation will accelerate across Italy and Belgium. Long-term viability over a five-to-ten-year window favors acquiring regional compounders with established OEM qualification relationships and captive fluorination capacity. Watch for OEMs completing 18-24 month safety classification windows as the signal for which blend architectures will dominate quota-limited years.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Fluoride | Captive AHHF supply insulates margin from Chinese export license volatility. |
| Modular Refrigerant Platform Licensing | Regional compounders in Poland compress lead times from 12 weeks to 3 weeks. |
| ASHRAE Standard 34 Certification Investment | Prequalified blends maintain equipment OEM eligibility under F-Gas deadlines. |
| Medical Aerosol Toxicology Data Package | FDA acceptance unlocks metered-dose inhaler propellant substitution revenue. |
| Heat Pump Circuit Compatibility Testing | METI efficiency standards in Japan open residential climate control volume. |
Research Methodology
Independent corroboration across fluorochemical plant managers, procurement leads at downstream HVAC OEMs, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Primary interviews with cold-chain operators in Germany and the Netherlands, aerosol compounders in France and Spain, and refrigerant distributors in Italy and Belgium combined with secondary validation from customs and trade data, Cefic fluorochemical reports, EPA SNAP rulings, and SEC 10-K filings. Bottom-up volume estimates from segment-level consumption patterns and top-down cross-checks against production capacity announcements were reconciled through iterative triangulation.
Historical reference periods spanning pre-pandemic baseline, quota-implementation transition, and post-regulatory-settlement phases anchored the forecast window across the analysis window. Segmentation dimensions modeled include product grade tier, end-use application, packaging format, and regional production hub. CAGRs were derived from slope-consistent growth trajectory fitting against equipment replacement cycle timing and regulatory deadline clustering. Industry-specific forecast inputs incorporated F-Gas quota phase-down schedules and OEM safety classification pipeline data.
Revisions become necessary when quota allocation methodologies shift, natural refrigerant cost curves steepen, or hydrogen fluoride export licensing regimes tighten. Forecasts reflect documented assumptions about equipment retrofit timing, blend certification success rates, and feedstock price stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Benzyl Alcohol Market
Solvents
Hydrocarbon Solvents Market
Solvents
Acetone Derivatives Market
Solvents
Methyl Acetate Market
Solvents
Asia-Pacific Ethane Market
Solvents
Hydrofluoroether Market
Solvents
Solvent Green 7 Market
Solvents
Green Solvents and Bio-Solvents Market
Solvents
Propylene Glycol Ether Market
Solvents
Hydrogen Cyanamide Market
Solvents
Global Furfural Solvent Market
Solvents
Ortho-Xylene Market
Solvents
North America Acetonitrile Market
Solvents
Diethanolamide Market
Solvents
Lithium-Ion Battery's Electrolyte Solvent Market
Solvents
Electronic Cleaning Solvents Market