
 Laboratory Chemical Reagents Market | 2026-2036
Laboratory Chemical Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Chemical Reagents Market Outlook
German fine-chemical producers is pivoting toward GMP-certified reagent suites to serve biopharma contract manufacturers. Thermo Fisher Scientific leverages its European distribution network to sustain just-in-time delivery for clinical diagnostics labs. Merck KGaA anchors high-purity solvent production through backward integration into semiconductor-grade feedstocks. Danaher Corporation competes on digital reagent tracking systems that integrate with automated liquid handlers.
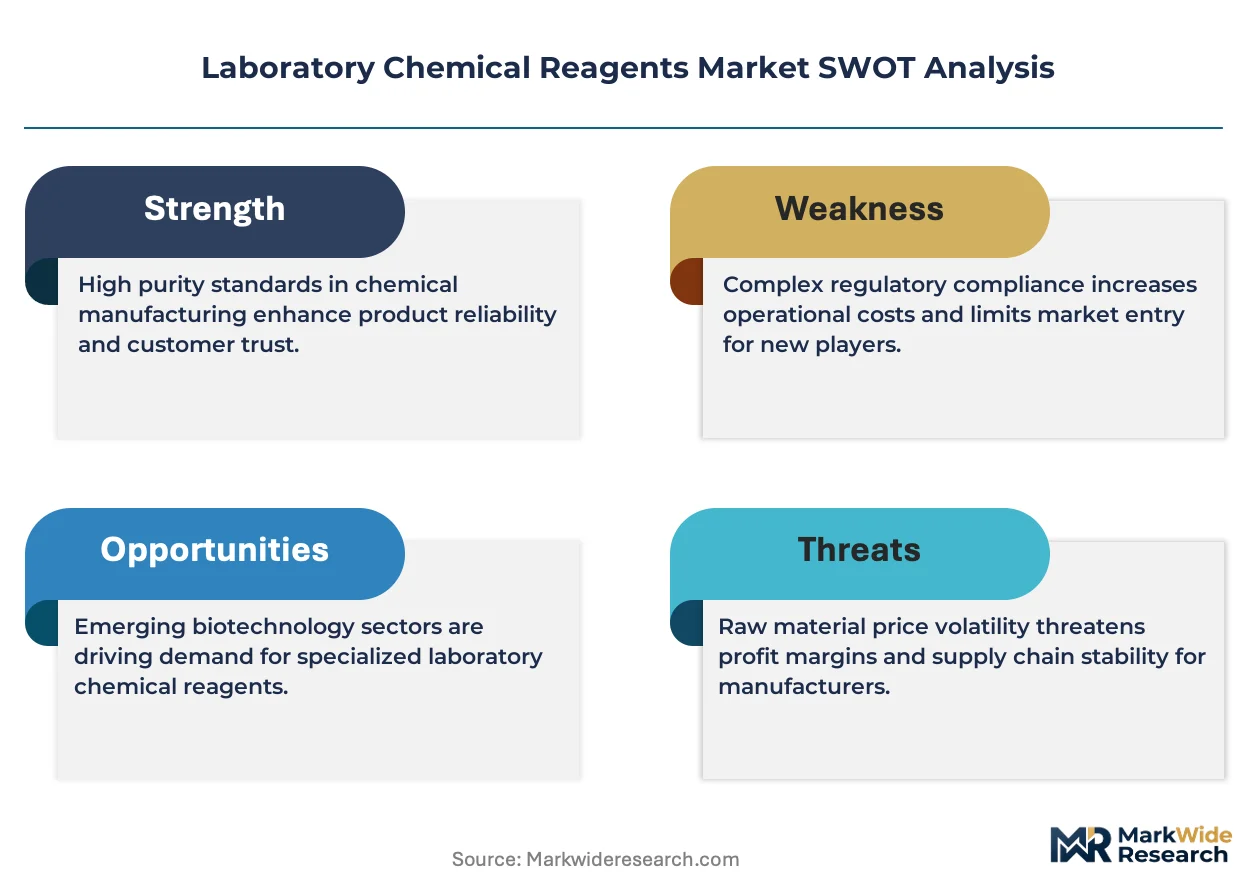
Laboratory chemical reagents encompass purified substances with defined assay values, typically manufactured through fractional distillation, crystallization, or chromatographic separation to achieve specified impurity thresholds below 0.1 percent. These compounds serve as reactive inputs, calibration standards, or analytical matrices across quantitative testing protocols in regulated industries. Biochemical reagents command premium positioning due to endotoxin-controlled production lines and cold-chain dependency that limits supplier pools. Analytical reagents for environmental testing face margin compression from instrument miniaturization, while ACS-grade products retain pricing power through pharmacopeial recognition in pharmaceutical quality control.
FDA's current good manufacturing practice guidelines and EPA's test method specifications shape reagent qualification protocols for U.S. environmental and clinical labs. ECHA's REACH authorization list restricts certain solvent precursors, forcing reformulation investments among European suppliers. ISO 17034 reference material producers gain preferential access to national metrology institute contracts. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs to anticipate qualification cost shifts.
Market Dynamics
Pharmaceutical quality control laboratories are expanding reagent consumption as biosimilar pipelines deepen, while REACH and CLP classifications in Europe tighten purity documentation requirements for cross-border chemical shipments.
Growth Catalysts
- Biosimilar pipeline expansion:Pharmaceutical contract manufacturers in Germany's Rhine-Main cluster are scaling GMP-certified reagent suites to support biologics quality control.
- REACH authorization mandates:ECHA's tightening purity documentation requirements are forcing laboratory upgrades that favor certified reagent suppliers with compliant documentation systems.
- Semiconductor-grade solvent demand:Backward integration into high-purity feedstocks is creating captive supply advantages for producers serving analytical instrumentation OEMs.
Market Restraints
- Precursor solvent restrictions:ECHA's REACH authorization list limits certain solvent precursors, forcing European suppliers into costly reformulation investments.
- Cold-chain dependency:Biochemical reagents require endotoxin-controlled production lines and temperature-controlled logistics that constrain supplier pools and inflate working capital requirements.
- Instrument miniaturization:Environmental testing labs are reducing per-test reagent volumes through microfluidic platforms, compressing margins on analytical-grade products.
Strategic Opportunities
- Digital reagent tracking integration:Automated liquid handlers in clinical diagnostics labs are creating demand for barcode-enabled reagent systems that synchronize with LIMS platforms.
- Pharmacopeial harmonization:Alignment between USP, EP, and JP monographs is reducing qualification costs for suppliers with multi-jurisdictional certification.
- Contract research co-location:Germany's chemical clusters are attracting specialty reagent distributors who embed inventory management directly at CRO sites.
Industry Challenges
- ISO 17034 certification timelines:Reference material producers face extended validation periods to secure national metrology institute contracts, delaying revenue recognition.
- Endotoxin control expertise:Biochemical reagent manufacturing requires specialized cleanroom operations and pyrogen testing capabilities that limit workforce mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Chemical Reagents Market |
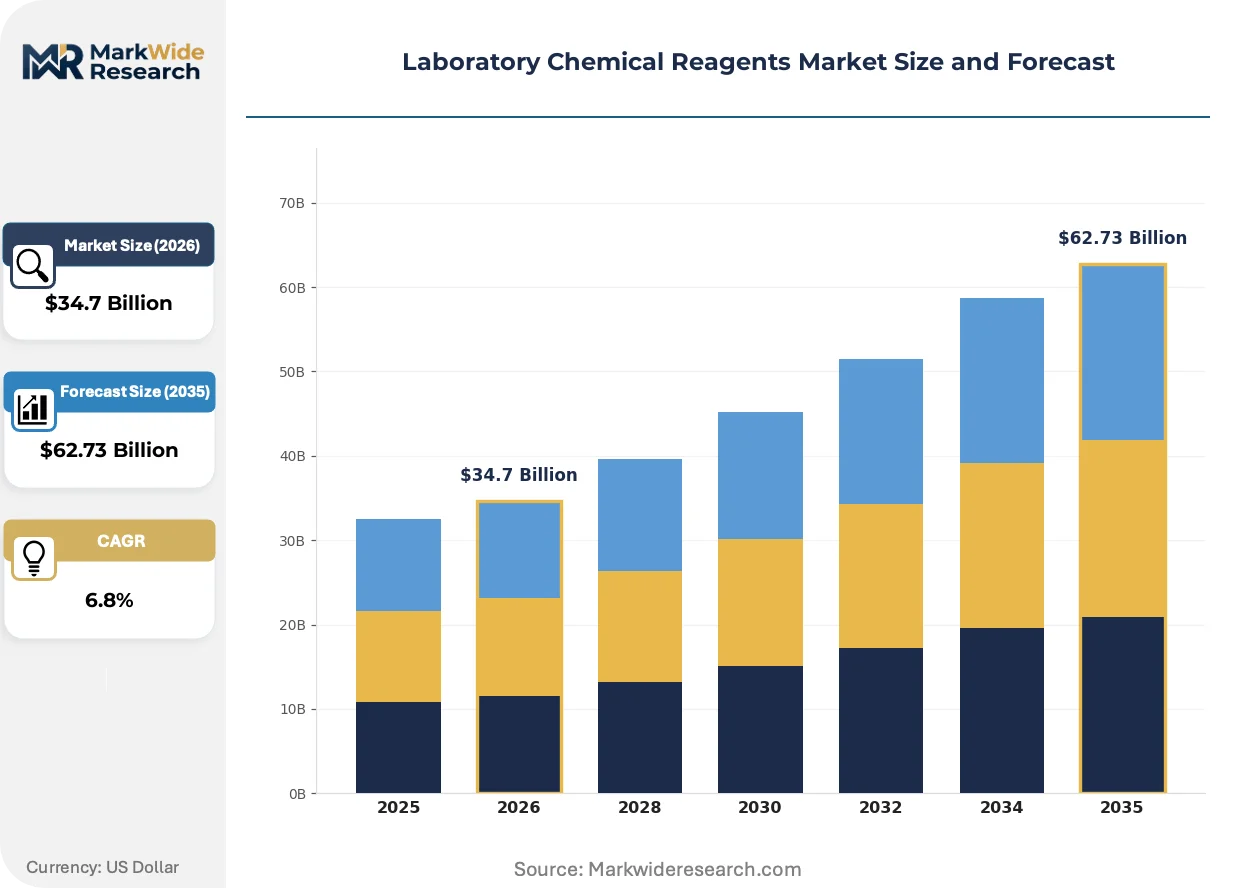
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Reagents, Inorganic Reagents, Biochemical Reagents, Analytical Reagents End Use Industry: Pharmaceuticals, Agriculture, Environmental Testing, Food & Beverage Packaging Type: Bottles, Pouches, Drums, Tubs Quality Grade: Reagent Grade, ACS Grade, Technical Grade, Others |
| Companies Covered | Agilent Technologies, Danaher Corporation, Thermo Fisher Scientific, Honeywell International, PerkinElmer, Merck KGaA, Bio-Rad Laboratories, FUJIFILM Wako Pure Chemical Corporation, Avantor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Chemical Reagents Market Strategic Shifts
Reagent supply chains are restructuring around just-in-time delivery models that synchronize with automated laboratory workflows, while digital tracking systems replace manual inventory management.
Chromatographic separation technologies for impurity profiling are converging with mass spectrometry detection platforms. Clinical diagnostics labs in Germany and Switzerland are adopting these integrated systems at accelerated replacement cycles. The technology convergence is compressing the supplier base toward vendors offering bundled reagent-instrument qualification packages.
ECHA's CLP classification revisions are expanding substance labeling requirements for cross-border chemical shipments. European distributors are restructuring documentation workflows to maintain customs clearance velocity. Specialty reagent exporters to Germany's Rhine-Main cluster are investing in automated regulatory data management systems to preempt border delays.
Consolidated procurement through group purchasing organizations is displacing direct supplier relationships among mid-sized environmental testing laboratories. Regional laboratory networks in Germany are centralizing reagent buying through specialized distributors with vendor-managed inventory programs. This channel consolidation is most visible in water quality testing operations serving municipal utilities.
Laboratory Chemical Reagents Market Segmentation
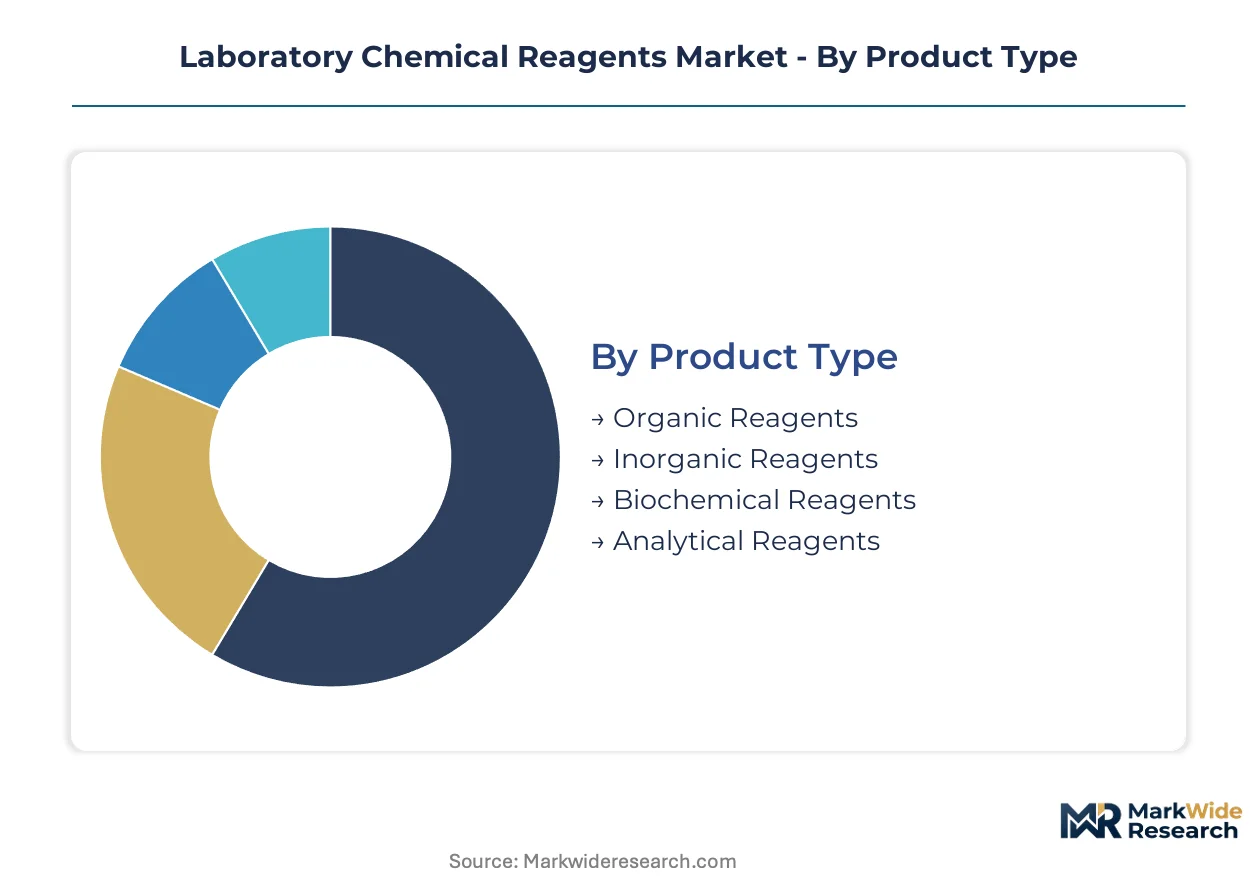
Segmentation in laboratory chemical reagents reveals how purity specifications, packaging logistics, and end-use compliance requirements create distinct competitive arenas. Suppliers configure production assets and certification investments around these boundaries rather than pursuing horizontal coverage.
Product Type:
Replacement cycles vary sharply across reagent chemistries, with instrumentation upgrades driving faster obsolescence for analytical-grade formulations than for commodity inorganics.
- Organic Reagents:Solvent-based compounds synthesized through fractional distillation and catalytic hydrogenation, typically specified to 99.5% purity thresholds. Demand concentrates in pharmaceutical quality control laboratories across Germany's Rhine-Main cluster, where HPLC method transfers require batch-to-batch consistency that favors qualified suppliers with dedicated production trains.
- Biochemical Reagents:Enzymes, antibodies, and cell culture media manufactured under endotoxin-controlled conditions with cold-chain dependency from production through point-of-use. Academic research institutions in Switzerland and contract research organizations in the Netherlands are expanding procurement of these temperature-sensitive products, though working capital intensity limits distributor participation.
- Inorganic Reagents:Acids, bases, and salts produced through crystallization and aqueous purification, serving routine titration and pH adjustment protocols.
- Analytical Reagents:Standardized compounds for calibration and quality control testing, requiring ISO 17034 certification for reference material status.
Volume placements concentrate in Inorganic Reagents; the faster expansion belongs to Biochemical Reagents.
End Use Industry:
Cost-tier differentiation separates pharmaceutical laboratories willing to pay pharmacopeial-grade premiums from environmental testing facilities optimizing per-test economics.
- Pharmaceuticals:GMP-certified reagent suites for active pharmaceutical ingredient testing and finished product release, governed by FDA and EMA validation protocols. Biosimilar manufacturers in Germany are deepening reagent consumption as pipeline complexity increases, with quality control laboratories demanding documentation packages that satisfy USP, EP, and JP harmonization requirements.
- Environmental Testing:EPA and ECHA-compliant reagents for water, soil, and air quality analysis, facing margin pressure from instrument miniaturization and microfluidic platform adoption. Regional laboratory networks in Germany's municipal utility sector are consolidating procurement through group purchasing organizations, displacing direct supplier relationships.
- Agriculture:Pesticide residue testing and soil nutrient analysis reagents, with demand tied to seasonal planting cycles and export certification requirements.
- Food & Beverage:Microbiological media and allergen detection reagents for safety testing and label verification.
Revenue concentration sits with Pharmaceuticals; the steepest expansion trajectory is emerging in Environmental Testing as regulatory test method specifications proliferate.
Packaging Type:
Supply concentration around automated filling lines favors formats that maximize throughput while minimizing contamination risk during dispensing operations.
- Bottles:Amber glass and fluoropolymer containers for light-sensitive and high-purity reagents, dominating laboratory-scale consumption. Clinical diagnostics labs in Germany are adopting barcode-enabled bottle systems that integrate with automated liquid handlers and LIMS platforms, creating demand for serialization-ready packaging.
- Drums:Stainless steel and high-density polyethylene bulk containers for solvent distribution and production-scale chemical manufacturing. Contract research organizations co-located with specialty reagent distributors in the Rhine-Main cluster favor drum formats for high-throughput screening operations where consumption velocity justifies bulk procurement.
- Pouches:Flexible film packaging for single-use aliquots and field testing kits.
- Tubs:Wide-mouth containers for solid reagents and hygroscopic salts requiring spatula access.
Procurement volume clusters in Bottles; Pouches are climbing the fastest as point-of-care and decentralized testing applications expand.
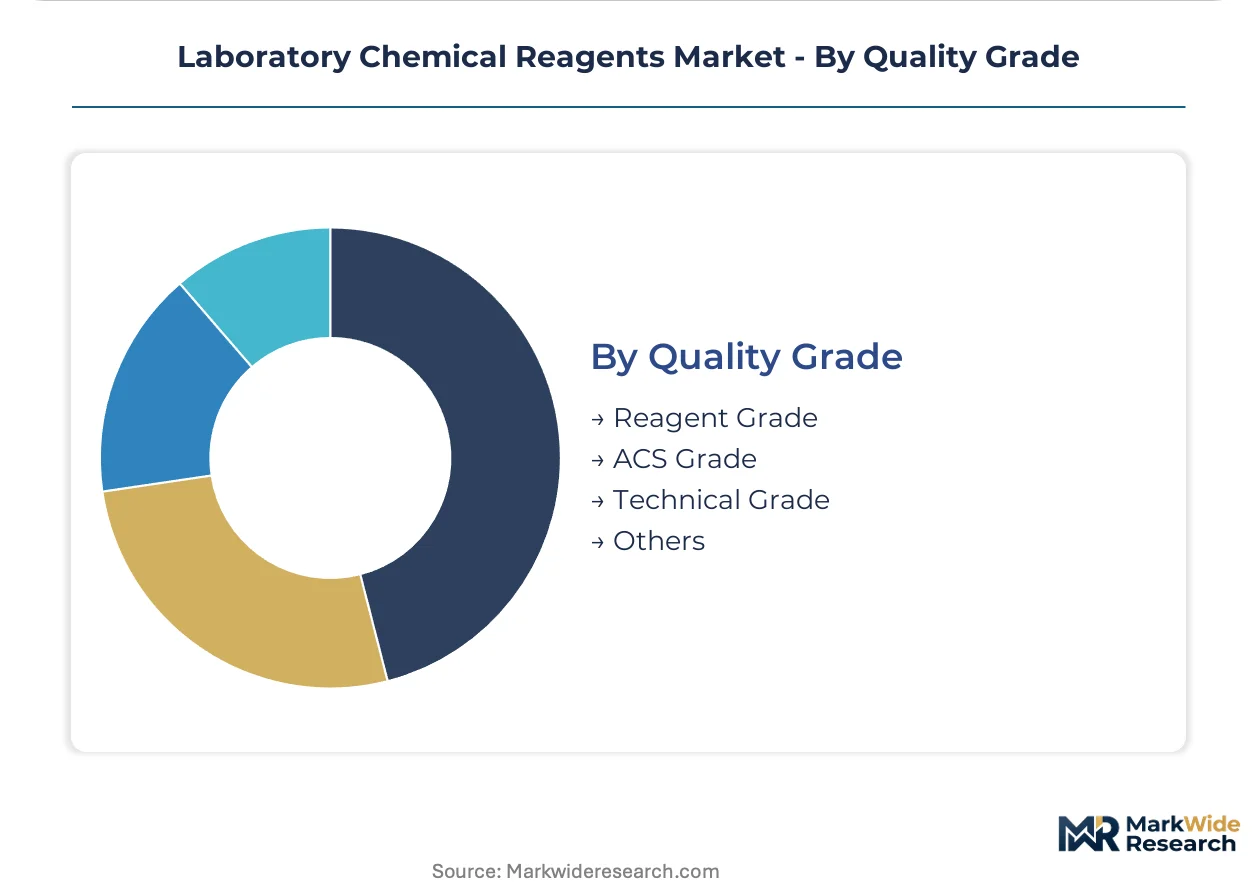
Quality Grade:
Margin structures stratify sharply across certification tiers, with pharmacopeial recognition creating pricing power that technical grades cannot replicate.
- ACS Grade:Reagents meeting American Chemical Society specifications with defined impurity thresholds below 0.1%, retaining premium positioning through pharmacopeial recognition in pharmaceutical quality control. Manufacturers serving FDA-regulated facilities maintain dedicated production lines with batch documentation that satisfies current good manufacturing practice guidelines.
- Reagent Grade:High-purity compounds for analytical and research applications, positioned between ACS and technical specifications. Environmental testing laboratories in Germany's water quality sector are standardizing on this tier as a cost-optimized alternative to ACS grades for non-regulatory monitoring protocols.
- Technical Grade:Industrial-scale reagents for synthesis and manufacturing processes where ultra-trace impurity control is unnecessary.
- Others:Custom and proprietary grades for specialized applications including semiconductor and nuclear specifications.
Revenue share peaks with ACS Grade; Reagent Grade is gaining share fastest as mid-tier laboratories seek qualification cost reductions without sacrificing method reliability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity solvent production clusters along Germany's Rhine-Main corridor anchor European supply capacity. Specialty reagent distributors co-locate with contract research organizations in this chemical belt to enable just-in-time inventory management for clinical diagnostics laboratories.
Germany
Biosimilar manufacturers in the Rhine-Main cluster are scaling GMP-certified reagent consumption as pipeline complexity deepens. ECHA's REACH authorization mandates tighten purity documentation requirements for cross-border chemical shipments. Frankfurt's logistics hub supports vendor-managed inventory programs that embed distributors directly at contract research organization sites.
United States
Pharmaceutical quality control laboratories drive demand for ACS-grade reagents with pharmacopeial recognition. FDA's current good manufacturing practice guidelines shape reagent qualification protocols for active pharmaceutical ingredient testing. Boston's biotech corridor concentrates procurement of endotoxin-controlled biochemical reagents for cell culture applications.
Switzerland
Academic research institutions expand procurement of temperature-sensitive biochemical reagents despite cold-chain dependency constraints. Swissmedic's quality standards align with EMA protocols for reference material certification. Basel's pharmaceutical cluster attracts specialty distributors offering barcode-enabled reagent systems for automated liquid handlers.
China
Semiconductor-grade solvent demand accelerates backward integration into high-purity feedstock production. NMPA's pharmaceutical regulations drive adoption of GMP-certified reagent suites for domestic drug manufacturing. Shanghai's Pudong district concentrates analytical reagent distribution serving environmental testing laboratories facing instrument miniaturization pressures.
Japan
Clinical diagnostics labs adopt integrated chromatography-mass spectrometry systems at accelerated replacement cycles. PMDA's harmonization with USP and EP monographs reduces qualification costs for multi-jurisdictional suppliers. Osaka's chemical manufacturing belt supports captive production of HPLC-grade solvents for pharmaceutical quality control.
Laboratory Chemical Reagents Market Competitive Environment
Global majors compete with regional champions across distribution reach and certification depth. The market structure tiers between integrated life science conglomerates and specialized purity-grade producers. Three archetypes dominate: diversified analytical instrumentation suppliers, fine-chemical backward-integrators, and digital tracking system specialists. Consolidation proceeds through strategic co-location partnerships with contract research organizations rather than horizontal mergers.
Among diversified analytical instrumentation suppliers, Agilent Technologies and PerkinElmer exemplify the bundled reagent-instrument qualification model. Danaher Corporation occupies a position within the digital tracking tier, while Thermo Fisher Scientific anchors the European distribution network archetype. Merck KGaA represents backward integration into semiconductor-grade feedstocks, and Bio-Rad Laboratories sits within the biochemical reagent specialization segment.
| Leading Market Players |
|---|
| Agilent Technologies |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Honeywell International |
| PerkinElmer |
| Merck KGaA |
| Bio-Rad Laboratories |
| FUJIFILM Wako Pure Chemical Corporation |
| Avantor, Inc. |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical quality control laboratories in Germany's Rhine-Main cluster concentrate procurement power around GMP-certified reagent suites, anchoring a contract-based pricing model where pharmacopeial-grade premiums reflect batch documentation investments rather than commodity spot dynamics.
Pricing Analysis
Service bundling separates qualified suppliers offering ISO 17034-certified reference materials with full regulatory documentation from unbundled commodity producers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and endotoxin control capability. Pricing pressure stems from instrument miniaturization in environmental testing, where microfluidic platforms compress per-test reagent volumes. Environmental laboratories exhibit highest price sensitivity, while biosimilar manufacturers accept pharmacopeial-grade premiums for multi-jurisdictional harmonization.
Supply Chain Analysis
High-purity solvent production rests on German specialty chemical producers with backward integration into semiconductor-grade feedstocks, drawing from fractional distillation capacity and chromatographic separation infrastructure. Key inputs include pyrogen-free water systems, cold-chain logistics networks, and amber glass packaging with fluoropolymer liners. Single-source vulnerability concentrates in endotoxin-controlled biochemical reagents where qualified cleanroom operations limit supplier pools. Distribution runs through vendor-managed inventory programs embedding distributors directly at contract research organization sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive control over high-purity feedstocks determines margin capture, with semiconductor-grade solvent backward integration representing the decisive upstream lever.
For Market Incumbents: Lock in GMP-certified production train exclusivity through dedicated capacity expansion in Germany's Rhine-Main corridor. Defend against digital tracking specialists by integrating barcode-enabled reagent systems with automated liquid handlers. Prioritize pharmacopeial harmonization investments that reduce customer qualification costs across USP, EP, and JP monographs.
For New Entrants and Emerging Players: Specialty distributors with cold-chain logistics capabilities represent the most viable channel partnership for biochemical reagent market entry. Target Switzerland's academic research institutions where temperature-sensitive procurement expands fastest with limited incumbent saturation. Pursue co-location partnerships with contract research organizations to embed inventory management directly at consumption points.
For Investors and Strategic Acquirers: The window for entry favors ISO 17034-certified reference material producers with national metrology institute contracts already secured. Long-term viability hinges on regulatory data management automation that preempts ECHA border documentation delays. Watch ECHA's REACH authorization list expansion as the critical inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor-Grade Feedstocks | Merck KGaA's captive solvent production anchors high-purity supply security for analytical instrumentation OEMs. |
| Digital Reagent Tracking Integration | Danaher's barcode-enabled systems synchronize with LIMS platforms in clinical diagnostics laboratories. |
| GMP-Certified Production Train Expansion | German fine-chemical producers scale dedicated lines to serve biosimilar quality control demand. |
| Pharmacopeial Harmonization Investment | Multi-jurisdictional certification reduces qualification costs for suppliers serving FDA and EMA-regulated facilities. |
| Co-Location Partnership with Contract Research Organizations | Specialty distributors embed vendor-managed inventory directly at CRO sites in the Rhine-Main cluster. |
Study Parameters
Multi-period observation of reagent procurement patterns, regulatory submission timelines, and instrumentation replacement cycles anchored the trend analysis, supplemented by interviews with plant managers at fine-chemical producers, procurement leads at pharmaceutical quality control laboratories, distribution channel partners in Germany's chemical cluster, and technical R&D directors at reference material suppliers. Secondary validation drew from ECHA REACH authorization databases, FDA current good manufacturing practice guidelines, SEC 10-K filings of listed life science conglomerates, and customs trade data for high-purity solvent shipments. Bottom-up segment sizing triangulated against top-down industry value chain estimates.
Segment-weighting across product type, quality grade, packaging format, and end-use industry shaped the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical replacement cycles and forward-looking regulatory pipeline impacts. Modeled inputs included biosimilar pipeline depth, ECHA CLP classification revision schedules, and semiconductor fabrication capacity expansion trajectories.
Caveats apply where ECHA authorization list expansions, pharmacopeial monograph revisions, or cold-chain logistics disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization velocity and instrumentation miniaturization adoption curves. A small set of triggers—REACH precursor restrictions, ISO 17034 certification backlogs, and group purchasing organization consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Amines Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Roofing Chemical Market
Chemicals
Sodium Methoxide Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
Cummene Derivatives Market
Chemicals
Hydrogen Fluoride Pyridine Market
Chemicals
Hydroxyzine Imine Market
Chemicals
Inorganic Chemicals Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Hydrophobing Agents Market
Chemicals
Ferric Fluoride Market
Chemicals
Amyl Nitrite Market
Chemicals
Sodium Hydride Market
Chemicals
Calcium Hydride Market
Chemicals
Allyl Chloride Market