
 Glycerol Market | 2026-2036
Glycerol Market Size, Share, and Industry Trends Forecast 2026-2036
Glycerol Market Analysis
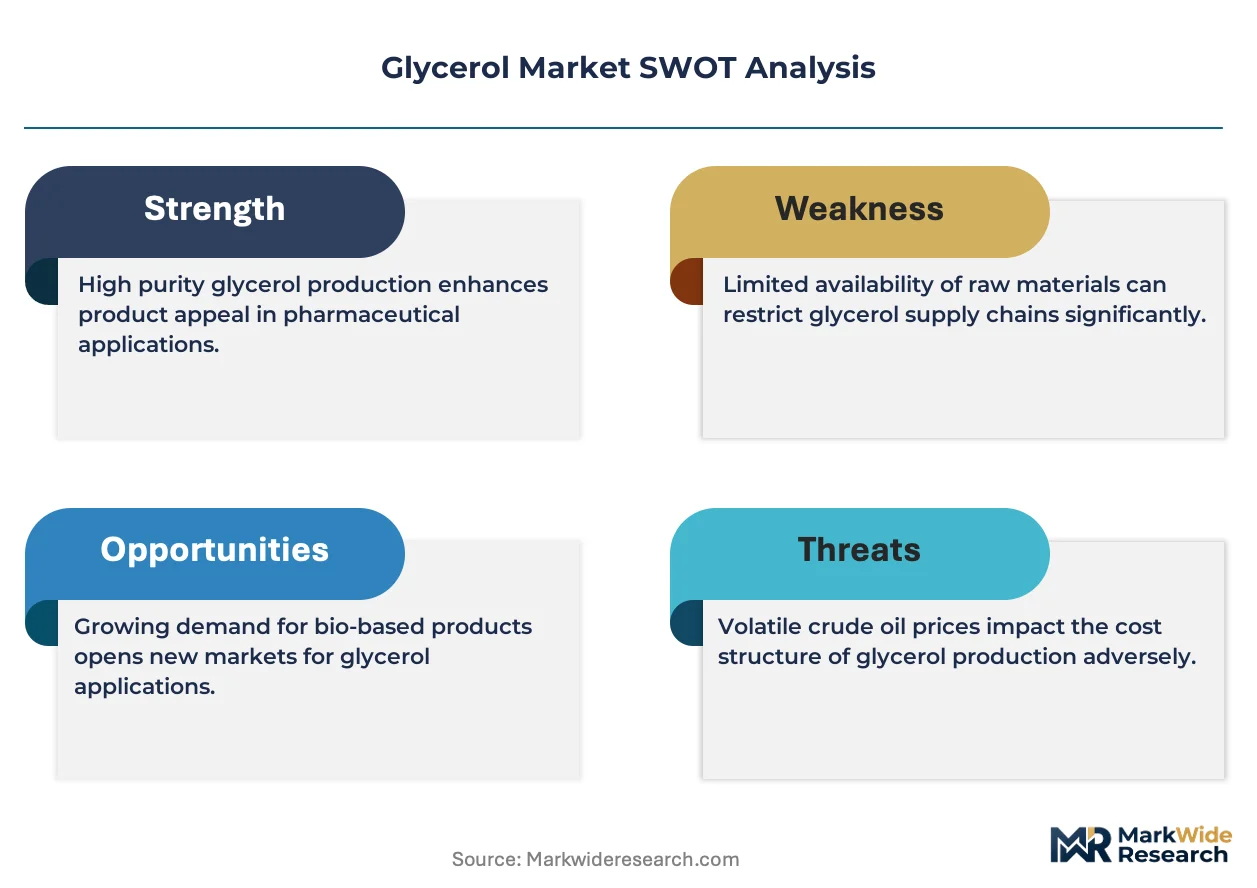
Bulk chemical distribution networks across Asia-Pacific is reconfiguring as glycerol supply pools shift toward integrated oleochemical hubs. Wilmar International Limited leverages its palm oil upstream operations to sustain captive glycerol output in Southeast Asia. Cargill, Incorporated anchors North American supply through biodiesel co-product streams. BASF SE differentiates via high-purity refining capabilities serving pharmaceutical and personal care clients.
Glycerol is a trihydric alcohol (propane-1,2,3-triol) with a molecular weight of 92.09 g/mol, typically produced via saponification, hydrolysis of fats and oils, or as a by-product of biodiesel transesterification using methanol and base catalysts. It functions primarily as a humectant, solvent, and precursor in alkyd resins, polyurethanes, and pharmaceutical formulations. Pharmaceutical grade glycerol commands the strongest margin pool due to USP and EP compliance requirements, while technical grade competes on volume in industrial applications such as alkyd resins and antifreeze. Food grade glycerol maintains steady demand from confectionery and beverage manufacturers seeking moisture retention and texture control.
The US FDA enforces glycerin purity standards under the Food Chemicals Codex for food and pharmaceutical applications, while the European Pharmacopoeia and REACH govern cosmetic and technical grades across EU member states. Indonesia's BIS-equivalent national standards and Malaysia's sustainable palm oil certification frameworks shape export eligibility for regional producers. Stakeholders must monitor biodiesel policy volatility and refining technology advances that alter crude glycerol availability.
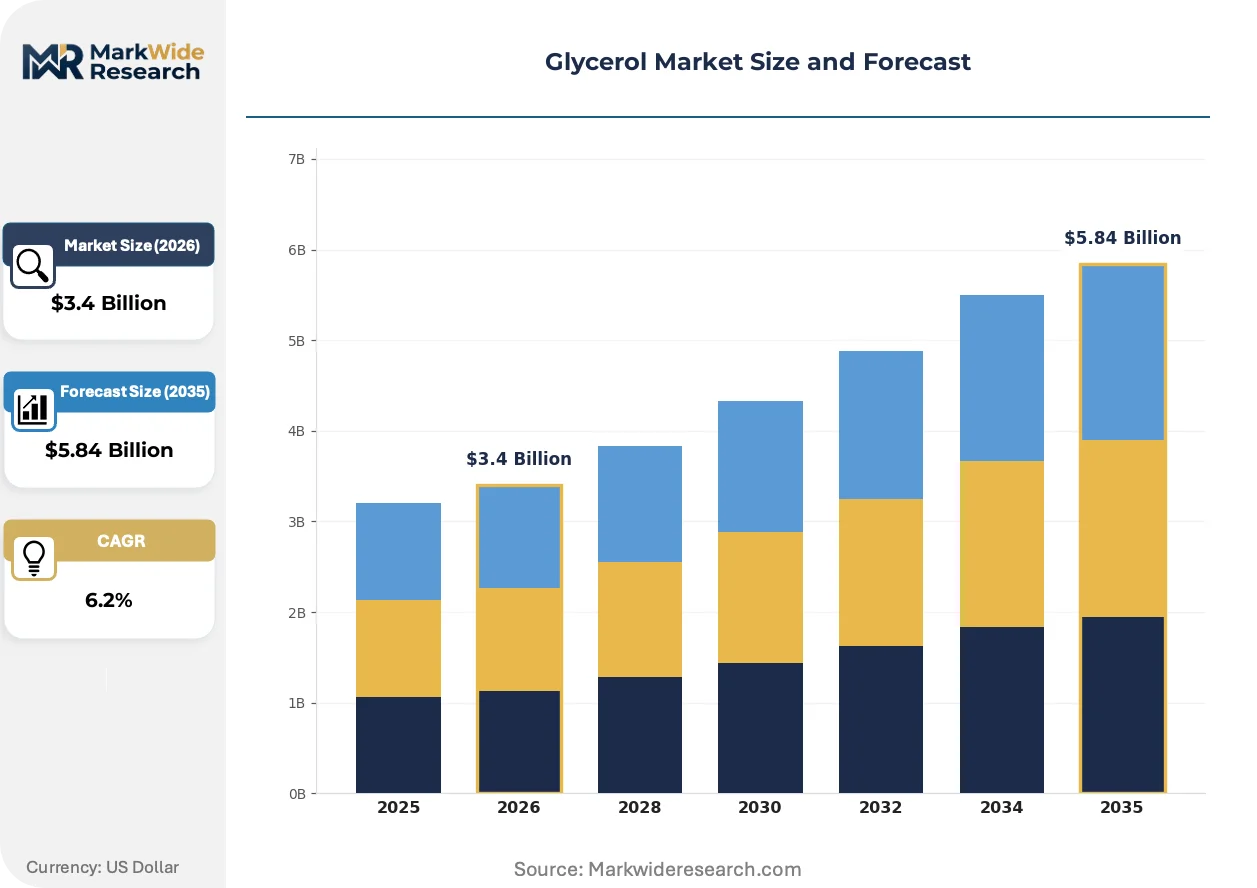
Market Dynamics
Integrated oleochemical complexes in Southeast Asia are consolidating glycerol supply pools, compressing margins for standalone refiners while pharmaceutical-grade certification requirements tighten procurement standards across personal care and food formulations.
Growth Catalysts
- Clean-label mandates:The European Union's tightening cosmetic ingredient transparency rules are forcing formulators to source USP-grade glycerol with full chain-of-custody documentation.
- Biodiesel policy:Indonesia's B35 biodiesel mandate is expanding crude glycerol feedstock availability for integrated refiners with captive methanol supply.
- Alkyd resin demand:Waterborne coating formulations in automotive OEM plants are substituting petroleum-based polyols with technical-grade glycerol derivatives.
Market Restraints
- Palm oil price volatility:Crude palm oil futures swings directly compress glycerol coproduct economics for non-integrated producers lacking upstream plantation assets.
- Refining technology barriers:Membrane filtration and ion-exchange purification systems require seven-figure capital commitments that exclude mid-scale entrants from pharmaceutical-grade certification.
- Substitution pressure:Sorbitol and propylene glycol are capturing humectant share in mass-market personal care where price sensitivity exceeds performance differentiation.
Strategic Opportunities
- Pharmaceutical-grade white space:India's CDSCO is tightening excipient purity standards, creating import substitution potential for domestic refiners achieving EP compliance.
- Epichlorohydrin route displacement:Bio-based glycerol-to-epichlorohydrin process chemistry is converging with chlorine-free catalytic systems to unlock epoxy resin feedstock markets.
- Direct-to-formulator channels:Specialty chemical distributors are building refrigerated last-mile networks that bypass traditional bulk terminal aggregation for temperature-sensitive pharmaceutical grades.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP compliance documentation requires 18-24 month validation cycles that lock working capital in qualification batches.
- Crude glycerol quality variance:Biodiesel source inconsistency—methanol residue, salt content, and color bodies—forces continuous process adjustment that degrades refinery utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycerol Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Technical Grade, Cosmetic Grade End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Plastics Form: Liquid, Solid, Powder, Emulsion Application: Preservative, Sweetener, Humectant, Solvent |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Wilmar International Limited, BASF SE, KLK Oleo, IOI Group Berhad, P&G Chemicals, Emery Oleochemicals, Oleon NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycerol Market Emerging Trajectories
Process intensification and sustainability certification are restructuring competitive advantage, separating integrated biorefinery operators from commodity traders dependent on spot crude glycerol arbitrage.
Continuous reactive distillation systems are replacing batch saponification in high-purity glycerol production, cutting energy intensity by half while enabling real-time quality adjustment. Pharmaceutical formulators in Germany and Switzerland are specifying these process-derived grades for parenteral applications. Traditional caustic refining with multiple crystallization stages is rendering obsolete for new capacity investments.
REACH Annex XVII restrictions on residual methanol in cosmetic-grade glycerol are forcing biodiesel-linked refiners to install secondary flash separation or face exclusion from EU personal care supply chains. The regulation's 0.2% methanol ceiling is compressing technical-grade output volumes as producers prioritize pharmaceutical compliance. Southeast Asian exporters are responding by diverting non-compliant streams to industrial alkyd resin buyers in China.
Personal care procurement teams are consolidating supplier panels from twelve-plus vendors to three approved partners with integrated sustainability certification. This concentration is eliminating spot-market traders and rewarding refiners with RSPO- or ISCC-compliant palm oil supply chains. The shift is most pronounced in Nordic markets where retailer ESG scorecards govern shelf placement decisions.
Glycerol Market Segmentation
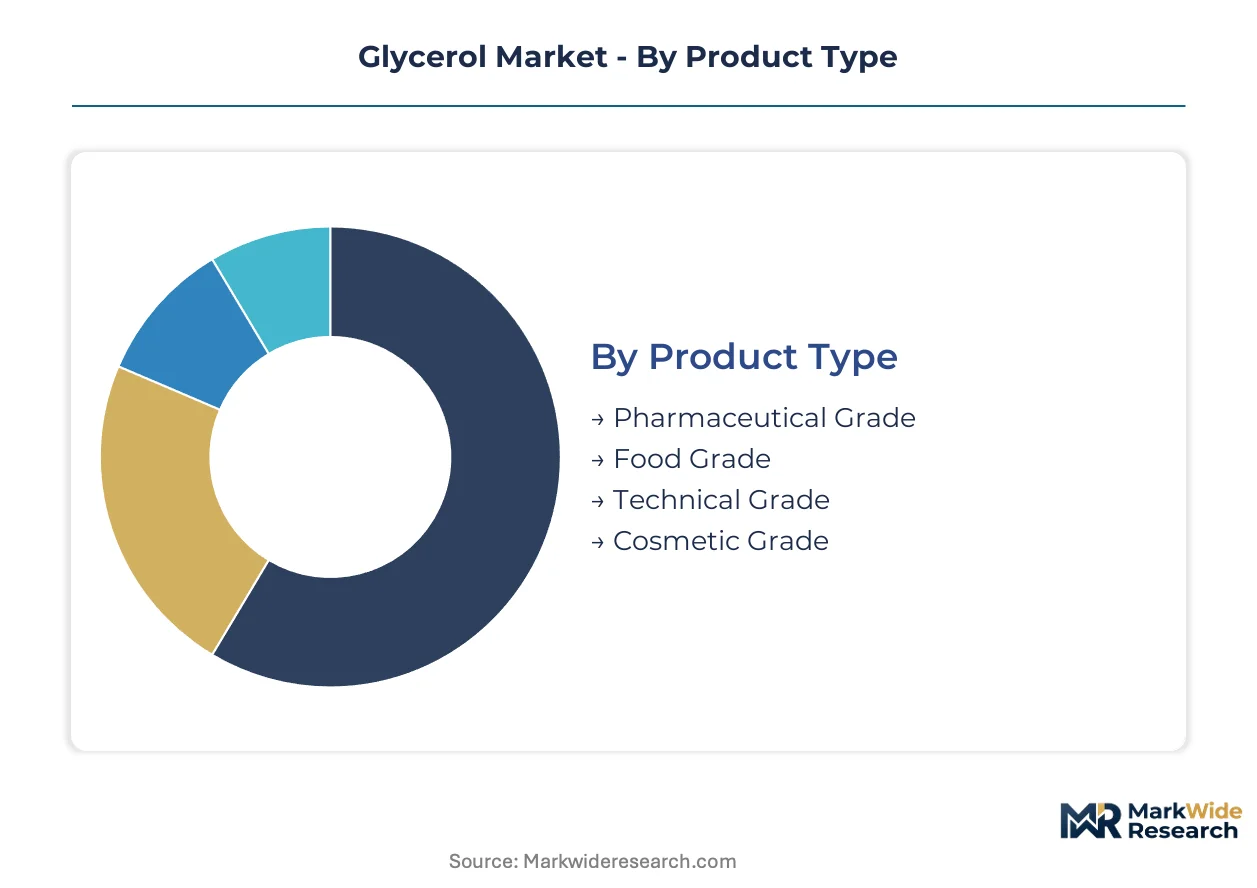
Glycerol segmentation reflects divergent purity standards and regulatory pathways that separate pharmaceutical certification from commodity volume plays. Manufacturers configure production assets around grade-specific margin pools rather than interchangeable output.
Product Type:
Mature refining technologies anchor the high-purity end while emerging process routes reshape technical-grade economics.
- Pharmaceutical Grade:USP and EP compliance mandates residual methanol below 0.1% and specific gravity controls within narrow bands. Demand concentrates in parenteral formulation facilities in Germany and Switzerland where batch documentation supports regulatory submissions. CDSCO's tightening excipient standards in India are redirecting procurement toward certified importers.
- Technical Grade:Alkyd resin manufacturers and antifreeze blenders absorb volume in price-sensitive applications. Specifications tolerate higher color bodies and moisture content. Chinese coating plants are substituting petroleum-derived polyols with technical-grade glycerol derivatives in waterborne automotive formulations.
- Food Grade:FCC standards govern moisture retention in confectionery and beverage applications. Clean-label trends are forcing confectioners to document vegetable-origin chain-of-custody.
- Cosmetic Grade:REACH Annex XVII methanol ceilings at 0.2% are compressing compliant supply availability. Nordic retailers are requiring RSPO certification for shelf placement eligibility.
Pharmaceutical Grade handles the majority of throughput; Technical Grade is expanding most quickly on share as coating substitution accelerates.
End Use Industry:
Cost tier differentiation separates premium formulation buyers from commodity absorption markets.
- Pharmaceuticals:Parenteral and excipient applications command the strictest pharmacopeial compliance. Validation batches lock working capital for 18-24 month qualification cycles. Swiss and German formulators are specifying continuous reactive distillation-derived grades for reduced endotoxin risk.
- Personal Care:Procurement consolidation from twelve-plus vendors to three approved partners is eliminating spot-market traders. RSPO and ISCC certification requirements are concentrating supply among integrated oleochemical operators with captive plantation assets.
- Food & Beverage:Moisture retention and texture control drive steady demand from confectionery manufacturers. Indonesia's integrated complexes are diverting food-grade streams toward domestic beverage producers.
- Plastics:Polyurethane polyol and alkyd resin feedstock applications compete on polyol substitution economics. Technical-grade glycerol derivatives are capturing share from petroleum-based alternatives in automotive OEM waterborne coating lines.
Personal Care captures the steepest margin premium; Plastics is climbing the fastest as polyol displacement gathers momentum.
Form:
Application requirements dictate physical state selection across temperature-sensitive and handling-convenience dimensions.
- Liquid:Dominates pharmaceutical and personal care formulations requiring precise dosing and homogeneous blending. Refrigerated last-mile networks are expanding for temperature-controlled pharmaceutical distribution.
- Solid:Compressed tablets and direct compression applications in nutritional supplements favor handling stability and extended shelf life.
- Powder:Instant beverage and dry mix applications prioritize flowability and anti-caking performance.
- Emulsion:Specialized cosmetic delivery systems and controlled-release pharmaceutical formulations exploit surface-active properties.
Liquid form manages the bulk of volume movement; Emulsion formats are gaining share fastest in targeted delivery applications.
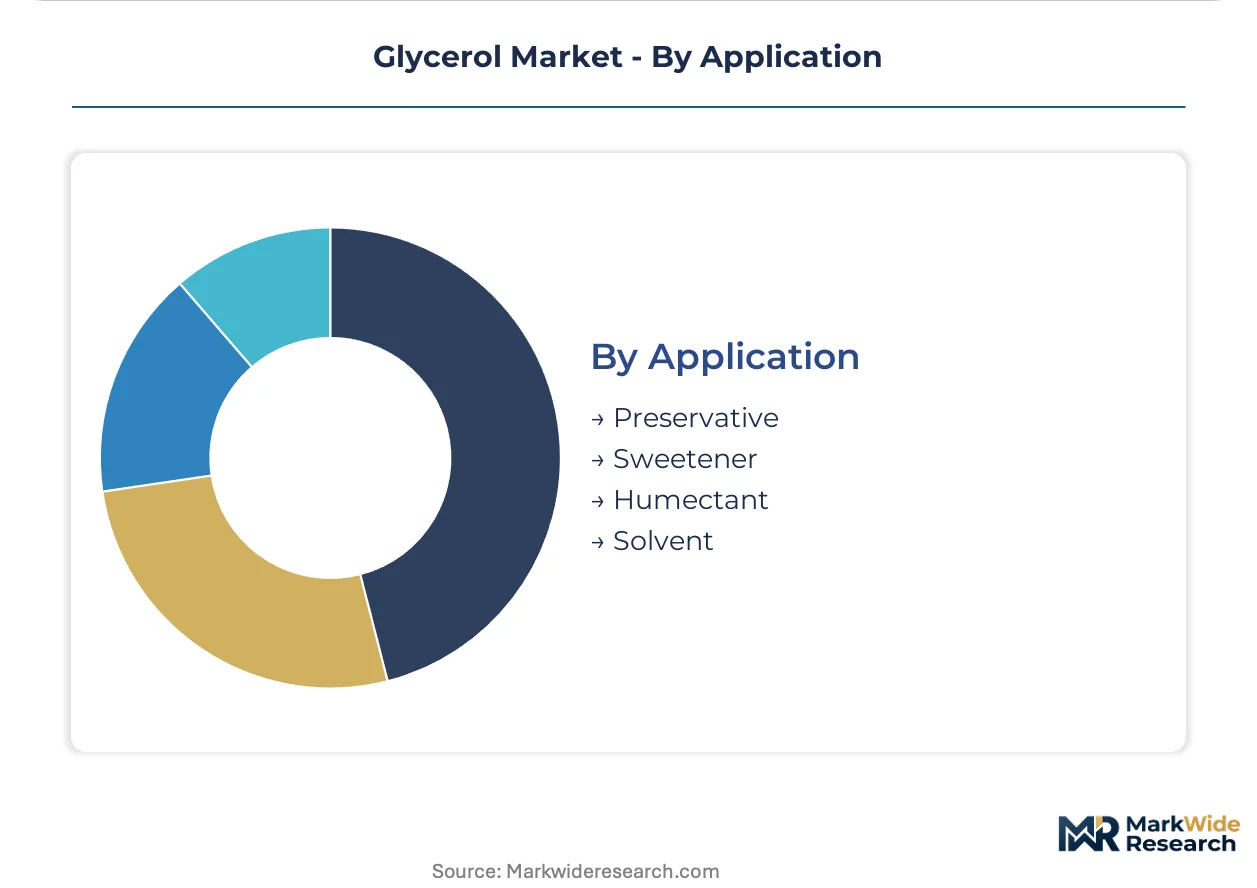
Application:
Functional role determines grade specification and regulatory pathway intensity.
- Humectant:Personal care and food applications exploit glycerol's hygroscopic properties for moisture retention. Sorbitol and propylene glycol are capturing share in mass-market personal care where price sensitivity exceeds performance differentiation.
- Solvent:Pharmaceutical extraction and botanical processing require low-aldehyde specifications. Continuous reactive distillation is displacing traditional caustic refining for solvent-grade output.
- Preservative:Osmotic pressure modification extends shelf life in intermediate-moisture foods. Clean-label mandates are restricting synthetic preservative alternatives.
- Sweetener:Caloric contribution and mouthfeel modification in sugar-free confectionery and beverages. Glycemic indexing requirements are shaping formulation decisions.
Humectant functions absorb the largest volume commitment; Solvent applications are expanding most rapidly as extraction processes convert from petroleum-derived alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA glycerin purity standards under the Food Chemicals Codex govern pharmaceutical and food applications in the United States, while REACH and the European Pharmacopoeia shape cosmetic and technical grade requirements across EU member states. Regional production clusters concentrate around integrated oleochemical complexes and biodiesel co-product streams.
United States
Biodiesel co-product glycerol from Midwest ethanol plants supplies technical-grade refiners serving alkyd resin manufacturers. EPA renewable fuel standards sustain feedstock availability through RFS2 mandate compliance. Houston-Galveston petrochemical corridors host pharmaceutical-grade purification capacity serving parenteral formulation facilities.
Germany
Continuous reactive distillation-derived glycerol from Rhineland refiners meets Swiss and German parenteral formulation specifications for reduced endotoxin risk. EMA excipient guidelines and REACH Annex XVII methanol ceilings enforce 0.2% residual limits on cosmetic-grade output. BASF SE operates high-purity refining assets in Ludwigshafen serving pharmaceutical and personal care clients.
China
Technical-grade glycerol derivatives displace petroleum-based polyols in waterborne automotive coating lines across Yangtze River Delta manufacturing zones. GB standards and SAMR food additive regulations govern food-grade imports from Southeast Asian integrated complexes. Shandong and Jiangsu provinces concentrate alkyd resin and polyurethane polyol feedstock demand.
Indonesia
B35 biodiesel mandate expansion generates crude glycerol feedstock for integrated refiners with captive methanol supply in Sumatra and Kalimantan plantation belts. BIS-equivalent national standards shape export eligibility for regional producers. Wilmar International Limited leverages palm oil upstream operations to sustain captive glycerol output across integrated oleochemical hubs.
India
CDSCO tightening of excipient purity standards redirects pharmaceutical procurement toward certified importers achieving EP compliance. FSSAI food additive regulations govern confectionery and beverage applications. Gujarat and Maharashtra industrial corridors concentrate technical-grade demand from alkyd resin and plastics manufacturers.
Glycerol Market Vendor Landscape
Integrated plantation-refinery operators and standalone specialty chemical refiners split the market between captive feedstock security and flexible multi-source procurement. Concentration is moderate, with top-tier players commanding pharmaceutical-grade certification while mid-scale refiners compete on technical-grade volume. Three strategic archetypes dominate: upstream-integrated palm oil conglomerates, biodiesel-linked biorefinery operators, and high-purity specialty chemical refiners. Capacity expansion in Southeast Asian oleochemical hubs and backward integration into plantation assets constitute the dominant competitive moves.
Among plantation-integrated conglomerates, Wilmar International Limited exemplifies upstream-controlled supply architecture, while Cargill, Incorporated anchors North American positioning through biodiesel co-product stream aggregation. BASF SE occupies the high-purity refining tier, representing pharmaceutical-grade certification capabilities serving regulated formulation markets.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Wilmar International Limited |
| BASF SE |
| KLK Oleo |
| IOI Group Berhad |
| P&G Chemicals |
| Emery Oleochemicals |
| Oleon NV |
| Others |
Supply Flow & Price Mechanics
Palm oil price volatility compresses glycerol coproduct economics for non-integrated producers, widening the spread between pharmaceutical-grade premiums and technical-grade spot prices while forcing supply chain reconfiguration toward captive plantation assets in Southeast Asia.
Pricing Analysis
The customization-premium spread between USP-grade pharmaceutical glycerol and technical-grade alkyd resin feedstock spans multiple certification tiers. Pricing stratifies across pharmaceutical, cosmetic, food, and technical grades based on USP/EP compliance investment and residual methanol thresholds. Cost compression in technical-grade volumes is intensifying because biodiesel-linked crude glycerol quality variance forces continuous process adjustment. Mass-market personal care buyers exhibit the highest price sensitivity, while parenteral pharmaceutical formulators in Germany and Switzerland absorb premium pricing for endotoxin-controlled continuous reactive distillation grades.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms are emerging as competitive weapons among integrated oleochemical conglomerates serving European personal care procurement panels. Supply concentrates in Indonesia, Malaysia, and Germany, with crude glycerol feedstock drawing from B35 biodiesel mandates and palm oil upstream operations. Raw material dependencies rest on crude palm oil futures, methanol supply for transesterification, and base catalysts for saponification routes. Single-source vulnerability from plantation concentration in Sumatra and Kalimantan belts threatens feedstock security. Distribution runs through refrigerated last-mile networks for pharmaceutical grades and bulk terminal aggregation for technical-grade industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sorbitol and propylene glycol substitution pressure in mass-market personal care humectant applications demands that glycerol incumbents fortify defensible positioning around certification moats and integrated supply security.
For Market Incumbents: Build pharmacopeial certification moats through USP and EP compliance documentation that locks out mid-scale entrants lacking eighteen-to-twenty-four-month validation cycle capacity. Deepen backward integration into palm oil plantation assets across Indonesian and Malaysian hubs to neutralize crude glycerol quality variance and secure captive methanol supply. Channel control through direct-to-formulator refrigerated distribution networks bypasses spot-market trader disintermediation. For New Entrants and Emerging Players: India's pharmaceutical-grade white space offers the most penetrable entry vector as CDSCO excipient purity standards tighten and redirect procurement toward domestic EP-compliant refiners. Target technical-grade alkyd resin displacement in Chinese waterborne automotive coating lines where petroleum-based polyol substitution economics favor glycerol derivatives. A go-to-market angle anchored in RSPO-certified sustainability documentation unlocks Nordic retailer procurement panels governed by ESG scorecards. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated plantation-refinery operators with captive feedstock security and multi-grade certification capabilities. Long-term viability hinges on biodiesel policy durability and refining technology barriers that sustain margin pool separation between pharmaceutical and technical grades. Watch REACH Annex XVII methanol ceiling enforcement and Indonesia's biodiesel mandate expansion as inflection indicators for crude glycerol feedstock availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive crude glycerol supply from Indonesian palm oil operations neutralizes price volatility exposure. |
| Pharmaceutical-Grade Certification Investment | USP and EP compliance documentation opens parenteral formulation markets in Germany and Switzerland. |
| Continuous Reactive Distillation Capacity | Process intensification cuts energy intensity while enabling real-time quality adjustment for high-purity output. |
| Direct-to-Formulator Distribution Buildout | Refrigerated last-mile networks bypass bulk terminal aggregation for temperature-sensitive pharmaceutical grades. |
| RSPO Sustainability Certification Program | Integrated supply chain documentation satisfies Nordic retailer ESG scorecards governing shelf placement decisions. |
Methodological Framework
Initial hypotheses were tested against primary input from oleochemical plant managers, personal care procurement leads, pharmaceutical formulation directors, and biodiesel refinery operators and refined through secondary validation across customs trade data, SEC 10-K filings, ACC and Cefic industry reports, and REACH regulatory databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers produced convergent estimates across the analysis window.
Demand-supply-balance framing anchored the analytical approach across grade tier, end-use industry, form factor, and regional production hub segmentation dimensions. CAGRs were derived from elasticity-adjusted volume projections and value pool allocation across purity certification tiers. Industry-specific forecast inputs included biodiesel mandate policy trajectories and alkyd resin polyol substitution elasticity in automotive coating applications.
Practitioners should monitor palm oil futures volatility, REACH methanol ceiling enforcement, and CDSCO excipient standard tightening for early signals of feedstock cost and certification barrier shifts. Forecasts reflect documented assumptions about biodiesel co-product availability and refining technology diffusion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Potassium Formate Market
Solvents
Chloroacetonitrile Market
Solvents
Isoparaffin Solvents Market
Solvents
Global Bio Solvents Market
Solvents
Nitromethane Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Hydrofluoroether Market
Solvents
Benzene and Its Derivatives Market
Solvents
Coating Solvents Market
Solvents
Europe Acetonitrile Market
Solvents
Global 2-Ethoxyethanol Market
Solvents
Global Droppers Market
Solvents
Global Solvents Market
Solvents
2-Phenylethanol Market
Solvents
Hydrocarbon Solvents Market
Solvents
India High Purity Solvents Market