
 Global Tetanus Toxoid Vaccine Market | 2026-2036
Global Tetanus Toxoid Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tetanus Toxoid Vaccine Market Foresight
Project finance tied to Gavi vaccine alliance commitments is reconfiguring which manufacturers can sustain large-scale tetanus toxoid supply contracts. Sanofi leverages its established cold chain infrastructure across Francophone Africa to anchor government tender participation. Serum Institute of India competes on volume economics, while Bharat Biotech differentiates through recombinant technology development for next-generation formulations.
Tetanus toxoid comprises formaldehyde-inactivated tetanus toxin adsorbed onto aluminum salt adjuvants, inducing protective antitoxin antibodies for prevention of Clostridium tetani infection. The manufacturing process requires controlled fermentation, detoxification, and potency testing against WHO international standards. Combination Diphtheria-Tetanus and Combination Tetanus-Diphtheria-Pertussis formulations dominate procurement volumes due to immunization program efficiency, while Recombinant Tetanus Toxoid represents the fastest-growing segment as manufacturers seek reduced production variability. Neonatal Immunization and Maternal Immunization therapy areas concentrate the largest margin pools through multilateral funding mechanisms.
WHO prequalification, FDA lot release requirements, and EMA GMP inspections shape manufacturing standards and market access for tetanus toxoid suppliers. India's CDSCO and China's NMPA enforce parallel national standards that determine which facilities can serve domestic versus export markets. Stakeholders must monitor evolving WHO policy shifts on booster scheduling and adjuvant formulations to align R&D pipelines with future procurement specifications.
Market Dynamics
Gavi vaccine alliance procurement criteria are consolidating contract eligibility around WHO prequalification status, forcing manufacturers to prioritize cold chain infrastructure over price competition in sub-Saharan Africa tender participation.
Growth Catalysts
- Expanded Maternal Immunization Programs:WHO policy prioritization of antenatal tetanus coverage in high-burden countries is pulling combination vaccine volumes through multilateral procurement channels.
- Aluminum Salt Adjuvant Optimization:Process improvements in adsorption technology are reducing potency variability and accelerating batch release timelines for combination formulations.
- Sub-Saharan African Government Healthcare Scaling:National immunization program budget expansion in Nigeria, Ethiopia, and the Democratic Republic of Congo is concentrating demand for pentavalent and hexavalent combination vaccines.
Market Restraints
- Formaldehyde Input Cost Volatility:Chemical feedstock price swings tied to petrochemical supply chains are compressing margins on toxoid detoxification processes.
- WHO Prequalification Timeline Friction:Extended facility inspection backlogs and lot release documentation requirements are delaying market access for new manufacturing entrants.
- Cold Chain Infrastructure Gaps:Last-mile refrigeration failures in rural distribution networks are limiting effective coverage and creating wastage liability for national procurers.
Strategic Opportunities
- Recombinant Toxoid Platform Development:Yeast-based expression systems are opening pathways to reduced production variability and simplified downstream processing for next-generation formulations.
- Single-Dose Booster Scheduling:WHO policy evolution toward extended-interval adult immunization protocols is creating white space for long-acting adjuvant formulations.
- Direct Government Contracting Models:Bypassing multilateral intermediaries to negotiate bilateral supply agreements with Ministries of Health in India, Indonesia, and Brazil is capturing margin previously allocated to procurement agents.
Industry Challenges
- Fermentation Specialist Talent Scarcity:Clostridium tetani culture expertise and GMP-compliant bioprocess engineering skills are concentrated among a narrow cohort of trained personnel.
- Potency Testing Bottlenecks:In vivo seroneutralization assays required for WHO international standard compliance are creating certification delays and capacity constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tetanus Toxoid Vaccine Market |
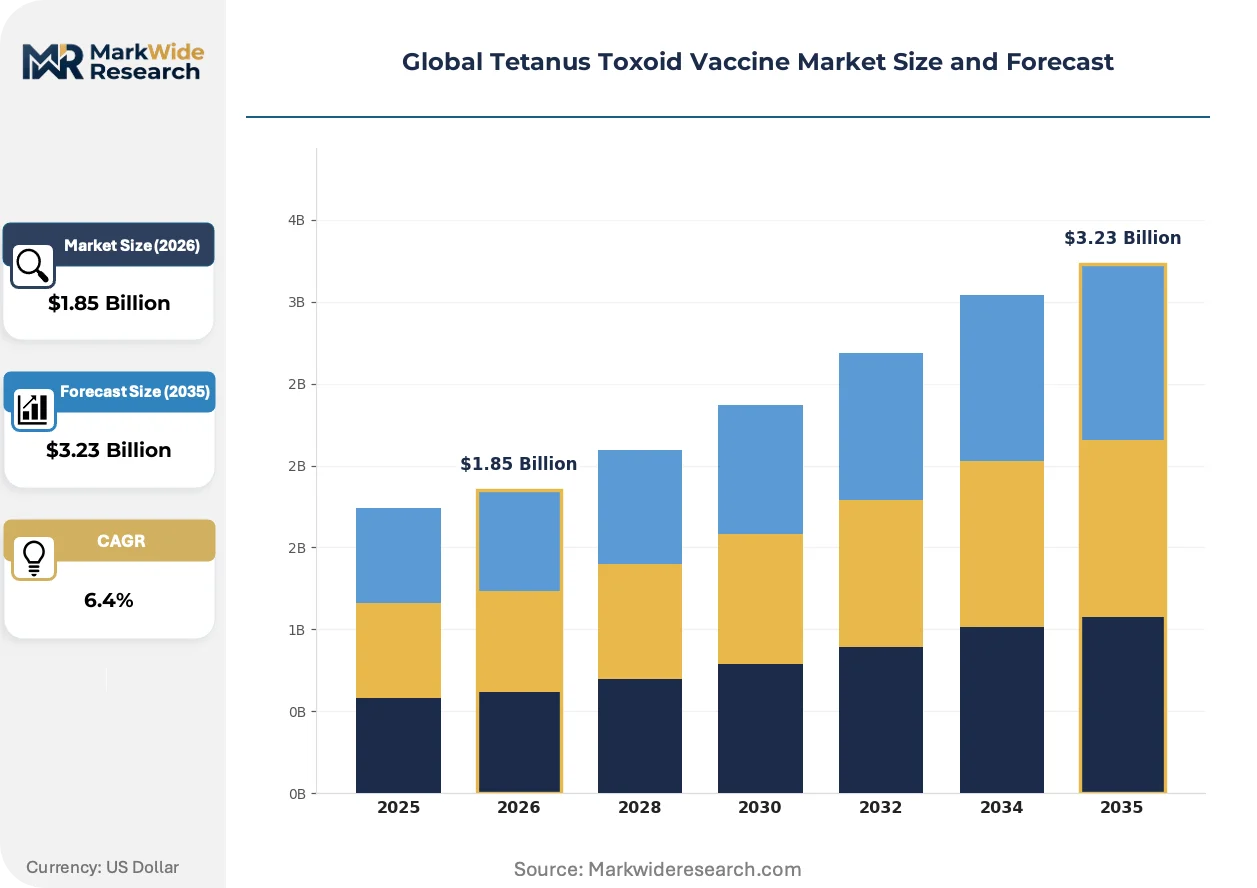
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Tetanus Toxoid Vaccine, Combination Diphtheria-Tetanus, Combination Tetanus-Diphtheria-Pertussis, Tetanus-Diphtheria-Acellular Pertussis, Recombinant Tetanus Toxoid, Conjugate Vaccines Therapy Area: Neonatal Immunization, Maternal Immunization, Wound Prophylaxis, Adult Booster Vaccination, Pediatric Vaccination, Emergency Postexposure End User: Government Healthcare Programs, Private Hospitals, Community Clinics, Non-Governmental Organizations, Occupational Health Centers, Military Health Services Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Vaccine Manufacturers, Cold Chain Logistics, Immunization Centers |
| Companies Covered | Merck, Bharat Biotech, Sanofi, Panacea Biotec, Emergent BioSolutions, GlaxoSmithKline, Serum Institute of India, Shenzhen Kangtai Biological Products, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tetanus Toxoid Vaccine Market Shifts & Advancements
Recombinant manufacturing platforms and adjuvant formulation advances are compressing traditional toxoid production economics while regulatory harmonization efforts are reshaping which facilities can serve export markets.
Yeast-derived recombinant tetanus toxoid expression systems are eliminating dependence on Clostridium tetani fermentation and hazardous toxin handling. Bharat Biotech and select European developers are advancing these platforms through preclinical and early clinical stages. This technology is rendering obsolete the capital-intensive BSL-3 containment infrastructure and specialized detoxification protocols that have defined conventional manufacturing for decades.
WHO prequalification pathway streamlining through the collaborative registration procedure is reducing duplicate facility inspections for manufacturers seeking simultaneous access to Gavi-eligible countries and domestic Indian markets. CDSCO and WHO are aligning GMP inspection schedules and documentation requirements. African national regulatory authorities are leveraging this harmonization to accelerate marketing authorization decisions for prequalified suppliers.
Ministries of Health are consolidating vaccine procurement through centralized tender mechanisms with outcome-based performance clauses tied to cold chain compliance and wastage rates. UNICEF and PAHO procurement channels are absorbing volume previously fragmented across bilateral agreements. This concentration is most visible in Latin American national immunization programs, where Brazil, Mexico, and Argentina have shifted to single-supplier frameworks with multi-year volume commitments.
Global Tetanus Toxoid Vaccine Market Segmentation
Tetanus toxoid vaccine procurement flows through distinct product, therapy, and channel configurations that determine pricing power and manufacturing requirements. Each segmentation dimension carries regulatory and logistical implications that shape supplier strategy across public and private demand pools.
Product Type:
Cost tier determines capital intensity and cold chain infrastructure requirements across formulation categories.
- Combination Diphtheria-Tetanus:Dual-antigen formulation adsorbed onto aluminum hydroxide adjuvant with standardized potency units per dose. Government tenders in Nigeria and Ethiopia concentrate procurement volumes through UNICEF supply channels, constrained by formaldehyde detoxification batch variability.
- Recombinant Tetanus Toxoid:Yeast-expressed antigen bypassing Clostridium tetani fermentation and hazardous toxin handling entirely. Bharat Biotech and European developers are advancing clinical pipelines, with WHO prequalification pathways accelerating for platforms eliminating BSL-3 containment requirements.
- Standalone Tetanus Toxoid Vaccine:Monovalent formulation retained for wound prophylaxis and emergency postexposure protocols in military and occupational health settings.
- Combination Tetanus-Diphtheria-Pertussis:Triple-antigen combination dominating pediatric national immunization schedules with established potency correlates.
- Tetanus-Diphtheria-Acellular Pertussis:Purified pertussis antigen variant commanding premium positioning in private hospital procurement.
- Conjugate Vaccines:Tetanus toxoid carrier protein linked to polysaccharide antigens for expanded disease coverage in hexavalent formulations.
Combination Diphtheria-Tetanus holds installed capacity. Recombinant Tetanus Toxoid is rotating up the share rankings.
Therapy Area:
Application focus determines funding mechanism and margin structure across immunization program targets.
- Maternal Immunization:Antenatal tetanus coverage delivered through combination vaccines with two-dose primary series and booster intervals. WHO policy prioritization in high-burden sub-Saharan African countries is pulling volumes through Gavi co-financing mechanisms, with cold chain compliance determining tender eligibility.
- Neonatal Immunization:Birth-dose administration within 24 hours targeting tetanus neonatorum elimination. India's national program and state-level procurement in Uttar Pradesh and Maharashtra concentrate demand, tied to auxiliary nurse midwife distribution networks.
- Wound Prophylaxis:Post-traumatic administration in emergency departments and military field hospitals with accelerated dosing schedules.
- Adult Booster Vaccination:Decadal revaccination protocols shifting toward extended-interval scheduling per evolving WHO guidance.
- Pediatric Vaccination:Primary series integration into national immunization schedules with pentavalent and hexavalent combination preferences.
- Emergency Postexposure:Disaster response stockpiling managed by national strategic reserves and humanitarian organizations.
Maternal Immunization commands multilateral funding concentration. Neonatal Immunization maintains volume leadership through birth-cohort scale.
End User:
Customer type shapes contract structure and payment risk across public and institutional procurement channels.
- Government Healthcare Programs:Centralized tender mechanisms with multi-year volume commitments and outcome-based performance clauses. Brazil's Ministry of Health and Indonesia's national immunization program are consolidating procurement through single-supplier frameworks, absorbing volume previously fragmented across bilateral agreements.
- Private Hospitals:Direct contracting with premium-tier combination vaccines and acellular pertussis variants, bypassing cold chain logistics shared with public systems.
- Community Clinics:Last-mile administration points dependent on district-level cold chain distribution in rural India and sub-Saharan Africa.
- Non-Governmental Organizations:Humanitarian procurement through WHO emergency stockpiles and MSF supply chains.
- Occupational Health Centers:Employer-mandated wound prophylaxis programs in construction and agricultural sectors.
- Military Health Services:Strategic stockpiling with field-stable formulation requirements and combat casualty care integration.
Government Healthcare Programs anchor contract scale. Private Hospitals are expanding fastest in value terms.
Distribution Channel:
Supply concentration determines temperature control liability and wastage allocation across fulfillment pathways.
- Cold Chain Logistics:Specialized 2-8°C distribution infrastructure with continuous temperature monitoring and validated packaging systems. Last-mile refrigeration failures in rural Democratic Republic of Congo and northern Nigeria are creating wastage liability concentrated on national procurers.
- Immunization Centers:Government-operated fixed sites with direct manufacturer delivery and real-time inventory management systems.
- Hospital Pharmacies:Institutional procurement with integrated vaccine storage and clinical administration workflows.
- Retail Pharmacies:Private market access point for adult boosters and travel medicine segments.
- Online Pharmacies:Emerging channel with cold chain integrity verification challenges for home delivery models.
- Vaccine Manufacturers:Direct government contracting bypassing intermediary distribution layers in India and Brazil.
Cold Chain Logistics controls fulfillment complexity. Immunization Centers are consolidating volume share through national program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gavi vaccine alliance procurement criteria are redirecting manufacturing investment toward WHO prequalification-compliant facilities across high-burden immunization corridors. National governments in sub-Saharan Africa and South Asia are consolidating tender mechanisms around cold chain performance metrics.
India
CDSCO regulatory alignment with WHO prequalification pathways is accelerating facility certification for export-eligible manufacturers. The national immunization program in Uttar Pradesh and Maharashtra concentrates birth-dose administration through auxiliary nurse midwife networks. Pune and Hyderabad anchor clustered vaccine manufacturing with integrated cold chain distribution to Francophone African markets.
Nigeria
Federal Ministry of Health tender consolidation is absorbing pentavalent and hexavalent combination volumes through single-supplier frameworks. WHO prequalification status determines eligibility for Gavi co-financed procurement channels. Lagos and Abuja serve as cold chain consolidation points for last-mile distribution to northern states.
Brazil
ANVISA GMP inspections and Ministry of Health centralized contracting are displacing fragmented bilateral procurement with multi-year volume commitments. The national immunization program in São Paulo and Minas Gerais states drives combination vaccine demand. Butantan Institute and private manufacturers in São Paulo state anchor regional supply capacity.
Ethiopia
Federal Health Ministry budget expansion is pulling combination vaccine volumes through UNICEF supply channels with performance-linked wastage clauses. WHO prequalification requirements filter manufacturer participation in national tender processes. Addis Ababa serves as the cold chain distribution hub for regional immunization program extension.
Indonesia
Ministry of Health direct contracting models are bypassing multilateral intermediaries to capture margin previously allocated to procurement agents. National immunization program scaling in Java and Sumatra concentrates demand for combination formulations. Jakarta and Bandung anchor manufacturing and distribution infrastructure for domestic and ASEAN export supply.
Global Tetanus Toxoid Vaccine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers defined by WHO prequalification status and cold chain infrastructure ownership. The supplier base organizes around three archetypes: multinationals with established African distribution networks, Indian volume producers with integrated fermentation capacity, and recombinant technology developers seeking next-generation positioning. Consolidation pressures are intensifying through Gavi eligibility requirements that favor prequalified facilities. Competitive moves center on strategic partnerships for cold chain infrastructure and technology licensing for recombinant platform access.
Within the multinational tier, Sanofi and GlaxoSmithKline occupy positions anchored by Francophone African distribution infrastructure and established government tender relationships. Among Indian volume producers, Serum Institute of India exemplifies scale-driven positioning through integrated fermentation and formulation capacity serving domestic and export markets. Bharat Biotech represents the recombinant technology archetype, with yeast-based expression platform development targeting reduced production variability and simplified regulatory pathways.
| Leading Market Players |
|---|
| Merck |
| Bharat Biotech |
| Sanofi |
| Panacea Biotec |
| Emergent BioSolutions |
| GlaxoSmithKline |
| Serum Institute of India |
| Shenzhen Kangtai Biological Products |
| Pfizer |
| Others |
Supply & Pricing Matrix
India's concentrated fermentation capacity and CDSCO-certified manufacturing clusters anchor global tetanus toxoid supply, directing margin capture toward WHO prequalification-holding incumbents with established cold chain infrastructure across Gavi-eligible markets.
Pricing Analysis
Certification level creates the primary spread between WHO-prequalified premium tier and non-prequalified domestic suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects Gavi eligibility, cold chain compliance investment, and lot release documentation depth. Pricing pressure stems from formaldehyde feedstock volatility and extended WHO inspection timelines compressing margins for emerging entrants. Government healthcare programs exhibit highest price sensitivity through centralized tender mechanisms, while private hospital procurement tolerates premium positioning for acellular pertussis combinations.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Gavi and UNICEF procurement channels stabilize working capital for Indian and European manufacturers serving high-burden African markets. Production concentrates in India, China, and select European facilities with BSL-3 containment infrastructure. Raw material dependencies include formaldehyde for toxin detoxification, aluminum salts for adjuvant formulation, and specialized culture media for Clostridium tetani fermentation. Single-source vulnerability in BSL-3 fermentation specialist talent creates bottleneck risk. Distribution runs through validated cold chain logistics with continuous temperature monitoring from manufacturing clusters to national immunization centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tetanus toxoid market is entering a cyclical upswing driven by Gavi alliance procurement commitments expanding through sub-Saharan African government healthcare budget scaling.
For Market Incumbents: Pre-empt recombinant platform displacement by securing exclusive licensing agreements with yeast-expression technology developers before WHO prequalification pathways accelerate for BSL-3-free manufacturing. Anchor government tender participation through backward integration into regional cold chain distribution infrastructure, particularly in Francophone African corridors where Sanofi holds established positioning. Threat of fermentation specialist talent scarcity demands captive training programs and university pipeline partnerships. For New Entrants and Emerging Players: Pursue direct contracting models with Ministries of Health in Indonesia and Brazil, bypassing multilateral intermediaries to capture margin previously allocated to procurement agents. White space concentrates in recombinant tetanus toxoid development, where Bharat Biotech's early positioning leaves room for differentiated adjuvant formulations. Go-to-market angle should emphasize simplified regulatory pathways and reduced production variability claims validated through early WHO collaborative registration procedure engagement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian volume producers possessing integrated fermentation capacity but limited recombinant pipeline exposure. Long-term viability over the next decade hinges on successful platform transition from conventional toxoid to yeast-derived expression systems. Acquisition target archetype: mid-scale manufacturers with CDSCO certification and established African distribution relationships but underinvested in next-generation technology. Signal to watch is WHO policy shift toward extended-interval adult booster scheduling, which would revalue long-acting adjuvant formulation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Acceleration | Unlocks Gavi procurement eligibility and consolidates tender participation across Nigeria, Ethiopia, and Democratic Republic of Congo. |
| Recombinant Platform Development | Eliminates BSL-3 containment capital intensity and reduces batch-to-batch potency variability for Bharat Biotech and European developers. |
| Cold Chain Infrastructure Partnership | Secures last-mile distribution capacity in northern Nigeria and rural Democratic Republic of Congo through UNICEF-aligned logistics. |
| Direct Government Contracting | Bypasses multilateral intermediaries in Indonesia and Brazil to capture margin previously allocated to procurement agents. |
| Fermentation Specialist Pipeline | Addresses Clostridium tetani culture expertise scarcity through captive university partnerships and GMP-compliant bioprocess training. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with vaccine manufacturing executives, regulatory affairs leads at CDSCO and WHO, national immunization program procurement managers, and cold chain logistics specialists; and secondary validation through WHO prequalification listings, Gavi procurement disclosures, CDSCO facility inspection records, and UNICEF supply division tender archives. Bottom-up and top-down triangulation cross-validated volume estimates against national birth cohort data and immunization schedule compliance rates.
Forecast inputs considered product type segmentation across combination and recombinant formulations, therapy area concentration in maternal and neonatal immunization, end-user channel mix between government programs and private institutions, and distribution channel configuration through cold chain versus direct manufacturer delivery. CAGRs were derived from multivariate regression across these dimensions, incorporating aluminum salt adjuvant optimization timelines and WHO booster scheduling policy evolution as industry-specific modifiers throughout the projection horizon.
Sensitivities concentrate around formaldehyde input cost volatility, WHO prequalification inspection backlog duration, and cold chain infrastructure failure rates in last-mile distribution networks. Forecasts reflect documented assumptions regarding Gavi alliance funding continuity and national government immunization budget trajectories. Macroeconomic disruption to petrochemical feedstock supply, regulatory harmonization delays between CDSCO and WHO, or breakthrough recombinant platform approval would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Gabapentin Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Antidepressant Drugs Market