
 Fumigation Service Market | 2026-2036
Fumigation Service Market Size, Share, and Industry Trends Forecast 2026-2036
Fumigation Service Market Foresight
Subscription-based preventive fumigation is consolidating what gets sold, shifting revenue from one-time treatments to recurring facility-management contracts. Rentokil Initial plc leverages this model across multi-site food-manufacturing accounts in Europe and Asia-Pacific. Terminix Global Holdings, Inc. anchors its position through national account structures serving property-management portfolios. Ecolab Inc. differentiates by integrating fumigation with sanitation chemistry and digital monitoring platforms.
Fumigation service denotes the controlled application of gaseous pesticides within enclosed spaces to eliminate pests, pathogens, or contaminants, typically requiring sealed environments, atmospheric monitoring equipment, and certified applicator credentials to achieve lethal gas concentrations for specified exposure periods. Its primary commercial purpose is to protect agricultural commodities, processed food inventories, and structural assets from infestation-related damage and regulatory rejection. Structural fumigation dominates value generation due to complexity premiums on building sealing and aeration protocols, while commodity fumigation at export terminals represents the fastest-growing application segment driven by phytosanitary certification requirements. Phosphine-based treatments now lead chemical-agent selection as methyl bromide faces progressive phase-out under ozone-protection frameworks.
The EPA regulates fumigant registration and applicator certification in the United States, while the EU REACH framework and F-Gas Regulation constrain chemical-agent availability across European markets. Brazil's ANVISA and India's FSSAI enforce residue limits and treatment documentation for agricultural exports, shaping service-provider compliance investments. Stakeholders must monitor evolving chemical-restriction schedules and alternative-gas approval timelines to anticipate capital reallocation toward phosphine recirculation systems and sulfuryl fluoride infrastructure.
Market Dynamics
Phosphine recirculation technology is compressing treatment timelines while EPA methyl bromide phase-out deadlines force capital reallocation across service-provider fleets. This dual pressure is restructuring competitive economics between commodity and structural fumigation segments.
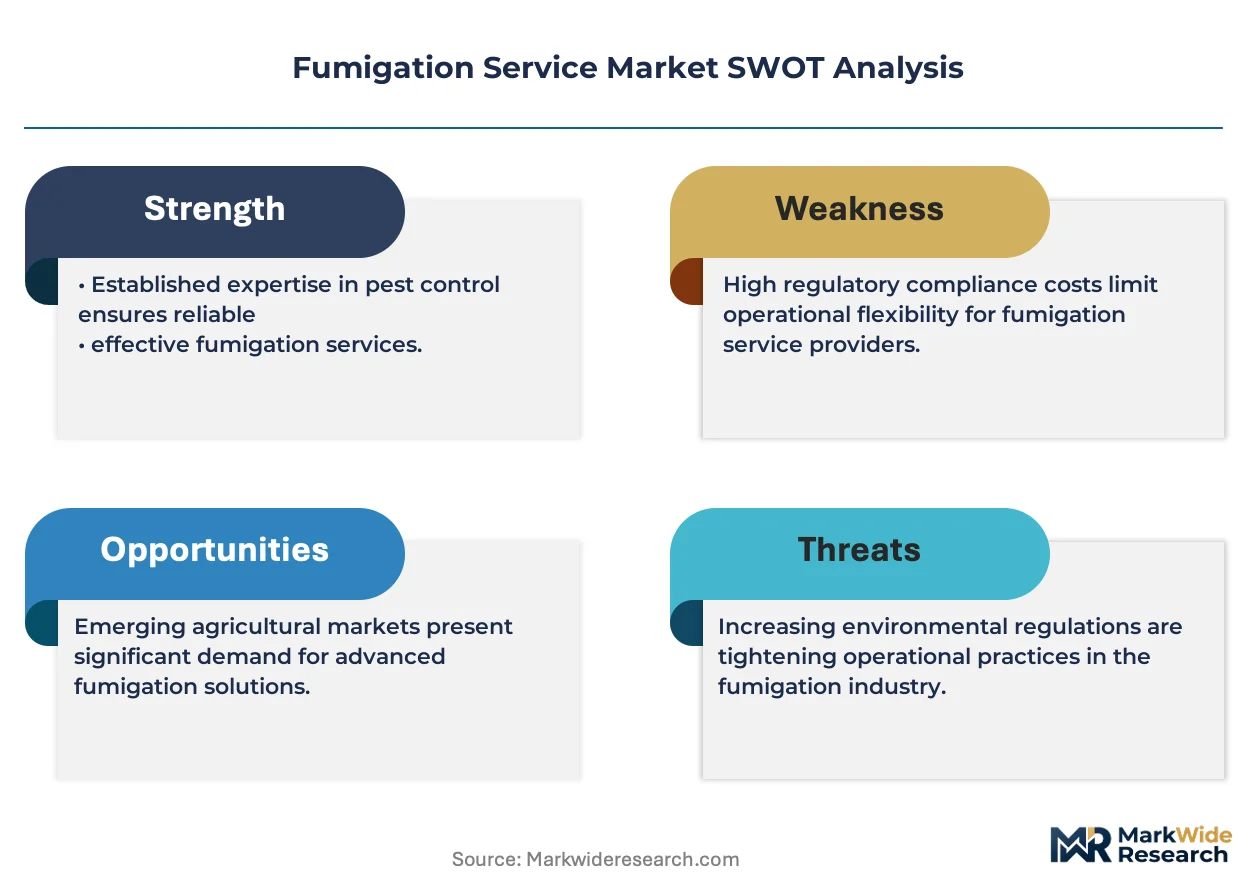
Growth Catalysts
- ANVISA export-certification mandates:Brazilian port authorities require continuous commodity fumigation for soybean and corn shipments, creating contracted demand for certified applicators.
- Phosphine-based alternatives:Service providers are retrofitting methyl bromide infrastructure to handle aluminum phosphide and magnesium phosphide formulations under Montreal Protocol schedules.
- Grain-export corridor expansion:Warehouse operators across Argentina, Ukraine, and the US Midwest are extending preventive fumigation coverage to secure phytosanitary compliance for cross-border trade.
Market Restraints
- Specialized equipment capex:Gas monitoring sensors, sealed enclosure materials, and aeration systems require substantial upfront investment before revenue generation begins.
- Applicator certification scarcity:EPA and state-level licensing requirements limit the pool of qualified technicians, constraining service expansion in high-demand regions.
- Sulfuryl fluoride supply concentration:Production of this methyl bromide alternative concentrates among limited chemical manufacturers, exposing service providers to input price volatility.
Strategic Opportunities
- India FSSAI agricultural export compliance:Basmati rice and spice processors require documented fumigation protocols for EU and Middle East market access.
- Digital monitoring convergence:Integration of IoT gas sensors with facility management platforms enables real-time atmospheric tracking and automated compliance reporting.
- Subscription facility management:Multi-site food manufacturers are consolidating pest control spend under recurring preventive contracts rather than episodic treatment procurement.
Industry Challenges
- Certified applicator pipeline gaps:Training programs for phosphine handling and sulfuryl fluoride application cannot match retirement rates among experienced methyl bromide technicians.
- Legacy aeration system incompatibility:Warehouse infrastructure designed for methyl bromide clearance cycles requires modification to meet phosphine exposure and ventilation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fumigation Service Market |
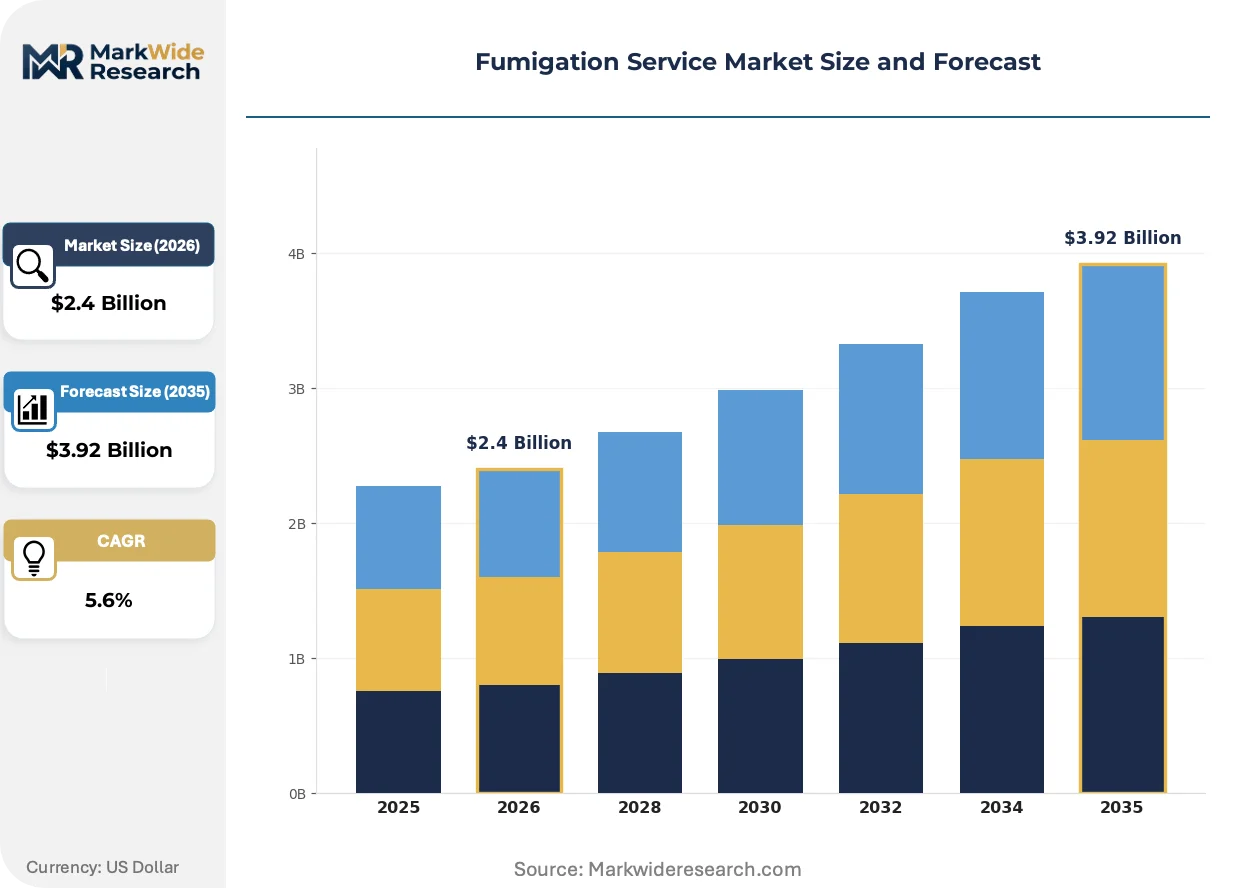
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Structural Fumigation, Commodity Fumigation, Container Fumigation, Soil Fumigation, Post-Harvest Fumigation Application: Agricultural Produce, Warehouses, Food Processing Units, Storage Facilities, Residential Buildings End User: Farmers, Food Manufacturers, Logistics Providers, Property Managers, Pest Control Agencies Chemical Agent Used: Methyl Bromide, Phosphine, Sulfuryl Fluoride, Aluminum Phosphide, Chloropicrin |
| Companies Covered | Rentokil Initial plc, Terminix Global Holdings, Inc., Ecolab Inc., Rollins, Inc., Anticimex Group, BASF SE, UPL Limited, PelGar International Ltd., Degesch America, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fumigation Service Market Shifts & Advancements
Service delivery is digitizing around atmospheric monitoring and predictive treatment scheduling. This shift compresses labor intensity while raising the technical bar for competitive participation.
Automated phosphine recirculation systems are absorbing the labor content of commodity fumigation operations. Grain elevator operators in Brazil and the US are deploying these units to reduce treatment duration from seven days to three days. The technology is absorbing margin pressure from tightening export-certification windows.
REACH and the EU F-Gas Regulation are restricting sulfuryl fluoride availability for structural applications. European service providers are redirecting investment toward heat treatment and controlled atmosphere alternatives for residential and commercial building protection. German and French regulatory authorities are accelerating alternative-gas approval timelines under pressure from building maintenance sectors.
Consolidated procurement through national account structures is displacing fragmented local contractor selection. Property management firms and multi-site food manufacturers are centralizing fumigation spend under single-source agreements with integrated service platforms. This pattern concentrates most visibly in UK and Australian commercial real estate portfolios where facility management outsourcing has matured.
Fumigation Service Market Segmentation
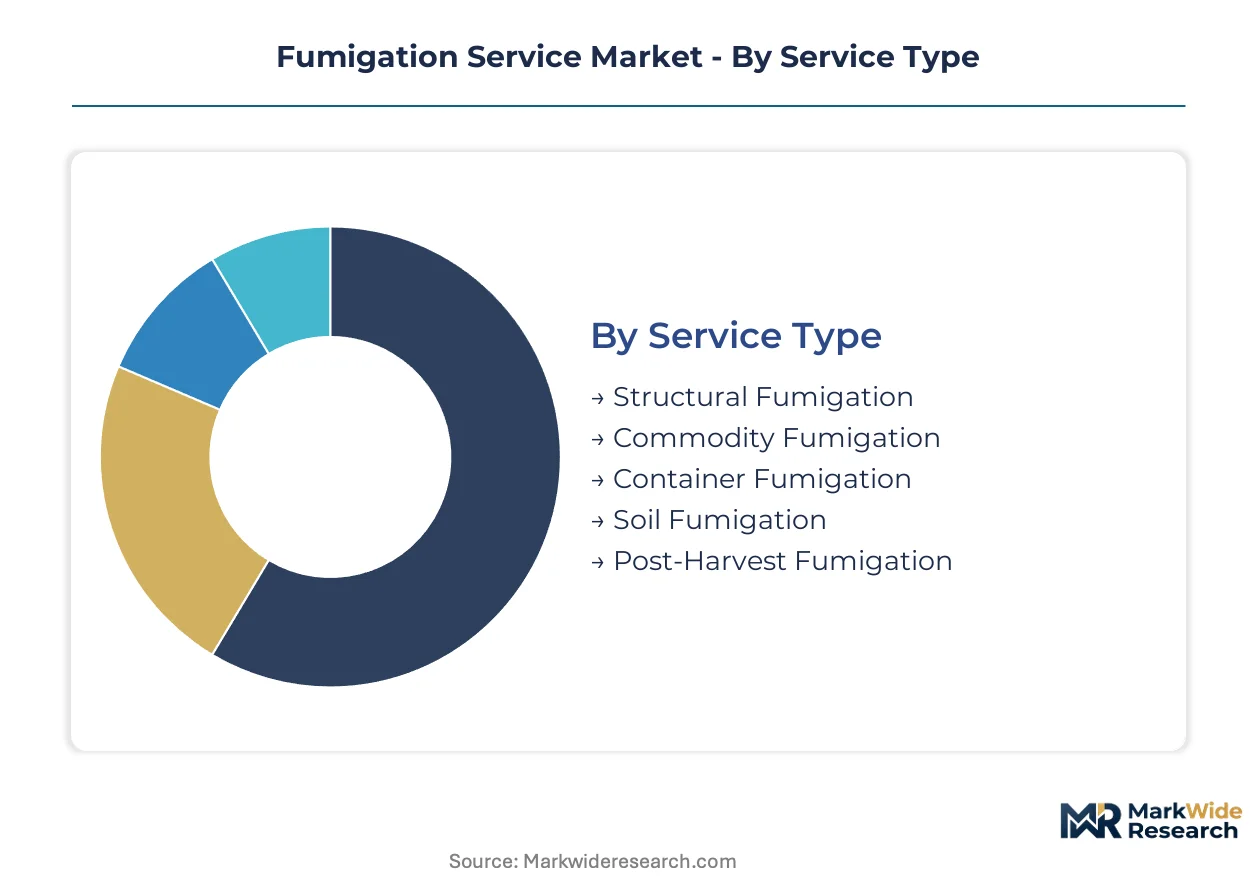
Fumigation service procurement hinges on matching treatment intensity to asset criticality and regulatory exposure. Buyers evaluate chemical compatibility, enclosure specifications, and certification documentation when selecting service tiers across commodity protection and structural preservation needs.
Service Type:
Complexity premiums and treatment duration drive buyer selection across enclosed-space applications.
- Structural Fumigation:Complete building sealing with tarpaulin or tenting systems achieves lethal gas concentration for termite, beetle, and rodent eradication in residential and commercial properties. Demand concentrates in Florida, California, and Texas where subterranean termite pressure and real estate transaction requirements mandate pre-sale treatment documentation. EPA sulfuryl fluoride labeling restrictions and aeration clearance protocols constrain service velocity.
- Commodity Fumigation:Recirculating phosphine systems treat bulk grain, oilseed, and spice inventories in elevator and warehouse configurations. Brazilian soybean exporters and US Midwest grain handlers require continuous ANVISA and phytosanitary-compliant treatment cycles to secure cross-border shipment certification. Phosphine recirculation technology compresses treatment windows from seven days to three days.
- Container Fumigation:Sealed intermodal unit treatment prevents pest transfer across international shipping lanes.
- Soil Fumigation:Pre-planting nematode and pathogen suppression for high-value crop establishment.
- Post-Harvest Fumigation:Stored product protection for harvested commodities prior to processing or export.
Volume sits with commodity fumigation at export terminals; growth tilts toward structural applications in coastal property markets.
Application:
Regulatory inspection frequency and infestation consequence severity shape facility investment priorities.
- Agricultural Produce:Field-to-export treatment protocols protect grain, oilseed, fruit, and vegetable shipments from quarantine rejection at destination ports. Indian basmati rice processors and Brazilian soybean cooperatives require documented fumigation certificates for EU and Middle East market access. FSSAI and ANVISA residue limit enforcement drives certified applicator demand.
- Warehouses:Large-volume storage facilities for grain, spices, and processed goods require continuous atmospheric monitoring and recirculation infrastructure. Operators across Argentina, Ukraine, and the US Midwest extend preventive coverage to satisfy phytosanitary compliance for cross-border trade. Capital intensity of sealed enclosure retrofitting limits competitive entry.
- Food Processing Units:Integrated pest management with fumigation as terminal intervention for contamination events.
- Storage Facilities:Dedicated commodity preservation structures with automated gas distribution systems.
- Residential Buildings:Localized termite and wood-destroying organism treatment for property preservation.
Revenue concentrates in warehouse and agricultural produce segments; regulatory stringency is expanding fastest in food processing compliance.
End User:
Contract structure preferences diverge between preventive subscription buyers and episodic treatment purchasers.
- Food Manufacturers:Multi-site processors of grain, dairy, meat, and packaged goods consolidate pest control spend under recurring facility management agreements. European and Asia-Pacific accounts favor integrated platforms combining sanitation chemistry with digital monitoring. Subscription models displace spot procurement.
- Logistics Providers:Third-party warehouse and cold chain operators require export-certification documentation for agricultural commodity handling. Brazilian port authorities and US Gulf Coast terminal operators contract certified applicators for continuous soybean and corn shipment treatment. Treatment windows align with vessel scheduling.
- Farmers:On-farm storage and pre-shipment treatment for cooperative delivery.
- Property Managers:Commercial and residential portfolio maintenance with national account structures.
- Pest Control Agencies:Subcontracted specialist services for complex enclosure treatments.
Food manufacturers generate the largest contract values; logistics providers are expanding procurement fastest on export corridor development.
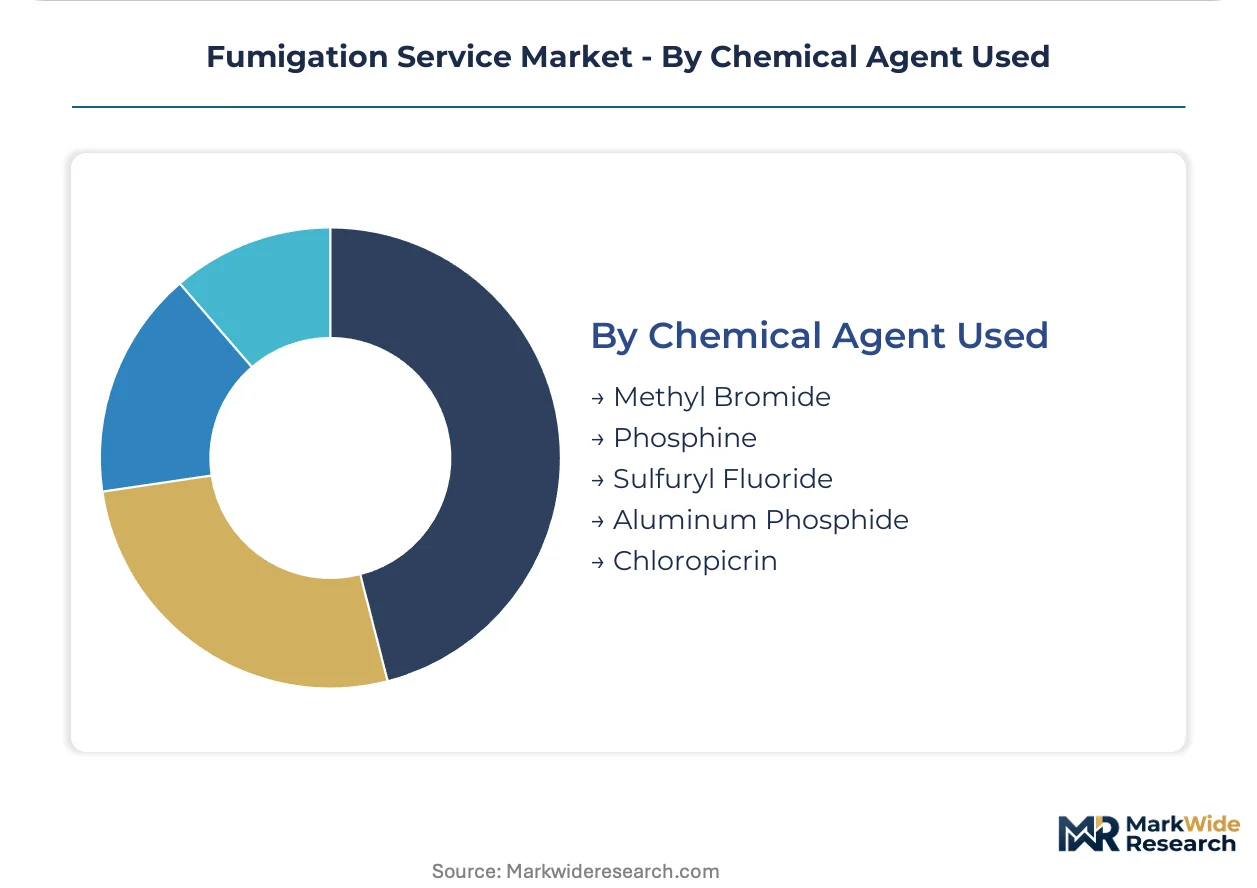
Chemical Agent Used:
Montreal Protocol phase-out schedules and residue limit enforcement are restructuring active ingredient selection.
- Phosphine:Aluminum phosphide and magnesium phosphide formulations generate toxic gas upon moisture contact for commodity treatment. Brazil, the US, and Argentina have accelerated phosphine recirculation system deployment as methyl bromide availability contracts. Applicator certification programs for phosphine handling cannot match retirement rates among legacy technicians.
- Sulfuryl Fluoride:Structural fumigation alternative to methyl bromide for termite and wood-destroying organism control. Production concentration among limited chemical manufacturers exposes service providers to input price volatility. EU F-Gas Regulation and REACH constraints are redirecting European investment toward heat treatment alternatives.
- Methyl Bromide:Legacy ozone-depleting agent with EPA-scheduled phase-out under Montreal Protocol.
- Aluminum Phosphide:Solid formulation phosphide source for controlled gas release applications.
- Chloropicrin:Pre-plant soil fumigation agent with warning agent properties.
Phosphine dominates current volume; sulfuryl fluoride faces supply concentration risk amid regulatory restriction expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in agricultural export corridors while consumption concentrates in grain-importing markets with strict phytosanitary regimes. Regulatory divergence between EPA methyl bromide phase-out schedules and EU F-Gas restrictions fragments chemical-agent availability across major trade lanes.
United States
EPA-mandated methyl bromide phase-out drives phosphine recirculation system deployment across Gulf Coast export terminals. Grain elevator operators in Louisiana and Texas retrofit legacy aeration infrastructure to meet phosphine exposure standards. Midwest warehouse clusters in Illinois and Iowa extend preventive fumigation coverage for cross-border corn and soybean shipments.
Brazil
ANVISA export-certification requirements for soybean and corn shipments sustain continuous demand for certified applicators at Paranaguá and Santos port complexes. Phosphine-based treatments displace residual methyl bromide applications in Mato Grosso grain storage facilities. São Paulo-based service providers consolidate multi-site contracts with agricultural cooperatives seeking integrated pest management platforms.
Germany
EU REACH and F-Gas Regulation constraints redirect structural fumigation investment toward heat treatment alternatives in residential and commercial building segments. BASF SE and industrial chemical distributors face tightening sulfuryl fluoride availability for wood-destroying organism control. Bavarian and North Rhine-Westphalia facility management firms centralize procurement under national account structures with integrated service platforms.
India
FSSAI residue limit enforcement and documented fumigation protocol requirements drive certified applicator demand among Basmati rice processors in Punjab and Haryana. Spice exporters in Kerala and Gujarat require treatment documentation for EU and Middle East market access. Mumbai and Chennai logistics hubs deploy automated gas monitoring systems to compress clearance timelines for containerized agricultural shipments.
Australia
Department of Agriculture biosecurity mandates sustain container fumigation intensity at Port of Melbourne and Port of Brisbane for incoming agricultural machinery and packaging materials. Grain export terminals in Western Australia retrofit phosphine recirculation systems to meet Asian import market phytosanitary standards. Sydney and Melbourne property management portfolios consolidate structural fumigation spend under subscription-based facility management contracts.
Fumigation Service Market Competitive Landscape
Top-tier vendors anchor national account structures serving multi-site food manufacturers and property management portfolios, while regional specialists retain position through certified applicator density in specific export corridors. The vendor base stratifies across integrated facility management platforms, commodity-focused treatment specialists, and chemical-agent suppliers with forward-integrated service capabilities. Three archetypes dominate: subscription-based preventive service providers, phosphine recirculation technology deployers, and sulfuryl fluoride structural treatment operators. Competitive dynamics center on M&A consolidation of regional applicator networks and capital reallocation toward digital monitoring platform integration.
Within the integrated facility management tier, Rentokil Initial plc and Ecolab Inc. occupy positions combining sanitation chemistry with atmospheric monitoring capabilities. Terminix Global Holdings, Inc. anchors the structural fumigation segment through national account penetration in coastal property markets. These three entities exemplify the shift from episodic treatment procurement toward recurring facility management contracts across European and Asia-Pacific food manufacturing accounts.
| Leading Market Players |
|---|
| Rentokil Initial plc |
| Terminix Global Holdings, Inc. |
| Ecolab Inc. |
| Rollins, Inc. |
| Anticimex Group |
| BASF SE |
| UPL Limited |
| PelGar International Ltd. |
| Degesch America, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists dominating Brazil's Mato Grosso grain corridor and India's Punjab rice belt have imposed pricing discipline through captive applicator networks and long-term cooperative contracts. Their consolidated ownership structures limit spot-market competition while locking in chemical procurement volumes that secure preferential phosphine pricing from UPL Limited and BASF SE distributors.
Pricing Analysis
Margin tightening in structural fumigation reflects EPA sulfuryl fluoride labeling restrictions and aeration clearance protocols that extend treatment duration. Three-tier pricing structure across certified-premium, standard-licensed, and economy-tier applicators separates buyers by documentation stringency and response-time guarantees. Cost compression accelerates in commodity segments as Brazilian port authorities consolidate procurement under multi-year vessel-alignment contracts. Logistics providers exhibit highest price sensitivity due to thin handling margins, while multi-site food manufacturers prioritize compliance documentation over rate negotiation.
Supply Chain Analysis
Certified applicator scarcity in Louisiana grain elevators and Paranaguá port complexes constrains service expansion despite phosphine tablet availability from Indian and Chinese chemical manufacturers. Active ingredient production draws from aluminum phosphide facilities in India, magnesium phosphide plants in China, and sulfuryl fluoride synthesis concentrated among German and US specialty chemical producers. Single-source vulnerability permeates sulfuryl fluoride supply given production concentration among limited manufacturers. Distribution runs through authorized applicator networks rather than open chemical resale, with equipment leasing bundled into service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained story where certified applicator pipeline gaps prop pricing power for incumbents with established training academies and retention programs.
For Market Incumbents: To counter phosphine recirculation technology commoditization, deepen backward integration into automated gas monitoring hardware and secure exclusive distribution agreements with Brazilian agricultural cooperatives. Prioritize certification investment in India's FSSAI-compliant applicator academies to capture Basmati rice processor consolidation.
For New Entrants and Emerging Players: Capture container fumigation white space at Australia's Port of Melbourne and Port of Brisbane where biosecurity mandates sustain treatment intensity without incumbent saturation. Target India's spice export corridor in Kerala and Gujarat with digital documentation platforms that compress EU market access timelines for small-batch processors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap applicator networks in Argentina's grain belt and Ukraine's export corridor where currency volatility and conflict disruption have weakened local operator balance sheets. Monitor phosphine recirculation system deployment rates as inflection indicator for technology substitution velocity and margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Applicator Certification Academy Buildout | EPA and ANVISA credential scarcity creates defensive moat for trained-technician networks in high-demand corridors. |
| Phosphine Recirculation System Deployment | Brazilian grain elevators compress treatment windows from seven days to three days, absorbing labor cost pressure. |
| Digital Monitoring Platform Integration | IoT gas sensors with automated compliance reporting displace manual documentation in EU and Middle East export lanes. |
| Long-term Cooperative Contracts | Multi-year vessel-alignment agreements with Paranaguá and Santos port authorities lock in volume and reduce spot-market exposure. |
| Heat Treatment Alternative Investment | EU F-Gas Regulation and REACH constraints redirect German and French structural fumigation toward non-chemical building protection. |
Research Methodology
Multi-period observation of phosphine recirculation system deployment rates, certified applicator licensing volumes, and export-certification compliance timelines anchored the trend analysis, supplemented by interviews with grain elevator operators, pest control service procurement managers, regulatory compliance officers at Brazilian port authorities, and chemical distribution specialists. Secondary validation drew from EPA registration databases, ANVISA export-certification records, EU REACH substance restriction schedules, and customs trade data for fumigant chemical flows. Bottom-up service-provider revenue aggregation triangulated against top-down agricultural export volume projections.
Segment-weighting across service type, application, end user, and chemical agent dimensions structured the analytical framework across the modeling period. CAGRs were derived from treatment volume intensity per metric ton of grain and oilseed exports, cross-referenced with regulatory phase-out schedules for methyl bromide and alternative-gas approval timelines. Industry-specific forecast inputs included vessel scheduling patterns at Brazilian port complexes and FSSAI enforcement intensity for Indian agricultural processors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Montreal Protocol acceleration schedules, phosphine tablet supply disruptions from Indian manufacturing clusters, and retirements among legacy methyl bromide technicians. Forecasts reflect assumptions regarding regulatory continuity and chemical-agent substitution velocity without anticipating unilateral policy reversals. Material deviation in EPA sulfuryl fluoride labeling restrictions or ANVISA certification mandate expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
India Insecticide Market
Crop Protection
China Fungicide Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
Europe Insecticides Market
Crop Protection
Propiconazole Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
Asia-Pacific Molluscicides Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
India Herbicide Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Metamifop Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
US Herbicide Market
Crop Protection
Nematicides Market
Crop Protection
Pest Control Market