
 Global Algaecides Market | 2026-2036
Global Algaecides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Algaecides Market Foresight
Project finance for municipal water infrastructure is tilting competitive access toward suppliers with balance-sheet capacity for multi-year service contracts. BASF SE leverages its integrated copper supply chain to control raw material costs across freshwater treatment applications. Ecolab Inc. sustains channel dominance through captive distribution to industrial cooling accounts in North America and Europe. Lonza Group AG differentiates via quaternary ammonium compound specialization for aquaculture biosecurity protocols.
Algaecides are chemical formulations designed to inhibit or eliminate algal biomass in aqueous systems, typically incorporating copper sulfate, quaternary ammonium salts, or synthetic polymeric actives at concentrations calibrated to target species while preserving non-target organisms. Their primary commercial purpose spans potable water safety, industrial heat-exchange efficiency, and aquaculture productivity protection. Copper-based formulations occupy the largest value share due to decades of proven efficacy in municipal reservoirs and power plant cooling loops, while polymeric algaecides represent the fastest-expanding category as regulators restrict heavy metal discharge. Quaternary ammonium compounds concentrate margin pools in aquaculture and decorative pond segments where bioaccumulation concerns limit copper alternatives.
The EPA FIFRA framework governs algaecide registration and label claims in the United States, while REACH in Europe mandates extensive ecotoxicological dossiers for copper-based actives entering EU waterways. China's MEE enforces dual carbon-aligned discharge standards that elevate compliance costs for phenyl urea formulations in industrial cooling applications. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation timelines and re-registration investments.
Market Dynamics
Regulatory divergence between jurisdictions is fragmenting formulation standards, forcing manufacturers to maintain parallel product lines for copper-based and polymeric actives while managing divergent re-registration timelines across EPA FIFRA, REACH, and China's MEE frameworks.
Growth Catalysts
- Aquaculture biosecurity mandates:Farm operators in Vietnam and Indonesia are expanding algaecide protocols to meet export certification requirements for shrimp and finfish destined for EU and US markets.
- REACH Annex XVII restrictions:European regulators are accelerating the shift from copper sulfate to synthetic polymeric alternatives in industrial cooling applications, opening reformulation service revenue streams.
- Inland fishery buildout:China's MEE is enforcing stricter discharge limits that elevate treatment intensity requirements across reservoir and pond systems in Hubei and Jiangsu provinces.
Market Restraints
- Copper price volatility:Fluctuations in London Metal Exchange copper pricing directly compress margins for sulfate-based formulations used in municipal water treatment.
- Supply concentration in Chinese actives:Over half of quaternary ammonium compound intermediates originate from Shandong and Jiangsu manufacturing clusters, creating geographic vulnerability.
- Technical efficacy gaps:Polymeric algaecides demonstrate inconsistent performance against cyanobacterial blooms in high-turbidity reservoirs, limiting complete copper substitution.
Strategic Opportunities
- Underpenetrated Brazilian aquaculture:Farmed tilapia and tambaqui producers in Paraná and São Paulo states lack established algaecide protocols, presenting first-mover positioning potential.
- EU Green Deal procurement alignment:Public water utilities in Germany and the Netherlands are incorporating lifecycle carbon metrics into chemical sourcing decisions, favoring low-energy manufacturing processes.
- Remote dosing system convergence:Integration of IoT sensors with automated chemical feed systems enables precision application in distributed cooling tower networks, reducing labor dependency.
Industry Challenges
- Ecotoxicological dossier compilation:REACH-compliant studies for novel polymeric actives require 18-24 month timelines and specialized aquatic toxicology expertise that consultancies struggle to staff.
- Legacy cooling tower infrastructure:Pre-2010 industrial facilities in the US Midwest and Rust Belt regions lack automated monitoring capabilities, complicating precision algaecide deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Algaecides Market |
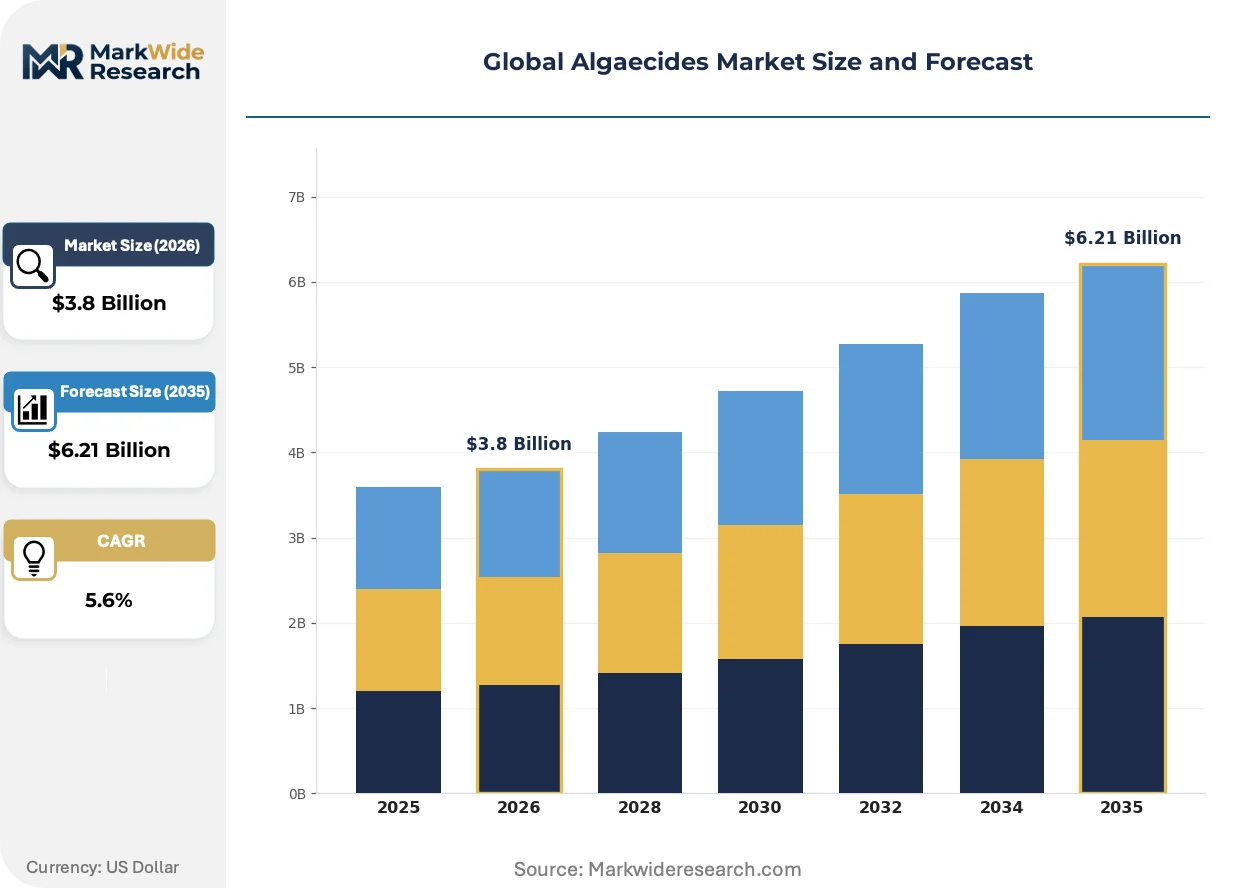
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Copper-Based, Polymeric, Quaternary Ammonium Compounds, Phenyl Urea, Others Application: Freshwater Treatment, Wastewater Management, Industrial Cooling Systems, Aquaculture, Decorative Ponds End User: Municipal Authorities, Industrial Facilities, Fishery Operators, Landscape Contractors, Golf Courses Form: Liquid, Granule, Pellet, Powder, Emulsion |
| Companies Covered | BASF SE, Ecolab Inc., FMC Corporation, UPL Limited, Nufarm Limited, Syngenta International AG, Akzo Nobel N.V., Kemira Oyj, Lonza Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Algaecides Market Shifts & Advancements
Formulation chemistry and application methodology are diverging sharply as regulators impose incompatible toxicity thresholds across major economies, compressing the viable window for universal product platforms.
Polymeric quaternary ammonium formulations are migrating from niche aquaculture applications toward mainstream municipal reservoir management. Water authorities in Florida and Texas are piloting these actives for cyanobacterial control in drinking water sources. The technology is migrating from specialty chemical suppliers into integrated water treatment service portfolios, compressing standalone algaecide vendor margins.
REACH authorization requirements for copper compounds are tightening discharge monitoring obligations across EU member states. Industrial operators in the Rhine basin now face quarterly ecotoxicity testing mandates for cooling tower effluent. Power generation facilities in Germany and Poland are accelerating polymeric substitution timelines to preempt enforcement actions.
Service bundling is displacing standalone chemical procurement in North American industrial accounts. Cooling tower operators in Texas and Ohio are contracting for guaranteed heat-exchange efficiency outcomes rather than volume-based chemical purchases. This restructuring concentrates purchasing authority with integrated water treatment providers and marginalizes specialty chemical distributors.
Global Algaecides Market Segmentation
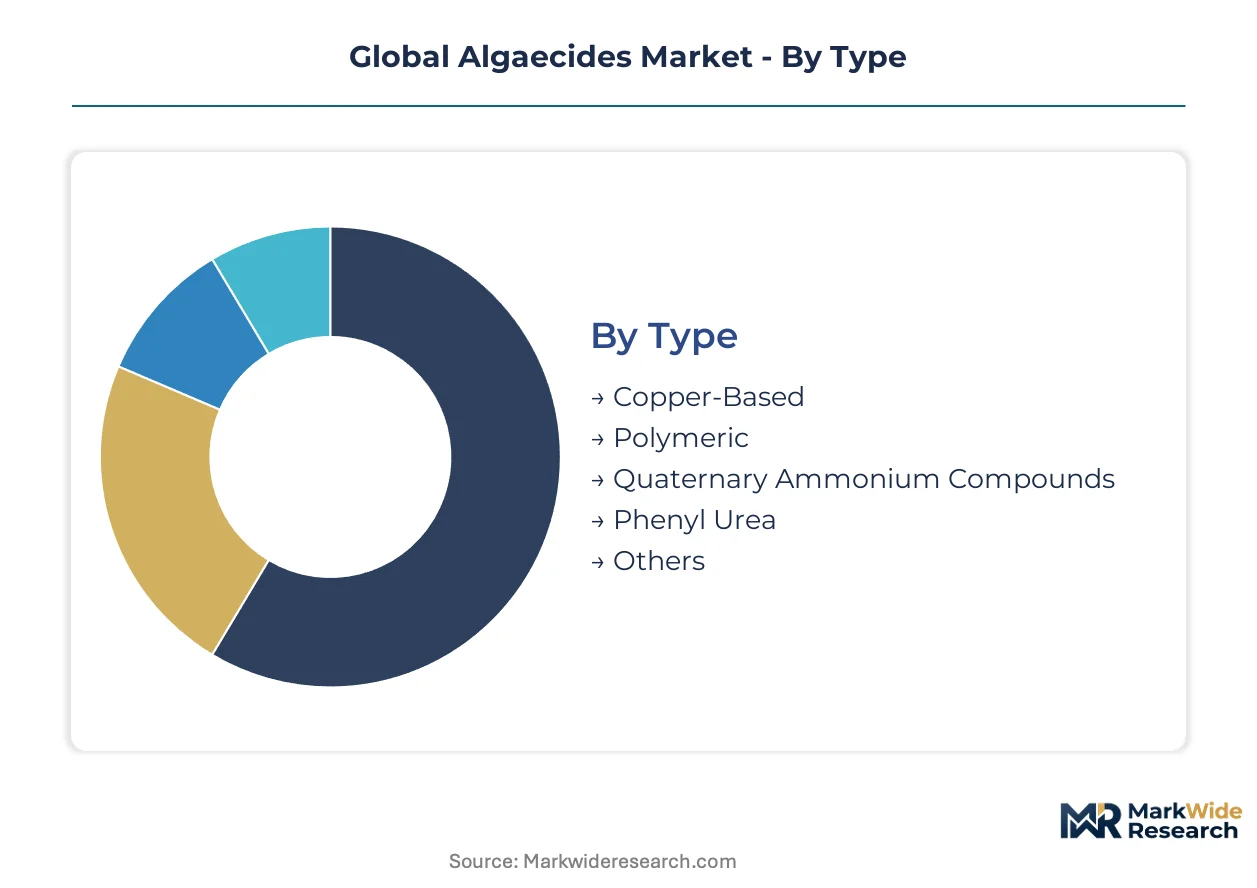
Algaecide procurement patterns diverge sharply across formulation chemistry, deployment setting, and buyer sophistication. Understanding these segment boundaries clarifies where technology investments concentrate and which customer relationships command premium pricing.
Type:
Cost tier stratification separates legacy metal-based formulations from emerging synthetic alternatives with divergent raw material exposure and regulatory compliance burdens.
- Copper-Based:Formulations incorporate copper sulfate pentahydrate or chelated copper complexes at concentrations calibrated for cyanobacterial suppression. Municipal reservoir operators in Florida and Texas specify these actives for drinking water source protection despite rising discharge scrutiny from EPA regional offices.
- Polymeric:Synthetic macromolecular actives, typically poly[oxyethylene(dimethylimino)ethylene(dimethylimino)ethylene dichloride], function via membrane disruption without heavy metal persistence. Industrial cooling operators in Germany's Rhine basin are accelerating procurement of these alternatives to preempt REACH authorization enforcement.
- Quaternary Ammonium Compounds:Cationic surfactant formulations dominate shrimp farm biosecurity protocols in Vietnam and Indonesia.
- Phenyl Urea:Photosystem II inhibitors face tightening discharge limits under China's MEE dual carbon standards.
- Others:Peroxygen-based and biological formulations serve niche ornamental pond applications in Japan.
Copper-Based holds installed capacity. Polymeric is rotating up the share rankings.
Application:
Application context dictates dosing precision requirements, from continuous feed systems in power generation to episodic treatment in seasonal aquaculture cycles.
- Freshwater Treatment:Reservoir and potable water source management requires sustained low-dose application to prevent taste-and-odor compound formation. Utilities in São Paulo state and Australia's Gold Coast region prioritize actives with minimal bromate formation potential under ozonation.
- Industrial Cooling Systems:Heat-exchange efficiency protection demands algaecide compatibility with corrosion inhibitors and scale control chemistries. Petrochemical complexes on the US Gulf Coast specify non-foaming formulations for once-through cooling designs.
- Wastewater Management:Effluent polishing applications in the Netherlands focus on phosphorus-binding algaecide adjuncts.
- Aquaculture:Biofloc and recirculating systems in India's Andhra Pradesh require species-specific toxicity windows.
- Decorative Ponds:Residential and commercial landscape applications in the UAE prioritize rapid visual clearance over residual control.
Industrial Cooling Systems anchors procurement volume. Aquaculture is climbing the fastest.
End User:
Customer type determines contract structure, from municipal RFP cycles to private industrial service agreements with outcome-based pricing.
- Municipal Authorities:Public water utilities operate under political procurement oversight with multi-year chemical supply contracts. German and Dutch authorities now embed lifecycle carbon metrics into sourcing decisions under EU Green Deal procurement guidelines.
- Industrial Facilities:Power generation, petrochemical, and data center operators prioritize guaranteed heat-exchange efficiency over chemical volume. Texas and Ohio cooling tower operators are contracting for outcome-based service bundles.
- Fishery Operators:Vietnamese shrimp farms and Indonesian finfish producers expand algaecide protocols to meet EU and US export certification requirements.
- Landscape Contractors:Commercial grounds maintenance firms in Florida purchase seasonal algaecide programs.
- Golf Courses:Turf management superintendents in Arizona and Spain specify irrigation-safe formulations for pond aesthetics.
Municipal Authorities command the longest contract tenors. Industrial Facilities are consolidating purchasing authority fastest.
Form:
Physical formulation dictates application equipment compatibility, labor requirements, and storage stability across climatic conditions.
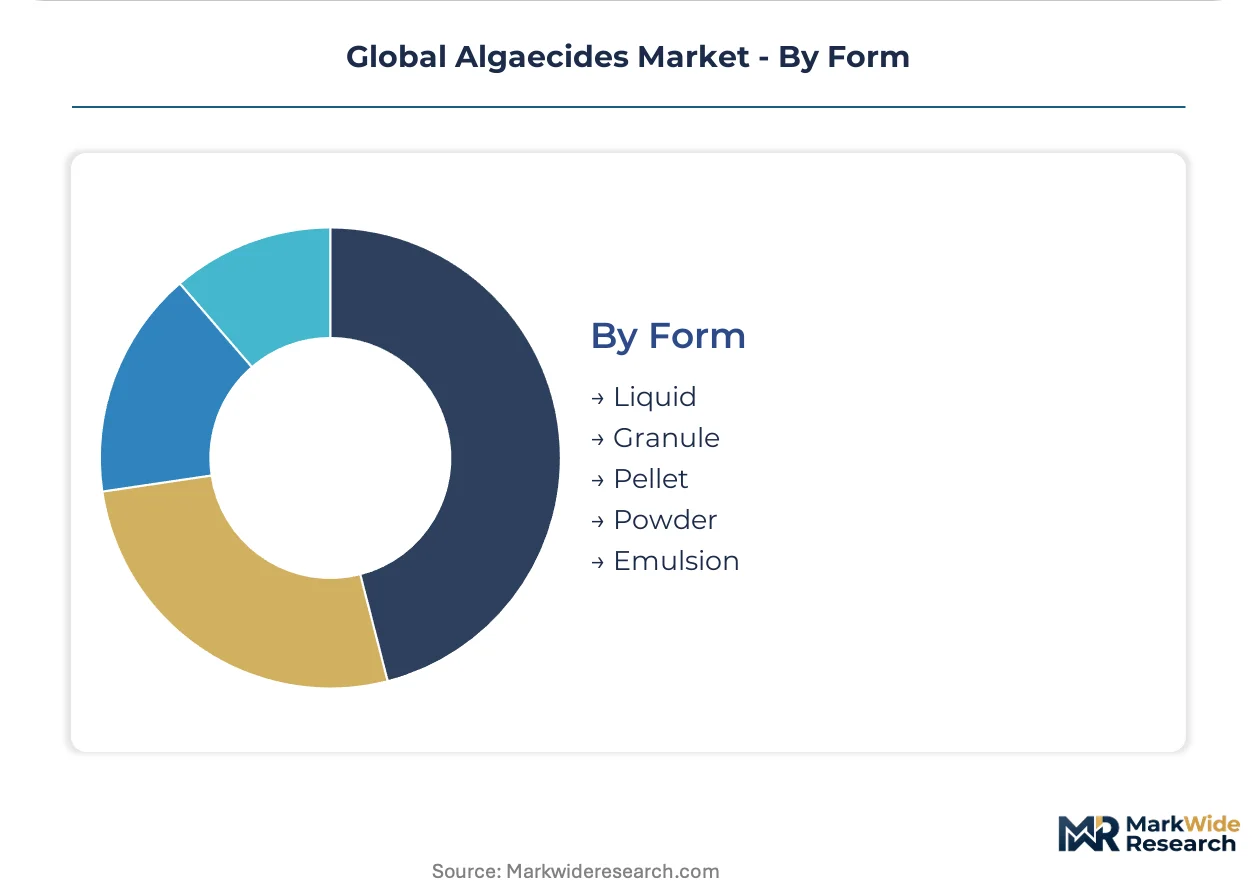
- Liquid:Ready-to-use or concentrate solutions enable precision metering through automated feed systems. Industrial cooling networks in Ohio and Texas favor liquid delivery for IoT-integrated remote dosing convergence.
- Granule:Slow-dissolving formulations provide sustained release in decorative ponds and golf course water features. Landscape contractors in the UAE specify granules for reduced application frequency in high-evaporation environments.
- Pellet:Sinking formulations target benthic algal mats in reservoir management.
- Powder:Dry concentrates serve bulk municipal procurement with on-site reconstitution.
- Emulsion:Oil-phase dispersions enhance penetration of filamentous algae in aquaculture ponds.
Liquid dominates automated system integration. Granule is gaining share in amenity applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial water treatment intensity and aquaculture biosecurity mandates concentrate procurement authority in five national markets. Each geography presents distinct regulatory timelines and customer archetypes reshaping supplier access.
United States
Data center cooling expansion and power plant efficiency mandates drive algaecide consumption. EPA regional offices in Florida and Texas enforce tightening discharge limits for copper-based formulations. Industrial operators in Ohio's Rust Belt retrofit legacy cooling towers with automated dosing systems to comply.
Germany
Rhine basin industrial clusters face quarterly ecotoxicity testing obligations under REACH Annex XVII. Power generation facilities in North Rhine-Westphalia accelerate polymeric substitution timelines. Municipal utilities in Bavaria embed lifecycle carbon metrics into chemical sourcing decisions under EU Green Deal procurement guidelines.
China
Inland fishery expansion in Hubei and Jiangsu provinces elevates treatment intensity requirements. MEE enforces dual carbon-aligned discharge standards elevating compliance costs for phenyl urea formulations. Manufacturing clusters in Shandong and Jiangsu supply over half of global quaternary ammonium compound intermediates.
Vietnam
Shrimp farm operators expand algaecide protocols to meet EU and US export certification requirements. The country's national environmental regulator tightens effluent standards for aquaculture discharge. Mekong Delta processing facilities in Cần Thơ and Sóc Trăng provinces integrate biosecurity chemical bundles.
Brazil
Farmed tilapia and tambaqui producers in Paraná and São Paulo states lack established algaecide protocols. ANVISA registration pathways for aquaculture biocides remain underdeveloped versus agricultural chemical frameworks. São Paulo state water utilities pilot copper alternatives in reservoir management.
Global Algaecides Market Competitive Landscape
Channel-controlling players compete with product-specialist players for purchasing authority in municipal and industrial accounts. The structure tilts toward integrated water treatment providers with balance-sheet capacity for multi-year service contracts. Three archetypes dominate: diversified chemical conglomerates with captive raw material positions, specialty biocide formulators with regulatory dossier expertise, and integrated service providers bundling chemicals with monitoring equipment. Competitive moves concentrate on geographic expansion into underpenetrated aquaculture markets and portfolio diversification toward polymeric actives.
Within the diversified chemical tier, BASF SE and Akzo Nobel N.V. exemplify players with upstream integration into copper and specialty surfactant supply chains. Ecolab Inc. and Kemira Oyj occupy positions as integrated service providers with captive distribution networks. Lonza Group AG represents the specialty formulator archetype with concentrated expertise in quaternary ammonium compound registration and aquaculture biosecurity protocols.
| Leading Market Players |
|---|
| BASF SE |
| Ecolab Inc. |
| FMC Corporation |
| UPL Limited |
| Nufarm Limited |
| Syngenta International AG |
| Akzo Nobel N.V. |
| Kemira Oyj |
| Lonza Group AG |
| Others |
Supply & Pricing Matrix
The Yangtze River freight corridor carries copper sulfate pentahydrate from Jiangsu manufacturing clusters to inland reservoir operators in Hubei province, with bunker fuel cost fluctuations amplifying price spreads between coastal formulators and interior municipal buyers. This logistics geometry concentrates pricing power with Shandong-based quaternary ammonium compound producers who leverage captive intermediate supply to undercut imported alternatives in Vietnamese aquaculture markets.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange copper pricing dominate municipal procurement in Florida and Texas, transferring commodity volatility risk from suppliers to public utilities. Three-tier pricing structure across premium chelated copper, standard sulfate formulations, and economy-grade phenyl urea separates certified aquaculture actives from industrial cooling commodities. Pricing pressure stems from REACH Annex XVII compliance costs accelerating polymeric substitution in Germany's Rhine basin. Industrial facilities demonstrate lowest price sensitivity due to outcome-based service bundling, while landscape contractors in the UAE exhibit acute cost consciousness for seasonal decorative pond programs.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supply-chain finance facilities offered by Shandong and Jiangsu manufacturing clusters to Vietnamese shrimp farm distributors, locking in channel loyalty against multinational competitors. Raw material flows draw from Chilean copper concentrate, Saudi petrochemical feedstock for quaternary ammonium intermediates, and German specialty surfactant precursors. Single-source vulnerability concentrates in Jiangsu province's quaternary ammonium compound capacity. Distribution runs through integrated water treatment providers with captive service contracts displacing specialty chemical distributors in North American industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EPA FIFRA, REACH, and China's MEE frameworks fragments formulation standards, creating specialized niches for regional compliance specialists and polymeric active innovators.
For Market Incumbents: Build regulatory dossier moats through accelerated REACH ecotoxicological study completion for novel polymeric actives, preempting 18-24 month approval bottlenecks that constrain competitor entry. Deepen backward integration into copper concentrate sourcing to insulate margins from London Metal Exchange volatility threatening sulfate-based formulation profitability. Channel control investments in IoT-integrated remote dosing systems defend against integrated service provider consolidation in Texas and Ohio cooling tower markets. For New Entrants and Emerging Players: Pursue underpenetrated Brazilian aquaculture where ANVISA registration pathways for biocides remain underdeveloped versus agricultural chemical frameworks, enabling first-mover positioning in Paraná and São Paulo tilapia operations. Target EU Green Deal procurement alignment in German and Dutch municipal utilities embedding lifecycle carbon metrics into chemical sourcing decisions. License polymeric formulation technology from specialty chemical research institutes to bypass capital-intensive active ingredient manufacturing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty formulators with concentrated quaternary ammonium compound expertise and aquaculture biosecurity protocol registration assets over diversified chemical conglomerates with commodity copper exposure. Long-term viability hinges on polymeric substitution trajectories in industrial cooling applications and aquaculture biosecurity mandate expansion in Southeast Asian export-oriented production. Watch for MEE enforcement acceleration in China's inland fishery provinces as inflection indicator for phenyl urea formulation obsolescence and copper alternative adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Concentrate | BASF SE's captive Chilean supply insulates sulfate formulation margins from London Metal Exchange volatility. |
| Polymeric Active R&D Partnership | Lonza Group AG's quaternary ammonium specialization accelerates REACH-compliant alternatives for Rhine basin industrial operators. |
| IoT-Integrated Remote Dosing Deployment | Ecolab Inc.'s automated feed systems reduce labor dependency in Ohio and Texas distributed cooling tower networks. |
| Aquaculture Biosecurity Certification Investment | Vietnamese shrimp farm operators expand algaecide protocols to meet EU export requirements in Cần Thơ processing facilities. |
| EU Green Deal Procurement Alignment | German and Dutch utilities embed lifecycle carbon metrics favoring low-energy polymeric manufacturing processes. |
Research Methodology
A standing panel of municipal water utility procurement directors, industrial cooling tower maintenance engineers, aquaculture farm operations managers, and specialty chemical regulatory affairs leads provided ongoing calibration across primary interview rounds and secondary validation. Bottom-up triangulation incorporated customs trade data for copper sulfate and quaternary ammonium compound flows, EPA FIFRA registration databases, REACH Annex XVII authorization filings, and SEC 10-K disclosures from diversified chemical conglomerates. Top-down cross-checks referenced MEE discharge standard enforcement records and EU Green Deal procurement guideline implementations.
Scenario-bracketing around regulatory enforcement intensity variations and copper price volatility bands shaped projections across the analysis window. Segmentation dimensions modeled include formulation chemistry tier, deployment setting context, buyer sophistication archetype, and regional regulatory cluster alignment. CAGRs derived from installed base erosion rates for copper-based actives and penetration velocity curves for polymeric alternatives, with aquaculture biosecurity mandate expansion and data center cooling buildout serving as volume growth anchors.
Macroeconomic conditions sit as an overlay; deviation in bunker fuel costs affecting Yangtze River freight economics or London Metal Exchange copper pricing volatility would shift the trajectory. Forecasts reflect documented assumptions regarding REACH enforcement timelines and MEE dual carbon standard implementation; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Fogger Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Soybean Fungicide Seed Treatment Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Europe Acaricides Market
Crop Protection
Organic Pesticides Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
South America Nematicides Market
Crop Protection
US Insecticide Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
Specialty Pesticides Market
Crop Protection
India Insecticide Market
Crop Protection
Herbicides Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Iprodione Market