
 Global Termite Control Market | 2026-2036
Global Termite Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Termite Control Market Outlook
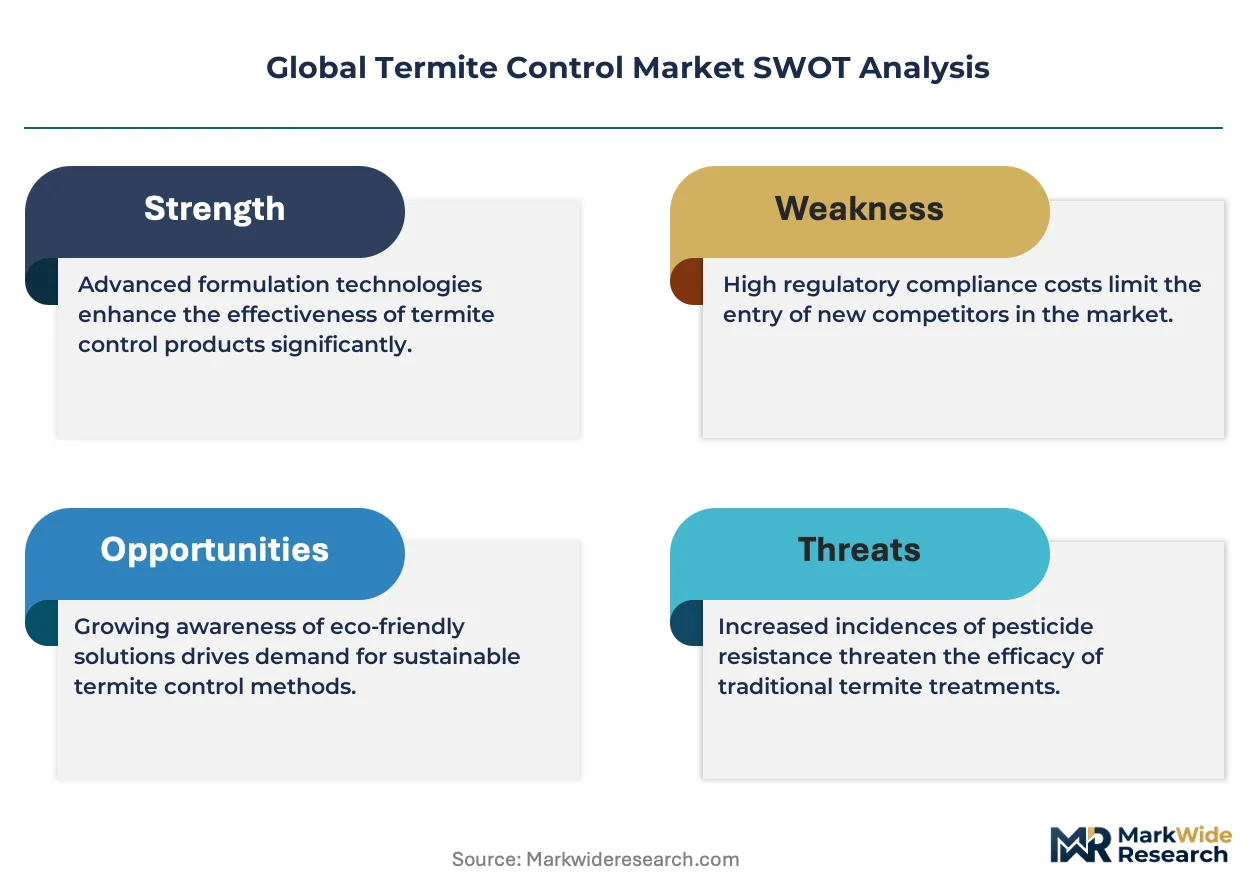
Buyer concentration across large-scale property management portfolios and national housing developers is recalibrating procurement patterns toward long-term service contracts with bundled monitoring. Syngenta Crop Protection leverages its agrochemical R&D pipeline to cross-develop termiticide active ingredients with broader pest control applications. BASF SE anchors its position through polymer-based bait matrix technologies that differentiate performance in high-moisture soil conditions. Rentokil Initial plc competes through dense technician networks spanning multiple continents, sustaining recurring revenue through inspection-based subscription models.
Termite control encompasses chemical, physical, and biological interventions designed to prevent, eliminate, or manage termite infestations in built structures and agricultural assets, with liquid termiticides typically formulated as non-repellent pyrethroids or neonicotinoids applied at 4 gallons per 10 linear feet of foundation perimeter. The primary commercial purpose centers on protecting structural timber integrity, reducing repair liabilities, and preserving property values in regions where subterranean and drywood species establish persistent colonies. Liquid termiticides occupy the largest value share due to immediate barrier efficacy and established applicator familiarity, though baiting systems represent the fastest-expanding category as property owners prioritize reduced environmental persistence and targeted colony elimination. Bio-control methods remain nascent but attract margin-focused investment where regulatory pressure restricts conventional chemistry access.
The EPA's FIFRA framework governs product registration and label restrictions in the United States, while the EU Biocidal Products Regulation mandates active substance approval through ECHA, narrowing the approved chemistry set and extending development timelines. Australia's APVMA enforces residue and efficacy standards that shape export formulation requirements for multinational suppliers. Stakeholders must monitor evolving regulatory thresholds for neonicotinoid class restrictions and calibrate R&D allocation toward biological alternatives before chemistry sunsets accelerate across major jurisdictions.
Market Dynamics
The termite control market is experiencing structural compression as regulatory chemistry sunsets in the United States and European Union force accelerated R&D redirection toward biological alternatives and polymer-based bait matrices.
Growth Catalysts
- Subtropical Residential Construction:Housing development across Florida, Queensland, and Southeast Asian coastal zones is embedding preventive termiticide protocols into building codes. Municipal inspectors now mandate pre-construction soil treatments.
- FIFRA Registration Pathways:The EPA's conditional registration framework for reduced-risk pesticides is channeling investment toward biopesticide active ingredients with favorable toxicological profiles.
- Integrated Pest Management Mandates:Australia's APVMA residue standards are driving adoption of monitoring-based service contracts that bundle inspection with targeted intervention rather than blanket chemical application.
Market Restraints
- Active Ingredient Supply Concentration:Neonicotinoid and pyrethroid technical manufacturing clusters in eastern China face export license volatility that disrupts formulation supply to Latin American and African markets.
- EU Biocidal Products Regulation Friction:ECHA's extended evaluation timelines for existing active substances are freezing product label expansions and forcing portfolio rationalization across European operators.
- Soil Barrier Degradation:High-moisture clay soils in monsoon-affected regions accelerate chemical breakdown, requiring reapplication cycles that strain customer retention and service margin.
Strategic Opportunities
- Biological Control Convergence:Entomopathogenic fungi and nematode formulations are converging with precision application drones to enable targeted colony elimination without soil persistence.
- Underpenetrated African Markets:Nigeria, Kenya, and Ghana present white space for preventive treatment adoption as urban timber construction accelerates and mortgage lenders begin requiring structural protection certificates.
- Smart Monitoring Hardware:IoT-enabled bait station sensors are creating subscription revenue streams that displace transactional treatment sales in Australian and Japanese residential markets.
Industry Challenges
- Certified Applicator Scarcity:The technical workforce trained in both conventional chemistry and biological systems remains thin across Southeast Asian service networks, constraining quality assurance.
- Dual Registration Burden:Suppliers seeking parallel EPA and EU approvals face divergent data requirements that extend development timelines and inflate dossier preparation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Termite Control Market |
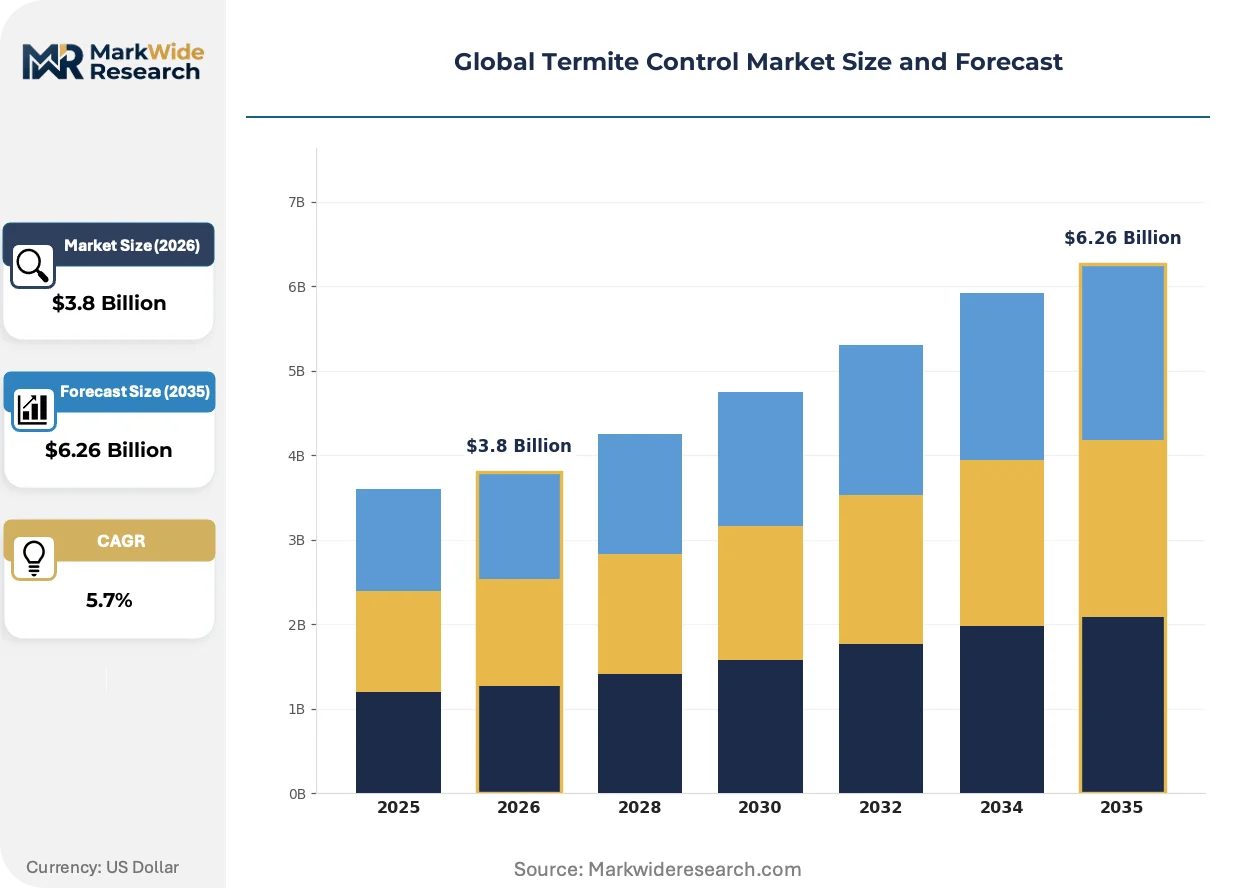
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Termiticides, Baiting Systems, Fumigants, Wood Treatments Application: Residential, Commercial, Industrial, Agricultural Treatment Method: Preventive, Curative, Integrated Pest Management, Bio-control Distribution Channel: Online Retail, Distributors, Direct Sales, Home Improvement Stores |
| Companies Covered | Syngenta Crop Protection, Dow Incorporation, BASF SE, Pidilite Industries Ltd., Sumitomo Chemical, Rentokil Initial plc, FMC Corporation, UPL Ltd., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Termite Control Market Strategic Shifts
Automation and biological substitution are restructuring how termite control services are delivered, with hardware-enabled monitoring displacing scheduled inspections and regulatory pressure compressing the chemistry toolkit.
Remote sensing technology is automating colony detection and treatment verification. National housing developers and institutional property managers in Australia and the southern United States are deploying networked in-ground sensors that transmit moisture and termite activity data to centralized dashboards. This infrastructure is automating the transition from calendar-based service visits to condition-triggered interventions, compressing labor costs and improving customer retention through demonstrated efficacy transparency.
REACH and the EU Biocidal Products Regulation are systematically narrowing approved chemistry sets for soil-applied termiticides. ECHA's hazard-based cutoff criteria for endocrine disruption and persistence are disqualifying legacy pyrethroid formulations from renewal applications. European formulators are responding by redirecting R&D toward microbial agents and physical barrier systems, with Germany and France leading pilot programs for nematode-based perimeter treatments in sensitive groundwater zones.
Large-scale property owners are consolidating vendor relationships and demanding performance-guaranteed service contracts. National retailers and logistics warehouse operators in the United States are unbundling inspection from treatment and awarding multi-year agreements based on documented damage prevention metrics. This restructuring favors service providers with dense technician networks and proprietary monitoring hardware, particularly visible in Texas and California industrial corridors where portfolio-scale procurement teams negotiate centralized contracts.
Global Termite Control Market Segmentation
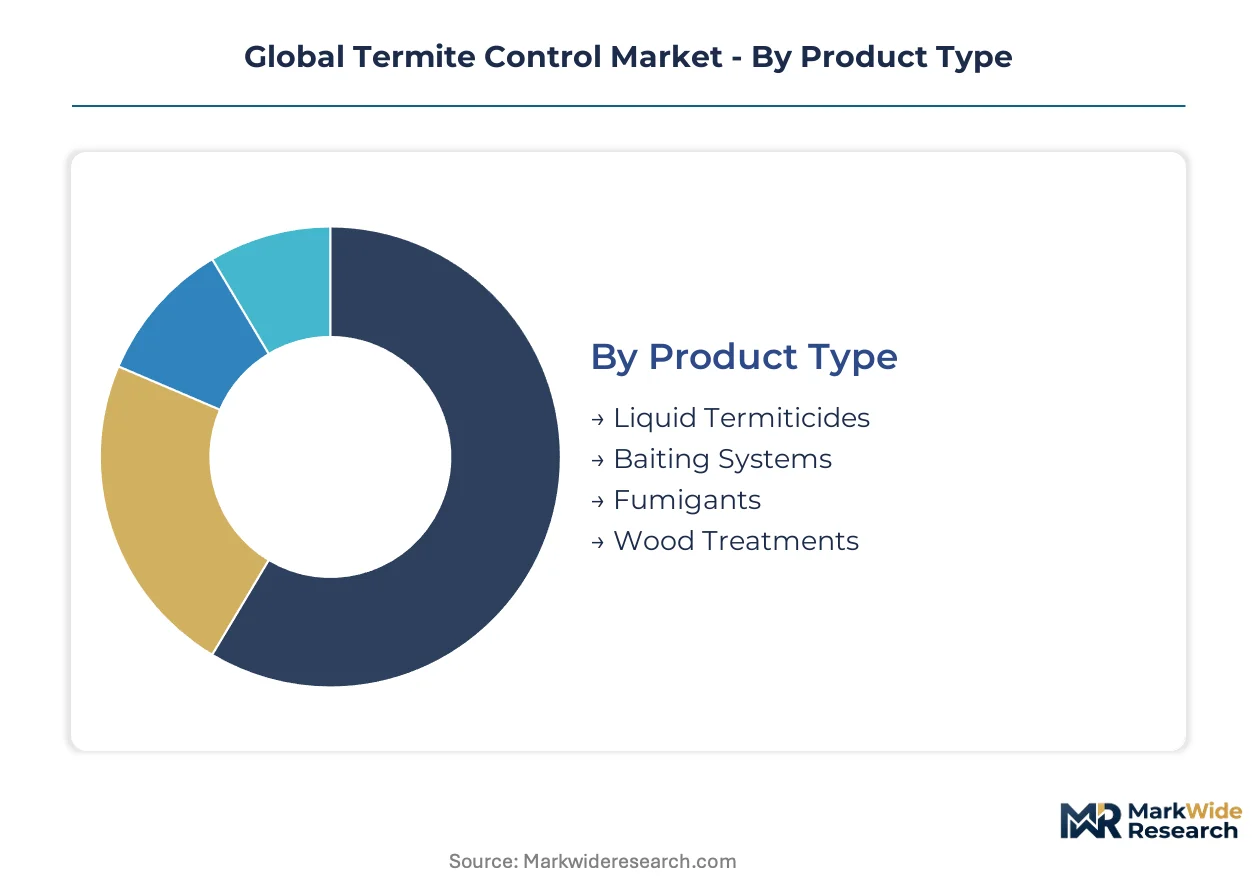
Termite control suppliers configure their manufacturing assets and field service networks around four distinct segment hierarchies. Product type determines formulation chemistry and equipment requirements. Application setting shapes service frequency and regulatory exposure. Treatment method reflects customer risk tolerance and environmental constraints. Distribution channel governs margin structure and customer acquisition costs.
Product Type:
Capital intensity concentrates in manufacturing infrastructure for liquid termiticides and polymer-based bait matrices, with fumigants and wood treatments requiring less specialized production equipment.
- Liquid Termiticides:Non-repellent pyrethroids and neonicotinoids formulated for soil barrier application at foundation perimeters. Demand clusters in Florida, Queensland, and Southeast Asian coastal zones where municipal building codes mandate pre-construction soil treatments.
- Baiting Systems:Polymer matrices impregnated with slow-acting active ingredients deployed in ground stations for colony elimination. Property owners in Australia and Japan prioritize reduced environmental persistence, driving adoption of monitoring-based service subscriptions.
- Fumigants:Gas-phase treatments for whole-structure elimination of drywood termite infestations. Limited to specific regulatory jurisdictions with certified applicator requirements.
- Wood Treatments:Surface and pressure-applied preservatives for exposed timber in agricultural and industrial settings. Demand concentrates in timber-framed warehouse construction.
Liquid termiticides absorb the bulk of installed capacity; baiting systems are expanding most quickly.
Application:
Service contract value and renewal rates diverge sharply across settings, with industrial and commercial portfolios generating recurring revenue through inspection mandates while residential remains transaction-heavy.
- Residential:Single-family homes and multi-unit housing developments requiring preventive soil treatments or reactive colony elimination. Australia's housing stock vulnerability to subterranean species sustains investment in integrated pest management services.
- Commercial:Retail, hospitality, and office properties where damage liabilities and lease compliance drive scheduled inspection protocols. National property management portfolios in the United States consolidate vendor relationships around performance-guaranteed multi-year agreements.
- Industrial:Logistics warehouses and manufacturing facilities with timber structural elements. Procurement teams in Texas and California industrial corridors negotiate centralized contracts based on documented damage prevention metrics.
- Agricultural:Timber storage facilities and processing equipment protection. Limited penetration outside tropical commodity zones.
Commercial applications command the highest contract values; residential delivers the largest addressable customer base.
Treatment Method:
Regulatory chemistry sunsets in the United States and European Union are compressing the conventional toolkit and redirecting R&D expenditure toward biological alternatives and precision hardware.
- Preventive:Pre-construction soil barriers and physical exclusion systems installed during building phase. Municipal inspectors in Florida and Queensland embed these protocols into building codes.
- Curative:Reactive treatments following confirmed infestation detection. Higher customer acquisition costs and one-time revenue recognition strain service margins.
- Integrated Pest Management:Monitoring-based protocols combining inspection, habitat modification, and targeted intervention. Australia's APVMA residue standards accelerate adoption of bundled service contracts.
- Bio-control:Entomopathogenic fungi and nematode formulations for targeted colony elimination. Pilot programs in Germany and France deploy nematode-based perimeter treatments in sensitive groundwater zones.
Preventive protocols dominate new construction attachment; integrated pest management is gaining share fastest in mature housing markets.
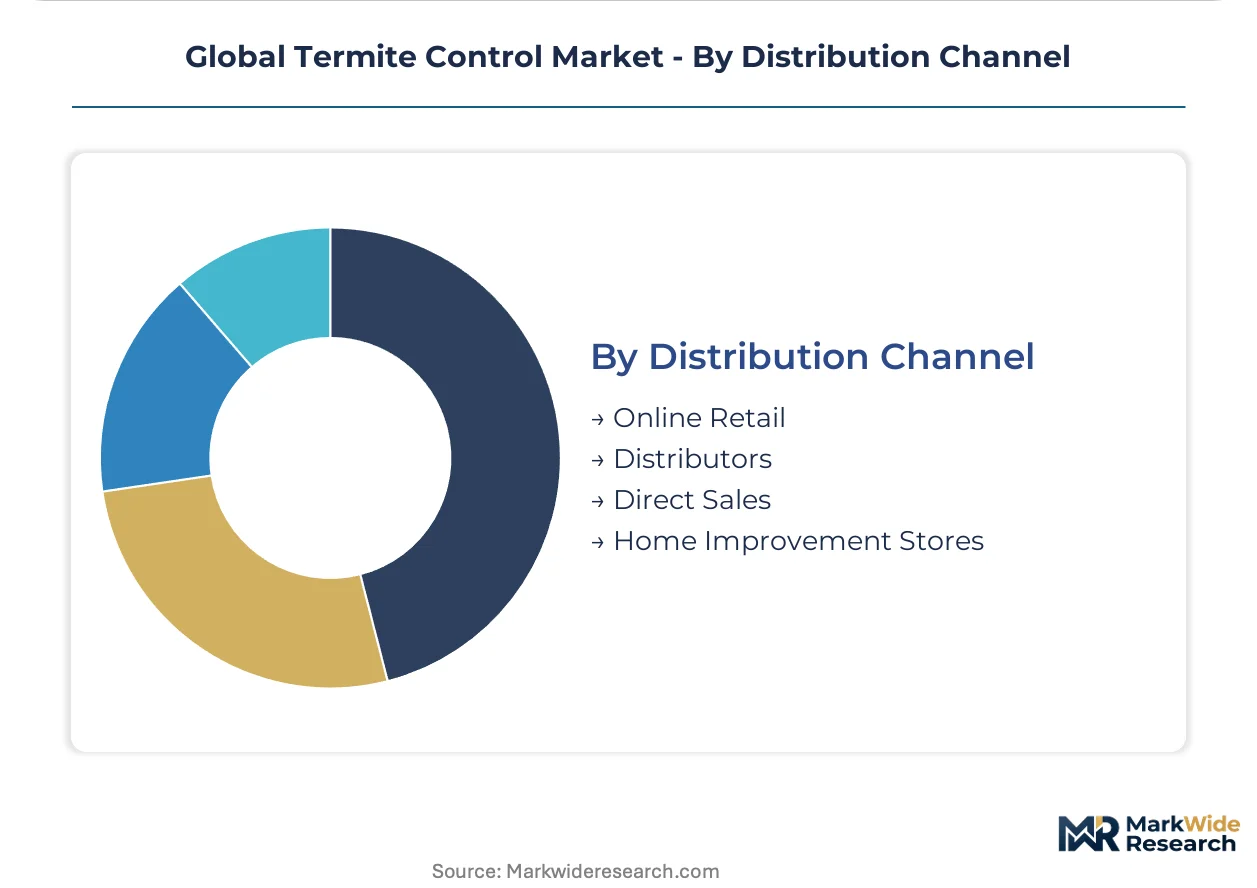
Distribution Channel:
Channel selection determines technical support requirements and price realization, with direct sales capturing premium service contracts while retail and online serve the DIY prevention segment.
- Direct Sales:Manufacturer-to-applicator relationships for professional-grade formulations and equipment. Dense technician networks sustain recurring revenue through inspection-based subscription models.
- Distributors:Regional chemical and pest control supply houses serving independent operators. Concentrated in Latin American and African markets with fragmented service landscapes.
- Home Improvement Stores:Consumer-grade termiticides and bait stations for perimeter application. Limited to jurisdictions without mandatory professional applicator requirements.
- Online Retail:E-commerce platforms for monitoring hardware and replacement bait cartridges. IoT-enabled sensor subscriptions create recurring revenue streams displacing transactional sales.
Direct sales channels capture the highest margin service contracts; online retail is climbing the fastest as smart monitoring hardware penetrates residential markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for termite control concentrates in subtropical housing markets where municipal building codes mandate preventive soil treatments and subterranean species threaten structural timber. Australia, the United States, and Southeast Asian coastal zones anchor procurement volume, while regulatory divergence across EPA, ECHA, and APVMA frameworks reshapes product registration strategies.
United States
Florida and Texas drive preventive termiticide demand through statewide building code mandates for pre-construction soil barriers. The EPA's FIFRA conditional registration framework channels investment toward reduced-risk biopesticide formulations with favorable toxicological profiles. Houston and Miami metropolitan construction corridors embed liquid termiticide protocols into foundation work, sustaining applicator network density.
Australia
Queensland and New South Wales housing stock faces persistent subterranean termite pressure, driving sustained investment in integrated pest management service contracts. The APVMA enforces residue and efficacy standards that shape formulation requirements for multinational suppliers. Brisbane and Sydney property markets prioritize monitoring-based subscriptions over blanket chemical application.
Germany
ECHA's hazard-based cutoff criteria for endocrine disruption and persistence disqualify legacy pyrethroid formulations from renewal applications. The EU Biocidal Products Regulation extends evaluation timelines for existing active substances, freezing product label expansions. Pilot programs in Bavaria and Baden-Württemberg deploy nematode-based perimeter treatments in sensitive groundwater zones.
China
Guangdong and Fujian provinces accelerate urban timber construction across coastal subtropical zones, expanding preventive treatment adoption. The Ministry of Ecology and Environment tightens export license oversight for neonicotinoid and pyrethroid technical manufacturing clusters. Shenzhen and Guangzhou housing developments increasingly specify polymer-based bait matrices for colony elimination.
Brazil
São Paulo and Rio de Janeiro industrial corridors witness rising demand for structural timber protection in logistics warehouse construction. ANVISA regulates termiticide registration with residue standards that influence formulation imports from Asian technical suppliers. National retailers consolidate vendor relationships around performance-guaranteed multi-year service agreements.
Global Termite Control Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biological alternatives and precision hardware integration. The market exhibits moderate consolidation, with agrochemical conglomerates leveraging cross-sector R&D pipelines alongside specialized pest control service networks. Three archetypes dominate: chemistry-led manufacturers with agrochemical heritage, service-intensive operators with dense technician footprints, and technology-focused entrants developing IoT-enabled monitoring infrastructure. Competitive moves center on portfolio diversification into bio-control formulations and strategic partnerships with property management platforms.
Within the chemistry-led tier, Syngenta Crop Protection and BASF SE exemplify agrochemical conglomerates redirecting R&D expenditure toward reduced-risk active ingredients and polymer-based delivery systems. Rentokil Initial plc anchors the service-intensive archetype through inspection-based subscription models spanning multiple continents. These three entities represent divergent strategic postures: manufacturing-scale chemistry development, materials science innovation in bait matrices, and field-service network density.
| Leading Market Players |
|---|
| Syngenta Crop Protection |
| Dow Incorporation |
| BASF SE |
| Pidilite Industries Ltd. |
| Sumitomo Chemical |
| Rentokil Initial plc |
| FMC Corporation |
| UPL Ltd. |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Polymer-based bait matrix manufacturing is compressing cost economics for mid-tier formulators while concentrating supply leverage among agrochemical conglomerates with captive technical production. This dual shift elevates procurement power for buyers of liquid termiticides while fragmenting pricing discipline across biological alternatives.
Pricing Analysis
Volume-margins split sharply between transactional liquid termiticide sales and subscription-based monitoring services. Three-tier pricing structure across premium certified-applicator services, standard independent operator supply, and economy-grade DIY retail channels reflects certification grade and after-sales bundling. Pricing pressure stems from ECHA's chemistry sunsets forcing portfolio rationalization. Residential property managers exhibit highest price sensitivity; national housing developers accept premium tiers for damage guarantee coverage.
Supply Chain Analysis
Technical-grade pyrethroid and neonicotinoid supply rests on manufacturing clusters in eastern China, India, and Germany. Active ingredient synthesis draws from petrochemical feedstocks, specialty solvent formulations, and polymer excipients. Single-source vulnerability concentrates in Chinese export license volatility for regulated substances. Distribution runs through regional chemical supply houses serving certified applicators, with direct manufacturer relationships capturing institutional contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active ingredient supply constraints are propping pricing power for manufacturers with backward-integrated technical production, even as service margins compress from chemistry-to-biological transition costs.
For Market Incumbents: Deepen vertical integration into nematode cultivation and fungal fermentation capacity before regulatory sunsets accelerate. Lock in long-term service contracts with national retailers and logistics operators to defend against IoT-enabled monitoring entrants. Prioritize APVMA pre-registration for biological formulations to secure Australian market positioning. For New Entrants and Emerging Players: Launch via direct-to-applicator digital platforms targeting independent operators in Nigeria, Kenya, and Ghana where certified technician networks remain thin. Focus initial penetration on preventive treatment adoption in urban timber construction corridors. Bundle smart monitoring hardware subscriptions with biological bait matrices to bypass chemistry registration barriers. For Investors and Strategic Acquirers: Re-rating potential sits with biological control specialists given ECHA's hazard-based cutoff criteria accelerating chemistry displacement. Five-to-ten year viability favors entomopathogenic fungi platforms with proven colony elimination metrics. Watch APVMA residue standard tightening as inflection signal for biological formulation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biological Production | Captive nematode and fungal supply insulates against ECHA chemistry renewal freezes. |
| IoT-Enabled Monitoring Platform Launch | Sensor subscriptions displace transactional treatment sales in Australian residential markets. |
| Long-Term Service Contract Expansion | Multi-year agreements with Texas and California industrial portfolios stabilize recurring revenue. |
| Joint Venture with Property Management Platforms | Centralized procurement access accelerates penetration of national housing developer accounts. |
| Green Certification Program Development | Reduced-risk biopesticide labeling unlocks EPA conditional registration pathways. |
Study Parameters
Independent corroboration across plant managers at termiticide formulation facilities, procurement leads at national pest control service networks, APVMA regulatory affairs specialists, and distribution channel partners underwrites the qualitative findings. Secondary validation draws from EPA FIFRA registration databases, ECHA biocidal product dossiers, customs trade data for pyrethroid technical imports, and SEC filings of publicly traded agrochemical conglomerates. Bottom-up service contract value estimates triangulate against top-down addressable housing stock calculations.
Historical reference periods anchor volume and value trajectories across the modeling period, with segmentation dimensions spanning product type, application setting, treatment method, and distribution channel. CAGRs derive from installed base growth rates, replacement cycle analysis, and regulatory-driven product mix shifts. Forecast inputs incorporate municipal building code adoption timelines, chemistry sunset schedules, and smart monitoring hardware penetration curves.
Regulatory approval delays, export license volatility for Chinese technical suppliers, and faster-than-expected biological formulation efficacy gains are the dominant revision risks. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
South America Nematicides Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
IPM Pheromones Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
China Fungicide Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Herbicides Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Dicamba Market
Crop Protection
Isoxaflutole Market
Crop Protection
Microbial Pesticides Market