
 China Crop Protection Chemicals Market | 2026-2036
China Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
China Crop Protection Chemicals Market Outlook
Project finance tied to integrated pest management infrastructure is rewriting competitive access for domestic formulators. Jiangsu Yangnong Chemical leverages captive synthesis of pyrethroid intermediates to sustain margin control across insecticide production. Shandong Weifang Rainbow Chemical anchors its position through backward integration into technical-grade active ingredient manufacturing. ADAMA Agricultural Solutions navigates China's regulatory environment through localized formulation facilities and distributor partnerships.
Crop protection chemicals encompass synthetic and biological agents formulated to control weeds, insects, fungi, and rodents that reduce agricultural yields, typically manufactured through multi-step organic synthesis or fermentation processes requiring precise purity thresholds above 95 percent active ingredient content. Herbicides occupy the largest product type position due to mechanized planting expansion across China's northern plains, while fungicides represent the fastest-growing category as humid southern climates intensify crop disease pressure. Agricultural application dominates volume consumption, though horticultural segments command premium pricing through specialized emulsifiable concentrate formulations.
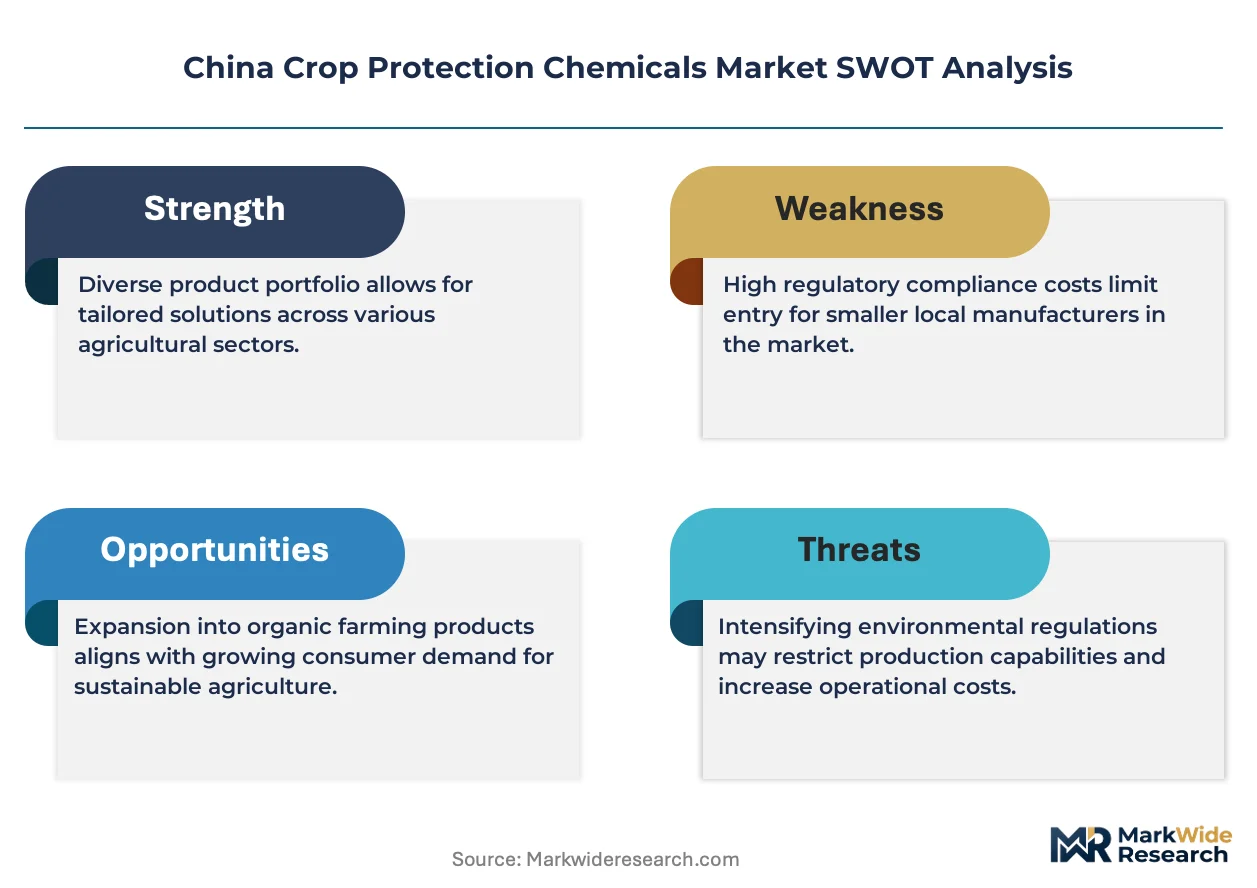
China's Ministry of Ecology and Environment enforces discharge standards under GB 31571 that constrain synthesis facility locations, while NMPA registration requirements under pesticide administration regulations extend product approval timelines and elevate R&D barriers for new molecular entries. The zero-growth pesticide action plan issued by the Ministry of Agriculture and Rural Affairs redirects formulation demand toward biopesticide alternatives and ultra-low-volume application technologies. Stakeholders must monitor evolving GB standard revisions and provincial environmental compliance audits to anticipate which active ingredients face production restrictions or accelerated phase-out schedules.
Market Dynamics
China's zero-growth pesticide use policy is compressing volume demand while redirecting procurement toward precision application systems and bio-based formulations. This structural pivot rewards formulators with captive technical-grade synthesis capabilities and penalizes pure traders.
Growth Catalysts
- Mechanized Planting Expansion:Large-scale wheat and rice operations across Hebei and Henan provinces require broad-spectrum herbicide coverage. Automated spraying equipment penetration creates pull for emulsifiable concentrate formulations calibrated to drone delivery systems.
- GB 31571 Discharge Standards:Ministry of Ecology and Environment enforcement is shuttering subscale synthesis facilities in non-compliant zones. Surviving producers in Shandong and Jiangsu gain capacity discipline and pricing leverage.
- Ultra-Low-Volume Application Technologies:Water-based nano-formulations reduce active ingredient loading per hectare. Yangtze River Basin horticulture operations adopt these systems to meet residue limit protocols for export-bound produce.
Market Restraints
- Intermediate Import Dependency:Captive pyrethroid precursor synthesis remains concentrated among three domestic producers. Technical-grade active ingredient supply bottlenecks constrain formulator margin recovery during input cost spikes.
- NMPA Registration Timelines:New molecular entity approval extends beyond five years under pesticide administration regulations. Extended R&D amortization periods deter venture investment in novel chemistry platforms.
- Biopesticide Performance Gaps:Fermentation-derived bacillus formulations exhibit temperature-sensitive efficacy profiles. Northern plain operators retain synthetic pyrethroids for reliable cold-weather pest control.
Strategic Opportunities
- Western Province Penetration:Sichuan and Shaanxi agricultural cooperatives remain underserved by technical advisory services. Bundled input-plus-application training packages open channel access for integrated pest management providers.
- Export Registration Arbitrage:Brazil's ANVISA and Australia's APVMA maintain parallel approval pathways for Chinese technical-grade exports. Dual-registration capabilities capture premium pricing in Southern Hemisphere growing seasons.
- Drone-Formulation Convergence:Low-volatility, low-drift adjuvant systems align with CAAC unmanned aerial vehicle operation permits. Co-development partnerships with agricultural drone manufacturers lock in specification standards.
Industry Challenges
- Formulation Chemist Scarcity:Multi-step organic synthesis expertise concentrates among aging technical staff in state-owned research institutes. Private-sector recruitment competes with pharmaceutical industry compensation benchmarks.
- Provincial Audit Compliance Burden:Environmental inspection rotation schedules require dedicated regulatory affairs personnel at each manufacturing site. Mid-tier formulators face fixed cost escalation without proportional volume recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Crop Protection Chemicals Market |
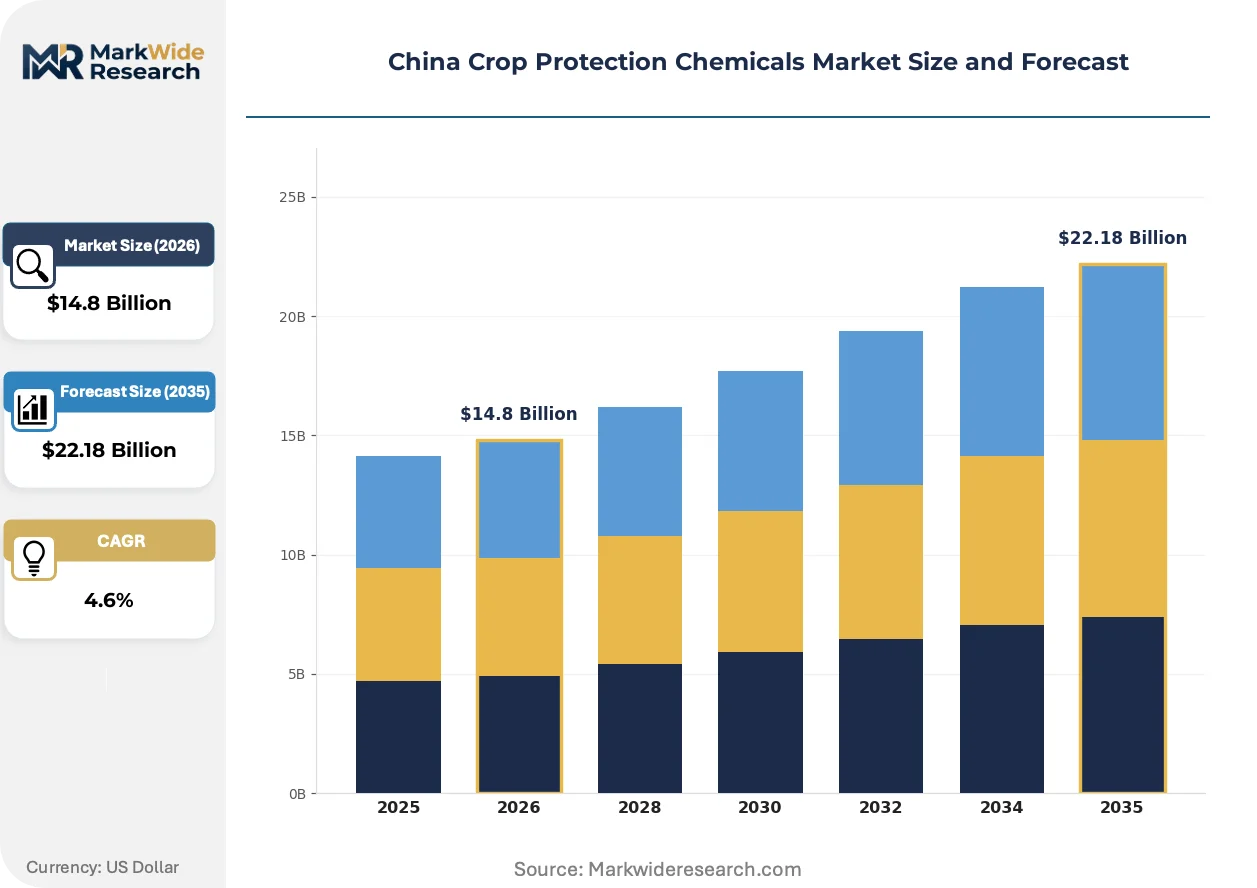
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Application: Agricultural, Horticultural, Turf & Ornamental, Others Distribution Channel: Direct Sales, Distributors, Retailers, E-commerce Formulation Type: Liquid, Granular, Water-Soluble, Emulsifiable Concentrate |
| Companies Covered | Jiangsu Yangnong Chemical Co. Ltd, Shandong Weifang Rainbow Chemical Co. Ltd, ADAMA Agricultural Solutions Ltd, Syngenta Group, BASF SE, Bayer AG, FMC Corporation, Anhui Guangxin Agrochemical Co. Ltd, CAC Nantong Chemical Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Crop Protection Chemicals Market Strategic Shifts
Formulation chemistry and application hardware are converging to reduce active ingredient intensity per treated hectare. This reconfiguration favors integrated input suppliers over standalone chemical traders.
Encapsulated controlled-release formulations are migrating from experimental greenhouse trials to broad-acre deployment. Large-scale vegetable cooperatives in Shandong province adopt these systems to compress labor scheduling around rainfall windows. The technology is migrating from premium horticulture into commodity grain operations as unit economics improve with manufacturing scale.
China's Ministry of Agriculture and Rural Affairs zero-growth action plan mandates annual pesticide use reduction targets at provincial level. County-level agricultural bureaus redirect subsidy eligibility toward biopesticide procurement and precision application equipment. Formulators with NMPA-registered biological product portfolios capture preferential distribution access through state procurement channels.
Cooperative buying consortia in Jiangsu and Anhui provinces consolidate input purchasing across contiguous township boundaries. Aggregated volume contracts displace traditional village-level retailer networks. This concentration is most visible in rice-producing counties where mechanized service providers bundle seed, fertilizer, and crop protection into single-season packages.
China Crop Protection Chemicals Market Segmentation
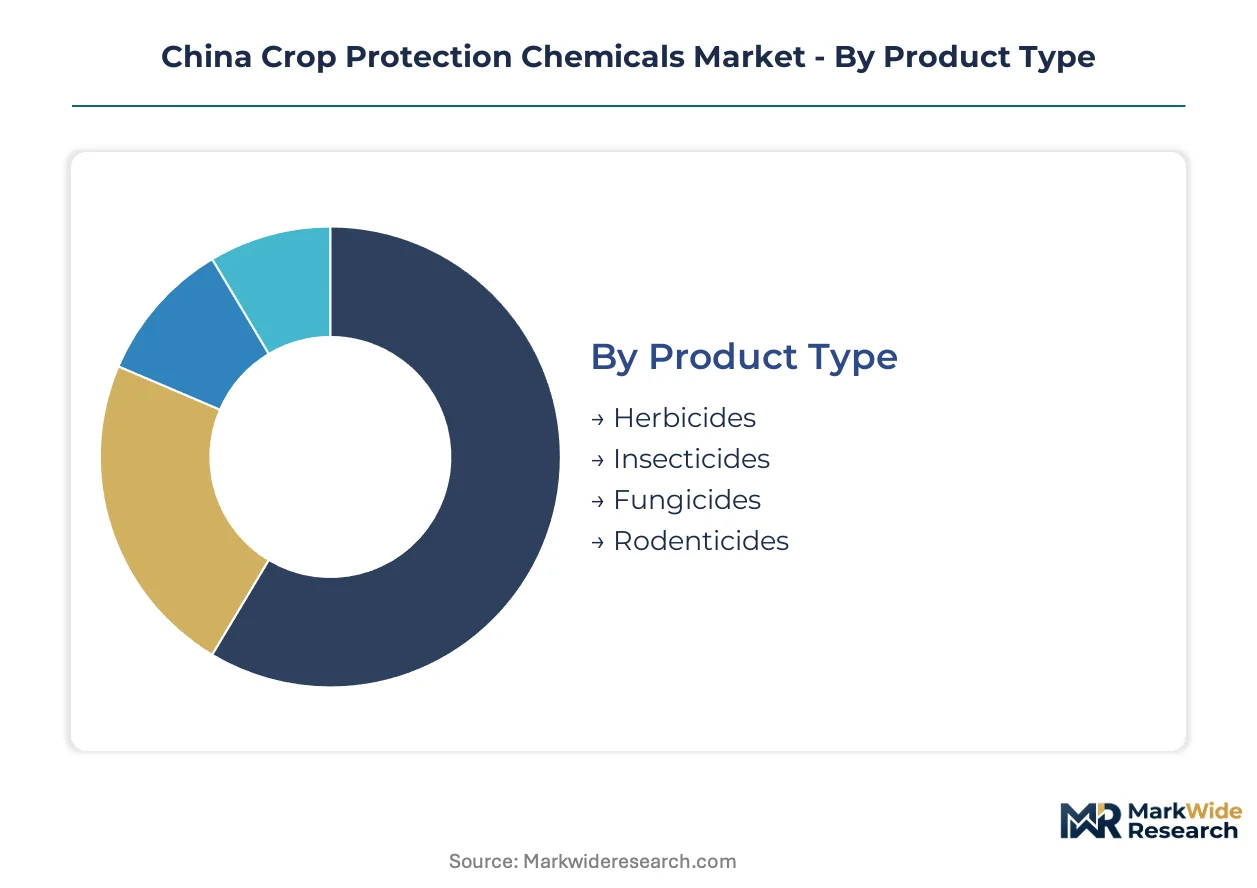
Segmentation in China's crop protection chemicals market reveals how procurement authority, application technology, and regulatory pressure fragment demand across distinct commercial channels. Understanding these divides exposes where margin concentrates and where volume growth is rotating.
Product Type:
Cost tier separation across synthetic and biological chemistries determines which active ingredients survive under zero-growth policy constraints.
- Herbicides:Synthetic auxin mimics and glyphosate-based formulations dominate mechanized wheat and rice operations across Hebei and Henan provinces. Large-scale planting contractors in the North China Plain specify broad-spectrum pre-emergent products to compress labor windows around sowing schedules. Herbicides hold installed capacity. Fungicides is rotating up the share rankings.
- Insecticides:Pyrethroid and neonicotinoid chemistries face MEE discharge standard restrictions that concentrate technical-grade synthesis among Shandong and Jiangsu producers with captive intermediate capabilities. Yangtze River Basin vegetable cooperatives retain synthetic options for reliable cold-weather efficacy where fermentation-derived alternatives fail.
- Fungicides:Triazole and strobilurin formulations address humid southern climate disease pressure in rice and citrus operations. Encapsulated controlled-release variants from Shandong manufacturers are migrating from greenhouse trials to broad-acre vegetable cooperatives.
- Rodenticides:Anticoagulant and zinc phosphide products serve grain storage facilities and pastoral grassland management in Inner Mongolia and Xinjiang production zones.
Fungicides is rotating up the share rankings. Herbicides holds installed capacity.
Application:
Customer type hierarchy separates price-sensitive commodity grain operators from premium-paying horticultural specialists seeking residue-compliant export certification.
- Agricultural:Mechanized wheat, rice, and corn operations across the North China Plain consume emulsifiable concentrate formulations calibrated to drone spraying systems. County-level agricultural bureaus redirect subsidy eligibility toward precision application equipment and biopesticide alternatives under zero-growth mandates.
- Horticultural:Shandong greenhouse vegetable cooperatives and Yangtze River Basin citrus orchards command premium pricing for specialized nano-formulations meeting EU and Japanese residue limits. Water-based ultra-low-volume systems reduce active ingredient loading per hectare while maintaining export market access.
- Turf & Ornamental:Golf course and municipal landscaping maintenance in tier-one cities drives demand for low-phytotoxicity selective herbicides and systemic fungicides with extended residual control.
- Others:Forestry protection and aquatic weed management applications serve specialized provincial water conservancy and ecological restoration programs under MEE watershed protection directives.
Agricultural commands volume scale. Horticultural is climbing the fastest.
Distribution Channel:
Supply concentration dynamics favor integrated formulators with direct township access over fragmented retailer networks facing cooperative buying consolidation.
- Direct Sales:Large-scale agricultural service providers in Jiangsu and Anhui provinces negotiate aggregated volume contracts across contiguous township boundaries. Bundled seed-fertilizer-crop protection packages displace traditional village-level retailer relationships.
- Distributors:Provincial-level agrochemical distributors with NMPA registration portfolios and technical advisory capabilities capture preferential access to state procurement channels for biopesticide subsidies.
- Retailers:Village-level input shops face margin compression as cooperative buying consortia consolidate purchasing power and mechanized service providers internalize chemical procurement.
- E-commerce:Alibaba and Pinduoduo platforms enable smallholder access to generic formulations, though drone-compatible specialty products and technical-grade actives remain offline due to CAAC operational permit requirements and NMPA registration verification needs.
Direct Sales is gaining share fastest. Distributors retains infrastructure depth.
Formulation Type:
Application technology convergence with drone hardware is reconfiguring which physical forms capture growth versus legacy ground-spray formats.
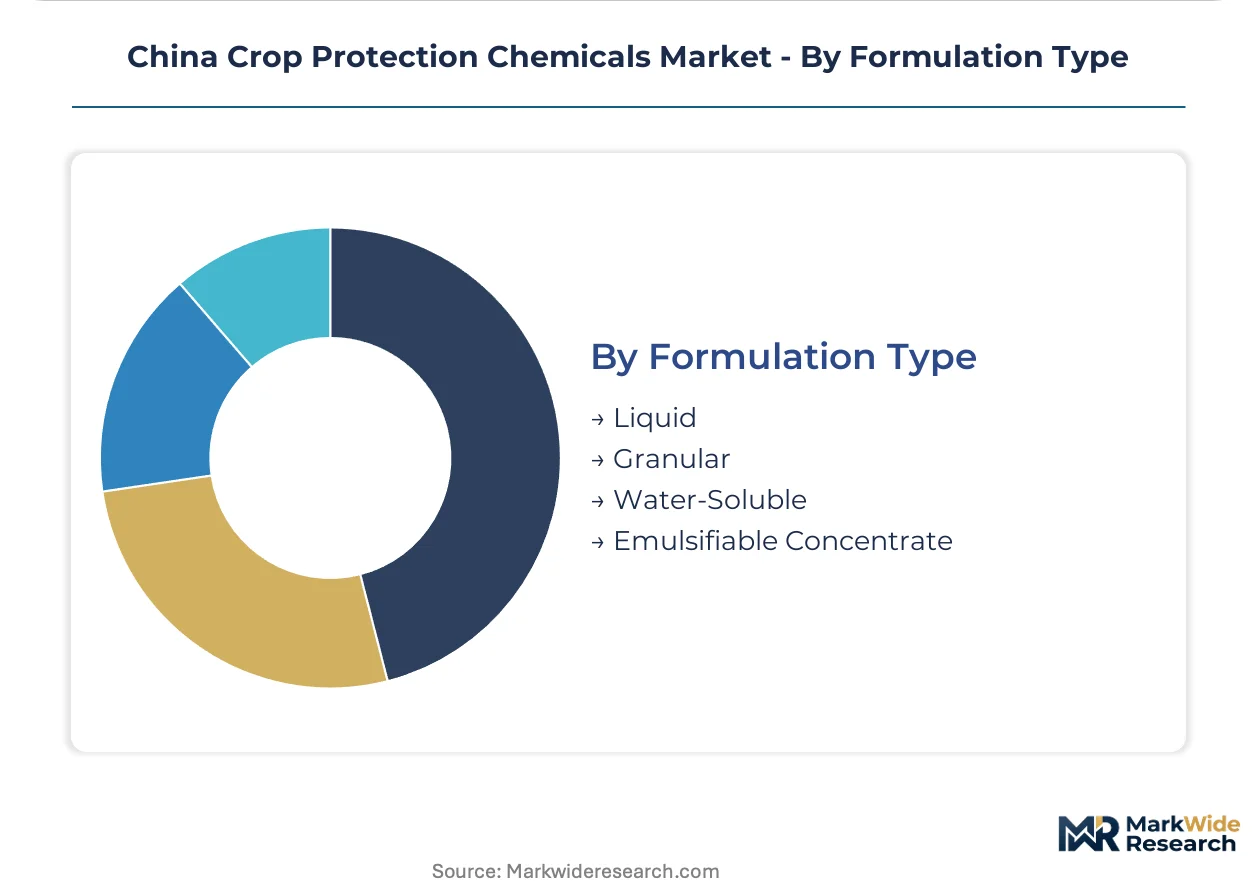
- Liquid:Suspension concentrate and micro-emulsion formats dominate drone spraying operations requiring low-viscosity flow through precision nozzles. Yangtze River Basin horticulture operations adopt water-based nano-formulations to meet residue protocols for export-bound produce.
- Granular:Controlled-release fertilizer-pesticide combinations serve labor-constrained rice operations in Sichuan and Hunan provinces where manual broadcasting persists.
- Water-Soluble:Powder and granule formats for tank-mix flexibility appeal to cooperative buying consortia seeking to optimize per-hectare input costs across variable soil conditions.
- Emulsifiable Concentrate:Traditional oil-based formulations retain share in northern plain ground-spray operations where drift control is less critical than unit cost minimization for commodity grain production.
Liquid is expanding most quickly. Emulsifiable Concentrate holds legacy volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial environmental enforcement under GB 31571 discharge standards is redistributing synthesis capacity toward compliant manufacturing clusters. County-level agricultural bureaus redirect subsidy eligibility toward precision application equipment and biopesticide alternatives.
Shandong Province
Mechanized wheat and corn operations across the North China Plain drive herbicide consumption for large-scale planting contractors. MEE discharge standard enforcement has shuttered subscale synthesis facilities in non-compliant zones. Weifang and Qingdao manufacturing clusters concentrate technical-grade active ingredient production for domestic distribution and export channels.
Jiangsu Province
Yangtze River Basin rice cultivation and greenhouse vegetable cooperatives generate fungicide demand amid humid southern climate disease pressure. NMPA registration requirements extend product approval timelines for new molecular entries. Yangnong Chemical and Nantong manufacturing anchors sustain captive pyrethroid intermediate synthesis capabilities.
Henan Province
Large-scale wheat operations require broad-spectrum pre-emergent herbicide coverage synchronized with compressed sowing labor windows. County-level zero-growth pesticide reduction targets redirect procurement toward ultra-low-volume application technologies. Zhengzhou logistics hubs coordinate input distribution to mechanized service providers bundling seed-fertilizer-crop protection packages.
Sichuan Province
Western agricultural cooperatives in rice-producing counties remain underserved by technical advisory services and integrated pest management infrastructure. Provincial environmental compliance audits constrain synthesis facility locations in watershed protection zones. Chengdu-based distributors consolidate purchasing across contiguous township boundaries through cooperative buying consortia.
Anhui Province
Rice mechanization and horticultural export zones drive nano-formulation adoption for residue-compliant produce bound for EU and Japanese markets. State procurement channels for biopesticide subsidies favor NMPA-registered biological product portfolios. Hefei and surrounding agricultural bureaus aggregate volume contracts displacing traditional village-level retailer networks.
China Crop Protection Chemicals Market Competitive Environment
On the supply side, the industry is consolidating around formulators with captive technical-grade synthesis capabilities and provincial environmental compliance infrastructure. Pure traders face margin compression as MEE enforcement eliminates subscale competitors. Three archetypes dominate: state-linked research institute spinoffs with legacy synthesis expertise, privately held chemical conglomerates with backward integration into intermediates, and multinational agricultural solutions providers with localized formulation facilities. Competitive dynamics center on M&A absorption of distressed synthesis assets and co-development partnerships with agricultural drone manufacturers for specification-locked adjuvant systems.
Among domestic chemical conglomerates, Jiangsu Yangnong Chemical Co. Ltd and Shandong Weifang Rainbow Chemical Co. Ltd exemplify the backward-integrated archetype with provincial manufacturing cluster positioning. ADAMA Agricultural Solutions Ltd occupies a position representing multinational localization strategy through distributor partnerships and NMPA registration infrastructure. These three anchors illustrate how technical-grade synthesis control and regulatory navigation capabilities determine competitive access under zero-growth policy constraints.
| Leading Market Players |
|---|
| Jiangsu Yangnong Chemical Co. Ltd |
| Shandong Weifang Rainbow Chemical Co. Ltd |
| ADAMA Agricultural Solutions Ltd |
| Syngenta Group |
| BASF SE |
| Bayer AG |
| FMC Corporation |
| Anhui Guangxin Agrochemical Co. Ltd |
| CAC Nantong Chemical Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Weifang and Qingdao manufacturing clusters in Shandong Province concentrate technical-grade active ingredient synthesis capacity, translating upstream environmental compliance costs into downstream pricing leverage for surviving formulators. MEE discharge standard enforcement has eliminated subscale competitors, tightening supply discipline and compressing margin recovery timelines for pure traders lacking captive intermediate production.
Pricing Analysis
Certification level under NMPA registration tiers creates the primary spread between premium and commodity formulations. Three-tier pricing structure across NMPA-registered biopesticide, precision-application specialty, and generic synthetic products reflects compliance investment amortization. Pricing pressure stems from zero-growth policy volume compression and cooperative buying consolidation across Jiangsu and Anhui provinces. Large-scale mechanized service providers exhibit lowest price sensitivity due to bundled input-plus-application contracts, while village-level retailers face margin erosion from aggregated volume negotiations.
Supply Chain Analysis
Captive synthesis capabilities at Jiangsu Yangnong Chemical and Shandong Weifang Rainbow Chemical anchor domestic technical-grade production, with intermediate supply drawing from Shandong and Jiangsu provincial clusters. Pyrethroid precursor synthesis and fermentation-derived biopesticide inputs hinge on temperature-controlled logistics and specialized chemical handling infrastructure. Single-source vulnerability concentrates around three domestic producers of pyrethroid intermediates, exposing formulators to input cost spikes during supply disruptions. Distribution runs through provincial-level agrochemical distributors with NMPA registration portfolios, bypassing fragmented village-level retailer networks as cooperative buying consortia consolidate township-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's crop protection chemicals sector is approaching a platform-economics inflection where drone-formulation interoperability standards will lock in specification control for integrated input suppliers, marginalizing standalone chemical traders unable to co-develop adjuvant systems with agricultural UAV manufacturers.
For Market Incumbents: Harden environmental compliance infrastructure across Shandong and Jiangsu manufacturing sites to defend against MEE audit rotation schedules that disproportionately burden mid-tier competitors. Prioritize backward integration into pyrethroid intermediate synthesis to reduce exposure to the three-producer supply bottleneck, while co-developing low-volatility adjuvant formulations with CAAC-permitted drone manufacturers to capture specification-locked procurement channels. For New Entrants and Emerging Players: Pursue technical advisory service bundling in underserved Sichuan and Shaanxi western provinces where integrated pest management infrastructure remains sparse. The penetrable entry point lies with rice-producing cooperatives seeking aggregated input-plus-training packages, using drone-compatible nano-formulation portfolios to differentiate from legacy ground-spray suppliers entrenched in commodity grain segments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulators with NMPA-registered biological product portfolios and captive synthesis capabilities over pure traders facing structural margin compression. Long-term viability across the analysis window rests on acquisition targets demonstrating provincial environmental compliance infrastructure and dual-registration capabilities for Brazil ANVISA and Australia APVMA export arbitrage. Watch NMPA biopesticide approval velocity as the inflection signal indicating subsidy channel access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrethroid Intermediates | Captive synthesis at Jiangsu and Shandong facilities insulates margin control from three-producer supply bottlenecks. |
| Drone-Formulation Co-Development Partnership | CAAC unmanned aerial vehicle permit alignment locks in specification standards for precision application adjuvant systems. |
| NMPA Biopesticide Registration Portfolio Expansion | Registered biological products capture preferential state procurement channel access under zero-growth subsidy redirection. |
| Dual-Registration Capability Buildout | Parallel ANVISA and APVMA approval pathways enable premium pricing capture in Southern Hemisphere growing seasons. |
| Western Province Technical Advisory Infrastructure | Sichuan and Shaanxi service bundling opens channel access for integrated pest management providers in underserved cooperatives. |
Study Parameters
A standing panel of agrochemical plant managers, provincial distributor procurement leads, NMPA regulatory affairs specialists, and Yangtze River Basin vegetable cooperative technical directors provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against MEE discharge compliance records, NMPA registration databases, customs export filings, and provincial agricultural bureau subsidy disbursement reports. Bottom-up volume estimates from township-level cooperative buying data were triangulated against top-down synthesis capacity assessments from Shandong and Jiangsu manufacturing clusters.
Scenario bracketing around zero-growth policy enforcement intensity and biopesticide substitution rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry type, application method, formulation physical form, and provincial regulatory compliance tier. CAGRs were derived from elasticity-adjusted demand projections incorporating mechanization penetration curves and drone adoption trajectories, with cross-validation against historical input intensity per hectare trends.
Sensitivities concentrate around MEE environmental audit rotation schedules, NMPA registration timeline extensions for novel molecular entities, and pyrethroid intermediate supply disruptions. Forecasts reflect assumptions regarding subsidy redirection velocity and cooperative buying consolidation pace that could materially revise trajectory if provincial implementation diverges. Quarterly review of NMPA biopesticide approval volumes, MEE facility closure announcements, and CAAC agricultural UAV permit issuance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Europe Herbicide Market
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Europe Nematicide Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Fosthiazate Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
Grape Fungicides Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Global Acephate Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Europe Acaricides Market
Crop Protection
Fumigation Market
Crop Protection
Vietnam Insecticide Market