
 Personal Protective Textile Market | 2026-2036
Personal Protective Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Protective Textile Market Intelligence
Healthcare procurement of protective textiles is recalibrating as infection control protocols expand beyond traditional hospital settings into outpatient clinics and long-term care facilities. DuPont leverages its aramid fiber expertise to anchor supply relationships with industrial buyers requiring flame-resistant coveralls. Milliken & Company competes through specialized flame-retardant fabric treatments that extend product lifecycles under extreme thermal exposure. W. L. Gore & Associates differentiates via membrane technology leadership in breathable chemical protective barriers.
Personal protective textiles encompass engineered fabrics designed to shield wearers from thermal, chemical, mechanical, or biological hazards through specified fiber compositions, weave densities, and functional coatings such as PTFE membranes or aluminized substrates. These materials serve critical industrial and commercial purposes by maintaining worker safety compliance while enabling task mobility in hazardous environments. Aramid-based materials dominate margin pools in high-heat applications where replacement cycles remain extended, while polyester blends capture volume in general manufacturing due to cost-efficient production scalability. Coveralls represent the fastest-growing product configuration as multi-hazard designs consolidate previously separate garment categories.
OSHA enforces permissible exposure limits that mandate employer-provided protective equipment across U.S. industrial workplaces, directly driving textile specification upgrades and replacement frequency. The EU Green Deal and REACH chemical restrictions are reshaping material formulations as European manufacturers phase out certain flame-retardant chemistries. China's GB standards and SAMR oversight accelerate domestic certification requirements that filter import access. Stakeholders must monitor evolving PFAS regulatory thresholds across multiple jurisdictions to anticipate reformulation costs and supply chain repositioning.
Market Dynamics
Multi-hazard garment consolidation is compressing procurement cycles as industrial buyers replace separate thermal, chemical, and mechanical protective inventories with single-coverall solutions certified to overlapping OSHA and GB standards.
Growth Catalysts
- OSHA permissible exposure limit enforcement:U.S. industrial employers face mandated equipment upgrades across manufacturing, construction, and chemical processing facilities, accelerating textile replacement frequency.
- Aramid fiber thermal performance:High-heat applications in steel, aluminum, and glass manufacturing extend product lifecycles while reducing total cost of ownership for protective coverall programs.
- China GB standards compliance:SAMR oversight and domestic certification requirements filter import access, redirecting procurement toward locally certified suppliers serving state-owned industrial enterprises.
Market Restraints
- Meta-aramid fiber supply concentration:Three producers control over 80% of global para-aramid capacity, creating input cost volatility and allocation risk during demand surges.
- PFAS regulatory friction:REACH restrictions and emerging U.S. state-level bans on per- and polyfluoroalkyl substances force reformulation of breathable chemical barriers without proven alternatives.
- Technical limitation in multi-hazard integration:Combining flame resistance, chemical permeation resistance, and ergonomic mobility in single garments requires trade-offs that degrade performance in extreme conditions.
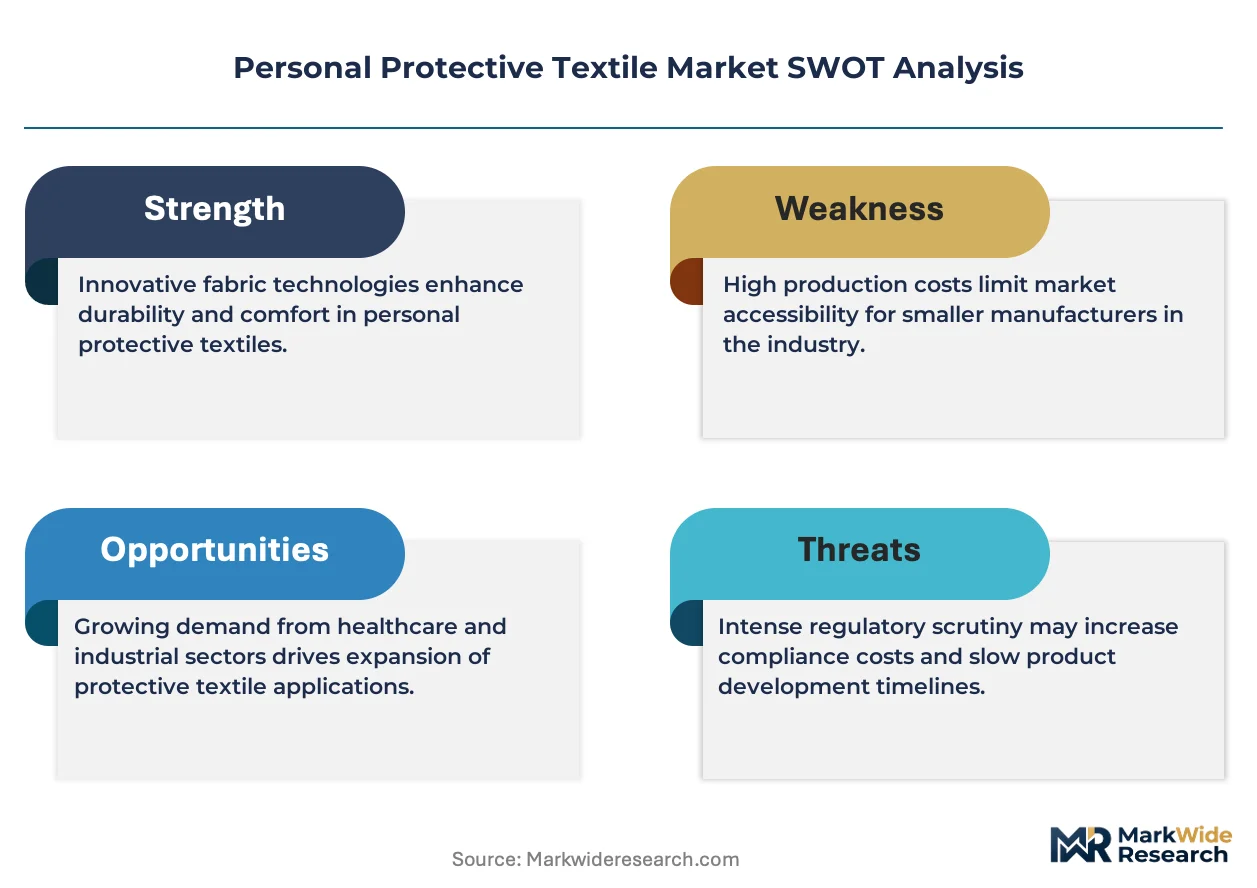
Strategic Opportunities
- India industrial safety expansion:BIS certification alignment with international standards opens procurement channels for export-oriented textile manufacturers serving domestic steel and petrochemical growth.
- Antimicrobial outpatient clinic adoption:Infection control protocols extend beyond hospital settings into long-term care and dialysis centers, creating demand for reusable protective apparel with verified biocidal properties.
- EU Green Deal material transition:Bio-based flame-retardant chemistries and recycled aramid feedstocks qualify for public procurement preferences and carbon accounting benefits in European industrial sectors.
Industry Challenges
- Certification timeline compression:Accelerated GB and OSHA standard revisions force manufacturers to maintain parallel testing programs across multiple jurisdictions with divergent sample requirements.
- Technical textile engineering talent scarcity:Specialized expertise in fiber-matrix interaction, coating adhesion, and garment pattern engineering concentrates in legacy industrial regions with limited training pipeline expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Protective Textile Market |
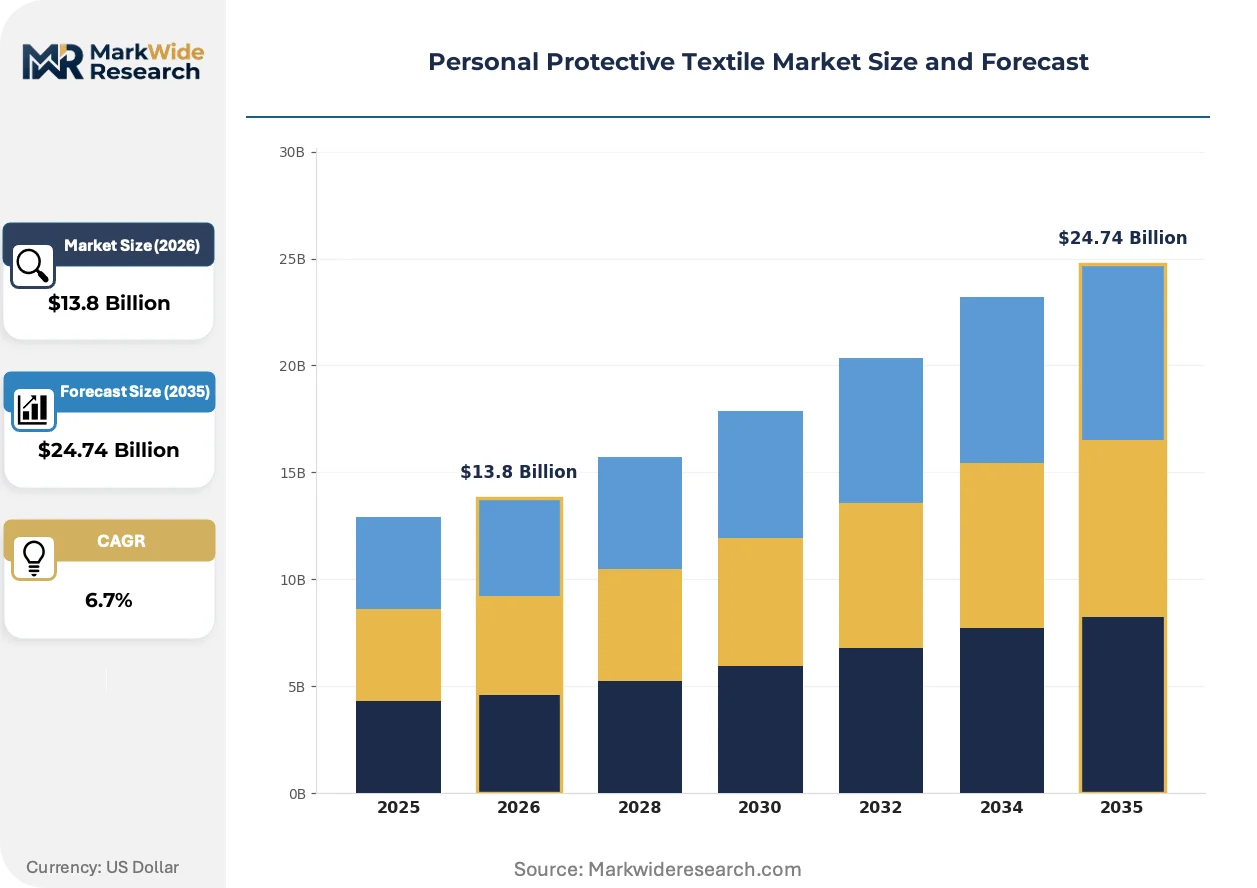
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.74 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coveralls, Gloves, Helmets, Aprons Material: Polyester, Aramid, Cotton, PVC Application: Construction, Healthcare, Manufacturing, Emergency Services End User: Industrial Workers, Medical Staff, Firefighters, Lab Personnel |
| Companies Covered | DuPont, 3M, Honeywell, Teijin Limited, TenCate Protective Fabrics, W. L. Gore & Associates, Milliken & Company, Ansell Limited, Lakeland Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Protective Textile Market Strategic Shifts & Innovations
Functional coating integration is displacing standalone membrane laminates as the dominant approach to breathable chemical protection, while digital specification tools compress buyer decision cycles.
Phase-change material microencapsulation is absorbing excess thermal energy in high-heat protective garments, extending safe exposure durations for foundry and smelter workers. Steel producers in Germany and the United States are piloting these textiles under ISO 11612 certification protocols. The technology is absorbing market share from traditional aluminized outer layers by reducing garment weight while maintaining radiant heat reflection performance.
REACH Annex XVII restrictions on halogenated flame retardants are forcing European manufacturers to reformulate polyester-cotton blends with phosphorus-based alternatives. Textile finishers face 18-24 month requalification timelines for existing CE-marked products. Industrial laundries serving the EU market are most affected, as new chemistries alter washing durability and require updated care label protocols.
Direct mill-to-end-user contracting is consolidating previously fragmented distributor relationships in North American industrial procurement. Safety managers at major chemical and energy operators now negotiate multi-year supply agreements with guaranteed volume tiers. This pattern is most visible in the U.S. Gulf Coast petrochemical corridor, where integrated operators seek supply security for flame-resistant coverall programs.
Personal Protective Textile Market Segmentation
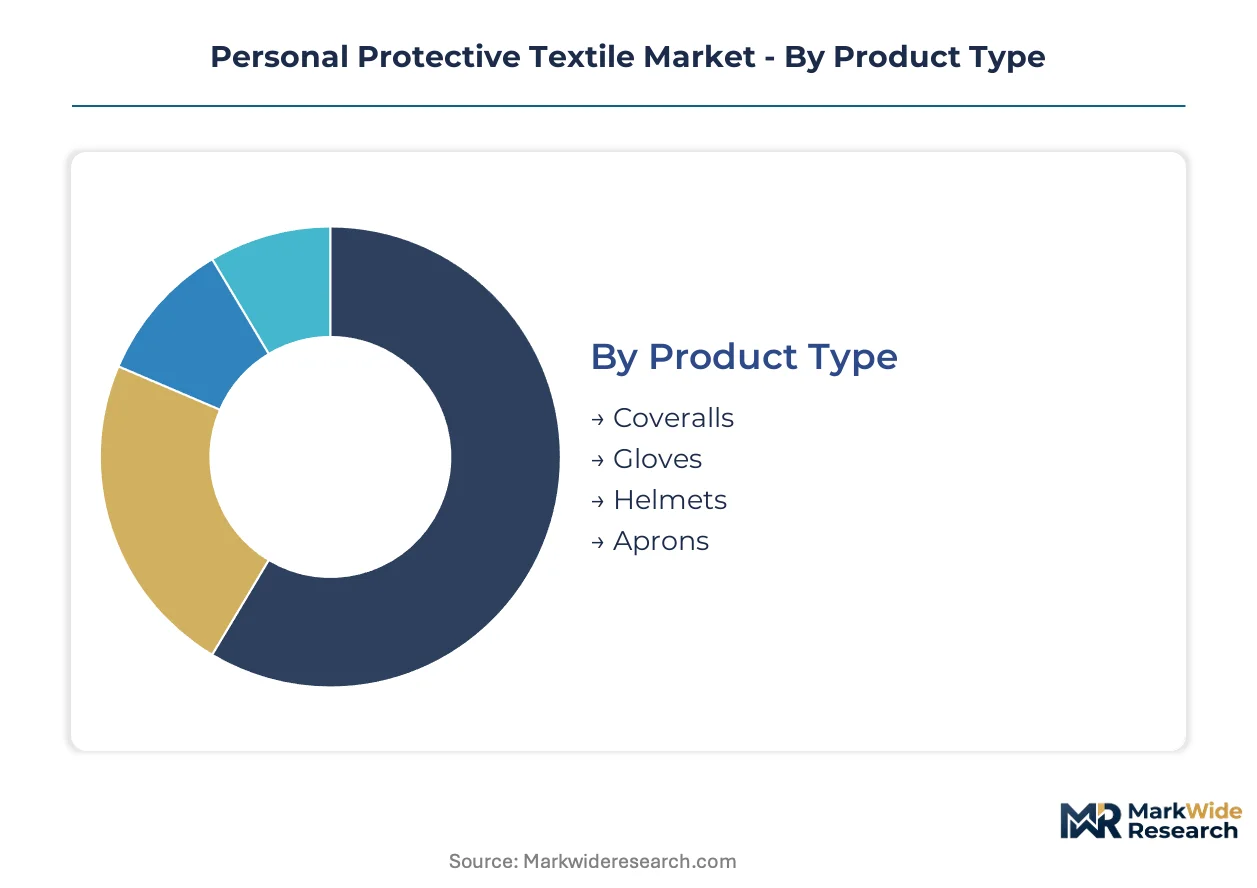
Personal protective textile procurement varies sharply by hazard exposure profile, with material specifications and garment configurations selected against precise regulatory thresholds. Understanding segment boundaries clarifies where technical differentiation commands premium positioning versus where cost-optimized specifications dominate purchasing decisions.
Product Type:
Standalone protective garments operate independently of external systems, while embedded textile components integrate into broader equipment platforms requiring interface compatibility.
- Coveralls:Multi-hazard designs consolidate thermal, chemical, and mechanical protection into single-garment solutions. Demand concentrates in U.S. petrochemical corridors and Chinese state-owned steel enterprises where OSHA and GB standards mandate full-body coverage.
- Gloves:Precision-engineered knit or dipped constructions balance tactile sensitivity with cut and chemical resistance. European automotive and electronics manufacturing drives specification upgrades under REACH-compliant chemistries.
- Helmets:Textile suspension systems and chin straps integrate with hard-shell protective headgear.
- Aprons:Frontal protection for splatter and spill scenarios in food processing and laboratory settings.
Volume placements concentrate in Coveralls; the faster expansion belongs to Gloves as precision manufacturing safety protocols tighten.
Material:
Cost tiers separate commodity synthetics from performance-engineered fibers with certified thermal or chemical resistance properties.
- Aramid:Meta-aramid and para-aramid structures deliver exceptional thermal stability and flame resistance for high-heat industrial environments. German steel foundries and U.S. aluminum smelters specify these fibers under ISO 11612 certification for extended safe exposure durations.
- Polyester:Cost-efficient synthetic base for general manufacturing protective apparel with FR treatments applied as secondary finishes. Volume procurement in Indian textile mills and Southeast Asian assembly operations prioritizes wash durability and colorfastness.
- Cotton:Natural fiber base for comfort-critical applications with inherent or treated flame resistance.
- PVC:Coated barrier construction for liquid chemical splash protection in cleaning and chemical handling operations.
Polyester captures the highest shipment volumes; Aramid claims the steepest expansion trajectory as high-heat industrial safety mandates strengthen.
Application:
End-use maturity determines whether procurement follows established specification patterns or responds to emerging regulatory triggers.
- Healthcare:Antimicrobial and fluid-resistant textiles for infection control in hospitals, outpatient clinics, and long-term care facilities. U.S. dialysis centers and European eldercare operators are expanding reusable protective apparel programs beyond acute care settings.
- Construction:High-visibility and cut-resistant textiles for building trades exposed to mechanical hazards and traffic proximity. Australian infrastructure projects and Canadian resource extraction sites specify retroreflective integrated fabrics under national work safety codes.
- Manufacturing:General industrial protection across automotive, electronics, and consumer goods assembly.
- Emergency Services:Multi-threat garments for firefighting, hazmat response, and search-rescue operations.
Manufacturing holds the largest installed base; Healthcare is climbing the fastest as post-acute care infection protocols proliferate.
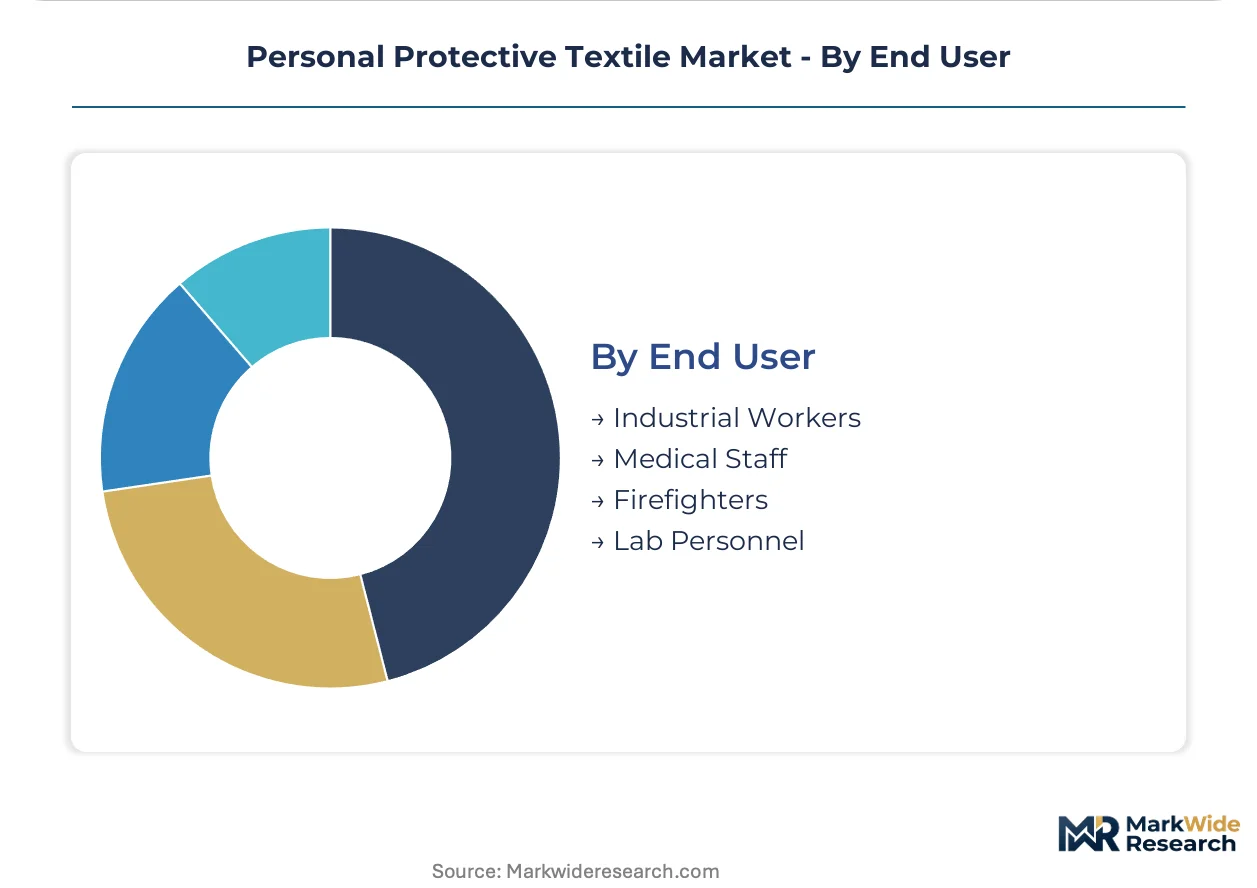
End User:
Customer type segmentation reflects distinct procurement authority structures and replacement cycle economics across occupational categories.
- Industrial Workers:Manufacturing, energy, and extraction personnel requiring daily-wear protective apparel with laundering durability. Brazilian mining operations and Saudi petrochemical complexes operate large-scale rental and industrial laundry programs with standardized garment pools.
- Medical Staff:Physicians, nurses, and technicians in clinical environments with protocol-driven textile specifications. Japanese hospital systems and South Korean outpatient networks are adopting reusable surgical textiles with verified barrier performance.
- Firefighters:Structural and wildland fire personnel with turnout gear and station wear requirements.
- Lab Personnel:Research and quality control technicians in pharmaceutical and chemical testing facilities.
Industrial Workers account for the dominant procurement volume; Medical Staff represents the segment gaining share fastest as outpatient clinic protective protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in China's Yangtze River Delta concentrate protective textile manufacturing capacity, attracting upstream aramid fiber suppliers and downstream garment finishers through tax incentives and streamlined GB standards certification.
United States
OSHA enforcement of permissible exposure limits drives replacement cycles for flame-resistant coveralls across Gulf Coast petrochemical complexes. The U.S. Department of Labor mandates employer-provided protective equipment under 29 CFR 1910.132. Houston-area integrated operators negotiate multi-year supply agreements with guaranteed volume tiers for industrial laundry programs.
Germany
REACH Annex XVII restrictions on halogenated flame retardants force textile finishers to reformulate polyester-cotton blends with phosphorus-based alternatives. ECHA oversight extends requalification timelines to 18-24 months for CE-marked products. Steel foundries in North Rhine-Westphalia pilot phase-change material microencapsulation under ISO 11612 certification protocols.
China
SAMR oversight of GB standards accelerates domestic certification requirements that filter import access for state-owned industrial enterprises. MIIT coordinates dual carbon goals with protective textile manufacturing upgrades. Yangtze River Delta clusters reshape procurement patterns as domestic scale advantages redirect sourcing toward locally certified suppliers.
India
BIS certification alignment with international standards opens procurement channels for export-oriented textile manufacturers. CDSCO oversight of medical protective textiles tightens as outpatient clinic protocols expand beyond acute care. Gujarat-based textile mills capture volume placements in general manufacturing protective apparel with cost-efficient polyester production.
Japan
METI promotes technical textile innovation through industrial safety equipment subsidies. JIS standards certification creates barriers for imported protective garments in domestic procurement. Kanto region hospital systems adopt reusable surgical textiles with verified barrier performance, extending infection control protocols from acute care into outpatient networks.
Personal Protective Textile Market Key Industry Players
Top-tier vendors anchor premium aramid fiber and membrane technology segments, while mid-scale regional fabricators compete on cost-optimized polyester blends and treated cotton. The vendor base stratifies across three functional tiers: integrated fiber-to-garment operators, specialized coating and finishing houses, and contract garment assemblers. Two dominant competitive moves are reshaping positioning: direct mill-to-end-user contracting that bypasses traditional distribution channels, and backward integration into captive aramid fiber supply to defend input cost stability.
Within the integrated fiber technology tier, DuPont and Teijin Limited occupy positions exemplifying aramid-based thermal protection leadership, while W. L. Gore & Associates anchors breathable membrane barrier specialization. These three entities represent distinct competitive archetypes: the diversified materials conglomerate with legacy fiber expertise, the Asia-Pacific-focused technical textile specialist, and the membrane technology pure-play. Their collective positioning illustrates how material science depth, rather than garment assembly scale, commands premium pricing in high-hazard industrial procurement.
| Leading Market Players |
|---|
| DuPont |
| 3M |
| Honeywell |
| Teijin Limited |
| TenCate Protective Fabrics |
| W. L. Gore & Associates |
| Milliken & Company |
| Ansell Limited |
| Lakeland Industries |
| Others |
Cost & Logistics Intelligence
U.S. Gulf Coast petrochemical operators anchor procurement volume through multi-year industrial laundry contracts, compressing spot market liquidity and entrenching contract-based pricing with guaranteed volume tiers. This buyer concentration amplifies pricing power for aramid-certified suppliers while squeezing margin flexibility for polyester blend competitors serving fragmented general manufacturing accounts.
Pricing Analysis
Short lead-time premiums of 15-25% apply to aramid-based coveralls for emergency replacement cycles in steel and aluminum smelters, while spot inventory discounts emerge for standard polyester blends in Southeast Asian textile mills. Three-tier pricing structure across premium aramid, standard treated polyester, and economy untreated cotton separates certification-grade thermal protection from basic mechanical coverage. Cost compression in the polyester tier intensifies as Indian mills expand spinning capacity and GB-certified Chinese suppliers redirect export volumes. Industrial Workers in Brazilian mining and Saudi petrochemical complexes exhibit highest price sensitivity due to standardized rental program economics, while Emergency Services procurement shows lowest sensitivity given performance mandates and replacement cycle rigidity.
Supply Chain Analysis
Freight cost volatility from Yangtze River Delta ports to European industrial laundries has compressed landed margins for membrane-laminated garments, accelerating regional finishing investments. Raw material supply concentrates in China for meta-aramid fiber and PTFE membrane substrates, with secondary dependence on U.S. para-aramid capacity and German chemical coating inputs. Single-source vulnerability in meta-aramid fiber—where three producers control over 80% of global capacity—creates allocation risk during demand surges in high-heat industrial sectors. Distribution runs through direct mill-to-end-user contracting in North America, while European and Asian markets retain industrial laundry and safety distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aramid fiber supply concentration constrains capacity expansion, propping pricing power for certified suppliers as OSHA and GB standard enforcement accelerates replacement frequency across high-heat industrial applications.
For Market Incumbents: To counter PFAS regulatory friction in breathable chemical barriers, prioritize backward integration into bio-based flame-retardant chemistry R&D and captive aramid fiber supply agreements with Teijin or DuPont. Secure multi-year GB certification maintenance contracts with Yangtze River Delta garment finishers to defend channel position against domestic Chinese competitors. For New Entrants and Emerging Players: REACH Annex XVII restrictions on halogenated flame retardants in Germany open a window for phosphorus-based chemistry specialists to capture reformulation demand from European textile finishers facing 18-24 month requalification timelines. Target India's BIS-certified industrial safety expansion, particularly Gujarat-based steel and petrochemical growth, with cost-optimized polyester-FR blends positioned below premium aramid tiers. For Investors and Strategic Acquirers: Distressed-cycle entries favor membrane technology specialists with ISO 11612 certification assets in Germany and the United States, where phase-change material microencapsulation pilots signal technology transition potential. Watch for OSHA permissible exposure limit expansion into outpatient healthcare settings as an inflection signal for antimicrobial protective textile demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Supply | Captive meta-aramid sourcing insulates margin volatility from three-producer concentration risk. |
| Bio-Based Flame-Retardant Chemistry Transition | EU Green Deal procurement preferences reward REACH-compliant phosphorus-based formulations in German steel foundries. |
| Direct Mill-to-End-User Contracting Expansion | Bypassing distributor layers captures pricing power in U.S. Gulf Coast petrochemical corridor procurement. |
| GB Standards Certification Pre-Positioning | SAMR oversight filters import access, favoring locally certified suppliers in Yangtze River Delta clusters. |
| Phase-Change Material Microencapsulation Scale-Up | ISO 11612-certified thermal energy absorption displaces aluminized outer layers in German and U.S. smelter trials. |
Research Approach
Independent corroboration across plant managers at German steel foundries, procurement leads at U.S. Gulf Coast petrochemical operators, and technical R&D directors at European textile finishers underwrites the qualitative findings. Secondary validation draws from OSHA enforcement records, REACH Annex XVII restriction filings, GB standards certification databases, and SEC 10-K disclosures from integrated fiber-to-garment operators. Bottom-up demand modeling across coverall, glove, and helmet product configurations triangulates against top-down market sizing from customs trade data and industrial laundry fleet estimates.
Comparable-period anchoring to pre-pandemic OSHA enforcement baselines and post-GB 2021 standard revision procurement patterns establishes the forecast reference framework across the analysis window. Segmentation dimensions include material tier (aramid, polyester, cotton, PVC), application vertical (healthcare, construction, manufacturing, emergency services), and end-user procurement structure (direct contract, industrial laundry, distributor). CAGR derivation incorporates fiber cost trajectory modeling, certification timeline compression effects, and replacement cycle frequency shifts under tightening exposure limits.
The model assumes a particular technology adoption path for phase-change material microencapsulation; alternative pathways for traditional aluminized thermal barriers would alter the outlook for high-heat garment weight reduction. Forecasts reflect assumptions about OSHA enforcement continuity, REACH restriction implementation timelines, and SAMR certification filtration intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Dry Suits Market
Protective and Workwear Textiles
Welding Curtains Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Uniforms and Workwears Market
Protective and Workwear Textiles
Winter Hats Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
Winter Wear Market