
 Dry Suits Market | 2026-2036
Dry Suits Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Suits Market Analysis
China is tilting toward expanded neoprene lamination capacity for marine exposure garments. Aqua Lung International leverages its integrated distribution network across North American dive centers. Johnson Outdoors Inc. anchors its position through sustained R&D spending on thermal protection systems. Henderson Group Limited specializes in custom-fit architectures for commercial and military buyers.
Dry suits are sealed, waterproof garments engineered from trilaminate or compressed neoprene assemblies with latex or silicone neck and wrist seals, designed to maintain a dry microclimate around the wearer during prolonged water immersion. Professional dry suits command premium pricing due to certification requirements and reinforced abrasion panels, while recreational dry suits represent the volume expansion tier as entry-level divers convert from wetsuits. Gore-Tex trilaminate materials lead the material segment for technical applications, whereas neoprene dominates rental fleets and training operations where durability and cost efficiency matter most.
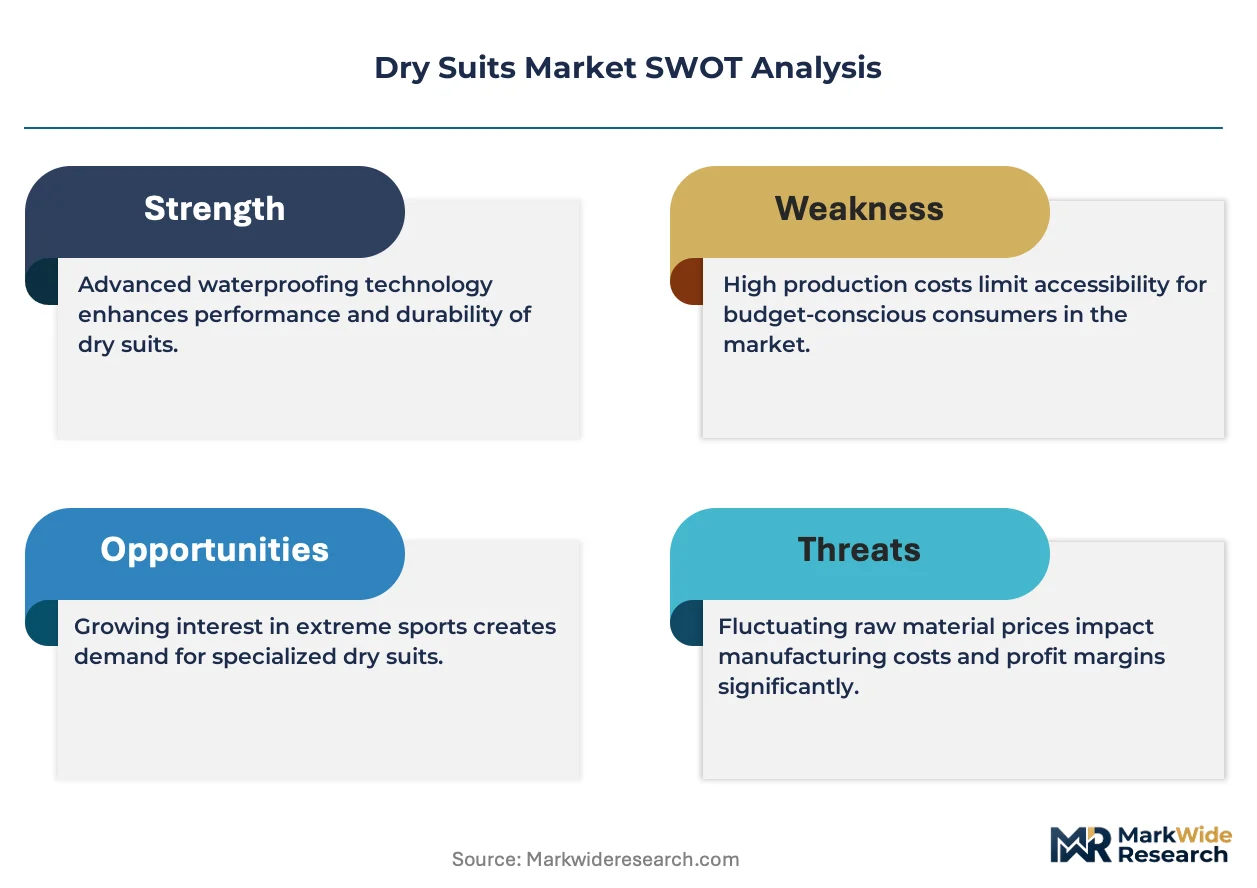
ISO 15027 and CE marking govern buoyancy and thermal protection standards in European markets, while the US Coast Guard influences cold-water survival equipment procurement for commercial vessels. The EU F-Gas Regulation indirectly shapes supply chains through restrictions on fluorinated polymer production inputs. Stakeholders must monitor how diver certification agencies revise thermal protection curricula, as training standards directly influence replacement cycles and upgrade demand across retail and institutional channels.
Market Dynamics
Expedition tourism expansion into polar and deep-wreck zones is compressing replacement cycles for thermal protection systems while forcing manufacturers to certify for mixed-gas technical diving protocols.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated polymer feedstocks are accelerating substitution toward bio-based membrane laminates, opening capacity for regional suppliers.
- Technical diving certification:PADI and TDI curriculum updates mandate dry suit training for wreck and cave specialties, institutionalizing upgrade demand across retail channels.
- Neoprene lamination clusters:Expanded manufacturing capacity in coastal China is reducing lead times for compressed neoprene assemblies serving rental fleet operators.
Market Restraints
- Latex seal price volatility:Natural rubber supply concentration in Southeast Asia exposes manufacturers to input cost swings that compress margin on entry-level suits.
- REACH compliance burden:ECHA substance restrictions on chemical treatments for waterproof breathable fabrics add certification overhead that disadvantages small European producers.
- Wetsuit substitution in warm-water training:Tropical dive markets default to 3mm neoprene wetsuits for cost and simplicity, capping dry suit penetration in certification pipelines.
Strategic Opportunities
- Arctic expedition tourism:Svalbard and Antarctic cruise operators are outfitting passengers with rental dry suits for zodiac operations, creating seasonal demand spikes.
- Smart thermal monitoring:Integration of biometric sensors with dry suit undergarments is enabling real-time core temperature tracking for commercial saturation divers.
- US Coast Guard mandates:Cold-water survival equipment requirements for commercial fishing vessels are expanding institutional procurement beyond recreational channels.
Industry Challenges
- Master pattern digitization:Custom-fit architecture requires skilled 3D scanning technicians that remain scarce outside established manufacturing hubs.
- CE marking timeline compression:ISO 15027 buoyancy testing protocols extend product development cycles, delaying seasonal launches and inventory positioning.
Report Scope
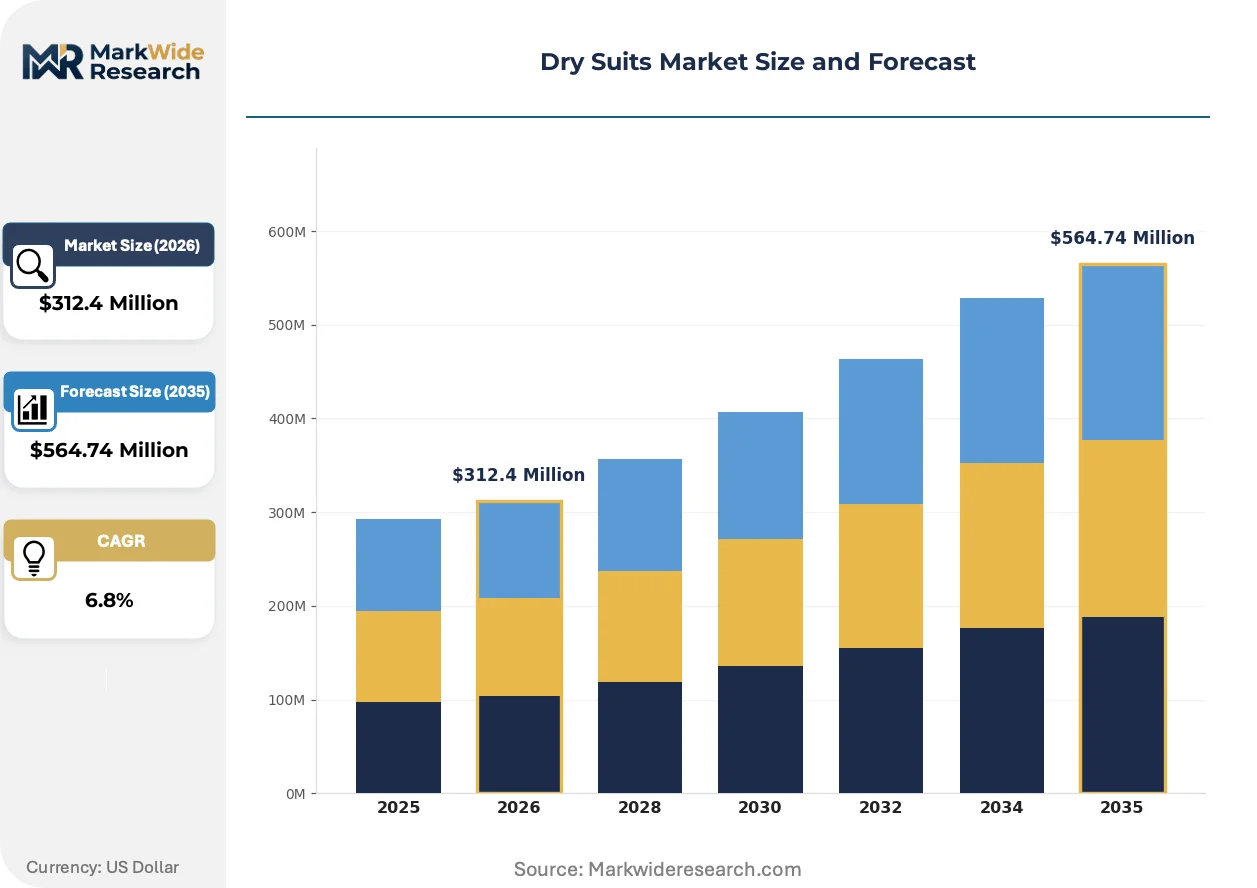
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Suits Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Dry Suits, Standard Dry Suits, Recreational Dry Suits, Professional Dry Suits Material: Neoprene, Gore-Tex, Nylon, Latex End User: Divers, Sailors, Water Sports Enthusiasts, Rescue Teams Application: Ocean Diving, River Rafting, Cold Water Survival, Surface Water Activities |
| Companies Covered | Aqua Lung International, Johnson Outdoors Inc., Cressi S.p.A., Mares S.p.A., Huish Outdoors, Bare Sports Ltd, Henderson Group Limited, Fourth Element Limited, Northern Diver International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Suits Market Emerging Trajectories
Digital fit customization and sustainable material substitution are converging to compress traditional manufacturing lead times while fragmenting the supplier base toward specialized component providers.
Trilaminate fabric construction is virtualizing the traditional cut-and-sew assembly model. Technical divers in the North Sea oil services sector are adopting made-to-measure suits configured through parametric design software. This shift is collapsing the distinction between stock inventory and custom production, enabling manufacturers to hold raw membrane rolls rather than finished garment SKU depth.
REACH substance restrictions are forcing reformulation of durable water repellent chemistries across European supply chains. Manufacturers are pivoting toward plasma-based surface treatments that eliminate perfluorinated compounds from Gore-Tex trilaminate assemblies. German and French producers face the steepest retooling costs, while Asian suppliers with less legacy equipment are capturing specification migration.
Direct-to-diver configuration platforms are disintermediating traditional dive center fitting rooms. Recreational buyers in the United States and United Kingdom are uploading body scan data to manufacturer portals, receiving tailored suits without intermediate retail markup. This channel compression is most visible among certified divers seeking replacement units, where fit confidence from prior ownership reduces the need for physical try-on.
Dry Suits Market Segmentation
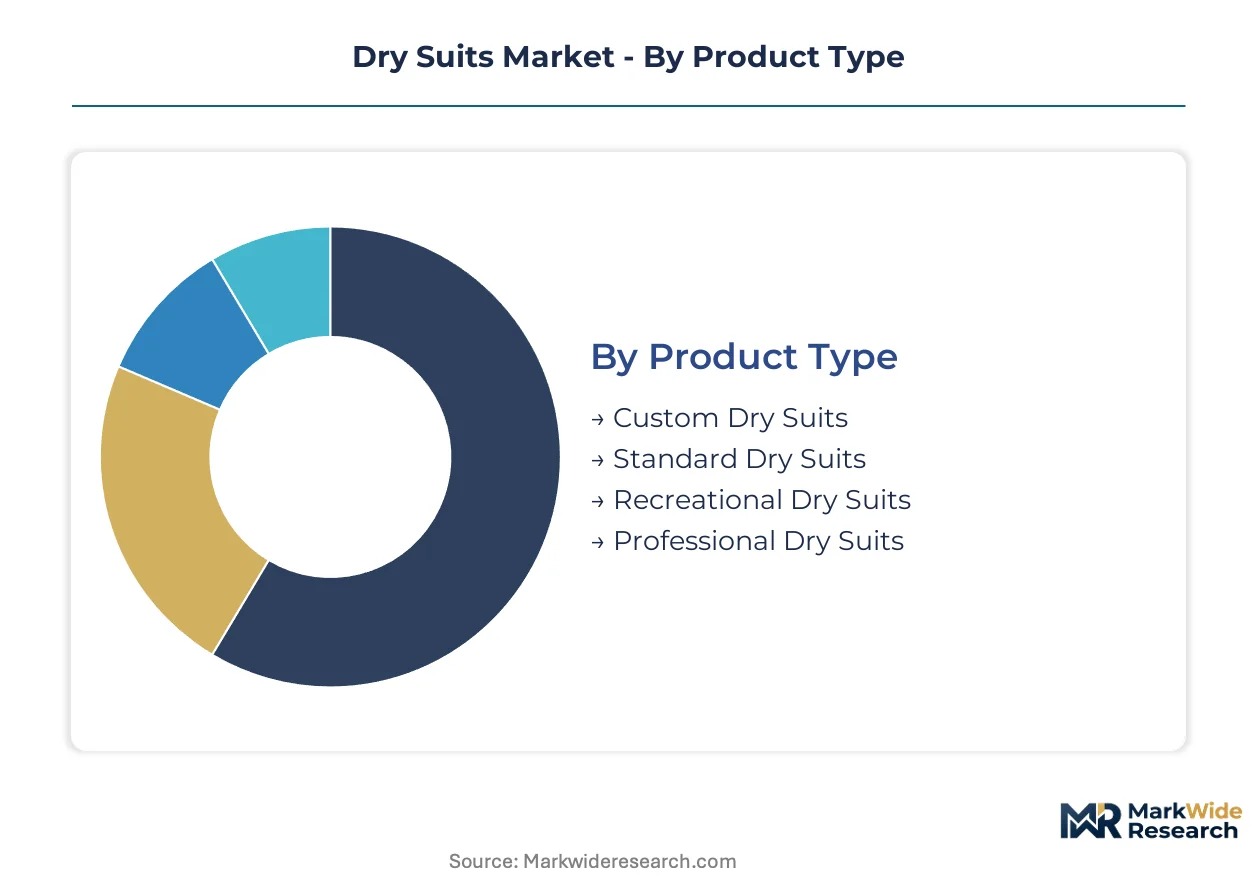
Dry suit segmentation reflects divergent performance requirements across certification grades, thermal environments, and institutional procurement channels. Manufacturers configure production lines around material laminates and seal architectures that map directly to end-use risk profiles and replacement cycle economics.
Product Type:
Mature commercial demand clusters around certified professional systems, while recreational conversion from wetsuits is accelerating volume tier expansion.
- Professional Dry Suits:Reinforced trilaminate or compressed neoprene assemblies with latex neck seals and integrated dry gloves, engineered for mixed-gas technical diving and saturation operations. Demand concentrates in North Sea oil services and commercial fishing fleets where OSHA cold-water exposure mandates drive institutional procurement cycles.
- Recreational Dry Suits:Entry-level compressed neoprene or membrane constructions prioritizing durability and simplified maintenance for rental fleets and certification training. PADI curriculum updates mandating dry suit specialties for wreck and cave diving are compressing upgrade timelines across United States dive centers.
- Custom Dry Suits:Parametric-fit architectures configured through 3D body scanning for technical divers requiring precise undergarment integration.
- Standard Dry Suits:Off-the-shelf sizing for cost-sensitive buyers and seasonal recreational users in temperate coastal zones.
Professional dry suits handle the majority of throughput; recreational dry suits are climbing the fastest on share.
Material:
Cost tier stratification separates premium membrane laminates from commodity neoprene serving high-volume rental channels.
- Gore-Tex:Expanded polytetrafluoroethylene membrane bonded to nylon face fabrics, delivering highest breathability ratings for extended immersion. REACH substance restrictions on perfluorinated compounds are forcing German and French producers toward plasma-based surface treatments, while Asian suppliers capture specification migration with cleaner production lines.
- Neoprene:Closed-cell foam rubber providing inherent thermal insulation and puncture resistance without supplemental undergarments. Coastal China lamination clusters are reducing lead times for compressed neoprene assemblies serving global rental fleet operators.
- Nylon:Lightweight shell fabrics for surface water activities where breathability requirements are reduced.
- Latex:Natural rubber seals and gaskets offering superior elasticity but exposed to Southeast Asian supply concentration and price volatility.
Gore-Tex commands the premium tier; neoprene moves the highest unit volumes through institutional channels.
End User:
Application intensity varies sharply between life-safety institutional procurement and discretionary recreational purchase patterns.
- Divers:Technical, commercial, and recreational submariners requiring thermal protection across depth and duration ranges. Expedition tourism expansion into polar zones is compressing replacement cycles for this segment.
- Rescue Teams:Swift-water and ice rescue units operating under US Coast Guard cold-water survival equipment mandates for commercial vessel compliance.
- Sailors:Offshore racing and cruising participants needing spray protection and immersion survival capability.
- Water Sports Enthusiasts:Kayakers, paddleboarders, and kiteboarders in temperate climates where dry suits extend seasonal activity windows.
Divers generate the deepest replacement cycles; rescue teams are gaining share fastest on regulatory procurement expansion.
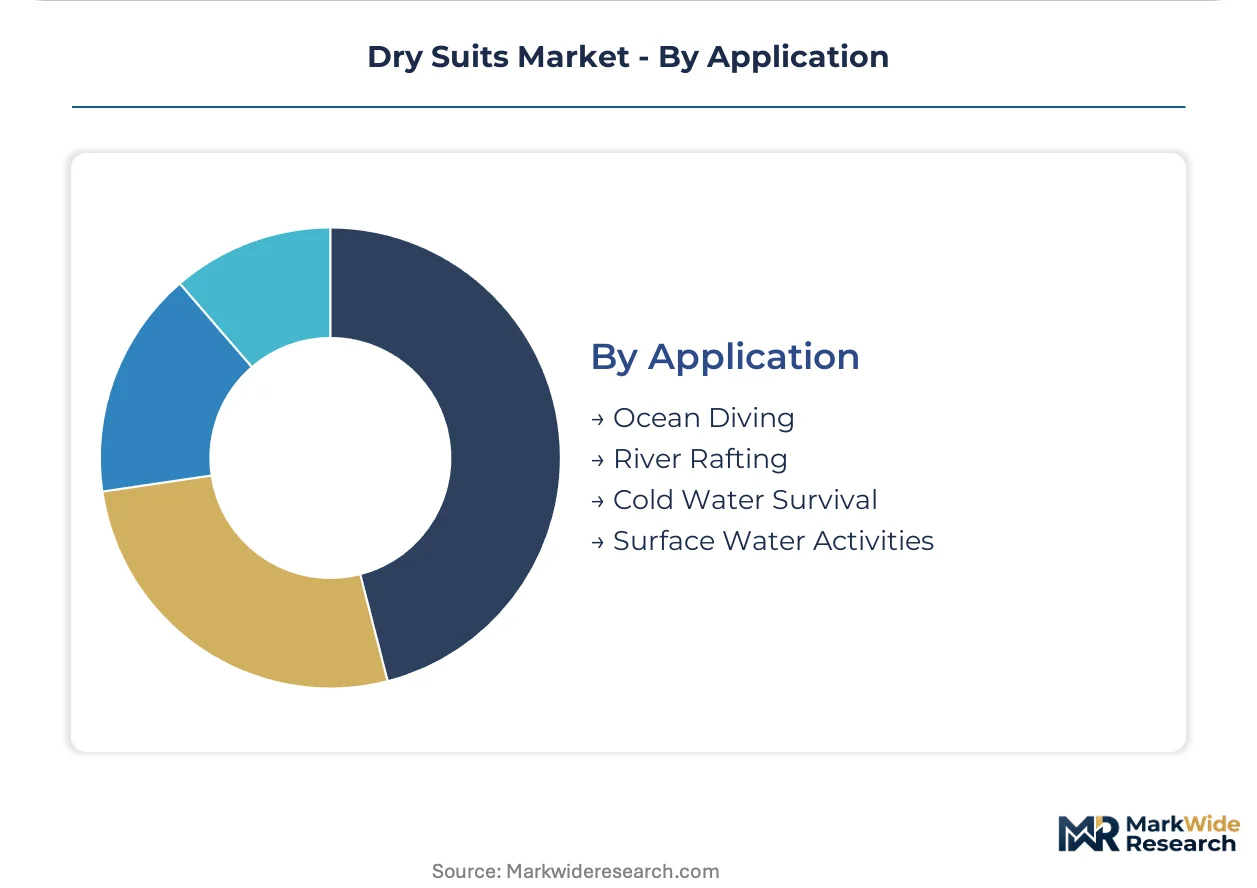
Application:
Geography determines thermal protection specifications, with cold-water environments mandating highest-performance configurations.
- Ocean Diving:Deep wreck, reef, and technical operations requiring redundant sealing and undergarment integration. Svalbard and Antarctic cruise operators are outfitting passengers with rental dry suits for zodiac operations, creating seasonal demand spikes in this category.
- Cold Water Survival:Commercial fishing vessel compliance under US Coast Guard regulations and offshore oil platform abandonment protocols. Institutional procurement channels here bypass retail markup and demand documented ISO 15027 buoyancy certification.
- River Rafting:Whitewater guiding and recreational paddling where abrasion resistance and quick-don capability prioritize different material tradeoffs.
- Surface Water Activities:Kayaking, sailing, and paddle sports where partial immersion and spray exposure dominate over full submersion scenarios.
Ocean diving absorbs the bulk of technical suit production; cold water survival is expanding most quickly on regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA cold-water exposure mandates anchor institutional procurement in the United States, while ECHA substance restrictions reshape European manufacturing economics. Coastal China lamination clusters compress lead times for compressed neoprene assemblies serving global rental operators.
United States
Technical diving certification pipelines and expedition tourism expansion into polar zones drive replacement cycle compression. US Coast Guard cold-water survival equipment mandates expand institutional procurement beyond recreational channels. The Pacific Northwest cold-water recreational diving infrastructure anchors mature distribution networks serving certified divers.
Germany
REACH compliance burdens and ISO 15027 buoyancy testing protocols extend product development cycles for domestic manufacturers. ECHA substance restrictions on perfluorinated compounds force reformulation of durable water repellent chemistries. Bavarian and Baden-Württemberg producers face steepest retooling costs as plasma-based surface treatments displace legacy processes.
China
Expanded neoprene lamination capacity in coastal manufacturing zones reduces lead times for compressed neoprene assemblies. MEE environmental standards and dual carbon goals reshape polymer feedstock sourcing for marine exposure garments. Yangtze River Delta and Pearl River Delta clusters capture specification migration from European suppliers burdened by legacy equipment.
United Kingdom
Direct-to-diver configuration platforms disintermediate traditional dive center fitting rooms for certified replacement buyers. CE marking timelines compress seasonal launch windows for manufacturers serving European markets. London and Southeast England concentrate demand from technical divers seeking parametric-fit architectures through 3D body scanning portals.
Australia
Tropical dive markets default to wetsuit substitution for warm-water training, capping dry suit penetration in certification pipelines. TGA-equivalent state-level equipment standards govern commercial diving operations in offshore resource sectors. New South Wales and Queensland coastal zones concentrate recreational diving infrastructure with limited cold-water thermal protection requirements.
Dry Suits Market Vendor Landscape
Integrated equipment conglomerates and specialized thermal protection fabricators split the market into distinct capability tiers. Consolidation pressure concentrates around certification-grade professional systems while entry-level recreational segments fragment across regional suppliers. Three archetypes dominate: vertically integrated dive equipment multinationals with captive distribution networks; neoprene lamination specialists serving high-volume rental channels; and custom-fit ateliers targeting technical diver specifications. Capacity expansion in Asian manufacturing clusters and strategic partnerships with certification agencies represent the dominant competitive moves.
Among integrated equipment conglomerates, Aqua Lung International and Johnson Outdoors Inc. exemplify archetypes combining captive distribution with sustained R&D positioning. Henderson Group Limited occupies a specialist tier focused on custom-fit architectures. These three anchors illustrate how geographic origin and corporate structure map to strategic positioning: Delaware-incorporated conglomerates leverage North American dive center networks; UK-based limited companies target commercial and military procurement channels.
| Leading Market Players |
|---|
| Aqua Lung International |
| Johnson Outdoors Inc. |
| Cressi S.p.A. |
| Mares S.p.A. |
| Huish Outdoors |
| Bare Sports Ltd |
| Henderson Group Limited |
| Fourth Element Limited |
| Northern Diver International |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta lamination clusters command disproportionate leverage over entry-level suit pricing through compressed neoprene assembly lead times. REACH compliance burdens and latex seal volatility upstream translate into tiered margin compression that separates premium membrane systems from commodity rental configurations.
Pricing Analysis
Asian-European price spreads widen as coastal Chinese capacity absorbs specification migration from legacy German producers. Three-tier pricing structure across professional certification-grade, recreational standard, and rental economy levels anchors the market, with ISO 15027 buoyancy certification and Gore-Tex membrane sourcing as primary differentiation drivers. Pricing pressure stems from Southeast Asian natural rubber supply concentration exposing seal-dependent manufacturers to input cost swings. Rental fleet operators exhibit highest price sensitivity, while saturation diving contractors for North Sea oil services accept premium positioning.
Supply Chain Analysis
Tariff exposure between United States and Chinese marine garment inputs dominates supply chain risk calculus for North American distributors. Manufacturing concentrates in coastal China, Germany, and the United Kingdom, with neoprene foam, polytetrafluoroethylene membranes, and natural rubber latex as critical feedstocks. Single-source vulnerability in Thai and Indonesian latex plantations threatens seal cost stability. Distribution runs through captive dive center networks for integrated equipment conglomerates, while direct-to-diver portals disintermediate replacement suit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry suit market dynamics favor incumbents through regulatory entrenchment, where ISO 15027 and CE marking timelines create certification moats that delay competitive replication.
For Market Incumbents: Harden certification-grade positioning by deepening captive supply of plasma-treated membrane laminates ahead of REACH perfluorinated compound phase-outs. Expand parametric-fit 3D scanning infrastructure in United Kingdom and Pacific Northwest clusters to capture technical diver replacement cycles. Defend against Asian neoprene specialists by anchoring institutional procurement relationships under US Coast Guard cold-water survival mandates. For New Entrants and Emerging Players: Build out direct-to-diver configuration platforms targeting certified recreational divers in United States and United Kingdom markets where fit confidence reduces physical try-on dependency. Arctic expedition tourism rental fleets represent the most penetrable white-space, with seasonal demand spikes from Svalbard and Antarctic cruise operators. Pursue smart thermal monitoring integration partnerships with commercial saturation diving contractors as differentiation anchor. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors custom-fit ateliers with parametric design capabilities over commodity neoprene assemblers. Long-term viability rests on regulatory compliance automation and membrane chemistry reformulation expertise. Acquisition targets should demonstrate established certification agency relationships and clean feedstock sourcing. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for European supplier retooling cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma-Based Surface Treatment Adoption | REACH perfluorinated compound restrictions force German and French producers toward cleaner chemistries. |
| Parametric 3D Fit Platform Launch | Direct-to-diver portals collapse inventory holding costs for technical replacement suit channels. |
| Arctic Expedition Rental Partnership | Svalbard and Antarctic cruise operators generate seasonal demand spikes for zodiac dry suit outfitting. |
| Smart Thermal Sensor Integration | Biometric monitoring enables real-time core temperature tracking for commercial saturation divers. |
| Neoprene Lamination Capacity Expansion | Yangtze River Delta clusters capture specification migration from European legacy equipment. |
Methodological Framework
The analysis maps professional certification-grade, recreational standard, and custom-fit parametric architectures, each validated through dive equipment procurement officers, certification agency curriculum directors, commercial diving safety managers, and marine exposure garment R&D leads. Primary interview intelligence triangulates against customs trade data for neoprene and membrane imports, SEC 10-K filings from integrated outdoor equipment conglomerates, ISO 15027 buoyancy testing protocol documentation, and ECHA substance restriction regulatory filings. Bottom-up unit economics for rental fleet depreciation cycles and top-down addressable market sizing from diver certification pipeline data converge through iterative reconciliation.
Assumptions held fixed include regulatory enforcement intensity for EU F-Gas and REACH frameworks, diver certification curriculum structures from PADI and TDI, and commercial vessel cold-water survival mandate scope from US Coast Guard. Variables include expedition tourism expansion velocity into polar zones, plasma treatment technology cost curves, and latex supply concentration resilience. Modeled segmentation spans product type, material laminate, end-user application intensity, and geographic regulatory cluster. CAGRs derive from replacement cycle compression analysis and certification pipeline conversion rates across recreational and technical diver archetypes.
Practitioners should monitor ECHA enforcement actions on perfluorinated compounds, Southeast Asian natural rubber harvest volatility, and PADI curriculum update cadence for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
Industrial Protective Fabrics Market
Protective and Workwear Textiles
Welding Curtains Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Sun Protective Clothing Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Uniforms and Workwears Market