
 Camouflage Suit Market | 2026-2036
Camouflage Suit Market Size, Share, and Industry Trends Forecast 2026-2036
Camouflage Suit Market Analytics
Turkey is rewriting regional supply dynamics through expanded textile manufacturing corridors near Izmir and Bursa. Propper International leverages vertical manufacturing control from fabric weaving to finished garment assembly across its North American plants. KUIU anchors premium hunting camouflage through direct-to-consumer channel dominance and alpine-specific pattern development. Taian BOWINS Garment Co., Ltd. competes on volume scale, supplying bulk military contracts across Asian defense ministries with standardized digital pattern specifications.
A camouflage suit constitutes a purpose-designed outer garment system employing engineered coloration, disruptive pattern geometry, and spectral signature management to reduce detection by human observers or electro-optical sensors. Modern iterations incorporate infrared-suppressive dyes, moisture-wicking substrates, and flame-resistant treatments to satisfy multi-threat operational requirements. Tactical Suits and Military Suits command the dominant value share, driven by sustained defense budget allocations for individual equipment modernization programs. Hunting Suits represent the fastest-expanding consumer segment, propelled by backcountry recreation participation and species-specific pattern licensing from North American wildlife agencies. Blend Fabrics lead material selection, combining nylon durability with cotton breathability to balance field longevity against thermal comfort during extended wear periods.
United States military procurement operates under Defense Federal Acquisition Regulation Supplement standards enforced by the Defense Logistics Agency, mandating Berry Amendment compliance for domestic textile sourcing. NATO Standardization Office protocols govern pattern interoperability across allied force structures, creating certification barriers for non-aligned suppliers. The EU Green Deal textile sustainability framework is pressing manufacturers toward recycled polymer feedstocks and perfluorinated chemical elimination in durable water repellent treatments. Stakeholders must monitor evolving multispectral threat detection capabilities and corresponding signature suppression investments to preserve product relevance against next-generation adversary sensor deployments.
Market Dynamics
Multispectral threat detection capabilities are forcing accelerated signature suppression investments across military procurement programs, compressing product development cycles and elevating technical certification requirements for suppliers.
Growth Catalysts
- NATO Standardization Office protocols:Pattern interoperability mandates across allied force structures create captive demand for certified suppliers, locking in multi-year procurement frameworks.
- Special Operations Command modernization schedules:Aggressive individual equipment refresh cycles in the United States sustain premium segment demand for next-generation concealment systems.
- EU Green Deal textile sustainability framework:Recycled polymer feedstock requirements and perfluorinated chemical elimination mandates are redirecting R&D investment toward compliant material platforms.
Market Restraints
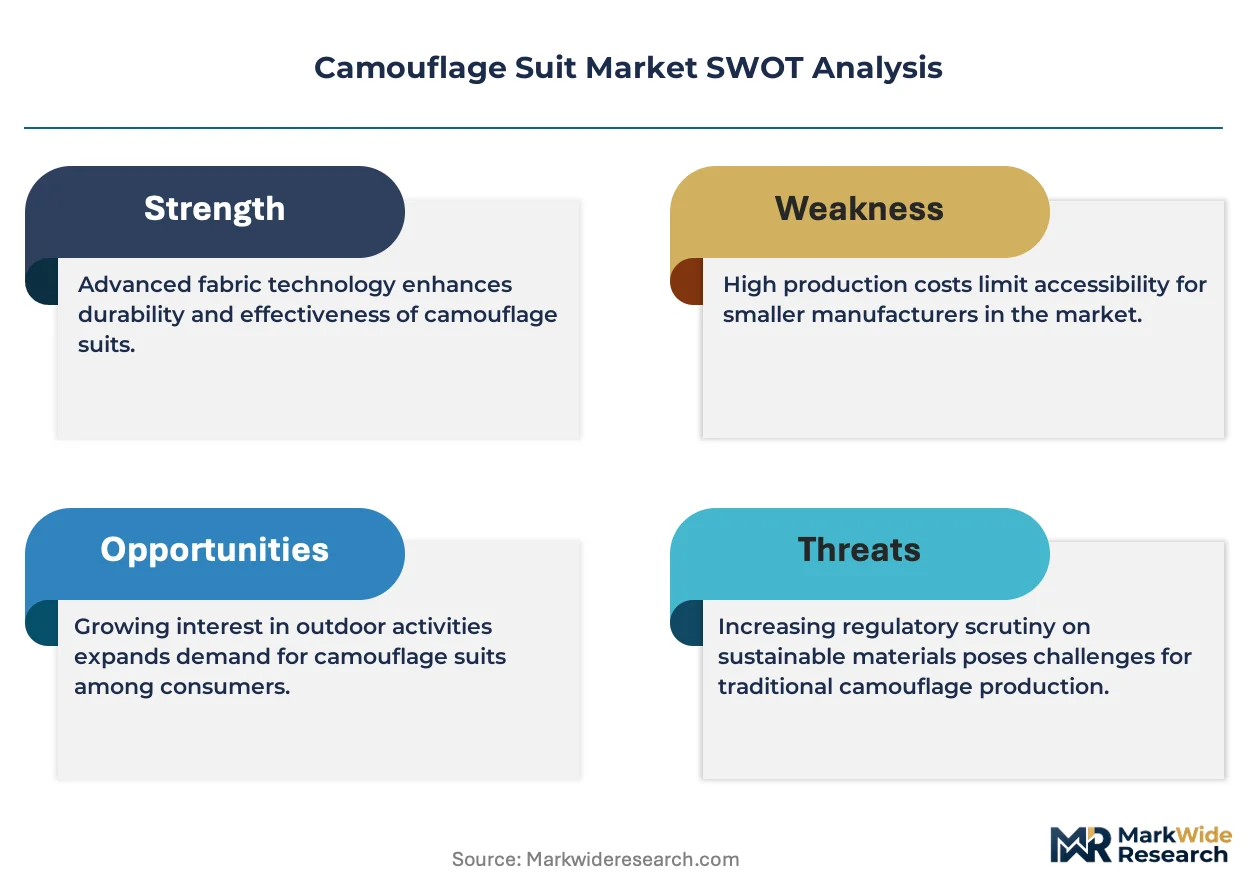
- Infrared-suppressive dye input costs:Specialized chemical feedstocks for near-infrared signature management face supply concentration among limited specialty chemical producers.
- Berry Amendment compliance:United States Defense Federal Acquisition Regulation Supplement standards enforce domestic textile sourcing, excluding lower-cost offshore alternatives from military contracts.
- Legacy woodland pattern substitution:Existing inventory amortization and training material sunk costs slow displacement of outdated concealment systems in reserve and training units.
Strategic Opportunities
- Backcountry recreation participation:Species-specific pattern licensing from North American wildlife agencies opens premium hunting suit segments with direct-to-consumer margin structures.
- Moisture-wicking substrate convergence:Integration of flame-resistant treatments with thermal comfort engineering creates dual-use platforms spanning military and commercial outdoor markets.
- Asian defense ministry bulk contracts:Standardized digital pattern specifications in procurement tenders favor volume-scale manufacturers with flexible production lines.
Industry Challenges
- Multispectral engineering talent scarcity:Cross-disciplinary expertise spanning textile chemistry, electro-optical physics, and garment engineering concentrates among defense contractor alumni pools.
- Certification timeline compression:NATO and national military laboratory testing protocols for pattern effectiveness against evolving sensor threats extend product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camouflage Suit Market |
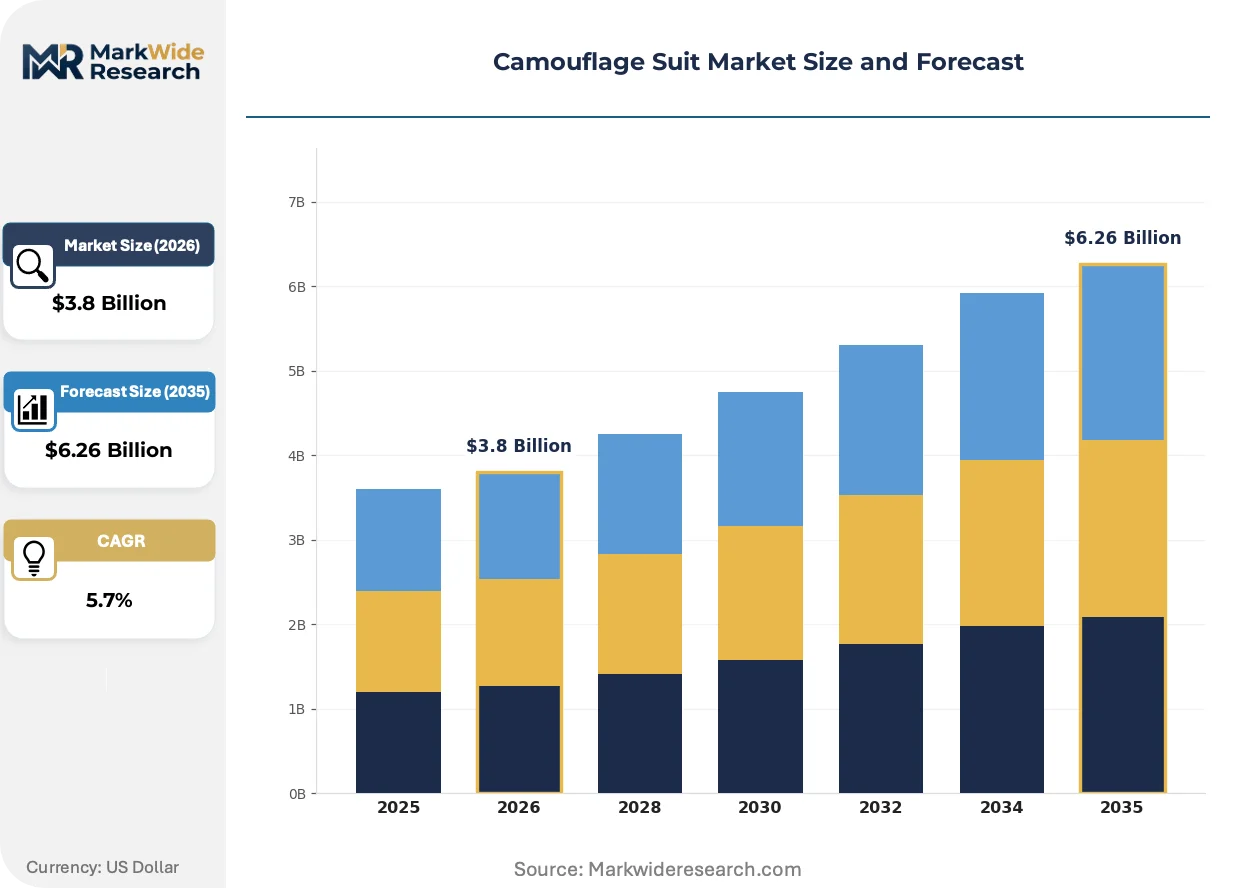
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tactical Suits, Military Suits, Hunting Suits, Outdoor Suits Material: Cotton, Polyester, Nylon, Blend Fabrics Use Case: Hunting, Military Operations, Wildlife Photography, Paintball End User: Military Personnel, Outdoor Enthusiasts, Law Enforcement, Private Security |
| Companies Covered | KUIU, Propper International, Taian BOWINS Garment Co., Ltd., 5.11 Tactical, Tru-Spec, Crystal International, Leelinesports, Rothco, Under Armour, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camouflage Suit Market Evolving Landscape
Active camouflage research and adaptive signature management are migrating from experimental programs toward fieldable prototypes, reshaping competitive investment priorities and supplier capability requirements.
Near-infrared suppressive fabric treatments are migrating from specialist military applications toward mainstream tactical and hunting segments. United States Special Operations units pioneered adoption of multispectral defeat technologies during the past decade. Commercial manufacturers are migrating from legacy dye chemistries toward compliant formulations that satisfy both military procurement standards and EU chemical safety frameworks.
REACH perfluorinated substance restrictions and EU Green Deal durable water repellent mandates are eliminating legacy chemical treatments from European supply chains. Manufacturers face reformulation investments or market exclusion from defense and civilian channels serving EU member states. Blend fabric producers with captive polymer recycling capabilities capture preferential positioning under emerging circular economy procurement criteria.
Direct-to-consumer channel dominance in premium hunting segments is compressing traditional wholesale-retail distribution structures. KUIU's alpine-specific pattern development and digital-native customer acquisition model demonstrates vertical brand control over design, manufacturing, and end-user relationships. North American backcountry recreation markets exhibit the most pronounced channel disintermediation, with military surplus and tactical retailers maintaining residual relevance for entry-level price tiers.
Camouflage Suit Market Segmentation
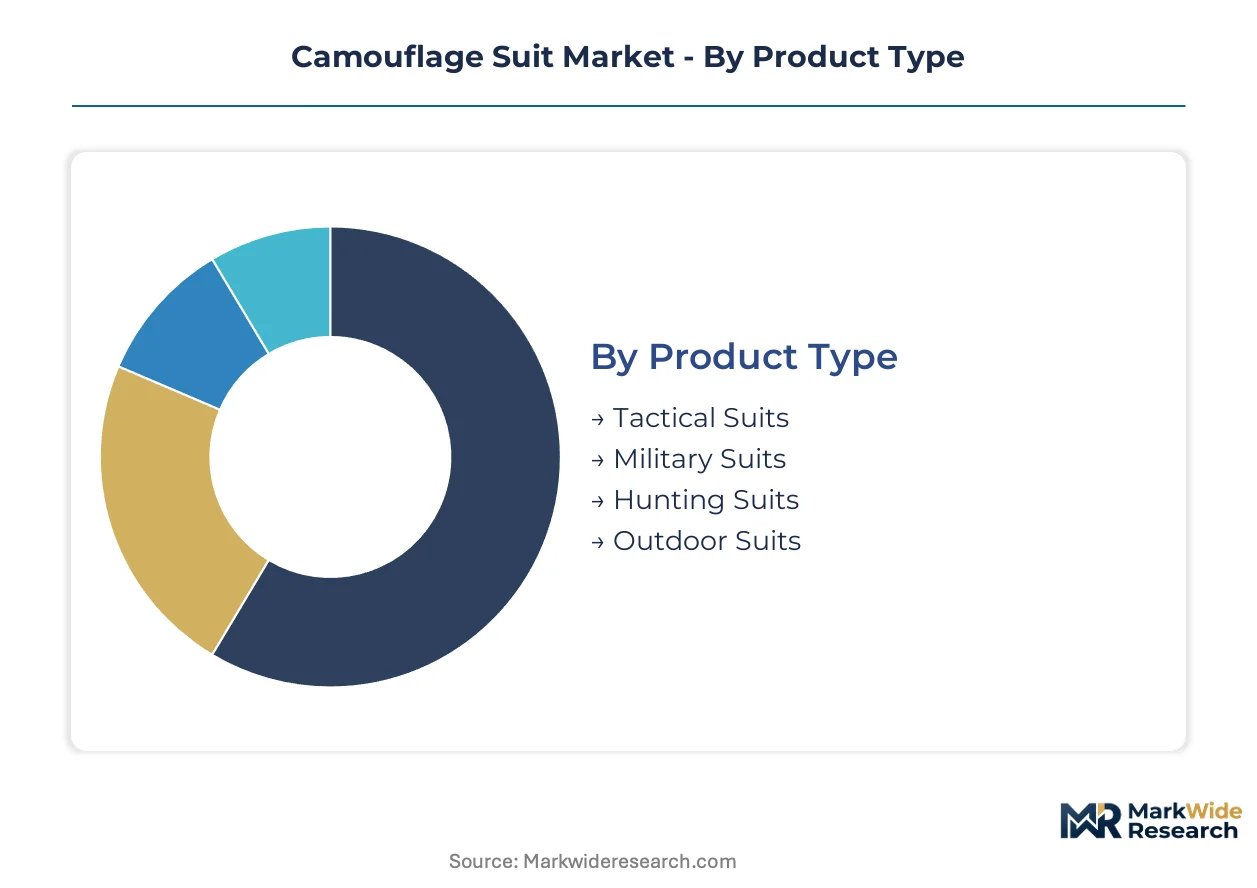
Segmentation in the camouflage suit market reveals distinct performance requirements across defense procurement and consumer outdoor channels. Each dimension—product architecture, substrate engineering, application environment, and user profile—carries unique certification barriers and margin structures that reshape supplier positioning.
Product Type:
Tactical and military applications demand multispectral signature suppression, while hunting and outdoor segments prioritize species-specific visual concealment and thermal comfort.
- Tactical Suits:Engineered with infrared-suppressive dyes and flame-resistant substrates to defeat near-infrared detection and thermal sensors. United States Special Operations Command maintains aggressive refresh schedules for these systems, locking in multi-year procurement frameworks with Berry Amendment-compliant domestic suppliers.
- Military Suits:Standardized digital patterns governed by NATO Standardization Office protocols ensure interoperability across allied force structures. Asian defense ministries issue bulk tenders favoring volume-scale manufacturers with flexible production lines.
- Hunting Suits:Alpine-specific pattern development and direct-to-consumer channel dominance characterize premium positioning.
- Outdoor Suits:General-purpose concealment for recreational users without specialized spectral requirements.
The dominant share belongs to Military Suits, while Hunting Suits are gaining share fastest through backchannel recreation expansion.
Material:
Substrate selection balances field longevity against thermal comfort, with regulatory pressure from EU chemical frameworks accelerating feedstock transitions.
- Blend Fabrics:Nylon-cotton combinations dominate procurement specifications by balancing abrasion resistance with breathability during extended wear. Recycled polymer feedstock capabilities now capture preferential positioning under EU Green Deal circular economy criteria.
- Nylon:High-tenacity synthetic base layers deliver durability in tactical load-bearing configurations.
- Cotton:Natural fiber comfort persists in training and reserve unit applications where spectral performance is secondary.
- Polyester:Moisture-wicking engineered fibers converge with flame-resistant treatments for dual-use military-commercial platforms.
Blend Fabrics command the installed base, though nylon formulations are climbing fastest on durability specifications.
Use Case:
Application environments dictate pattern geometry complexity and sensor threat profiles, from unaided human observation to electro-optical defeat.
- Military Operations:Multispectral threat detection capabilities force signature suppression investments across near-infrared, thermal, and radar bands. Certification timelines at NATO and national military laboratories extend validation cycles for pattern effectiveness.
- Hunting:Species-specific pattern licensing from North American wildlife agencies opens premium segments with direct-to-consumer margin structures and alpine terrain specialization.
- Wildlife Photography:Visual concealment without spectral requirements suits static observation at reduced price points.
- Paintball:Cosmetic pattern replication for recreational simulation without functional performance standards.
Military Operations absorb the largest procurement volume, while Hunting shows the steepest expansion trajectory on recreation participation growth.
End User:
Customer type determines compliance burden, with defense procurement enforcing domestic sourcing mandates that exclude offshore alternatives.
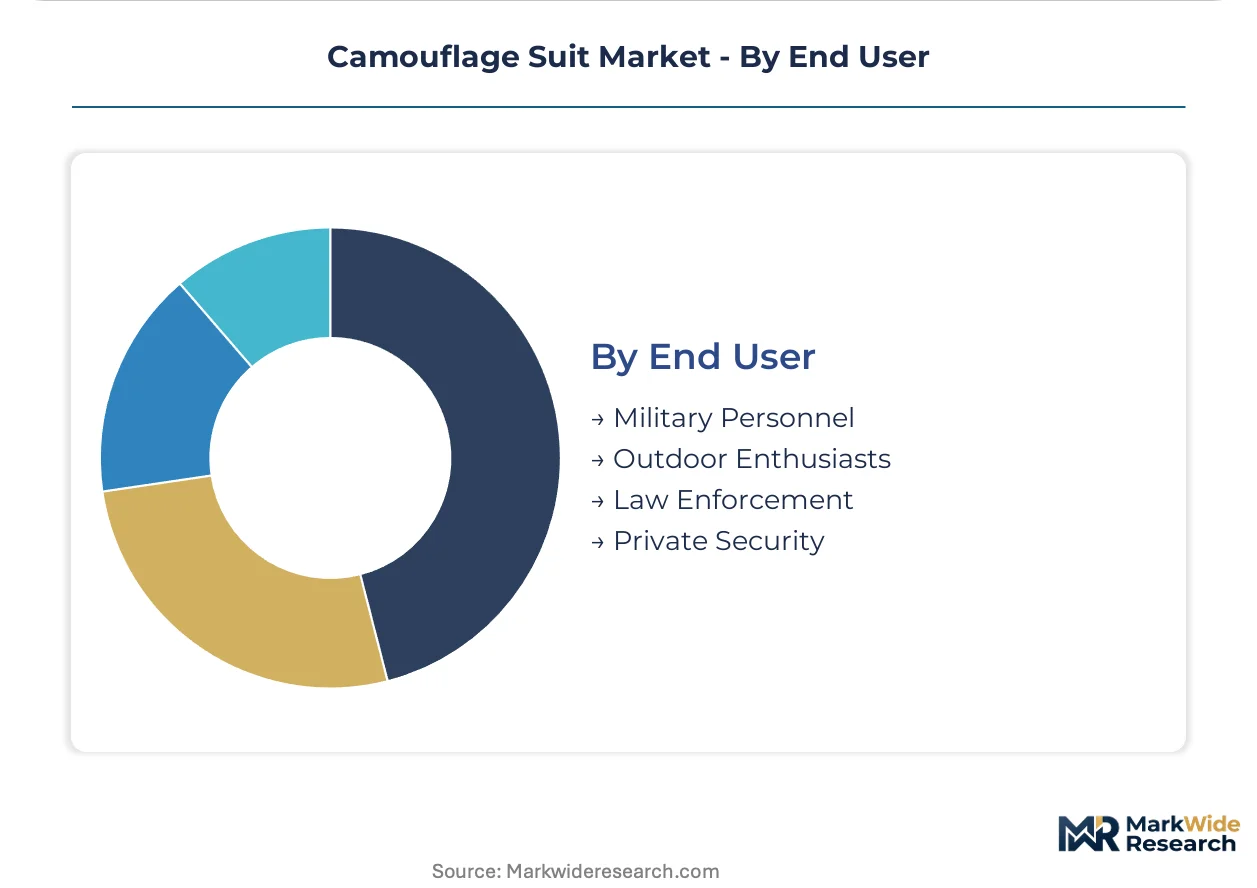
- Military Personnel:Defense Federal Acquisition Regulation Supplement standards mandate Berry Amendment compliance for domestic textile sourcing. Infrared-suppressive dye input costs concentrate among limited specialty chemical producers, elevating supplier qualification barriers.
- Outdoor Enthusiasts:Digital-native customer acquisition models demonstrate vertical brand control over design and end-user relationships in North American backcountry markets.
- Law Enforcement:Tactical pattern adoption without full military spectral certification requirements.
- Private Security:Commercial-grade concealment for protective details operating in varied threat environments.
Military Personnel represent the anchor customer, with Outdoor Enthusiasts expanding most quickly on channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense Federal Acquisition Regulation Supplement standards enforce Berry Amendment compliance for domestic textile sourcing in the United States. This regulatory framework anchors procurement patterns across NATO member states and shapes supplier qualification requirements in allied defense markets.
United States
Special Operations Command maintains aggressive modernization schedules for individual soldier equipment, sustaining premium segment demand for multispectral concealment systems. Defense Logistics Agency procurement operates under Berry Amendment domestic sourcing mandates that exclude offshore alternatives from military contracts. Manufacturing corridors in the Southeast and Southwest concentrate garment assembly operations with captive fabric weaving capabilities.
Germany
Bundeswehr equipment modernization programs drive demand for NATO Standardization Office-certified pattern interoperability. ECHA REACH perfluorinated substance restrictions are eliminating legacy chemical treatments from defense supply chains. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host specialized textile finishing operations for spectral signature management.
Turkey
Expanded textile manufacturing corridors near Izmir and Bursa are rewriting regional supply dynamics for bulk military contracts. National defense procurement agencies favor domestic suppliers under offset requirements tied to major weapons system acquisitions. The Aegean coastal region concentrates integrated fabric-to-garment production facilities serving Middle Eastern and Central Asian defense ministries.
China
Standardized digital pattern specifications in Asian defense ministry tenders favor volume-scale manufacturers with flexible production lines. MIIT guidelines on dual-use textile technologies govern export licensing for infrared-suppressive fabric treatments. Yangtze River Delta manufacturing bases supply bulk contracts across regional defense markets with cost-optimized production configurations.
United Kingdom
Ministry of Defence individual equipment refresh cycles sustain demand for next-generation concealment systems with thermal comfort engineering. CE marking requirements and EU-UK regulatory alignment debates create certification complexity for cross-channel suppliers. Midlands industrial corridors maintain legacy garment assembly capacity alongside emerging technical textile research clusters.
Camouflage Suit Market Competitive Landscape
Defense contractors and commercial outdoor specialists split the market along certification-tier lines. The vendor base concentrates among Berry Amendment-compliant domestic suppliers in North America and integrated textile manufacturers in Asia-Pacific. Three archetypes dominate: vertically integrated defense contractors with captive R&D, direct-to-consumer premium brands with pattern licensing control, and volume-scale bulk contractors serving standardized tenders. Competitive moves center on backward integration into polymer recycling capabilities and strategic partnerships with specialty chemical producers for compliant dye formulations.
Within the premium-tier vector, KUIU exemplifies direct-to-consumer channel dominance through alpine-specific pattern development. Propper International anchors the defense-contractor archetype with North American manufacturing control from fabric weaving to finished garment assembly. Taian BOWINS Garment Co., Ltd. occupies the volume-scale position, supplying standardized digital pattern specifications across Asian defense ministry bulk tenders.
| Leading Market Players |
|---|
| KUIU |
| Propper International |
| Taian BOWINS Garment Co., Ltd. |
| 5.11 Tactical |
| Tru-Spec |
| Crystal International |
| Leelinesports |
| Rothco |
| Under Armour |
| Others |
Value Network & Pricing Analysis
Berry Amendment domestic sourcing mandates determine both pricing tier spreads and supply chain shape, compressing cost-competitive offshore alternatives from military procurement channels while elevating premium positioning for compliant North American suppliers. This regulatory chokepoint fragments the market into certification-gated premium tiers and volume-scale standard tiers with divergent margin structures.
Pricing Analysis
United States military contracts command 40-60% premiums over Asian defense ministry tenders due to Berry Amendment compliance costs and domestic labor inputs. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified multispectral systems from standardized digital patterns and basic visual concealment. Cost compression in the standard tier is intensifying because Taian BOWINS and volume-scale competitors optimize flexible production lines for bulk tenders. Military Personnel exhibit lowest price sensitivity due to mandated procurement frameworks, while Paintball and entry-level Outdoor Enthusiasts drive economy-tier volume.
Supply Chain Analysis
MIIT guidelines on dual-use textile technologies and United States export control regimes for infrared-suppressive dyes limit cross-border flows of spectral signature management capabilities. Manufacturing gravity centers on Turkey's Izmir-Bursa corridor, China's Yangtze River Delta, and the United States Southeast-Southwest belt. Supply chains draw from specialty chemical producers for near-infrared suppressive feedstocks, nylon-cotton blend weavers, and flame-resistant treatment applicators. Single-source vulnerability concentrates in infrared-suppressive dye inputs from limited specialty chemical producers. Distribution runs through defense logistics agencies for military procurement and direct-to-consumer platforms for premium hunting segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pattern licensing and certification renewal services represent a recurring-revenue layer expanding faster than garment hardware, as NATO Standardization Office protocols and species-specific wildlife agency agreements require ongoing compliance maintenance and pattern refresh cycles.
For Market Incumbents: Entrench multispectral engineering capabilities through captive R&D investments and exclusive partnerships with specialty chemical producers for compliant dye formulations. Lock in multi-year NATO certification maintenance contracts to defend against emerging Turkish and Chinese volume-scale entrants. Prioritize backward integration into polymer recycling capabilities to capture preferential positioning under EU Green Deal circular economy procurement criteria. For New Entrants and Emerging Players: Pursue white-space opportunities in wildlife photography and law enforcement tactical segments where spectral certification requirements are reduced but pattern differentiation still commands margin. Target North American backcountry recreation markets through digital-native customer acquisition models that bypass traditional wholesale-retail distribution structures. Lead with species-specific pattern licensing partnerships with state wildlife agencies as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive fabric-to-garment production and certification credentials. Long-term viability rests on positioning against next-generation adversary sensor deployments and evolving EU chemical safety frameworks. Acquire targets with demonstrated NATO Standardization Office protocol compliance and established relationships with defense logistics agencies. Watch active camouflage research program funding levels as the inflection indicator for platform transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Multispectral Certification Investment | NATO Standardization Office compliance locks in multi-year procurement frameworks with allied defense ministries. |
| Backward Integration into Polymer Recycling | EU Green Deal circular economy criteria favor suppliers with captive recycled feedstock capabilities. |
| Direct-to-Consumer Channel Development | KUIU's digital-native model demonstrates vertical brand control over design and end-user relationships. |
| Specialty Chemical Partnership | Infrared-suppressive dye supply concentration elevates barriers for non-integrated competitors. |
| Species-Specific Pattern Licensing | North American wildlife agency agreements open premium hunting segments with recurring renewal revenue. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with defense procurement officers, textile R&D directors, and specialty chemical supply managers; and secondary validation through Defense Logistics Agency contract disclosures, NATO Standardization Office certification registries, and EU ECHA REACH substance restriction updates. Bottom-up triangulation across garment shipment volumes and top-down reconciliation against defense budget allocation patterns anchored market sizing.
Forecast inputs span product type segmentation across tactical, military, hunting, and outdoor suit architectures; material substrates from blend fabrics to engineered synthetics; and use case dimensions from multispectral military operations to species-specific hunting applications. CAGRs were derived from defense modernization schedule analysis and backcountry recreation participation trends across the projection horizon. NATO equipment refresh cycle timing and EU Green Deal compliance deadline phasing served as key industry-specific forecast inputs.
Sensitivities concentrate around Special Operations Command budget reallocation decisions, REACH perfluorinated substance restriction enforcement intensity, and active camouflage technology maturation timelines. Forecasts reflect assumptions about sustained NATO standardization protocols and continued Berry Amendment domestic sourcing mandates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
Industrial Hand Gloves Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Winter Hats Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
Personal Protective Textile Market
Protective and Workwear Textiles
Fabric Protection Market