
 Compression Garments Market | 2026-2036
Compression Garments Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Garments Market Analysis
Post-surgical patients are rotating toward athletic and fitness-oriented buyer archetypes as compression garments cross over from clinical settings to mainstream wellness. Bauerfeind leverages its German engineering heritage to dominate orthopedic-grade sleeve production. Medi GmbH & Co KG anchors its position through vertically integrated knitting operations that control yarn-to-garment quality. SIGVARIS competes across medical and sports channels with differentiated graduated-pressure protocols.
Compression garments are elastic textile products engineered to apply controlled mechanical pressure to limbs or torso, typically constructed from nylon-spandex blends with graduated compression gradients measured in millimeters of mercury (mmHg) to enhance venous return or reduce edema. Their primary commercial purpose spans post-operative recovery management, lymphedema prevention, athletic performance optimization, and chronic venous insufficiency treatment. Socks command the largest volume pool within product type segmentation due to standardized sizing and reimbursement eligibility, while sleeves capture premium margins from sports performance positioning. Nylon-spandex constructions lead material segmentation for medical-grade durability, though cotton blends are gaining traction in daily wear segments where skin breathability drives repeat purchase behavior.
FDA regulates medical compression garments as Class II devices requiring 510(k) clearance for therapeutic claims, while the EU MDR and CE marking framework impose stricter clinical evidence requirements on post-surgical and lymphedema applications. ISO 13485 quality management standards govern manufacturing processes for devices sold across multiple jurisdictions, creating compliance barriers for smaller knitters. Stakeholders must monitor how evolving reimbursement codes in Medicare and national health systems recalibrate the medical-sports pricing boundary.
Market Dynamics
The convergence of medical-grade compression with athletic performance positioning is restructuring competitive boundaries, as FDA Class II device requirements force sports-oriented entrants to either upgrade manufacturing protocols or retreat to wellness-adjacent claims.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter CE marking requirements under the EU Medical Device Regulation are elevating quality benchmarks and accelerating consolidation among subscale knitters unable to fund clinical validation.
- Post-surgical rehabilitation protocols:Hospital discharge planners in the United States and Germany are standardizing graduated compression wear for orthopedic and vascular procedures, embedding garments into bundled payment frameworks.
- Nylon-spandex technical knitting:Advances in circular knitting machinery enable finer graduated pressure gradients measured in precise mmHg increments, satisfying both athletic performance claims and therapeutic efficacy standards.
Market Restraints
- Petrochemical input volatility:Spandex fiber production depends on polyurethane precursors whose pricing fluctuates with crude oil derivatives, compressing margins for mid-tier manufacturers lacking long-term supply contracts.
- ISO 13485 certification barriers:The capital and timeline requirements for quality management system certification exclude smaller textile converters from medical channel access, concentrating supply among established device manufacturers.
- Reimbursement code fragmentation:Medicare's inconsistent coverage determination for compression garments across MAC jurisdictions creates pricing uncertainty that deters new market entry.
Strategic Opportunities
- Daily wear cotton blend segments:Consumer preference for breathable, skin-friendly materials in Japan and Germany is opening premium positioning for cotton-spandex hybrids that bridge medical function with lifestyle aesthetics.
- Direct-to-patient digital channels:Telehealth platforms and specialized e-commerce portals are bypassing traditional durable medical equipment distributors, capturing margin and patient data simultaneously.
- Japan's aging demographic acceleration:METI-supported preventive care initiatives are expanding compression garment access through community health programs, creating volume pools outside hospital procurement.
Industry Challenges
- 510(k) clearance timelines:FDA review backlogs for therapeutic claims are extending product launch schedules by 12-18 months, straining R&D amortization models.
- Gradient pressure calibration expertise:The specialized knowledge required for mmHg-accurate garment engineering is scarce, forcing manufacturers to compete for textile engineers with medical device backgrounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Garments Market |
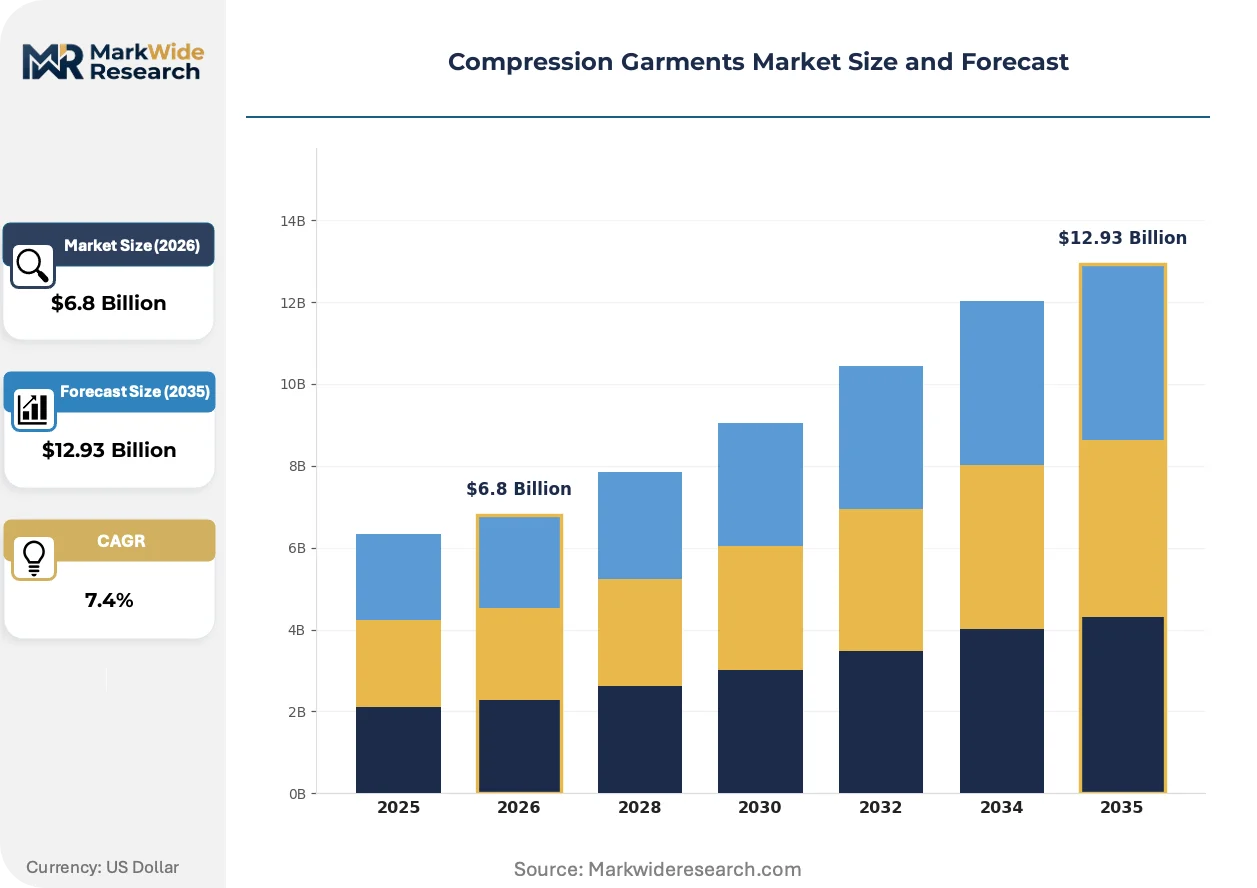
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shorts, Sleeves, Tops, Socks Application: Post-Surgery, Sports Performance, Medical Recovery, Daily Wear Material: Nylon, Spandex, Cotton, Polyester End User: Athletes, Patients, Healthcare Professionals, Fitness Enthusiasts |
| Companies Covered | 3M, Bauerfeind, Medi GmbH & Co KG, BSN Medical, SIGVARIS, Lohmann and Rauscher, Leonisa, Essity, The Marena Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Garments Market Emerging Trajectories
Material science advances and regulatory recalibration are converging to redefine how compression garments are manufactured, certified, and consumed across medical and wellness channels.
Smart textile integration with embedded pressure sensors is displacing passive garment categories in post-surgical monitoring applications. Hospital systems in Germany and the United States are piloting connected compression sleeves that transmit compliance data to clinical dashboards. This sensorization is compressing the traditional boundary between medical devices and consumer wearables.
EU MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate prospective evidence for lymphedema prevention claims. The burden falls heaviest on sleeve and stocking producers targeting post-mastectomy applications, driving partnerships with academic medical centers for registry studies. Smaller knitters without trial infrastructure are exiting therapeutic positioning entirely.
Subscription-based replenishment models are reshaping chronic condition management for venous insufficiency patients. Direct-to-consumer platforms in the United States are displacing quarterly DME supplier interactions with algorithm-driven sizing and automated replacement cycles. This channel pivot is most pronounced among Medicare Advantage populations where supplemental benefits cover over-the-counter compression purchases.
Compression Garments Market Segmentation
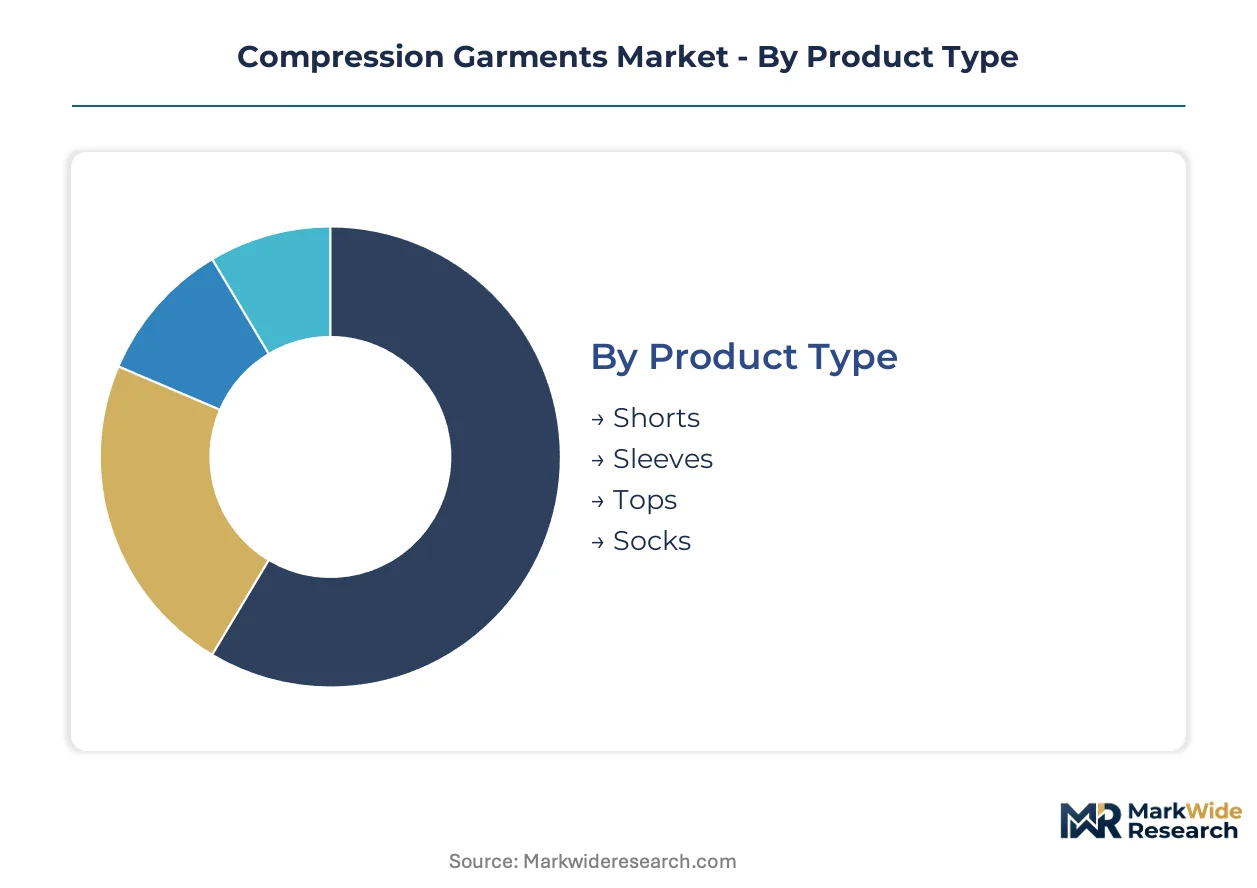
Compression garment manufacturers must navigate divergent technical specifications across medical and athletic channels, where FDA Class II device requirements collide with consumer wellness positioning. Segmentation strategy determines whether suppliers capture reimbursement-eligible hospital procurement or direct-to-consumer premium pricing.
Product Type:
Socks face the most intense substitution pressure from basic athletic hosiery, while orthopedic-grade sleeves defend differentiated positioning through mmHg-calibrated engineering.
- Socks:Knee-high and thigh-high constructions dominate standardized medical protocols with graduated pressure gradients from 15-20 mmHg for prophylaxis up to 30-40 mmHg for venous insufficiency management. Medicare reimbursement eligibility in the United States and statutory coverage in Germany's GKV system embed socks into chronic disease management pathways, though athletic compression socks from running specialty retailers erode pricing power in the wellness-adjacent segment.
- Sleeves:Arm and calf sleeves command premium positioning through sport-specific designs featuring zoned compression mapping for muscle stabilization during high-impact activity. NBA and Bundesliga training staff specify graduated-pressure protocols for post-game recovery, while post-mastectomy lymphedema applications require EU MDR-compliant clinical evidence under Article 10 evaluation mandates.
- Shorts:Hip and groin compression garments target cycling and running disciplines with chamois-integrated padding and moisture-wicking nylon-spandex constructions.
- Tops:Postural support shirts and chest compression vests serve post-surgical recovery and athletic training with torso-encircling pressure distribution.
Socks retain volume leadership through reimbursement infrastructure; sleeves hold the steepest expansion curve as sensorized monitoring applications penetrate hospital systems.
Application:
Cost tier stratification separates hospital-procured medical recovery garments from self-pay sports performance and daily wear categories.
- Medical Recovery:Post-operative and chronic venous insufficiency applications demand ISO 13485-certified manufacturing with batch-level pressure validation and 510(k) clearance for therapeutic claims in the United States. Hospital discharge planners in Germany and Japan are standardizing graduated compression into bundled payment frameworks for orthopedic and vascular procedures, locking in multi-year supply agreements with device manufacturers.
- Post-Surgery:Procedure-specific protocols for mastectomy, liposuction, and joint replacement require custom-fitted garments with adjustable closure systems and antimicrobial fabric treatments. EU MDR clinical evaluation requirements for lymphedema prevention claims are forcing manufacturers to fund prospective registry studies with academic medical centers in France and the Netherlands.
- Sports Performance:Athletic positioning emphasizes perceived recovery acceleration and muscle oscillation reduction without medical device regulatory burden, though FDA scrutiny of therapeutic claims is narrowing the wellness-medical boundary.
- Daily Wear:Consumer preference for breathable cotton-spandex blends in Japan and Germany is opening lifestyle-oriented positioning for preventive compression during prolonged standing or air travel.
Medical Recovery captures the highest average selling prices through procurement formalization; Post-Surgery is expanding most quickly as ambulatory surgical volume rises across OECD health systems.
Material:
Volume concentration in nylon-spandex technical knitting creates supply vulnerability to petrochemical input volatility, while cotton blend alternatives attract sustainability-conscious positioning.
- Nylon:Polyamide 6,6 and 6,10 yarns deliver the tensile strength and abrasion resistance required for medical-grade durability through 100+ wash cycles. Circular knitting machinery from Mayer & Cie and Santoni enables precise graduated pressure engineering with seamless toe closures for diabetic foot compliance.
- Spandex:Elastane fiber content typically ranges from 15% to 35% by weight to achieve specified mmHg gradients, with Invista Lycra and Hyosung Creora commanding premium positioning through supply security guarantees.
- Cotton:Natural fiber blends address skin sensitivity concerns in pediatric and geriatric populations, though moisture retention limits high-performance athletic applications.
- Polyester:Recycled PET yarns from ocean plastic recovery programs are penetrating daily wear segments in Germany and Japan where ESG procurement criteria influence retail buyer decisions.
Nylon dominates medical channel specification; cotton-spandex hybrids are gaining share fastest in direct-to-consumer lifestyle positioning.
End User:
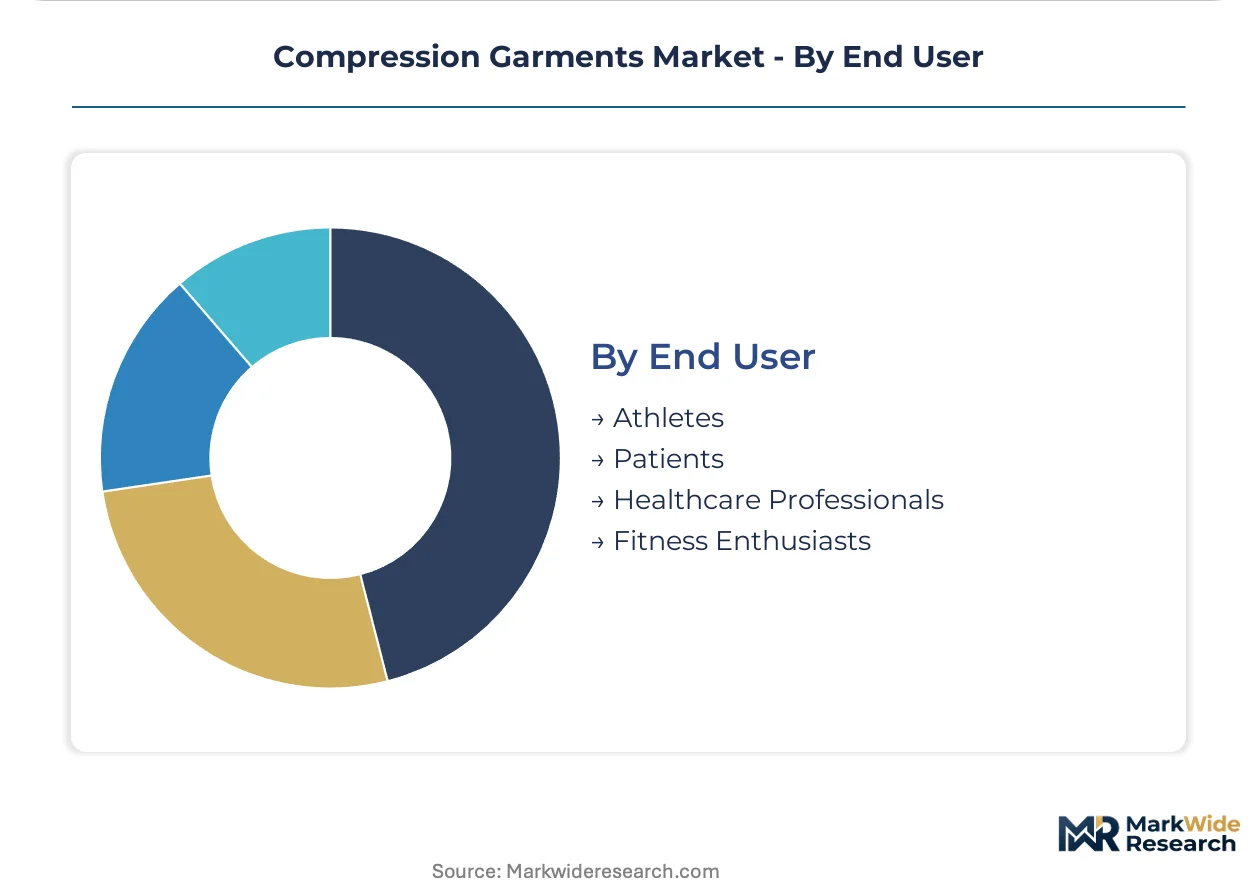
Customer type fragmentation demands parallel channel strategies, with healthcare professionals acting as gatekeepers for patient segments while athletes and fitness enthusiasts drive brand equity through social proof.
- Patients:Chronic condition management for venous insufficiency and lymphedema creates recurring replenishment demand, with Medicare Advantage supplemental benefits in the United States now covering over-the-counter compression purchases through specialized e-commerce portals.
- Healthcare Professionals:Vascular surgeons, lymphedema therapists, and orthopedic discharge planners function as prescription authorities whose protocol standardization decisions determine category access for device manufacturers.
- Athletes:Professional and amateur competitors prioritize perceived performance enhancement and post-exercise recovery acceleration, with NBA, NFL, and Bundesliga training staff influencing amateur purchase decisions through visible sideline use.
- Fitness Enthusiasts:Boutique studio participants and marathon training cohorts respond to influencer marketing and subscription-based replenishment models for graduated compression accessories.
Patients generate the most predictable revenue through chronic condition management; athletes provide the steepest volume expansion as compression crosses from clinical to mainstream wellness positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-surgical patients and sports performance teams concentrate demand in markets where aging populations intersect with high athletic participation rates. Hospital discharge planners and professional training staff now function as parallel buyer archetypes driving graduated compression adoption.
United States
Medicare Advantage supplemental benefits now cover over-the-counter compression purchases, expanding access beyond traditional durable medical equipment channels. FDA Class II device regulations enforce 510(k) clearance requirements for therapeutic claims, elevating compliance costs for market entrants. The Cleveland Clinic and Mayo Clinic clusters in Ohio and Minnesota pilot sensorized compression sleeves for post-operative monitoring.
Germany
Statutory health insurance (GKV) coverage embeds compression socks into chronic venous insufficiency management pathways. EU MDR Article 10 clinical evaluation mandates force manufacturers to generate prospective evidence for lymphedema prevention claims. The Rhine-Main region around Frankfurt hosts vertically integrated knitting operations controlling yarn-to-garment quality benchmarks.
Japan
METI-supported preventive care initiatives expand compression garment access through community health programs outside hospital procurement. Japan's national health insurance system reimburses medical-grade compression for specified venous conditions. The Kansai industrial corridor around Osaka concentrates circular knitting machinery manufacturers serving domestic and export markets.
United Kingdom
NHS England bundled payment frameworks for orthopedic procedures increasingly standardize graduated compression wear in discharge protocols. MHRA alignment with EU MDR post-Brexit maintains stringent clinical evidence requirements for therapeutic positioning. The East Midlands textile cluster retains specialized compression knitting capacity serving both medical and athletic channels.
Australia
Private health insurance ancillary coverage drives compression garment purchases for sports recovery and travel-related venous prophylaxis. TGA medical device regulations classify therapeutic compression as Class IIa, requiring conformity assessment procedures. Melbourne's medical technology precinct hosts distributors bridging European manufacturer supply with Asia-Pacific demand.
Compression Garments Market Vendor Landscape
Player mix skews toward established medical device manufacturers with ISO 13485 certification rather than textile converters lacking quality management infrastructure. Market structure concentrates among German engineering heritage firms and vertically integrated European knitters. Three archetypes dominate: orthopedic-grade specialists with clinical trial capabilities, sports-performance crossovers navigating FDA wellness-medical boundaries, and private-label suppliers serving pharmacy chains. Consolidation accelerates through acquisition of subscale knitters unable to fund EU MDR clinical validation, while strategic partnerships with academic medical centers secure registry study access.
Within the orthopedic-grade tier, Bauerfeind and Medi GmbH & Co KG exemplify engineering-driven positioning. SIGVARIS occupies a position spanning medical and sports channels with differentiated graduated-pressure protocols. These three anchors represent how regulatory compliance infrastructure—rather than manufacturing scale alone—determines competitive viability as quality benchmarks tighten across jurisdictions.
| Leading Market Players |
|---|
| 3M |
| Bauerfeind |
| Medi GmbH & Co KG |
| BSN Medical |
| SIGVARIS |
| Lohmann and Rauscher |
| Leonisa |
| Essity |
| The Marena Group |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification gates both supply qualification and price differentiation in the compression garments market, concentrating production among knitters with quality management infrastructure while segmenting pricing across medical-grade and wellness-adjacent tiers. This regulatory threshold simultaneously excludes subscale textile converters from hospital procurement channels and enables certified manufacturers to command premium positioning through batch-level pressure validation.
Pricing Analysis
Long-term offtake contracts with petrochemical suppliers index spandex fiber pricing to polyurethane precursor markets, creating cost-pass-through mechanisms that stabilize margins for tier-one manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical devices from CE-marked wellness products and unregulated athletic hosiery. Cost compression in the standard tier is intensifying because athletic compression socks from running specialty retailers erode pricing power. Patients with chronic venous insufficiency exhibit lowest price sensitivity due to Medicare reimbursement eligibility, while fitness enthusiasts demonstrate highest sensitivity to per-unit pricing in direct-to-consumer channels.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability fluctuations in the Hamburg-Rotterdam corridor elevate inbound logistics costs for German knitters dependent on Asian spandex fiber shipments. Manufacturing gravity centers on Germany, Japan, and the United States, where circular knitting machinery from Mayer & Cie and Santoni enables precise mmHg engineering. Raw material sourcing draws from Invista Lycra and Hyosung Creora for elastane content, alongside Polyamide 6,6 yarn suppliers in Germany and Japan. Single-source vulnerability concentrates in polyurethane precursor supply from Korean and Chinese petrochemical complexes. Distribution runs through durable medical equipment distributors for hospital channels, with direct-to-consumer platforms capturing growing share in lifestyle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compression garments market represents an early-cycle expansion story, with sensorized monitoring applications and subscription-based replenishment models driving penetration beyond traditional clinical settings into mainstream wellness management.
For Market Incumbents: Shield market position by accelerating backward integration into circular knitting machinery capacity in the Rhine-Main region, securing captive control over yarn-to-garment quality benchmarks against emerging sports-performance crossovers. Deepen ISO 13485 certification moats through investment in smart textile R&D for hospital system pilot programs, preempting FDA wellness-medical boundary scrutiny that threatens athletic entrants with therapeutic claims. For New Entrants and Emerging Players: Differentiate on cotton-spandex hybrid formulations targeting Japan's daily wear segment, where METI-supported preventive care initiatives expand access outside hospital procurement. The most penetrable white space sits in direct-to-patient digital channels for Medicare Advantage populations, where supplemental benefits now cover over-the-counter compression purchases. Pursue telehealth platform partnerships as the primary go-to-market angle, capturing patient data and margin simultaneously through algorithm-driven sizing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensorized compression sleeve manufacturing, as embedded pressure sensor integration and EU MDR clinical validation requirements demand sustained R&D commitment. Long-term viability favors acquisition of subscale knitters with established hospital system relationships but lacking trial infrastructure, positioning buyers to consolidate EU MDR-compliant production. Watch FDA 510(k) clearance timeline extensions as the critical inflection signal, as review backlogs stretching 12-18 months strain R&D amortization models and accelerate distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Validation Partnership | Academic medical center registry studies satisfy Article 10 evidence mandates for lymphedema prevention claims. |
| Sensorized Sleeve Development | Embedded pressure sensors transmit compliance data to Cleveland Clinic and Mayo Clinic clinical dashboards. |
| Direct-to-Consumer Platform Launch | Telehealth portals bypass DME distributors to capture Medicare Advantage supplemental benefit flows. |
| Backward Integration into Circular Knitting | In-house Mayer & Cie machinery deployment secures mmHg-accurate gradient engineering capacity. |
| Cotton-Spandex Hybrid Formulation | Skin-friendly material blends address pediatric and geriatric sensitivity concerns in Japan and Germany. |
Methodological Framework
A standing panel of vascular surgeons, lymphedema therapists, hospital discharge planners, and GPO contracts managers provided ongoing calibration against manufacturer production data and procurement database trends. Primary fieldwork combined structured interviews with biomedical engineers at German and Japanese knitting operations alongside secondary validation through FDA 510(k) filings, EU MDR Article 10 clinical evaluation summaries, CMS Medicare reimbursement code determinations, and hospital procurement contract databases. Bottom-up unit economics triangulated against top-down spending flow analysis across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for nylon-spandex fiber imports, circular knitting machinery shipment records from Mayer & Cie and Santoni, and statutory health insurance reimbursement statistics from Germany's GKV system. Segmentation modeling spanned product type, application, material composition, and end-user archetype across the projection horizon. CAGR derivation incorporated procedure volume growth in orthopedic and vascular surgery, athletic participation rate trajectories, and aging demographic elasticities. Forecast inputs included Medicare Advantage penetration curves and METI preventive care initiative budget allocations.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement code stability, petrochemical input price moderation, or FDA review timeline normalization would require recalibration. Forecasts reflect documented assumptions regarding hospital bundled payment framework expansion, EU MDR enforcement consistency, and sensorized garment adoption curves. Specific risk factors capable of revising projections include REACH regulation amendments affecting spandex fiber chemistry, single-payer system reimbursement retrenchment, and smart textile cybersecurity liability frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Dry Suits Market
Protective and Workwear Textiles
Personal Protective Textile Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Winter Hats Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Stain-Resistant Fabric Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
Winter Wear Market