
 Winter Wear Market | 2026-2036
Winter Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Winter Wear Market Outlook
REACH compliance is rebalancing material sourcing costs across European supply chains, forcing reformulation of perfluorinated water-repellent chemistries. VF Corporation leverages its vertical manufacturing footprint to absorb these transitions, while Patagonia differentiates through bluesign-certified supply chain transparency. Columbia Sportswear Company anchors its competitive position with proprietary Omni-Heat thermal-reflective technology.
Winter wear encompasses insulated, weather-resistant, and thermal-regulating garments engineered from layered constructions of wool, down, synthetic fibers, or fleece to maintain core body temperature in sub-zero environments; functional parameters include hydrostatic head ratings exceeding 10,000mm for waterproofing and fill power measurements above 600 for down insulation. Coats and jackets command the largest value pool as performance outerwear commands persistent premium pricing, while synthetic fibers represent the fastest-expanding material category as brands phase out virgin down and petroleum-derived alternatives improve warmth-to-weight ratios. Accessories lag in absolute revenue but carry disproportionate margin contribution due to lower size-driven return rates and impulse purchase dynamics.
EPA oversight of per- and polyfluoroalkyl substances in the United States, coupled with ECHA restrictions on persistent organic pollutants under REACH, is eliminating legacy DWR treatments and accelerating migration to bio-based and silicone alternatives. China's GB standards for textile safety and the EU's forthcoming Digital Product Passport requirements will further fragment compliance obligations across manufacturing footprints. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and locked capital in non-compliant material stocks.
Market Dynamics
EU Green Deal textile mandates are forcing wholesale reformulation of synthetic insulation and water-repellent chemistries, compressing margins for manufacturers dependent on legacy perfluorinated treatments while rewarding early movers into bio-based alternatives.
Growth Catalysts
- REACH compliance deadlines:ECHA restrictions on persistent organic pollutants are eliminating legacy DWR treatments and accelerating certified supply chain investments across European manufacturing footprints.
- Alpine tourism infrastructure:Cold-climate fitness activities and ski resort expansion in China are creating concentrated demand for performance outerwear among first-time winter sports participants.
- Synthetic fiber innovation:Advanced polyester and recycled nylon blends with improved warmth-to-weight ratios are displacing virgin down in insulated garment constructions.
Market Restraints
- Petrochemical input volatility:Crude oil price swings directly compress margins on synthetic insulation and polyester shell fabrics, exposing mid-tier brands to working capital strain.
- Dye process concentration:Wet processing capacity clusters in Zhejiang and Guangdong provinces, creating single-point vulnerability for color-treated winter wear supply chains.
- Technical performance ceiling:Bio-based water-repellent alternatives still fail to match the hydrostatic head ratings of fluorinated chemistries in extreme alpine conditions.
Strategic Opportunities
- Digital Product Passport readiness:EU regulatory requirements for traceability documentation create first-mover advantage for brands with blockchain-enabled supply chain visibility.
- Secondhand channel integration:Resale platforms and peer-to-peer marketplaces are opening margin-accretive revenue streams for certified pre-owned technical outerwear.
- GB standards alignment:China's textile safety regulations favor domestic manufacturers with compliant dye houses, creating partnership openings for foreign brands seeking local production.
Industry Challenges
- Bluesign certification backlog:Third-party chemical assessment queues are stretching to 14-18 months, delaying product launches for reformulated collections.
- Multi-jurisdiction compliance:Divergent EPA, ECHA, and SAMR chemical restrictions are fragmenting material stocks and complicating inventory planning across manufacturing footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Winter Wear Market |
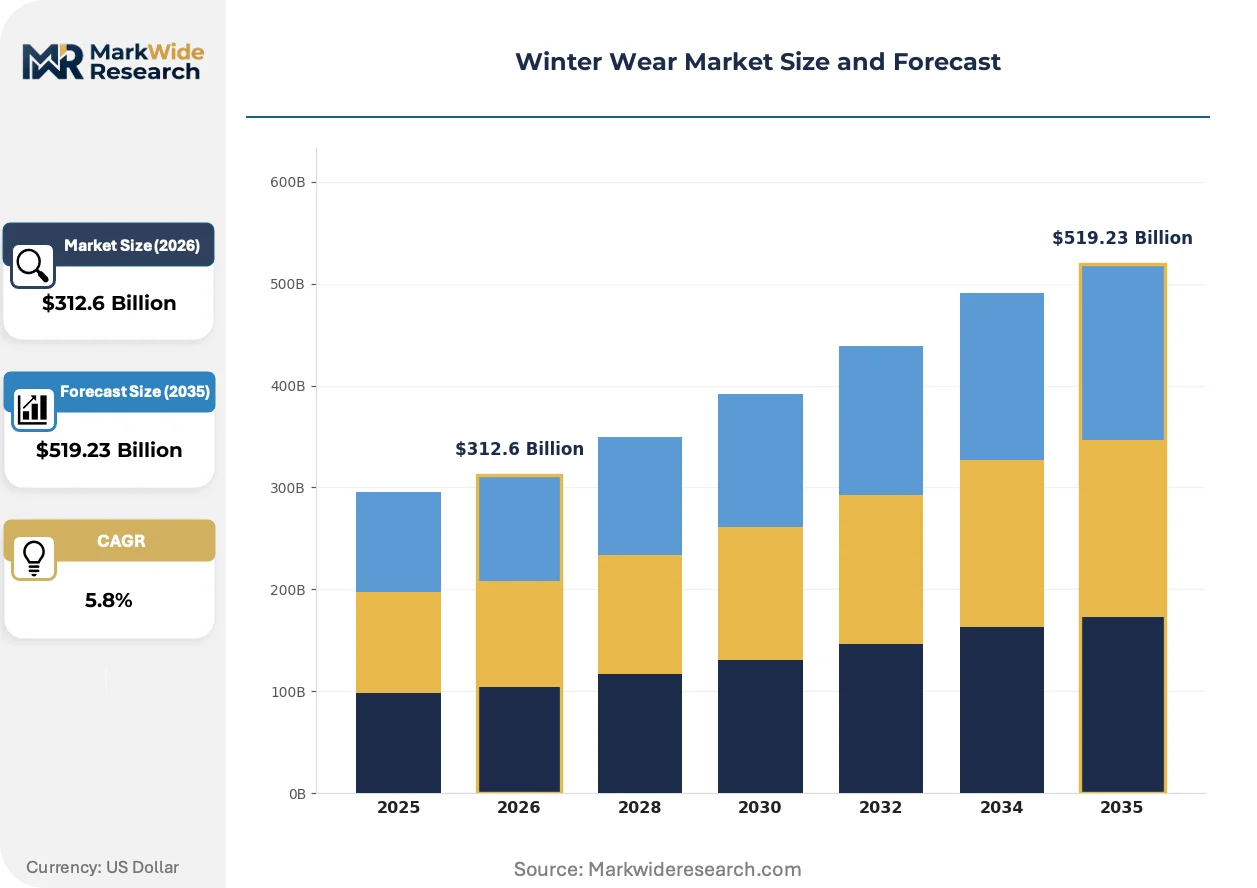
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coats, Jackets, Sweaters, Accessories Material: Wool, Down, Synthetic Fibers, Fleece Customer Type: Men, Women, Children, Unisex Price Tier: Luxury, Mid-range, Budget, Discount |
| Companies Covered | VF Corporation, Columbia Sportswear Company, Canada Goose Holdings Inc., Patagonia, Inc., Adidas AG, Nike, Inc., Inditex, Gap Inc., H & M Hennes & Mauritz AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Winter Wear Market Strategic Shifts
Material science breakthroughs and regulatory pressure are converging to reshape how thermal performance gets engineered, tested, and communicated to buyers across price tiers.
Aerogel-infused insulation is rewriting warmth-to-bulk ratios in technical outerwear. Mountaineering and backcountry ski segments are adopting these silica-based materials despite 40% cost premiums over synthetic alternatives. The technology is compressing the addressable market for traditional down fill above 800 fill power in professional-grade applications.
EPA oversight of per- and polyfluoroalkyl substances is eliminating C8 fluorocarbon water repellents from US-bound production. Manufacturers are pivoting to silicone-based and plant-derived DWR treatments, though performance degradation after 20 wash cycles remains unresolved. The outdoor performance segment bears the highest reformulation cost burden as durability expectations resist compromise.
Rental and subscription models are displacing outright ownership among urban consumers with intermittent cold-climate exposure. Specialty retailers in Nordic cities and North American mountain towns are piloting seasonal wardrobe programs. This behavioral shift is most pronounced among 25-34 year old buyers in Germany and Colorado who prioritize access over accumulation.
Winter Wear Market Segmentation
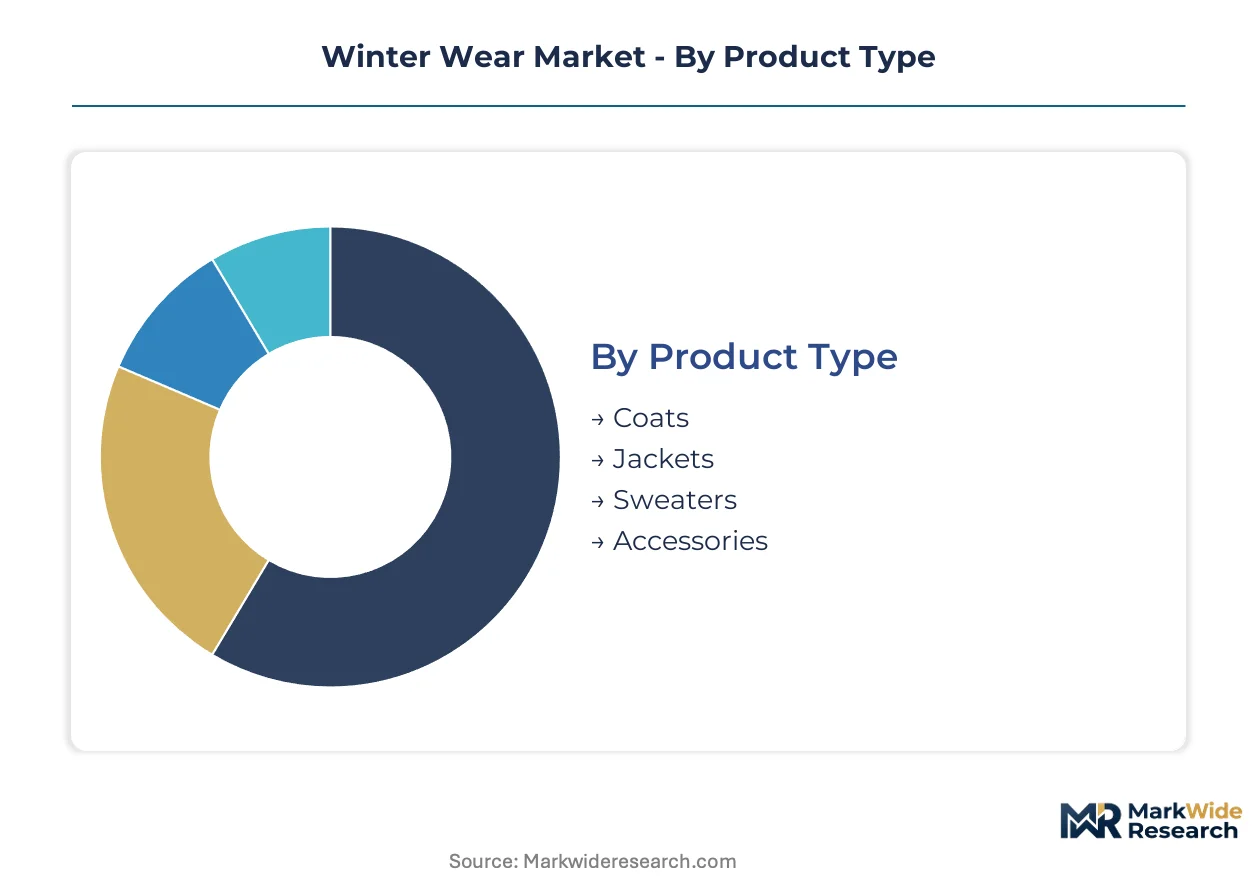
Winter wear segmentation reveals divergent capital requirements across product architectures, with thermal engineering complexity driving factory specialization and inventory risk concentration. Material sourcing decisions lock manufacturers into multi-year feedstock commitments that reshape margin exposure across price tiers.
Product Type:
Coats and jackets demand the heaviest upfront tooling investment due to taped seam machinery, waterproof membrane lamination, and fill power testing infrastructure.
- Coats:Full-length insulated constructions with hydrostatic head ratings exceeding 10,000mm require specialized bonding equipment and thermal chamber validation. Demand clusters in China's ski resort corridor as domestic alpine tourism infrastructure expands, though return rates spike 40% above category average due to fit sensitivity.
- Jackets:Technical outerwear with layered membrane systems and adjustable venting dominates professional-grade mountaineering applications. European REACH compliance deadlines are forcing wholesale reformulation of DWR chemistries, compressing margins for manufacturers dependent on legacy perfluorinated treatments.
- Sweaters:Knit constructions of merino wool or synthetic blends carry lower capital barriers but face compressed differentiation headroom.
- Accessories:Gloves, hats, and scarves require minimal specialized equipment yet generate disproportionate margin contribution through impulse purchase dynamics and size-driven return rate advantages.
Coats absorb the bulk of installed capacity; jackets are expanding most quickly.
Material:
Cost tier stratification runs sharpest here, with raw material positioning determining price band eligibility and regulatory compliance burden.
- Synthetic Fibers:Advanced polyester and recycled nylon blends with improved warmth-to-weight ratios are displacing virgin down in insulated constructions. China's GB standards for textile safety favor domestic manufacturers with compliant dye houses, creating partnership openings for foreign brands seeking local production.
- Down:Fill power measurements above 600 define premium positioning, though EPA oversight of PFAS and ECHA restrictions on persistent organic pollutants are eliminating legacy water-repellent treatments. Supply concentrates in Eastern European and Chinese processing clusters with long certification queues.
- Wool:Merino and cashmere variants serve luxury price tiers with natural moisture-wicking properties.
- Fleece:Recycled PET constructions anchor mid-range performance positioning with lower environmental compliance costs.
Synthetic fibers command the steepest expansion trajectory; down retains premium price anchoring despite regulatory pressure.
Customer Type:
Volume concentration and margin structure diverge sharply across demographic targeting, with sizing complexity driving return rate economics.
- Women:Fashion-forward styling requirements and fit variation across body types necessitate broader SKU proliferation. Demand concentrates in urban Nordic and North American markets where rental and subscription models are displacing outright ownership among 25-34 year old buyers.
- Men:Technical performance prioritization supports higher average selling prices in alpine and backcountry segments. China's winter sports infrastructure expansion is creating concentrated demand among first-time male participants seeking durable entry-level kit.
- Children:Rapid size turnover drives replacement purchase frequency but compresses per-unit margin.
- Unisex:Simplified sizing reduces inventory risk for direct-to-consumer brands with limited retail footprint.
Women's lines absorb the bulk of installed capacity; unisex positioning is climbing the fastest among digitally native entrants.
Price Tier:
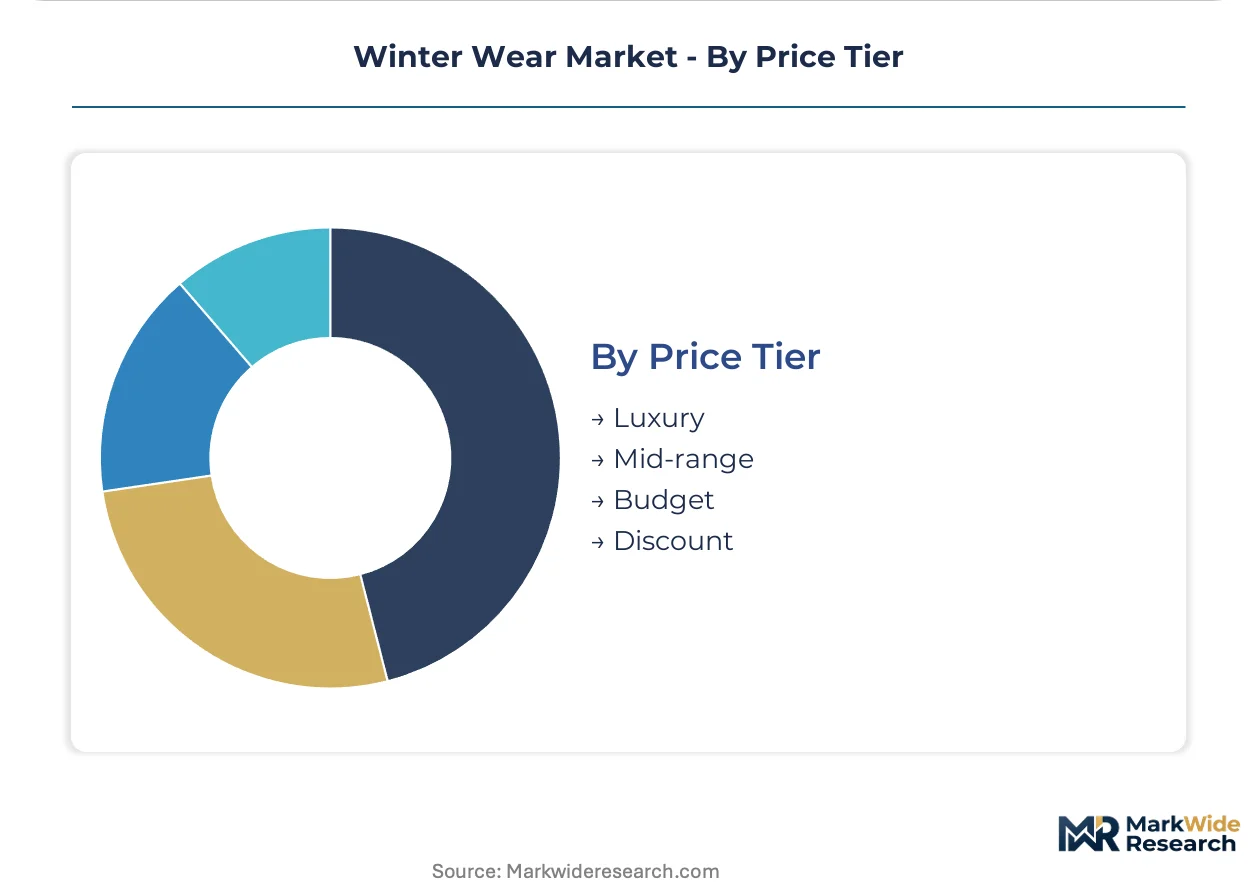
Supply chain configuration and certification grade separate tiers more than raw material cost alone, with traceability documentation becoming a price threshold.
- Luxury:Bluesign-certified supply chain transparency and blockchain-enabled provenance documentation command persistent premiums. EU Digital Product Passport requirements will further fragment compliance obligations, rewarding early movers with established traceability infrastructure.
- Mid-range:Proprietary thermal technologies and reformulated bio-based DWR treatments balance performance claims with accessibility. This tier bears the highest reformulation cost burden as durability expectations resist compromise during chemical transitions.
- Budget:Standardized synthetic insulation and silicone-based water repellents serve intermittent cold-climate exposure with minimal compliance documentation.
- Discount:Unbranded commodity constructions face stranded inventory risk from accelerating regulatory divergence across manufacturing footprints.
Mid-range lines absorb the bulk of installed capacity; luxury positioning is gaining share fastest on certification differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port and designated consumption zones concentrate inbound luxury winter wear demand while domestic production clusters absorb technology transfer from European specialists.
United States
Colorado and Utah mountain towns drive technical outerwear consumption through backcountry skiing participation. EPA oversight of PFAS eliminates C8 fluorocarbon water repellents from domestic production lines. Portland, Oregon hosts concentrated specialty retail and rental platform headquarters serving intermittent cold-climate urban buyers.
China
Hebei province's Chongli district anchors domestic ski resort infrastructure expansion targeting first-time winter sports participants. GB standards for textile safety favor compliant dye houses in Zhejiang province. Yangtze River Delta manufacturing clusters specialize in synthetic insulation reformulation for export markets.
Germany
Bavarian alpine regions sustain demand for professional-grade mountaineering equipment with hydrostatic head ratings exceeding 10,000mm. ECHA restrictions on persistent organic pollutants under REACH eliminate legacy DWR treatments from European supply chains. Munich and Stuttgart concentrate bluesign certification consulting and thermal testing infrastructure.
Japan
Nagano prefecture's ski resort corridor drives replacement purchase frequency for high-performance outerwear. METI guidance on sustainable textiles accelerates domestic brand adoption of recycled polyester constructions. Osaka-Kobe manufacturing clusters specialize in precision seam-sealing equipment for technical garments.
Canada
Quebec's Mont-Tremblant and British Columbia's Whistler anchor North American luxury winter wear consumption. Health Canada alignment with EPA chemical restrictions pressures reformulation of imported synthetic insulation. Toronto concentrates direct-to-consumer brand headquarters targeting rental and subscription model expansion.
Winter Wear Market Competitive Environment
North American producers anchor the premium technical tier; European specialists hold certification-driven positioning. The vendor base stratifies across three performance tiers with distinct supply chain configurations. Archetypes include vertically integrated outdoor conglomerates, purpose-built sustainability brands, and fast-fashion portfolio players. Dominant competitive moves center on certified supply chain acquisition and bio-based material licensing agreements.
Among North American outdoor conglomerates, VF Corporation and Columbia Sportswear Company exemplify scale-driven archetypes with captive manufacturing footprints. Patagonia occupies a position within the purpose-built sustainability tier, representing supply chain transparency differentiation. These three entities anchor competitive positioning across premium and mid-range price bands while navigating divergent EPA and ECHA chemical compliance obligations.
| Leading Market Players |
|---|
| VF Corporation |
| Columbia Sportswear Company |
| Canada Goose Holdings Inc. |
| Patagonia, Inc. |
| Adidas AG |
| Nike, Inc. |
| Inditex |
| Gap Inc. |
| H & M Hennes & Mauritz AB |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialty retailers anchor pricing discipline through captive distribution networks while sovereign-backed Chinese producers in Zhejiang province compress synthetic fiber feedstock costs. This ownership fragmentation creates divergent margin trajectories across European REACH-compliant supply chains and budget-tier Asian manufacturing footprints.
Pricing Analysis
Short lead-time premiums of 15-25% apply to bluesign-certified outerwear with sub-90-day replenishment cycles, while spot inventory of non-compliant legacy stock trades at distressed clearing levels. Three-tier pricing structure across premium, standard, and economy levels separates certification grade, with EU Digital Product Passport readiness commanding persistent premiums. Cost compression in mid-range synthetic insulation is intensifying because petrochemical input volatility exposes reformulation-dependent manufacturers to working capital strain. Urban rental-subscription participants in Germany and Colorado exhibit lowest price sensitivity; discount-channel intermittent buyers face highest elasticity.
Supply Chain Analysis
China's GB standards for textile safety are reshaping sourcing toward compliant dye houses in Zhejiang and Guangdong provinces, displacing legacy wet-processing capacity. Raw material flows draw from South Korean advanced polymer suppliers, Taiwanese membrane lamination specialists, and Eastern European down-processing clusters. Single-source vulnerability concentrates in silicone-based DWR chemistry feedstocks as EPA and ECHA restrictions eliminate fluorinated alternatives. Distribution runs through specialty outdoor retailers, direct-to-consumer brand flagships, and emerging peer-to-peer resale platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Winter wear consolidation accelerates as multi-jurisdiction chemical compliance fragments material stocks and strands non-compliant inventory. REACH, EPA, and SAMR regulatory divergence forces mid-tier manufacturers into distressed exits or strategic absorption.
For Market Incumbents: To counter bluesign certification backlogs stretching 14-18 months, VF Corporation and Columbia Sportswear Company should accelerate captive dye-house acquisitions in compliant Zhejiang clusters. Backward integration into aerogel insulation sourcing from South Korean material science specialists secures warmth-to-weight differentiation above 800 fill power down alternatives. For New Entrants and Emerging Players: Rental platform partnerships in Nordic cities and Colorado mountain towns unlock access-over-accumulation demand among 25-34 year old urban buyers. Secondhand certification services for technical outerwear represent the most penetrable white-space, with blockchain-enabled provenance documentation as the differentiated go-to-market anchor. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-range synthetic specialists with stranded perfluorinated inventory in European manufacturing footprints. Long-term viability hinges on bio-based DWR licensing agreements and Digital Product Passport infrastructure deployment. Watch ECHA enforcement escalation against persistent organic pollutants as the inflection signal for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Bluesign Certification Fast-Track | ECHA enforcement timelines reward 12-month compliance pathways over standard 18-month queues. |
| Aerogel Insulation Licensing | South Korean material science partnerships compress warmth-to-bulk ratios in professional-grade mountaineering applications. |
| Digital Product Passport Infrastructure | EU regulatory requirements create first-mover advantage for blockchain-enabled supply chain visibility. |
| Secondhand Channel Integration | Certified pre-owned technical outerwear opens margin-accretive revenue streams with lower return rates. |
| GB Standards Alignment Partnerships | China's textile safety regulations favor domestic dye house partnerships for foreign brand local production. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this winter wear analysis. Primary interviews with outdoor brand supply chain directors, specialty retail category managers, textile chemical compliance officers, and Zhejiang province dye house operators combined with ECHA restriction documents, EPA PFAS guidance, and China GB standard updates. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation validated volume and value estimates.
Data-stream reconciliation across the projection horizon integrated product type, material composition, customer demographic, and price tier segmentation with regional regulatory cluster overlays. CAGRs derived from historical consumption patterns, alpine tourism infrastructure buildout trajectories, and synthetic fiber innovation adoption curves. Down fill power displacement rates and bio-based DWR durability degradation after 20 wash cycles informed substitution elasticity parameters.
Several conditions sit outside the modeled scope, including extreme weather event frequency impacts on replacement purchase cycles and sovereign trade policy shifts affecting China-EU textile flows. Forecasts reflect documented assumptions about ECHA enforcement consistency and aerogel cost curve trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Industrial Protective Fabrics Market
Protective and Workwear Textiles
Stain-Resistant Fabric Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market