
 Garment Active Insulation Market | 2026-2036
Garment Active Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Garment Active Insulation Market Analysis
Market Context
Subscription-based thermal-layer rental and maintenance services is repositioning how active insulation reaches consumers, shifting ownership models toward circular access. PrimaLoft, Inc. leverages its recycled fiber platform to anchor sustainable insulation supply for premium outerwear brands. Arc'teryx Equipment Inc. dominates technical alpine segments through precision channel control in specialty retail. Columbia Sportswear Company competes across mass-market outdoor layers with broad distribution scale.
Technical Definition and Segments
Garment active insulation comprises engineered thermal barrier systems—typically 60–200 gsm fill weights of synthetic loft fibers, phase change microcapsules, or treated down clusters—designed to modulate heat retention during variable physical exertion in cold environments. Phase change materials absorb and release latent heat at calibrated transition temperatures, while synthetic insulation maintains thermal performance when compressed or moist. Jackets command the largest value pool in product type segmentation, though base layers show the fastest trajectory as next-to-skin thermal regulation gains priority among athletes. Synthetic insulation leads technology segmentation by volume, yet hybrid insulation constructions capture expanding margin pools by combining down warmth with synthetic moisture resilience.
Regulatory Environment
REACH restrictions on perfluorinated chemicals and the EU Green Deal's textile circularity requirements are reshaping material specifications and chemical finishing protocols across European supply chains. The EPA's TSCA oversight of synthetic polymer manufacturing and state-level extended producer responsibility laws in California and New York are adding compliance layers for U.S. market access. Stakeholders must monitor evolving chemical disclosure mandates and recycling infrastructure requirements to anticipate specification shifts before they harden into procurement barriers.
Market Dynamics
The EU Green Deal's textile circularity mandates are forcing a wholesale reconfiguration of insulation material specifications, compressing lead times for recycled synthetic fiber certification while elevating compliance costs for conventional petroleum-based fills.
Growth Catalysts
- Alpine Sports Rental Subscriptions:Technical mountaineering communities in Germany and Austria are driving adoption of thermal-layer access models that prioritize performance over ownership, expanding addressable demand beyond traditional retail channels.
- REACH Chemical Restrictions:Perfluorinated compound limitations under ECHA oversight are accelerating substitution toward bio-based water-repellent finishes, creating specification pull for compliant insulation systems.
- Phase Change Microencapsulation:Latent heat management technology is penetrating mid-layer categories as athletes demand thermoregulation across variable exertion intensities in cold environments.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic insulation relies on polyester and polypropylene derivatives whose pricing tracks crude oil and natural gas indices, compressing margin stability for manufacturers.
- East Asian Supply Concentration:Recycled fiber processing and blown-in insulation manufacturing cluster in China's Zhejiang and Jiangsu provinces, creating geographic risk exposure.
- Down Substitution Ceiling:Treated down clusters retain warmth-to-weight advantages below 100 gsm fill weights that synthetic loft fibers struggle to replicate in ultralight alpine applications.
Strategic Opportunities
- Scandinavian Circular Infrastructure:Sweden and Norway's advanced textile recycling ecosystems offer first-mover positioning for closed-loop insulation take-back programs aligned with EU Green Deal targets.
- Base Layer Thermal Regulation:Next-to-skin active insulation represents an underdeveloped category where phase change materials can capture premium positioning in competitive cycling and Nordic skiing segments.
- California EPR Precedent:State-level extended producer responsibility legislation creates regulatory tailwinds for brands establishing domestic recycling infrastructure ahead of federal harmonization.
Industry Challenges
- Recycled Fiber Certification Bottlenecks:GRS and OEKO-TEX supply chain audits require 12-18 month validation cycles that delay product launches and strain working capital.
- Hybrid Construction Complexity:Combining down clusters with synthetic fibers demands specialized quilting equipment and pattern engineering that legacy outerwear manufacturers must acquire or outsource.
Report Scope
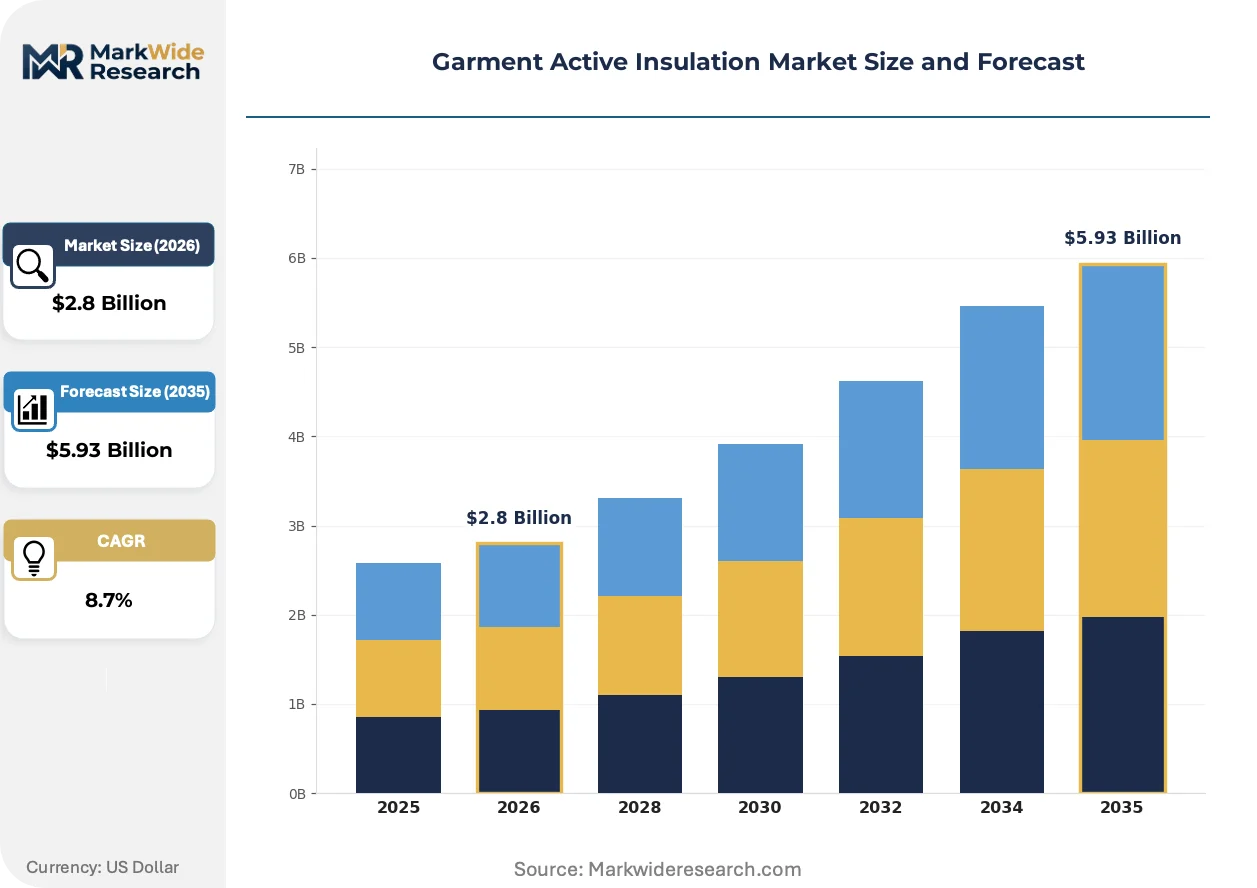
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garment Active Insulation Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackets, Vests, Pants, Base Layers Technology: Phase Change Materials, Synthetic Insulation, Hybrid Insulation, Down Alternatives End User: Outdoor Enthusiasts, Athletes, Casual Wearers, Industrial Workers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Patagonia, Inc., adidas AG, VF Corporation, PrimaLoft, Inc., Arc'teryx Equipment Inc., Columbia Sportswear Company, Under Armour, Inc., Polartec, LLC, Canada Goose Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garment Active Insulation Market Emerging Trajectories
Material science convergence with circular economy protocols is redefining competitive advantage in thermal barrier systems, shifting differentiation from raw warmth metrics to traceable sustainability credentials and adaptive thermoregulation.
Aerogel-infused synthetic batt insulation is expanding into technical alpine outerwear as manufacturers seek warmth-to-weight ratios approaching down performance without moisture vulnerability. Specialty mountaineering retailers in the German Alps and Colorado Rockies are accelerating placement of aerogel-based mid-layers. This technology is expanding into hybrid constructions that blend aerogel particles with recycled polyester loft, compressing the addressable market for traditional high-fill synthetic alternatives.
REACH Annex XVII restrictions on perfluorinated chemicals are eliminating durable water-repellent chemistries that long anchored synthetic insulation performance. European supply chains are requalifying bio-based paraffin and silicone alternatives that sacrifice some oil resistance for regulatory compliance. Alpine outerwear brands serving the Austrian and Swiss technical climbing communities are absorbing reformulation costs fastest, while mass-market players delay specification shifts pending cost parity.
Rental and resale platform integration is fragmenting traditional wholesale relationships as outdoor enthusiasts prioritize access over accumulation. Specialty retailers in Munich and Innsbruck are unbundling thermal-layer ownership from mountain sports participation, replacing unit sales with subscription recurring revenue. Germany's technical mountaineering demographic exhibits the highest penetration of this model, with Austrian and French alpine regions following at compressed adoption rates.
Garment Active Insulation Market Segmentation
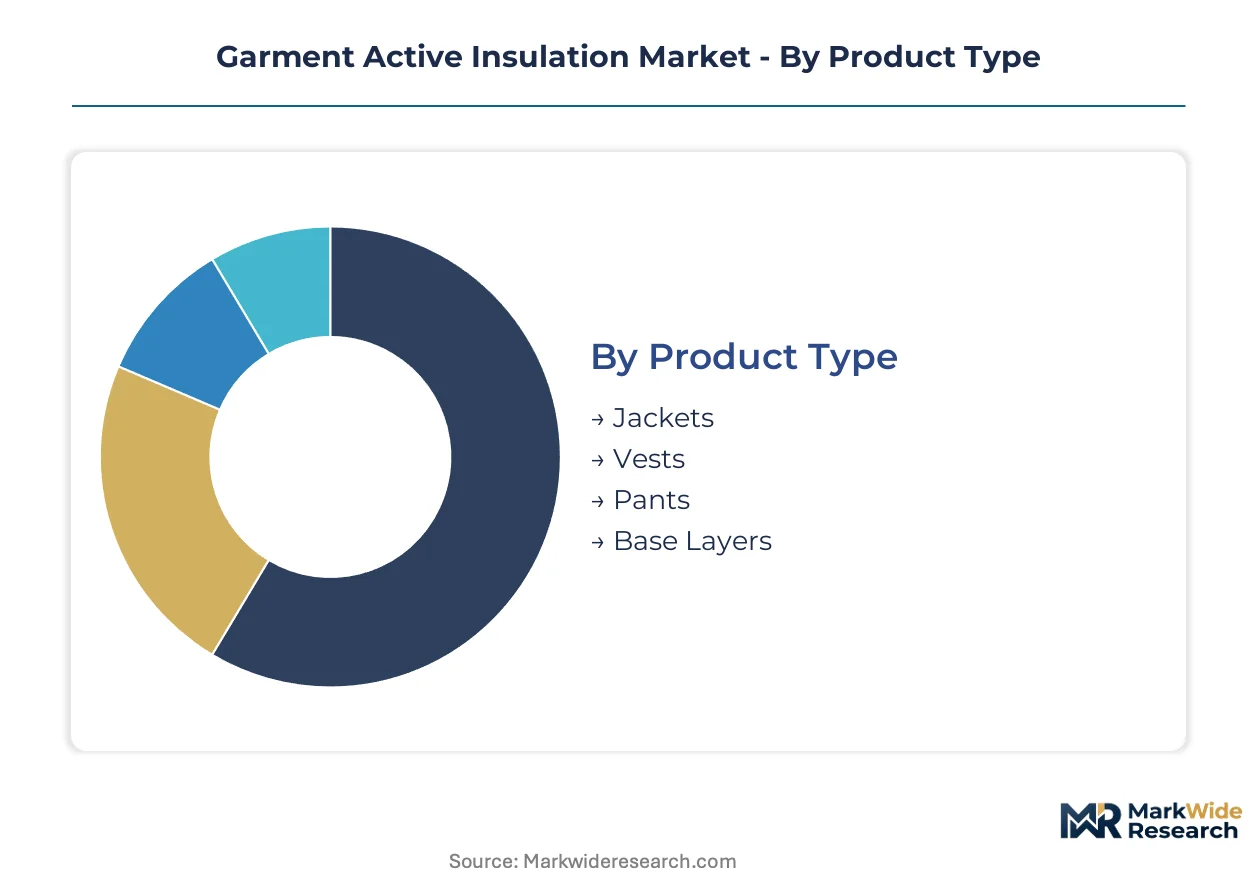
Active insulation segmentation reveals how thermal barrier technologies embed into different garment architectures and reach distinct user communities. Product form factors determine integration complexity, while technology choices balance moisture resilience against warmth-to-weight targets.
Product Type:
Standalone outer layers command premium positioning through visible technical performance, whereas embedded base-layer systems require seamless next-to-skin engineering.
- Jackets:Mid-weight and heavyweight shell constructions with 80–200 gsm synthetic loft or treated down clusters dominate alpine and urban cold-weather applications. German technical mountaineering communities drive specification intensity here, demanding modular layering compatibility with hardshell systems.
- Base Layers:Phase change microencapsulation and aerogel-infused knits integrate thermoregulation directly against the skin for variable-exertion Nordic skiing and competitive cycling. Austrian and Swiss retailers report the steepest adoption curves as athletes prioritize sweat management over static warmth.
- Vests:Core-focused insulation with reduced sleeve bulk suits high-output activities where arm mobility and venting take priority.
- Pants:Insulated lower-body systems concentrate in ice climbing and stationary cold-weather industrial applications where leg thermal protection is non-negotiable.
Jackets lead volumes today; base layers are gaining share fastest.
Technology:
Material science differentiation separates moisture-resilient synthetic platforms from adaptive thermoregulation systems, with cost structures tracking feedstock and processing complexity.
- Synthetic Insulation:Polyester and polypropylene loft fibers, often recycled under GRS certification, deliver consistent thermal performance when compressed or wet. REACH-compliant water-repellent finishes are reshaping European procurement specifications for this segment.
- Phase Change Materials:Microencapsulated paraffin or salt hydrates absorb and release latent heat at calibrated transition temperatures, enabling dynamic thermoregulation across exertion intensities. The technology commands premium positioning in mid-layer categories where athletes demand responsive thermal management.
- Hybrid Insulation:Down-synthetic combinations balance warmth-to-weight ratios with moisture resilience, though specialized quilting equipment requirements constrain manufacturer participation.
- Down Alternatives:Plant-based or recycled fiber batts replicate down cluster structure without animal sourcing, appealing to sustainability-focused outdoor enthusiasts in Scandinavian markets.
Synthetic insulation leads volumes today; phase change materials are expanding most quickly.
End User:
User sophistication determines performance thresholds and price elasticity, with technical athletes accepting specification tradeoffs that casual wearers reject.
- Outdoor Enthusiasts:Hikers, campers, and general recreationists prioritize versatility across conditions, driving demand for synthetic systems with broad temperature ranges. This cohort shows highest sensitivity to rental and subscription access models in German alpine regions.
- Athletes:Competitive and endurance sports participants require precise thermoregulation during variable exertion, making them early adopters of phase change base layers and aerogel-enhanced mid-layers.
- Casual Wearers:Urban and commuter applications favor aesthetic integration and easy care over technical performance metrics.
- Industrial Workers:Cold-storage, construction, and utility sectors demand durable insulation meeting workplace safety standards, with procurement concentrated through specialized workwear distributors.
Outdoor enthusiasts lead volumes today; athletes are climbing the fastest.
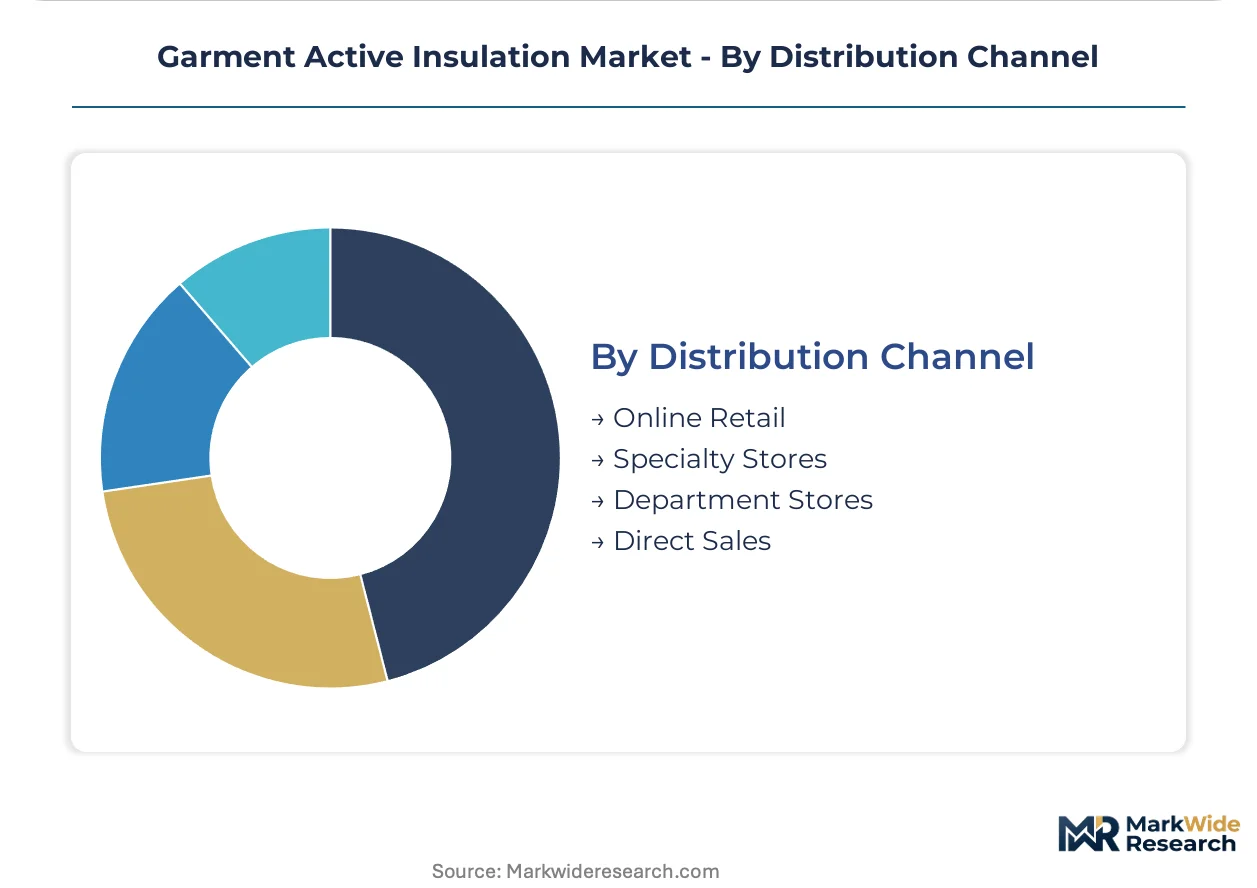
Distribution Channel:
Channel selection reflects purchase urgency, technical consultation needs, and circular economy participation preferences across user segments.
- Specialty Stores:Munich, Innsbruck, and Chamonix retailers provide fitted technical guidance and rental subscription integration for alpine sports communities. These outlets anchor premium brand positioning through controlled assortment and staff expertise.
- Online Retail:Direct-to-consumer and marketplace platforms capture price-sensitive demand and facilitate resale circulation, with Swedish and Norwegian consumers showing highest digital adoption for circular access models.
- Department Stores:Mass-market outerwear placement reaches casual wearers through seasonal promotional cycles, though technical specification depth remains limited.
- Direct Sales:Brand-owned channels enable subscription rental programs and take-back logistics for EU Green Deal compliance, with German technical mountaineering brands pioneering this infrastructure.
Specialty stores lead volumes today; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's technical mountaineering communities drive premium specification intensity that outpaces France's broader outdoor recreation base, while both markets operate under identical EU Green Deal compliance timelines.
United States
Colorado and California anchor demand through alpine sports clusters and outdoor lifestyle penetration. EPA TSCA oversight of synthetic polymer manufacturing adds compliance layers for domestic insulation producers. Denver-Boulder specialty retailers pioneer subscription thermal-layer models that unbundle ownership from mountain sports participation.
Germany
Munich and Innsbruck-adjacent Bavarian communities demand modular layering compatibility with hardshell systems for technical climbing. ECHA REACH Annex XVII restrictions on perfluorinated chemicals force rapid reformulation of water-repellent finishes. Stuttgart industrial belt hosts blown-in insulation manufacturing for premium outerwear supply chains.
China
Zhejiang and Jiangsu provinces concentrate recycled fiber processing and synthetic loft manufacturing for global brand supply. MEE environmental compliance requirements and dual carbon goals accelerate shifts toward certified recycled polyester feedstocks. Hangzhou textile engineering clusters develop hybrid down-synthetic quilting capabilities for European export orders.
Sweden
Stockholm and Gothenburg consumers show highest digital adoption for circular access models including rental and resale platforms. EU Green Deal textile circularity mandates align with existing advanced recycling infrastructure. Scandinavian retail ecosystems enable closed-loop insulation take-back programs ahead of continental compliance deadlines.
Japan
Tokyo and Nagoya metropolitan areas demand precision thermoregulation for urban commuting and weekend alpine activities. METI industrial standards and JIS certification requirements shape material specifications for domestic and export markets. Osaka specialty retailers integrate phase change base layers into competitive cycling and Nordic skiing assortments.
Garment Active Insulation Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with technical alpine positioning commanding premium margins against mass-market scale economics. The vendor base organizes around three archetypes: integrated outdoor lifestyle brands controlling full product ecosystems, materials science platforms supplying certified insulation to multiple labels, and precision alpine specialists dominating specialty retail channels. Consolidation pressure concentrates among mid-tier outerwear labels lacking vertical fiber sourcing or direct consumer access. Competitive moves cluster on circular economy certification acquisition and subscription infrastructure buildout.
Within the materials science platform tier, PrimaLoft, Inc. and Polartec, LLC anchor recycled fiber supply for brands navigating REACH compliance timelines. Arc'teryx Equipment Inc. occupies the precision alpine specialist position, representing channel control strategies that prioritize technical credibility over distribution breadth. Columbia Sportswear Company exemplifies mass-market scale economics, competing through seasonal volume cycles and broad retail penetration rather than specification intensity.
| Leading Market Players |
|---|
| Patagonia, Inc. |
| adidas AG |
| VF Corporation |
| PrimaLoft, Inc. |
| Arc'teryx Equipment Inc. |
| Columbia Sportswear Company |
| Under Armour, Inc. |
| Polartec, LLC |
| Canada Goose Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal textile circularity mandates are forcing brands to requalify insulation suppliers around GRS-certified recycled fiber specifications, compressing procurement timelines while elevating compliance premiums that synthetic loft manufacturers must absorb or pass through.
Pricing Analysis
Capacity additions in China's Zhejiang province are reshaping price floors for conventional polyester loft fibers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and fill weight density. Cost compression in standard-tier recycled synthetic insulation is intensifying because REACH-compliant water-repellent finish reformulations add processing overhead. Casual urban wearers exhibit highest price sensitivity, while German technical mountaineering communities accept specification premiums for modular hardshell compatibility.
Supply Chain Analysis
Dual-sourcing requirements from Arc'teryx and Patagonia procurement teams are fragmenting order concentration across China's Jiangsu province, Vietnam's emerging textile belt, and domestic Portuguese manufacturing for EU compliance. Raw material flows draw from petroleum-derived polyester chips, post-consumer recycled PET flake, and bio-based paraffin phase change materials. Single-source vulnerability concentrates in aerogel particle supply from limited specialty chemical producers. Distribution runs through Munich and Innsbruck specialty retail clusters for technical alpine segments, with direct-to-consumer channels capturing circular rental subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier phase change base layer penetration and recycled fiber certification premiums that command sustainable sourcing markups.
For Market Incumbents: Cement channel control in Bavarian specialty retail through exclusive rental subscription partnerships that lock out competitor access. Deepen backward integration into certified recycled PET flake processing to capture GRS compliance premiums before feedstock bottlenecks harden. Aerogel-infused hybrid constructions represent the priority R&D frontier for warmth-to-weight parity with treated down clusters. For New Entrants and Emerging Players: Launch via Swedish digital circular platforms that aggregate rental demand across Nordic skiing and competitive cycling segments. Scandinavian closed-loop take-back infrastructure offers the most penetrable geography for EU Green Deal-aligned market entry. Phase change base layers for variable-exertion athletes present the clearest white-space opportunity with premium positioning potential. For Investors and Strategic Acquirers: Asymmetric upside sits with materials science platforms possessing validated GRS supply chains and blown-in insulation manufacturing capabilities. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than raw capacity scale. Watch for ECHA expansion of perfluorinated chemical restrictions to signal accelerated specification turnover and acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| GRS Certification Investment | Unlocks EU Green Deal procurement eligibility for recycled synthetic fiber supply. |
| Subscription Rental Infrastructure | Captures recurring revenue from German technical mountaineering communities. |
| Phase Change Base Layer Launch | Penetrates Nordic skiing and competitive cycling thermoregulation segments. |
| Aerogel Hybrid Construction Scale-Up | Compresses addressable market for traditional high-fill synthetic alternatives. |
| Portuguese Manufacturing Footprint | Shortens EU REACH compliance pathways for premium outerwear brands. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from outerwear brand procurement directors, specialty retail buyers in Munich and Innsbruck, blown-in insulation manufacturing engineers, and ECHA regulatory affairs consultants. Secondary validation drew from customs trade databases for synthetic fiber flows, OEKO-TEX and GRS certification registries, and EU Green Deal implementation progress reports. Bottom-up demand modeling and top-down supply capacity assessments were cross-referenced for triangulation.
Historical reference periods anchored volume and value trajectories across the modeling period. Segmentation dimensions included product architecture, insulation technology platform, end-user sophistication tier, and distribution channel type. CAGRs were derived from fitted growth curves incorporating petrochemical feedstock price indices, alpine sports participation rates, and circular subscription penetration assumptions. Phase change material cost curves and aerogel manufacturing scale economics informed technology-specific outlooks.
Several conditions sit outside the modeled scope, including sudden ECHA chemical restriction expansions, trade policy disruptions affecting Zhejiang-Jiangsu supply corridors, and breakthrough plant-based down alternative technologies. Deviation in REACH enforcement timelines or recycled fiber certification audit backlogs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Fabric Protection Market
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
Winter Hats Market
Protective and Workwear Textiles
Welding Curtains Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Industrial Hand Gloves Market
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
Personal Protective Textile Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Stain-Resistant Fabric Market