
 North America Western Wear Market | 2026-2036
North America Western Wear Market Size, Share, and Industry Trends Forecast 2026-2036
North America Western Wear Market Insights
Buyer concentration across cattle ranching cooperatives and professional rodeo circuits is rebalancing toward specialty retailers serving smaller, dispersed operations. Boot Barn leverages its store network across rural corridors to sustain geographic dominance in boots and accessories. Tecovas competes through direct-to-consumer channels that specialize in premium leather craftsmanship. Wrangler anchors mass-market jeans supply through long-standing relationships with farm supply chains.
North America western wear encompasses durable apparel and footwear designed for ranch labor, rodeo competition, and regional lifestyle expression, typically constructed from heavyweight denim, full-grain leather, and oil-resistant soles with reinforced stitching at stress points. Boots represent the highest-margin product category due to material intensity and repair-service attach rates, while online retail channels capture the fastest growth trajectory among distribution pathways. The customer-type segmentation reveals cattle ranchers as the most brand-loyal buyer group, with replacement cycles tied to calving seasons and rodeo calendars.
The US Consumer Product Safety Commission oversees flammability standards for cotton-denim blends, while EPA guidelines govern leather tanning effluent limits that affect domestic boot manufacturing costs. Health Canada enforces similar textile safety protocols that shape cross-border product compliance requirements. Stakeholders must monitor how evolving labor standards at Mexican tanneries influence raw material pricing and supply continuity for integrated brands.
Market Dynamics
Technical fabric innovations are compressing replacement cycles for ranch workwear as moisture-wicking denim and synthetic leather alternatives meet durability benchmarks previously reserved for traditional materials. This shift is rebalancing procurement patterns across cattle operations and rodeo circuits alike.
Growth Catalysts
- USMCA Rules of Origin:The agreement's regional content requirements for leather goods are incentivizing integrated North American supply chains for boot manufacturing. Tanneries in Guanajuato and León are expanding capacity to serve US brands.
- Moisture-Wicking Denim Blends:Advanced cotton-synthetic weaves are extending garment lifespan in high-sweat ranch environments. Working cattle operations in the Texas Panhandle are adopting these fabrics for summer calving crews.
- Professional Rodeo Circuits:Athlete sponsorship programs are creating predictable demand spikes tied to championship seasons. Boot and hat purchases concentrate around National Finals Rodeo qualifying periods.
Market Restraints
- Leather Input Volatility:Hide prices fluctuate with cattle cycle downturns and meatpacking capacity constraints. Mexican tannery wages are rising under labor compliance pressure from USMCA labor chapters.
- EPA Effluent Limits:Chromium discharge regulations for tanning operations are elevating domestic boot production costs. Compliance investments are squeezing mid-tier manufacturers without captive tannery access.
- Synthetic Leather Substitution:Polyurethane and microfiber alternatives are capturing casual wear segments. Traditional full-grain leather faces price-elasticity pressure in non-work applications.
Strategic Opportunities
- Alberta Ranching Cooperatives:Consolidated cattle operations in Southern Alberta are underserved by specialty western wear retailers. Direct-to-ranch mobile fitting services could capture bulk replacement orders.
- Repair-Service Attachments:Boot resoling and leather conditioning programs create recurring revenue streams. Rodeo athletes and working ranchers prioritize rebuildable footwear over disposable alternatives.
- Health Canada Textile Standards:Harmonized flammability testing with US CPSC protocols simplifies cross-border product launches. Brands with dual compliance can access Canadian agricultural markets efficiently.
Industry Challenges
- Skilled Stitching Labor:Industrial sewing technicians capable of handling heavyweight leather and triple-stitch denim are scarce in rural manufacturing corridors. Training pipelines have not kept pace with retirements.
- Legacy Inventory Systems:Seasonal demand spikes around calving and rodeo seasons strain forecasting accuracy. Size-run fragmentation across wide-width boot requirements complicates automated replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Western Wear Market |
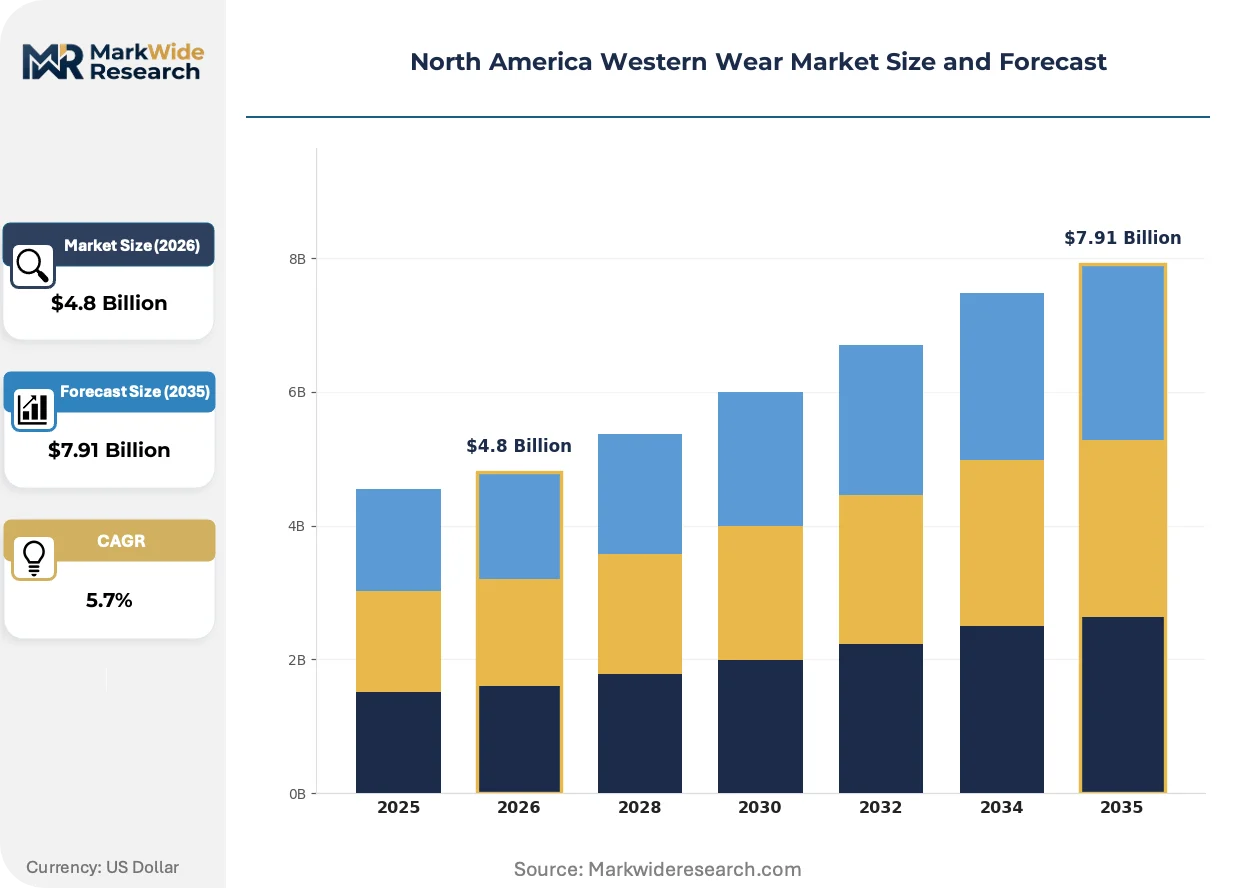
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jeans, Shirts, Belts, Boots Customer Type: Men, Women, Children, Cattle Ranchers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Farmers Markets Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Levi Strauss & Co., Justin Brands, Boot Barn, Pinto Ranch, Tecovas, Wrangler, Lucchese Brand, Kontoor Brands, Ariat International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Western Wear Market Trends and Innovations
Material science advances and regulatory harmonization are reshaping how western wear manufacturers balance heritage aesthetics with functional performance. Three developments are compressing traditional production timelines and reconfiguring channel economics.
Advanced moisture-management textiles are converging with heritage denim construction to create hybrid workwear that satisfies both ranch durability requirements and comfort expectations. Cattle operations in Oklahoma and Kansas are adopting these garments for year-round crews, reducing seasonal wardrobe rotation. The convergence is enabling premium pricing for technical workwear that previously competed solely on cost.
EPA effluent guidelines for chromium tanning are tightening discharge limits at facilities supplying domestic boot manufacturers. Compliance investments are accelerating consolidation among mid-sized tanneries unable to fund wastewater treatment upgrades. Small-batch artisan bootmakers sourcing from compliant Mexican facilities are capturing positioning advantages in premium segments.
Rural buyers are fragmenting across direct-to-consumer digital channels and mobile pop-up retail formats that reach dispersed ranch operations. Specialty retailers with fixed storefronts in county-seat towns are losing share to trailer-based fitting services that visit cattle auctions and breed association events. This pattern is most pronounced in the Texas Hill Country and Eastern Oklahoma where ranch density supports route economics.
North America Western Wear Market Segmentation
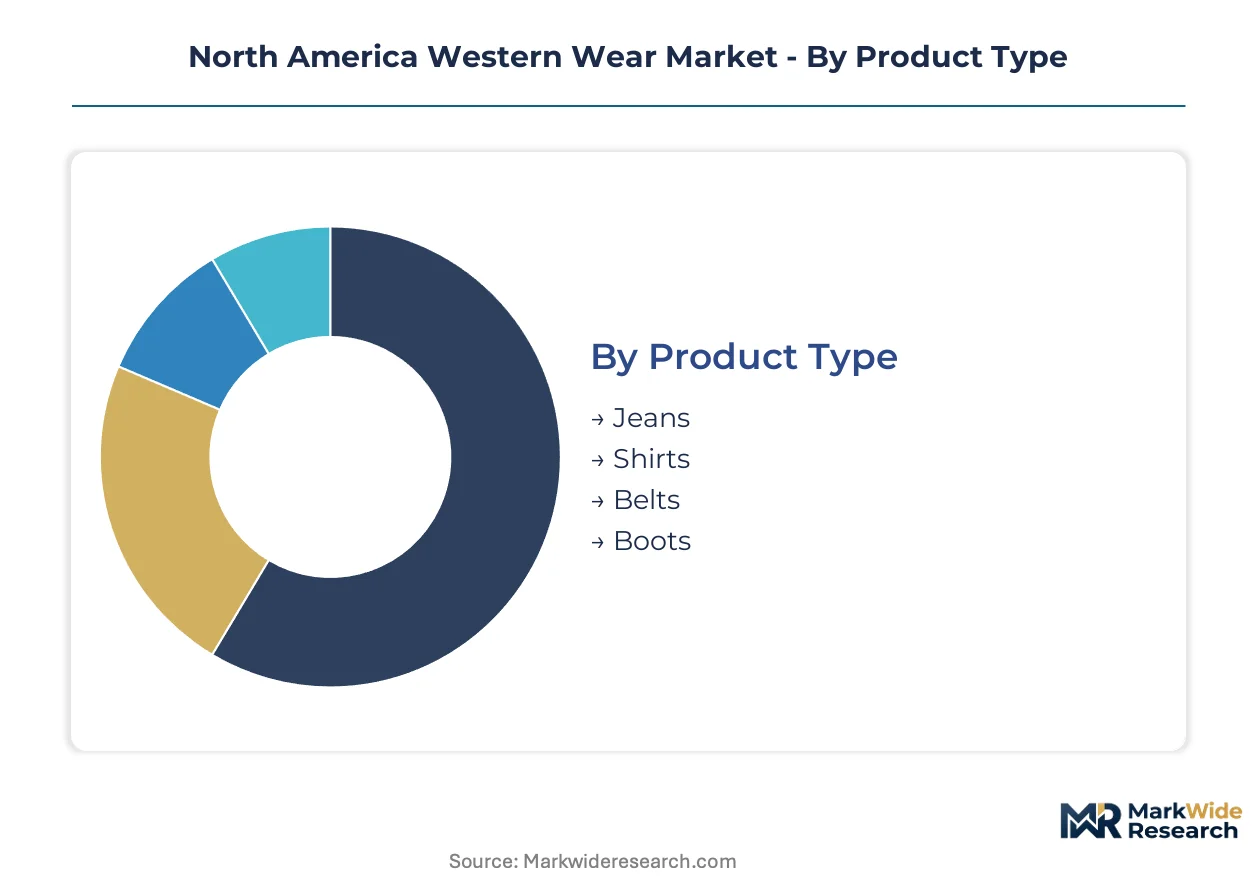
Western wear segmentation reflects divergent purchasing logic across ranch labor, rodeo competition, and lifestyle expression. Volume concentration in workwear contrasts with premium capture in performance footwear, creating distinct margin architectures by segment.
Product Type:
Boots command the steepest premium tiers due to material intensity and repair-service economics, while denim operates at higher volumes with compressed margins.
- Boots:Full-grain leather construction with oil-resistant soles and reinforced stitching at stress points defines technical specifications. Demand concentrates in Texas, Oklahoma, and Alberta where ranching culture drives replacement cycles tied to calving seasons and rodeo calendars. Repair-service attach rates sustain recurring revenue streams that jeans and shirts cannot replicate.
- Jeans:Heavyweight denim with reinforced stress points dominates cattle operation procurement. Moisture-wicking cotton-synthetic blends are expanding share among summer calving crews in the Texas Panhandle and Kansas ranchlands.
- Shirts:Western-cut cotton and cotton-poly blends serve both work and social occasions. Pearl-snap closures and yoke detailing distinguish regional styling preferences across the US Southwest and Canadian Prairies.
- Belts:Full-grain leather with tooling and buckle customization anchors accessory purchases. Rodeo athletes and working ranchers drive replacement through wear rather than fashion cycles.
Mature deployment sits with jeans as the baseline workwear standard. Newer deployment is concentrated in technical fabric boots gaining share among professional rodeo circuits.
Customer Type:
Procurement authority differs sharply between household purchasers and institutional buyers operating through cattle cooperatives.
- Cattle Ranchers:Consolidated operations in Southern Alberta and the Texas Hill Country purchase through cooperative procurement channels with predictable replacement calendars. Brand loyalty exceeds other segments due to durability requirements and fit consistency across extended workdays.
- Men:Individual purchasers dominate volume in boots and denim through both retail and direct-to-consumer channels. Mobile fitting services are gaining traction among dispersed operations in Eastern Oklahoma.
- Women:Fashion-forward western styling drives purchase frequency above functional replacement cycles. Online retail channels capture disproportionate share through size-run availability that rural storefronts struggle to stock.
- Children:Growth-stage replacement creates predictable demand spikes ahead of school terms and youth rodeo seasons. Price sensitivity exceeds adult segments with budget and mid-range tiers dominating.
Established demand concentration rests with male individual purchasers. Expanding deployment is concentrated in cooperative procurement serving consolidated cattle operations.
Distribution Channel:
Channel economics are fragmenting as fixed retail costs lose competitiveness against mobile and digital formats reaching dispersed rural buyers.
- Online Retail:Direct-to-consumer platforms specializing in premium leather craftsmanship bypass geographic constraints. Size-run fragmentation for wide-width boot requirements complicates fulfillment but captures customers beyond specialty store catchment areas.
- Specialty Stores:County-seat storefronts anchor brand relationships through fitting expertise and repair-service integration. Boot Barn leverages rural corridor density to sustain geographic dominance in boots and accessories.
- Department Stores:Mass-market jeans supply through farm supply chains reaches price-sensitive segments. Wrangler anchors this channel through long-standing relationships with agricultural retail networks.
- Farmers Markets:Artisan bootmakers and small-batch leatherworkers access local ranch communities. Guanajuato and León tannery connections support compliant sourcing for premium positioning.
Traditional deployment sits with specialty store networks. Channel expansion is climbing the fastest through trailer-based mobile fitting services visiting cattle auctions and breed association events.
Price Tier:
Price architecture separates rebuildable investment goods from disposable seasonal purchases across the customer base.
- Premium:Full-grain leather boots with resoling capability target working ranchers and rodeo athletes. Tecovas competes through direct-to-consumer channels emphasizing craftsmanship transparency.
- Mid-Range:Blended leather and synthetic construction balances durability with accessibility. This tier captures bulk replacement orders from mid-sized cattle operations.
- Budget:Polyurethane and microfiber alternatives serve casual wear and entry-level work applications. Price elasticity pressure is most acute in non-work segments.
- Luxury:Exotic leathers and custom tooling serve collector and status-purchase demand. Limited production runs and artisan labor inputs constrain scalability.
Volume concentration sits with mid-range tiers serving operational procurement. Margin expansion is concentrating in premium tiers where repair-service economics sustain customer lifetime value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
León and Guanajuato anchor North American leather supply chains with expanding tannery capacity serving integrated boot manufacturers. The USMCA rules of origin provisions are reshaping sourcing decisions across the tri-national trade corridor.
United States
Texas Panhandle cattle operations drive replacement cycles for heavyweight denim and full-grain leather boots tied to calving seasons. EPA effluent limits for chromium tanning discharge elevate production costs for domestic manufacturers. Nashville and Dallas-Fort Worth retail corridors concentrate specialty storefronts serving rodeo circuits and ranch cooperatives.
Canada
Southern Alberta ranching cooperatives generate consolidated procurement demand with predictable seasonal purchasing calendars. Health Canada textile flammability standards harmonize with US CPSC protocols to simplify cross-border compliance. Calgary anchors distribution infrastructure serving Prairie Provinces agricultural markets.
Mexico
Guanajuato and León tanneries expand chromium-compliant capacity to capture USMCA regional content requirements for leather goods. Labor compliance pressure under USMCA labor chapters elevates wage costs at hide processing facilities. Northern border states concentrate maquiladora assembly operations for denim finishing and boot manufacturing.
North America Western Wear Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer craftsmanship positioning. The vendor base stratifies across mass-market denim suppliers, specialty retail networks, and artisan bootmakers with captive tannery relationships. Three archetypes dominate: vertically integrated leather specialists, rural corridor specialty retailers, and farm supply channel anchors. Competitive moves concentrate on mobile fitting service expansion and repair-service program development to capture recurring revenue streams.
Among heritage denim suppliers, Levi Strauss & Co. and Wrangler occupy positions as farm supply channel anchors with long-standing agricultural retail relationships. Tecovas exemplifies the direct-to-consumer archetype emphasizing premium leather transparency. Boot Barn represents the rural corridor specialty retailer model with geographic density across county-seat markets.
| Leading Market Players |
|---|
| Levi Strauss & Co. |
| Justin Brands |
| Boot Barn |
| Pinto Ranch |
| Tecovas |
| Wrangler |
| Lucchese Brand |
| Kontoor Brands |
| Ariat International |
| Others |
Pricing and Supply Chain Analysis
Captive tannery operations in Guanajuato and León anchor both cost predictability and premium-tier pricing power for integrated boot manufacturers serving USMCA-compliant supply chains. This backward integration into chromium-compliant hide processing insulates vertically positioned brands from EPA effluent-driven cost spikes that squeeze mid-tier competitors lacking similar upstream control.
Pricing Analysis
Repair-service bundling separates premium boot tiers from disposable alternatives, with resoling programs and leather conditioning subscriptions justifying 40-60% price premiums over unbundled competitors. Three-tier pricing structure across premium, standard, and economy levels stratifies by material grade and craftsmanship transparency, with full-grain leather commanding position against polyurethane alternatives. Cost compression in the budget tier is intensifying because synthetic leather substitution erodes price inelasticity among casual wear buyers. Cattle ranchers exhibit lowest price sensitivity due to durability requirements and fit consistency needs, while youth rodeo participants drive highest elasticity in growth-stage replacement cycles.
Supply Chain Analysis
USMCA regional content certification gates market access for leather goods, requiring 55-60% North American value-add to qualify for duty-free treatment across the tri-national corridor. Raw material flows draw from Guanajuato tanneries, Texas Panhandle hide processors, and Alberta cattle cooperatives, with chromium-tanned full-grain leather and oil-resistant rubber compounds anchoring boot construction inputs. Single-source vulnerability concentrates in Mexican tannery capacity expansion timelines, where labor compliance investments under USMCA labor chapters strain wage-cost structures. Distribution runs through specialty retail networks in rural corridor county seats, supplemented by direct-to-consumer platforms capturing dispersed ranch operations beyond fixed storefront catchment areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA effluent compliance investments are accelerating consolidation by eliminating mid-tier manufacturers without captive tannery access or wastewater treatment capital, compressing the vendor base toward integrated specialists and mass-market anchors.
For Market Incumbents: Lock in cooperative procurement relationships with Southern Alberta and Texas Hill Country cattle operations through mobile fitting services that visit calving seasons and breed association events. Deepen backward integration into Guanajuato tannery capacity to secure USMCA-compliant chromium processing ahead of competitor compliance investments. Synthetic leather substitution from polyurethane and microfiber entrants threatens mass-market positioning; counter through repair-service program expansion that emphasizes rebuildable economics over disposable alternatives. For New Entrants and Emerging Players: Moisture-wicking denim technology offers entry wedge into summer calving crew procurement in Oklahoma and Kansas, where technical fabric adoption outpaces incumbent refresh cycles. Target trailer-based mobile fitting routes through Eastern Oklahoma and Texas Hill Country ranch auctions, where geographic dispersion has left specialty retail coverage gaps. Direct-to-consumer craftsmanship transparency, modeled on artisan bootmaker positioning, enables premium capture without fixed storefront overhead. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by vertically integrated apparel conglomerates seeking USMCA-compliant leather supply chain control. Long-term viability favors brands with dual Health Canada and US CPSC compliance infrastructure, enabling efficient cross-border expansion without redundant testing investment. Watch for inflection in Mexican tannery wage arbitration as USMCA labor chapter enforcement tightens, signaling margin compression for non-integrated competitors and acquisition opportunity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Fitting Service Expansion | Trailer-based routes visiting cattle auctions capture dispersed ranch procurement beyond county-seat retail density. |
| Repair-Service Program Development | Boot resoling subscriptions create recurring revenue streams that jeans and shirts cannot replicate for working ranchers. |
| USMCA-Compliant Tannery Investment | Chromium-compliant capacity in Guanajuato secures regional content qualification for duty-free North American trade. |
| Moisture-Wicking Denim Line Launch | Technical fabric adoption among Texas Panhandle calving crews enables premium pricing previously reserved for traditional materials. |
| Direct-to-Consumer Platform Buildout | Digital channels bypass specialty store geographic constraints while capturing wide-width boot customers in underserved rural markets. |
Research Methodology
Document review covered customs and trade data, SEC filings from publicly traded apparel conglomerates, and EPA enforcement records for chromium tanning discharge, complemented by interviews with tannery operations managers, Boot Barn category buyers, Tecovas supply chain directors, and Alberta cattle cooperative procurement officers. Secondary validation drew from USMCA rules of origin documentation, Health Canada textile flammability standards, and US CPSC cotton-denim blend regulations. Bottom-up unit economics from boot manufacturing cost structures were triangulated against top-down market sizing from agricultural retail network sales data.
Historical shipment volumes from specialty retail POS systems were cross-referenced against panel input from rodeo circuit sponsorship directors and ranch supply cooperative managers to anchor projection assumptions. The analytical framework modeled product type segmentation across boots, jeans, shirts, and belts; customer type splits between cattle ranchers, men, women, and children; and distribution channel dynamics across online retail, specialty stores, department stores, and farmers markets. CAGRs were derived from replacement cycle analysis tied to calving seasons and rodeo calendars, with inputs from hide price volatility indices and Mexican tannery wage trend data.
Several conditions sit outside the modeled scope, including potential USMCA renegotiation, catastrophic drought impacts on cattle herd sizes affecting hide supply, and breakthrough synthetic leather technologies achieving full durability parity with full-grain construction. Forecasts reflect assumptions about continued EPA effluent limit enforcement and stable USMCA labor chapter implementation. A model refresh is warranted upon material change in chromium tanning compliance costs or USMCA regional content threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Welding Curtains Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Industrial Hand Gloves Market
Protective and Workwear Textiles
Dry Suits Market