
 Winter Hats Market | 2026-2036
Winter Hats Market Size, Share, and Industry Trends Forecast 2026-2036
Winter Hats Market Intelligence
Bluesign certification is reorganizing competitive entry in technical winter headwear, filtering out suppliers unable to meet traceable chemical management standards. Columbia Sportswear Company leverages its vertical manufacturing network to sustain compliance across fleece and wool-blend product lines. Mammut Sports Group AG anchors its Alpine heritage in high-loft merino trapper designs that dominate specialty retail in mountain regions. Carhartt, Inc. competes on workwear authenticity, extending thermal acrylic beanies through industrial distribution channels that prioritize durability ratings over fashion cycles.
Winter hats are insulated cranial coverings engineered from woven, knitted, or felted textiles with thermal resistance values typically ranging from 0.5 to 2.0 clo, designed to reduce conductive and convective heat loss in ambient temperatures below 10°C. Their commercial purpose spans occupational cold protection, athletic performance, and fashion expression across seasonal retail cycles. Beanies and knitted caps occupy the highest volume tier in casual and sports styling, where acrylic-wool blends balance cost with wash durability. Fleece material formulations capture margin pools in outdoor specialty channels due to moisture-wicking certifications and lighter weight-to-warmth ratios that appeal to alpine athletes.
REACH in Europe, OEKO-TEX Standard 100, and the US Consumer Product Safety Commission's flammability standards for wearing apparel collectively govern fiber content labeling, chemical residue limits, and combustion safety in winter hat distribution. These frameworks raise compliance costs for smaller knitwear producers while creating market access advantages for vertically integrated manufacturers with in-house testing laboratories. Stakeholders must monitor evolving extended producer responsibility mandates for textile recycling, as circular economy requirements in the EU and several US states will soon dictate post-consumer material quotas and reverse logistics obligations.
Market Dynamics
REACH chemical restrictions under ECHA oversight are compressing supplier margins while rewarding certified organic wool and recycled synthetic blend producers with premium channel access across European distribution networks.
Growth Catalysts
- EU Green Deal textile circularity mandates:Extended producer responsibility requirements for post-consumer recycling are creating first-mover advantages for manufacturers with established reverse logistics infrastructure in Germany and France.
- Alpine sports participation rates:Cold-weather outdoor recreation expansion in Austria, Switzerland, and Norway is pulling technical insulated headwear through specialty retail channels prioritizing thermal performance certifications.
- Recycled synthetic fiber technology:Mechanical recycling advances for post-consumer polyester are lowering input costs for fleece material formulations while satisfying Bluesign chemical traceability standards.
Market Restraints
- Merino wool price volatility:Australian and New Zealand fiber auction fluctuations are compressing margins for premium knitwear producers dependent on certified organic supply chains.
- REACH compliance cost concentration:Small-batch knitwear manufacturers in Italy and Portugal face disproportionate testing laboratory expenses relative to vertically integrated competitors with captive certification capabilities.
- Synthetic fleece microfiber substitution pressure:Biodegradable natural fiber alternatives are capturing sustainability-conscious consumer segments in Nordic markets.
Strategic Opportunities
- US Consumer Product Safety Commission flammability standard harmonization:Convergence with EU chemical safety frameworks would streamline cross-Atlantic product development for multinational apparel brands.
- Industrial workwear channel expansion:Cold-storage logistics and construction sectors in Poland and Czech Republic represent underpenetrated demand for thermal acrylic beanies with durability ratings.
- Digital product passport integration:Blockchain-enabled fiber traceability systems are enabling premium pricing for verifiable recycled content claims in German specialty retail.
Industry Challenges
- Bluesign certification timeline compression:Chemical management audit backlogs are delaying product launches for mid-tier suppliers without established auditor relationships.
- Legacy dye house equipment retrofitting:Waterless supercritical CO2 dyeing technology adoption requires capital outlays that strain family-owned knitwear producers in Northern Italy.
- Multi-standard compliance fragmentation:Simultaneous adherence to OEKO-TEX Standard 100, GOTS, and ZDHC MRSL is creating specification conflicts for blended fiber formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Winter Hats Market |
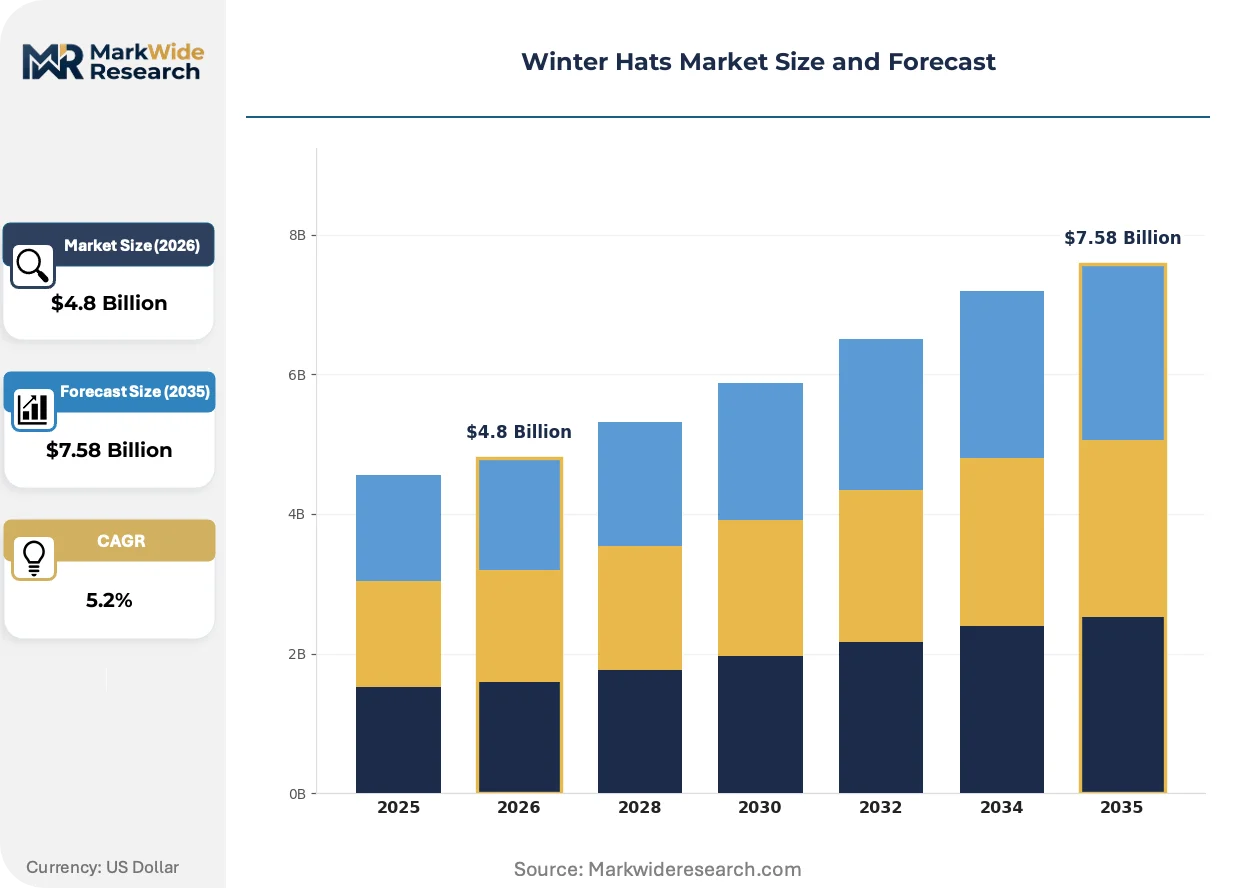
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beanies, Berets, Trappers, Knitted Caps Material: Wool, Acrylic, Fleece, Cotton Style: Casual, Formal, Sports, Fashionable Target Audience: Women, Men, Children, Unisex |
| Companies Covered | Arc'teryx Equipment Inc., Lacoste SA, Adidas AG, Icebreaker New Zealand Ltd, Mammut Sports Group AG, Columbia Sportswear Company, Carhartt, Inc., Fjallraven, Gucci, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Winter Hats Market Strategic Shifts & Innovations
Material science advances and chemical safety mandates are restructuring competitive advantage around verifiable supply chain transparency rather than cost-based manufacturing scale.
Phase-change microencapsulation technology is embedding paraffin-based thermal regulation directly into acrylic-wool yarn structures. Alpine athletes and mountaineering enthusiasts are adopting these smart textiles at accelerating rates through specialty channels. The technology is bifurcating the mid-market into performance-certified premium tiers and undifferentiated commodity beanies.
REACH Annex XVII restrictions on azo dyes and formaldehyde-based finishes are tightening under ECHA enforcement protocols. Manufacturers are reformulating textile treatments to meet Substance of Very High Concern screening thresholds or exiting European distribution entirely. High-loft merino trapper designs face the steepest reformulation costs due to complex multi-fiber construction.
Certification-driven purchasing behavior is displacing price-first selection in German and Austrian specialty retail. Buyers now demand Bluesign or GOTS documentation before placing seasonal orders, forcing undifferentiated suppliers toward discount channels. This preference shift is most visible in Munich and Innsbruck mountain sports clusters where retailer buying committees have formalized sustainability scorecards.
Winter Hats Market Segmentation
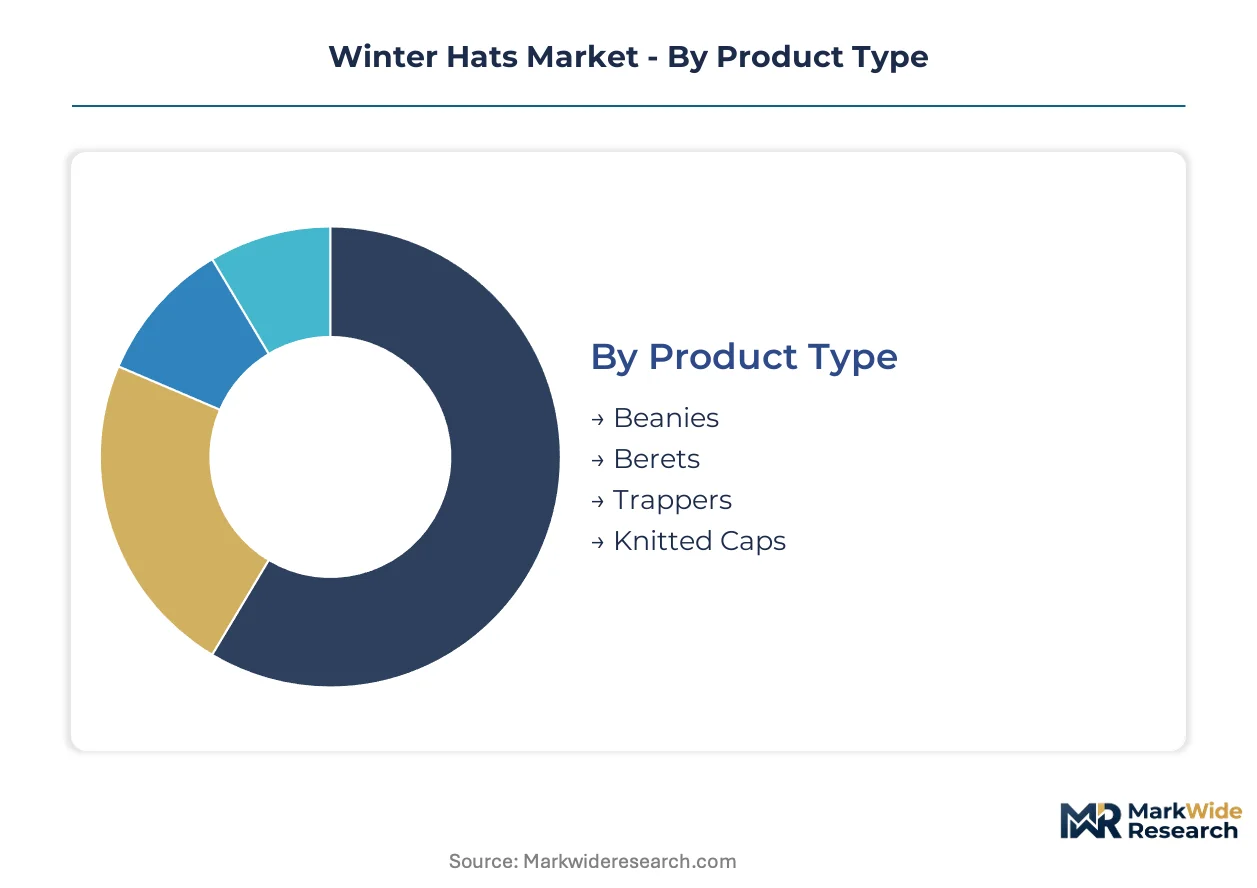
Winter hat segmentation reveals distinct channel affinities where thermal performance specifications and certification requirements reshape procurement patterns. Material composition and end-use application determine whether products flow through specialty outdoor retail, industrial workwear distributors, or fast-fashion mass merchants.
Product Type:
Channel mix varies sharply across headwear forms, with alpine specialty retailers prioritizing technical trapper constructions while urban fashion merchants stock lightweight beanies in volume.
- Beanies:Knitted skull-hugging designs in acrylic-wool blends dominate casual wear channels across German and Austrian urban centers. REACH-compliant dye formulations now filter supplier access to premium Munich and Innsbruck specialty retailers who mandate Bluesign documentation for seasonal orders.
- Trappers:High-loft ear-flap constructions with merino fleece lining command price premiums in mountain sports clusters. Austrian alpine guides and Norwegian backcountry operators specify thermal resistance values above 1.5 clo, pulling technical trapper inventory through specialty channels that reject undifferentiated commodity suppliers.
- Berets:Flat-crowned wool felt designs concentrate in fashion-forward Paris and Milan retail with minimal thermal performance requirements.
- Knitted Caps:Cuffed constructions with fold-over brims serve industrial workwear distributors in Poland and Czech Republic cold-storage logistics sectors.
Beanies dominate installed base across European distribution. Trapper designs are where expansion concentrates in alpine specialty channels.
Material:
Cost tier stratification separates certified organic supply chains from commodity synthetics, with ECHA chemical restrictions compressing margins at the low end.
- Wool:Merino and lambswool grades with GOTS certification capture premium positioning in German specialty retail. Australian and New Zealand fiber auction volatility compresses margins for producers dependent on certified organic supply chains, pushing some Italian knitters toward recycled synthetic alternatives.
- Fleece:Polyester microfiber formulations with moisture-wicking certifications dominate outdoor athlete segments. Bluesign-approved mechanical recycling advances for post-consumer polyester are lowering input costs while satisfying ECHA traceability standards for Norwegian and Swedish sustainability-conscious consumers.
- Acrylic:Synthetic polymer yarns balance wash durability with cost in mass-market casual channels.
- Cotton:Natural fiber constructions occupy transitional season fashion applications with limited thermal performance claims.
Wool retains margin leadership in certified channels. Fleece is climbing the fastest in outdoor specialty expansion.
Style:
Application context determines performance specifications, with sports styling requiring thermal certifications absent from fashion-forward segments.
- Sports:Technical headwear engineered for alpine performance integrates phase-change microencapsulation and moisture management. Swiss and Austrian mountaineering enthusiasts drive adoption of smart textiles through specialty retailers who demand documented thermal resistance values and Bluesign chemical compliance.
- Casual:Everyday beanies and knitted caps prioritize cost efficiency and wash durability over technical specifications. German mass merchants source acrylic-wool blends from vertically integrated manufacturers with captive testing laboratories that absorb REACH compliance costs.
- Formal:Structured felt and refined wool designs serve limited ceremonial and professional contexts.
- Fashionable:Trend-driven styling emphasizes aesthetic novelty with minimal thermal functional claims.
Casual styling dominates volume throughput. Sports styling is where margin expansion concentrates.
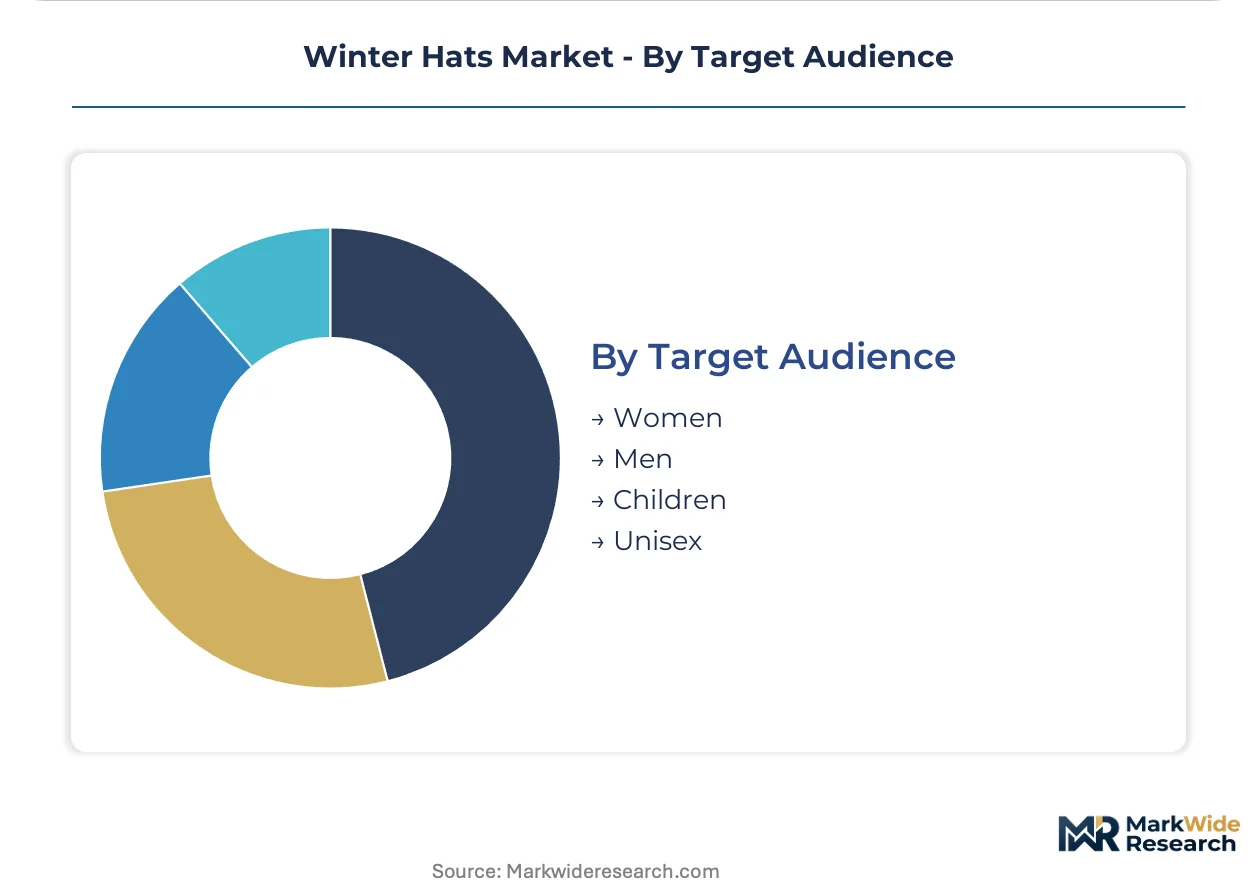
Target Audience:
Customer type shapes sizing specifications and thermal performance requirements, with children's segments facing additional flammability standards.
- Men:Larger head circumference specifications and workwear durability ratings drive industrial channel procurement. Polish and Czech Republic cold-storage logistics operators specify thermal acrylic beanies with reinforced stitching for male-dominated workforces.
- Women:Fashion-forward styling and color variety priorities concentrate in urban specialty and department store channels. Paris and Berlin retailers demand extended size runs and seasonal color freshness that strain small-batch Italian producers.
- Children:Smaller sizing with stringent US Consumer Product Safety Commission flammability requirements limits supplier pool.
- Unisex:Standardized sizing reduces inventory complexity for mass merchants serving broad demographic bases.
Men's workwear segments dominate industrial channel volume. Women's fashion styling is where premium pricing concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal textile circularity mandates are redrawing procurement geography across winter headwear distribution, with extended producer responsibility requirements rewarding manufacturers with established reverse logistics infrastructure in core European markets.
Germany
Alpine sports culture and stringent material standards converge to reward premium insulated headwear in Bavaria and North Rhine-Westphalia. ECHA REACH enforcement compresses supplier margins while creating market access advantages for vertically integrated manufacturers with in-house testing laboratories. Munich and Innsbruck mountain sports clusters formalize sustainability scorecards that mandate Bluesign documentation before seasonal orders.
United States
Industrial workwear channels prioritize durability ratings over fashion cycles in cold-storage logistics and construction sectors across the Midwest and Northeast. Consumer Product Safety Commission flammability standards for wearing apparel govern fiber content labeling and combustion safety, raising compliance costs for smaller knitwear producers. Chicago and Detroit distribution networks absorb thermal acrylic beanies through established industrial supply relationships.
Austria
Alpine guide services and backcountry operators specify thermal resistance values above 1.5 clo, pulling technical trapper inventory through specialty channels. EU Green Deal mandates on post-consumer recycling create first-mover advantages for manufacturers with reverse logistics infrastructure. Salzburg and Innsbruck retail corridors reject undifferentiated commodity suppliers in favor of performance-certified premium tiers.
France
Fashion-forward styling and color variety priorities concentrate in Paris and Lyon urban specialty channels. ANSM chemical safety oversight aligns with REACH restrictions on textile dyes and finishes, pushing manufacturers toward certified organic wool. Extended producer responsibility requirements for textile recycling dictate post-consumer material quotas that strain small-batch Italian producers serving French retailers.
Norway
Backcountry enthusiasts and sustainability-conscious consumers drive demand for biodegradable natural fiber alternatives to synthetic fleece. ECHA traceability standards reward Bluesign-approved mechanical recycling advances for post-consumer polyester. Oslo and Bergen specialty retail channels capture margin pools in outdoor segments prioritizing moisture-wicking certifications and lighter weight-to-warmth ratios.
Winter Hats Market Key Industry Players
Player mix skews toward vertically integrated outdoor apparel conglomerates with captive certification capabilities and heritage workwear specialists with industrial distribution lock-in. Market structure concentrates around three strategic archetypes: alpine technical specialists commanding thermal performance premiums, mass-market athletic brands leveraging global supply scale, and authenticity-driven workwear incumbents defending durability-rated channels. Competitive moves center on portfolio diversification into smart textile formulations and geographic expansion through specialty retail partnerships in mountain sports clusters.
Within the alpine technical tier, Arc'teryx Equipment Inc. and Mammut Sports Group AG exemplify heritage positioning anchored in high-loft merino constructions and thermal resistance specifications that dominate specialty retail in mountain regions. Columbia Sportswear Company occupies a position among scale-driven conglomerates with backward integration into fleece and wool-blend product lines that sustain REACH compliance across European distribution networks. Carhartt, Inc. represents the workwear authenticity archetype, extending thermal acrylic designs through industrial channels in North American cold-storage logistics sectors where durability ratings outweigh seasonal fashion cycles.
| Leading Market Players |
|---|
| Arc'teryx Equipment Inc. |
| Lacoste SA |
| Adidas AG |
| Icebreaker New Zealand Ltd |
| Mammut Sports Group AG |
| Columbia Sportswear Company |
| Carhartt, Inc. |
| Fjallraven |
| Gucci |
| Others |
Cost & Logistics Intelligence
Recycled polyester mechanical recycling is displacing virgin fiber inputs across European winter headwear manufacturing, simultaneously shifting supply geography toward post-consumer waste collection hubs in Germany and France while compressing raw material cost differentials between certified sustainable and conventional synthetic tiers. This substitution dynamic rewards vertically integrated producers with captive recycling infrastructure, enabling margin defense against REACH compliance cost escalation that disproportionately burdens small-batch Italian knitters dependent on Australian wool auction markets.
Pricing Analysis
Certification level creates the primary spread across winter hat tiers, with Bluesign-approved constructions commanding substantial premiums in Munich and Innsbruck specialty retail while undifferentiated acrylic-wool blends compete on cost in mass-market channels. Three-tier pricing structure separates performance-certified alpine headwear from standard casual beanies from economy workwear acrylics. Pricing pressure stems from ECHA chemical testing cost concentration that squeezes mid-tier manufacturers without captive laboratory capabilities. Industrial workwear buyers in Poland and Czech Republic cold-storage logistics exhibit highest price sensitivity, prioritizing durability-rated thermal acrylic beanies over fashion cycles, while Austrian alpine guide services demonstrate lowest sensitivity, specifying thermal resistance values above 1.5 clo regardless of cost.
Supply Chain Analysis
Italy and Portugal anchor premium knitwear finishing and dye house operations for European winter headwear distribution, while Bangladesh and Vietnam supply mass-market acrylic and cotton base constructions. Raw material flows draw from Australian and New Zealand merino wool auctions, Chinese virgin and recycled polyester fiber production, and German mechanical recycling facilities for post-consumer synthetic inputs. Supply chain risk centers on REACH Annex XVII chemical restriction expansion that threatens dye house equipment obsolescence across Northern Italian family-owned producers. Distribution runs through alpine specialty retailers in Munich and Innsbruck for technical trapper designs, industrial workwear distributors in Chicago and Detroit for thermal acrylic beanies, and fast-fashion mass merchants for undifferentiated casual caps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among vertically integrated outdoor apparel conglomerates and specialty retail buying committees, with sustainability scorecard mandates in German mountain sports clusters consolidating procurement leverage around documented chemical compliance.
For Market Incumbents: Compound certification advantages by embedding blockchain-enabled fiber traceability into digital product passport systems, capturing premium channel access as EU Green Deal extended producer responsibility mandates harden post-consumer recycling quotas. Defend position against recycled synthetic fiber technology commoditization by deepening backward integration into mechanical recycling infrastructure in Germany and France, securing captive supply of Bluesign-approved post-consumer polyester that insulates margin pools from virgin fiber price volatility.
For New Entrants and Emerging Players: Lead with biodegradable natural fiber alternatives to synthetic fleece, targeting sustainability-conscious consumer segments in Norwegian and Swedish Nordic markets where microfiber substitution pressure is accelerating. Underpenetrated industrial workwear channels in Poland and Czech Republic cold-storage logistics offer white-space expansion for thermal acrylic beanies with reinforced durability ratings, accessed through established distributor relationships rather than direct retail competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap outdoor apparel specialists possessing captive Bluesign certification capabilities but lacking reverse logistics infrastructure for EU Green Deal compliance. Long-term viability over the five-to-ten year window hinges on extended producer responsibility mandate adaptation, making reverse logistics-equipped manufacturers attractive acquisition targets. Watch ECHA enforcement protocol tightening on azo dyes and formaldehyde-based finishes as the inflection signal for accelerated consolidation among undifferentiated small-batch knitters.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Product Passport Integration | Blockchain-enabled fiber traceability enables premium pricing for verifiable recycled content claims in German specialty retail. |
| Backward Integration into Mechanical Recycling | Captive post-consumer polyester processing secures Bluesign-compliant input supply while lowering exposure to virgin fiber auction volatility. |
| Waterless Supercritical CO2 Dyeing Adoption | Eliminates REACH-restricted chemical discharge while reducing water consumption for Italian dye house equipment retrofitting. |
| Alpine Specialty Retail Partnership Expansion | Direct channel relationships with Munich and Innsbruck buying committees lock in sustainability scorecard-compliant seasonal orders. |
| Industrial Workwear Distribution Lock-In | Exclusive supply agreements with Polish and Czech Republic cold-storage logistics operators defend volume throughput against fashion cycle volatility. |
Research Approach
Desk research of ECHA regulatory filings, EU Green Deal textile circularity mandate documentation, and alpine sports participation databases preceded structured interviews with specialty retail buying committee heads, industrial workwear procurement managers, Italian knitwear plant managers, and Bluesign auditor relationship leads. Primary fieldwork combined with secondary validation against customs trade data, SEC apparel company filings, and fiber auction market reports from Australian and New Zealand wool exchanges. Bottom-up product-level volume estimates triangulated against top-down market sizing derived from retail audit data and channel shipment disclosures.
Variance decomposition across material composition, end-use application, and geographic regulatory cluster dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro drivers including EU Green Deal implementation pace and alpine sports participation trajectory. Industry-specific forecast inputs incorporated REACH chemical restriction expansion timelines and mechanical recycling technology cost curves for post-consumer polyester.
The analysis sits within stated boundaries; outcomes outside sustained ECHA enforcement intensity or accelerated EU Green Deal textile circularity mandate adoption would require recalibration. Forecasts reflect documented assumptions regarding certification-driven purchasing behavior persistence and recycled synthetic fiber technology cost reduction trajectories. Recalibration cycles align with material shifts in chemical safety regulatory enforcement protocols and extended producer responsibility mandate implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Stain-Resistant Fabric Market
Protective and Workwear Textiles
Industrial Protective Fabrics Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Sun Protective Clothing Market
Protective and Workwear Textiles
Dry Suits Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
Personal Protective Textile Market