
 Uniforms and Workwears Market | 2026-2036
Uniforms and Workwears Market Size, Share, and Industry Trends Forecast 2026-2036
Uniforms and Workwears Market Insights
Direct-to-business procurement channels is reconfiguring how uniform suppliers reach end users, compressing traditional distributor roles while expanding captive account relationships. Cintas Corporation leverages its national service infrastructure to embed rental programs inside Fortune 500 facilities. Aramark Corporation anchors its position through integrated facility-service contracts that bundle workwear with food and uniform management. Dickies competes on brand recognition in durable work apparel, extending its retail heritage into B2B uniform programs.
Uniforms and workwears encompass purpose-designed garments engineered with specified fabric weights, seam constructions, and finish treatments to meet occupational hazards, corporate identity requirements, or hygiene protocols. Protective clothing leads product-type value pools due to mandated flame-resistant and high-visibility specifications in energy and construction sectors. Corporate attire sits in a mature phase with replacement-driven demand, while medical uniforms represent the fastest-expanding category as hospital systems standardize antimicrobial fabric protocols. Blended fabrics dominate material selection by balancing durability against laundering economics across industrial laundries.
OSHA, the EU Green Deal textile frameworks, and China's GB standards collectively shape product compliance burdens and market-access requirements for cross-border uniform suppliers. REACH chemical restrictions and emerging extended-producer-responsibility rules in Europe are forcing material substitutions and supply-chain documentation upgrades. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps that could lock them out of institutional procurement channels.
Market Dynamics
Antimicrobial fabric protocols are reshaping procurement specifications across hospital systems, compressing traditional cotton-polyester blends while elevating specialized textile suppliers into tier-one vendor status.
Growth Catalysts
- OSHA workplace safety standards:Mandated flame-resistant specifications in energy and construction sectors are expanding protective clothing procurement volumes. Compliance deadlines are accelerating replacement cycles for aging workwear inventories.
- EU Green Deal textile frameworks:Extended producer responsibility rules are forcing material substitutions toward recycled and bio-based fibers. Institutional buyers are preemptively sourcing compliant uniforms to avoid procurement lockouts.
- China's industrial employment expansion:Manufacturing and logistics workforce growth is driving standardized workwear adoption across state-owned enterprises and private contractors alike.
Market Restraints
- Cotton price volatility:Input cost swings are compressing margins for blended-fabric producers who cannot pass through increases to locked institutional contracts.
- Polyester supply concentration:Petrochemical feedstock dependence on concentrated Middle Eastern and Asian suppliers creates vulnerability to energy price shocks and shipping disruptions.
- REACH chemical restrictions:Dye and finish substance bans are forcing costly reformulations and supply-chain documentation upgrades that smaller uniform vendors cannot absorb.
Strategic Opportunities
- India's manufacturing workforce expansion:Underpenetrated formal sector employment offers white space for standardized industrial workwear programs targeting textiles, automotive, and food processing plants.
- Rental-service model convergence:Bundled uniform management with facility services is displacing direct purchase in Fortune 500 accounts, creating recurring revenue pools for integrated providers.
- GB standards alignment:China's national standard harmonization with ISO protective clothing specifications is opening cross-border supplier opportunities for certified foreign manufacturers.
Industry Challenges
- Antimicrobial certification timelines:EPA and FDA dual registration requirements for medical textiles are extending product launch cycles by 18-24 months, freezing innovation pipelines.
- Legacy ERP integration:Rental program operators face friction connecting RFID-enabled garment tracking systems with client procurement platforms, delaying contract implementations.
- Specialized laundering infrastructure:Industrial laundries require capital-intensive equipment upgrades to handle emerging fabric chemistries, constraining service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uniforms and Workwears Market |
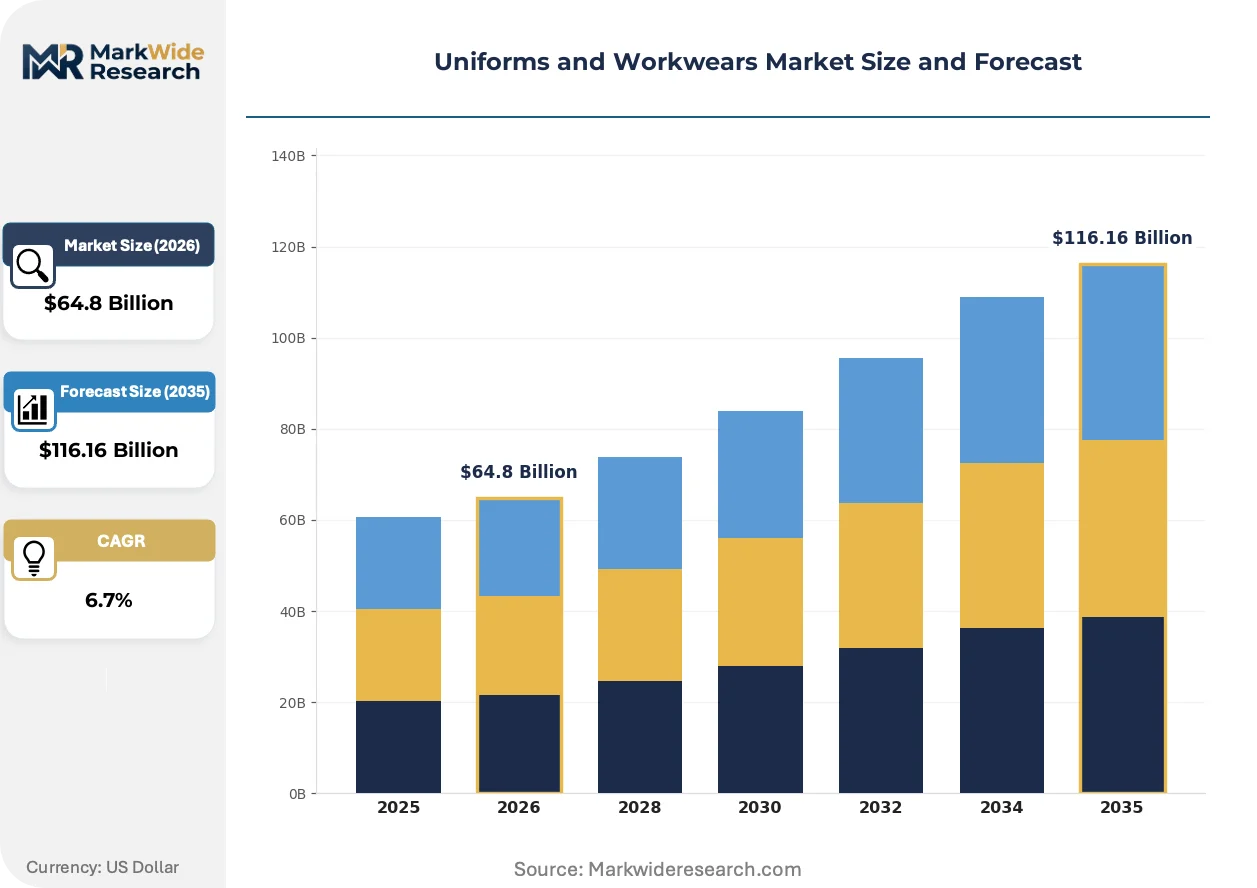
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $116.16 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protective Clothing, Corporate Attire, Medical Uniforms, Industrial Apparel End User Type: Healthcare Providers, Hospitality Services, Manufacturing Sector, Construction Firms Material: Cotton, Polyester, Blended Fabrics, Fire-Resistant Fabrics Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Bulk Orders |
| Companies Covered | Carhartt Inc, Cintas Corporation, Aramark Corporation, Red Kap, Dickies, Delta Plus Group, Engelbert Strauss Ltd, Alsico Group, UniFirst Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uniforms and Workwears Market Trends and Innovations
Smart textile integration and circular material flows are compressing traditional uniform lifecycles while elevating data-enabled service models over transactional garment sales.
Silver-ion and copper-infused antimicrobial treatments are penetrating medical uniform specifications as hospital systems prioritize infection-control protocols. Surgical and emergency departments are mandating these finishes at contract renewal. Conventional untreated cotton scrubs are rendering obsolete in acute care settings where CMS reimbursement ties to HAI reduction metrics.
REACH chemical restrictions and emerging EU Green Deal extended producer responsibility rules are forcing dye house consolidation across European supply chains. Small-batch finishers lacking substitution R&D capabilities are exiting the market. Protective clothing categories face the steepest compliance burdens as flame-retardant chemistries undergo systematic substance bans.
Direct-to-business digital procurement platforms are disintermediating traditional uniform distributors in North American and European accounts. Self-service specification tools and automated replenishment algorithms are capturing mid-market corporate attire contracts. Facility management and healthcare verticals show the fastest platform adoption as procurement teams centralize vendor management through integrated spend analytics.
Uniforms and Workwears Market Segmentation
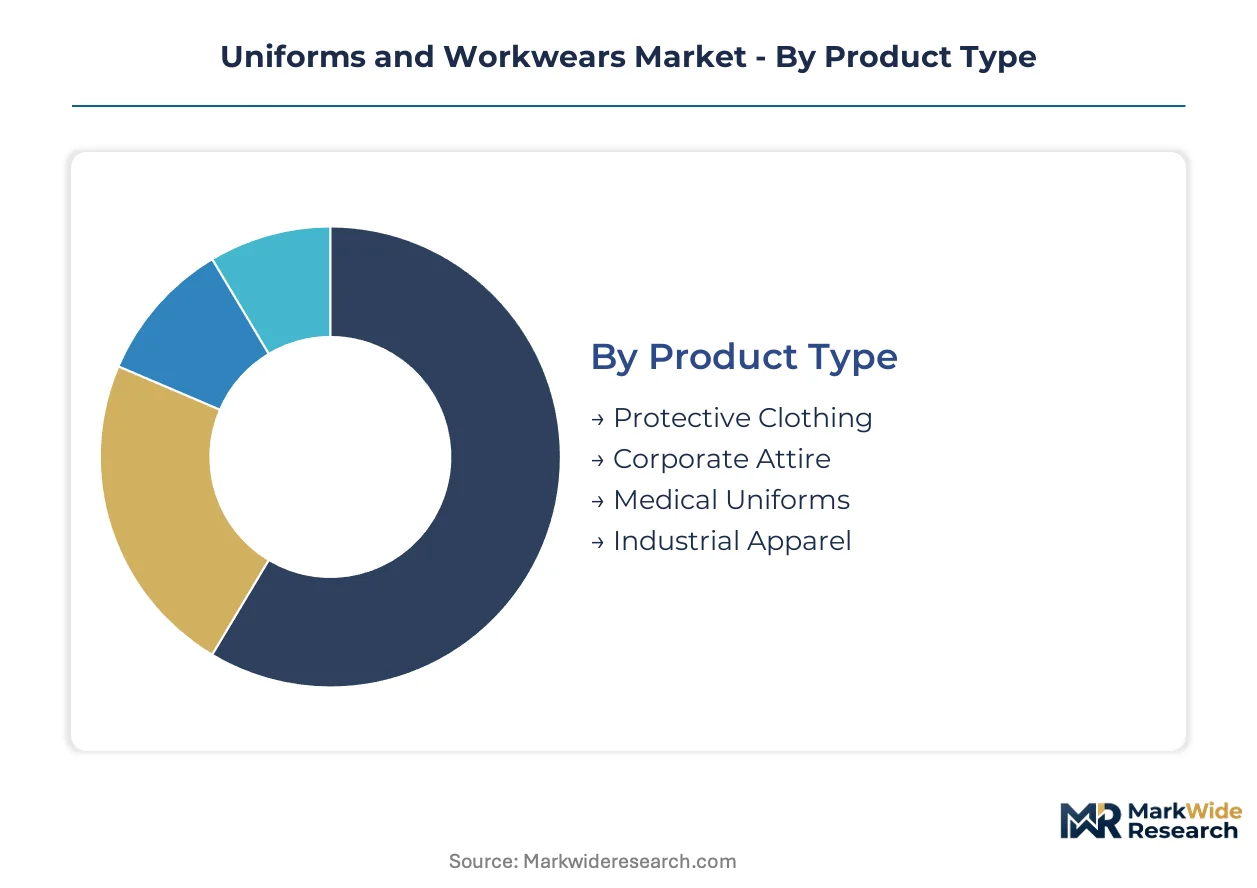
Uniform and workwear procurement varies sharply across end-use contexts, with rental-service intensity and laundering protocols dicting supplier selection criteria. Segmentation reveals where specification complexity creates pricing power versus commodity substitution risk.
Product Type:
After-sales service intensity diverges dramatically across garment categories, with rental-managed protective clothing requiring embedded logistics infrastructure while corporate attire operates on transactional replenishment models.
- Protective Clothing:Flame-resistant and high-visibility garments engineered to OSHA and EU PPE directive specifications dominate energy and construction procurement. Demand concentrates in United States shale operations and German industrial clusters where compliance audits mandate documented certification trails. Rental-service providers capture recurring revenue through embedded laundering and replacement programs.
- Medical Uniforms:Antimicrobial-finished scrubs and lab coats incorporating silver-ion or copper treatments are displacing untreated cotton-polyester blends. Hospital systems in United States, China, and Germany are standardizing infection-control protocols that tie vendor selection to HAI reduction metrics. This category is expanding most quickly as procurement specifications harden.
- Corporate Attire:Replacement-driven demand for standardized business uniforms in banking and airline sectors operates on volume contracts with limited service attachment.
- Industrial Apparel:Durable work shirts and pants for manufacturing floors prioritize laundering economics over technical performance specifications.
Protective clothing holds the largest share; momentum sits with medical uniforms.
End User Type:
Cost-tier differentiation separates healthcare and hospitality procurement—where premium antimicrobial and brand-image specifications justify price premiums—from industrial segments where per-unit cost minimization dominates vendor selection.
- Healthcare Providers:Hospital systems and long-term care facilities mandate EPA-registered antimicrobial finishes and color-coded department protocols. United States health networks are consolidating vendor panels to three preferred suppliers per region, compressing mid-tier competitors. Procurement teams weight total cost of ownership including laundering durability over upfront garment pricing.
- Manufacturing Sector:Automotive and food processing plants in China and Germany drive standardized coverall programs with high-volume, low-margin contract structures. State-owned enterprises in China are accelerating workwear standardization under GB compliance frameworks. Volume concentration enables direct mill relationships that bypass distributor markups.
- Hospitality Services:Hotel and restaurant chains prioritize brand-consistent appearance with rapid replacement cycles for stained or worn garments.
- Construction Firms:Project-based procurement of high-visibility apparel follows seasonal employment patterns with limited loyalty to specific suppliers.
Manufacturing sector holds the largest share; hospitality services are climbing the fastest as tourism recovery accelerates uniform refresh cycles.
Material:
Supply concentration in petrochemical feedstocks and natural fiber commodities creates divergent margin profiles across material categories, with specialty finishes commanding pricing premiums unavailable to commodity blends.
- Blended Fabrics:Cotton-polyester combinations balancing durability against industrial laundering economics dominate volume production. European dye houses are consolidating under REACH chemical restriction compliance burdens, reducing supplier options for institutional buyers. Blends remain the default specification where antimicrobial or flame-resistant properties are not mandated.
- Fire-Resistant Fabrics:Inherent flame-resistant fibers and chemically treated cotton meet OSHA and EU PPE requirements for electrical utility and oil field workers. United States shale patch expansion and German industrial safety enforcement are expanding specification adoption. Certification documentation requirements create vendor stickiness once contracts are awarded.
- Cotton:Price volatility in agricultural commodities compresses margins for producers locked into annual institutional contracts.
- Polyester:Petrochemical feedstock dependence on concentrated Asian and Middle Eastern suppliers creates input cost vulnerability.
Blended fabrics hold the largest share; fire-resistant fabrics are gaining share fastest as safety mandates expand across energy sectors.
Distribution Channel:
Customer-type stratification separates enterprise accounts—where direct sales and bulk order relationships dominate—from mid-market buyers increasingly migrating to digital self-service platforms.
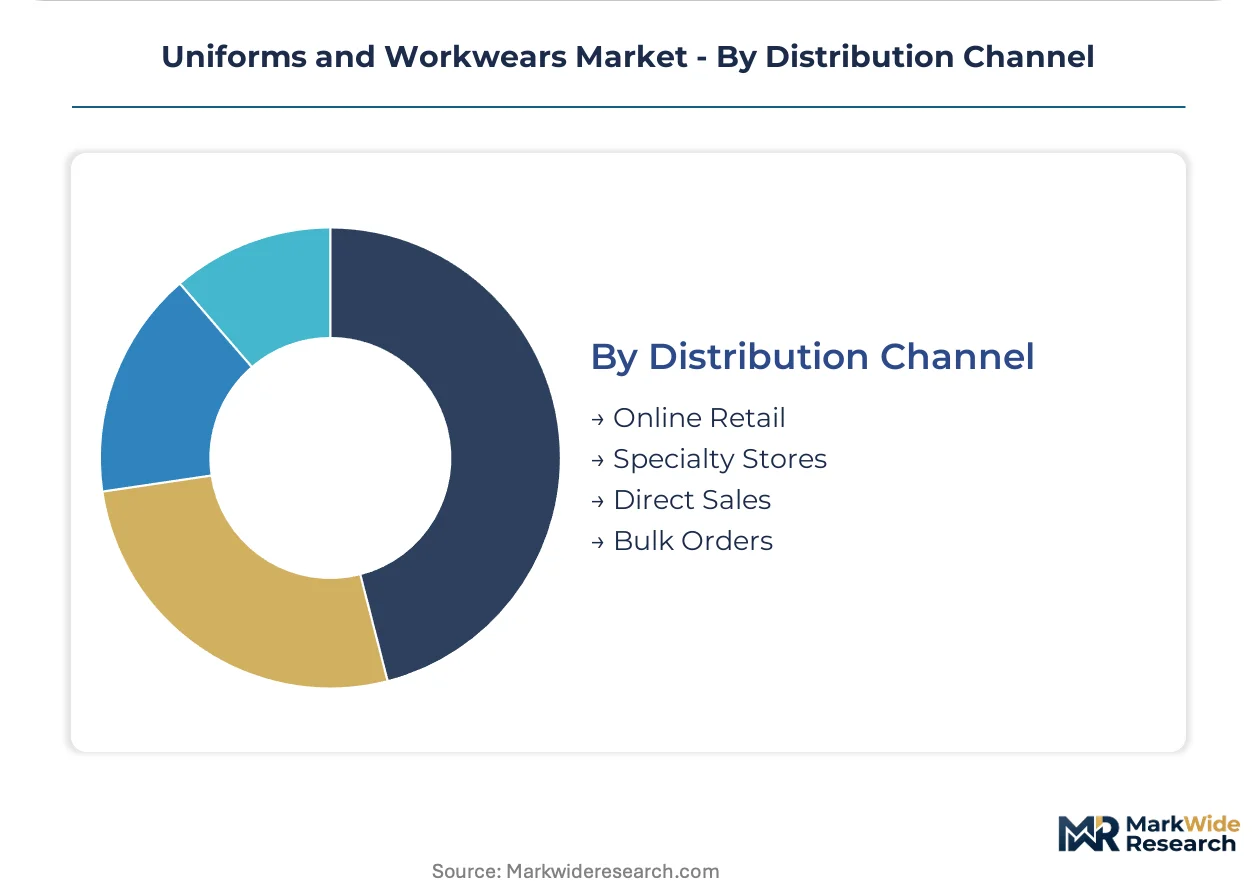
- Direct Sales:National account teams embedded in Fortune 500 facilities manage rental programs and multi-year uniform service contracts. Cintas and Aramark leverage integrated facility-service bundling to displace transactional competitors. Contract renewal rates exceed ninety percent where RFID tracking and automated replenishment systems are deployed.
- Bulk Orders:Manufacturing sector procurement through centralized buying cooperatives captures volume discounts for standardized industrial apparel. China's state-owned enterprise procurement platforms are consolidating supplier pools under GB standards compliance requirements. Direct mill relationships eliminate distributor margins for qualified large-volume accounts.
- Online Retail:Self-service specification tools are capturing mid-market corporate attire contracts with automated replenishment algorithms.
- Specialty Stores:Local uniform shops serve small-business and individual buyers with limited technical specification requirements.
Direct sales holds the largest share; online retail is expanding most quickly as procurement teams centralize vendor management through integrated spend analytics platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial clusters where compliance premiums command double-digit markups, while Chinese manufacturing zones compete on volume scale with compressed margins. Divergent regulatory burdens and labor-cost structures create persistent arbitrage opportunities for cross-border suppliers.
United States
Shale energy expansion and hospital system consolidation drive protective clothing and antimicrobial uniform procurement. OSHA enforcement deadlines accelerate replacement cycles for flame-resistant inventories in Texas and North Dakota oilfields. Midwest manufacturing belts standardize workwear programs under corporate procurement centralization.
Germany
Automotive supplier networks and chemical processing plants mandate certified protective clothing under EU PPE directive specifications. REACH chemical restrictions force dye house consolidation, reducing vendor options for institutional buyers. Bavarian industrial clusters concentrate premium-tier uniform demand with documented compliance trails.
China
State-owned enterprise procurement platforms consolidate supplier pools under GB standards alignment with ISO protective clothing specifications. Yangtze River Delta manufacturing hubs drive standardized coverall adoption across textiles and automotive plants. Dual carbon goals accelerate recycled fiber substitution in institutional uniform contracts.
India
Automotive and food processing workforce expansion creates white space for industrial workwear programs in Maharashtra and Gujarat. BIS certification requirements and PLI scheme incentives attract domestic manufacturing investment. Southern textile belts develop captive uniform production for export-oriented garment factories.
Uniforms and Workwears Market Competitive Landscape
Integrated service providers and specialized garment manufacturers split the market into distinct competitive spheres with divergent margin structures. Rental-program operators capture recurring revenue through embedded facility-service contracts, while direct-sale fabricators compete on specification compliance and volume pricing. Three archetypes dominate: national service infrastructure players, brand-heritage workwear specialists, and regional protective-clothing fabricators. Consolidation pressures favor M&A activity among mid-tier distributors, while technology licensing agreements accelerate RFID tracking adoption across rental fleets.
Within the integrated service tier, Cintas Corporation and Aramark Corporation exemplify the facility-service bundling model that displaces transactional competitors in Fortune 500 accounts. Among brand-heritage specialists, Dickies occupies a position translating retail recognition into B2B uniform program penetration. These three anchors represent divergent pathways to procurement channel access without overlapping strategic positioning.
| Leading Market Players |
|---|
| Carhartt Inc |
| Cintas Corporation |
| Aramark Corporation |
| Red Kap |
| Dickies |
| Delta Plus Group |
| Engelbert Strauss Ltd |
| Alsico Group |
| UniFirst Corporation |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta textile clusters anchor global uniform fabric capacity, with spinning and finishing concentration translating into downstream pricing leverage for compliant suppliers serving institutional buyers under GB standards and REACH frameworks.
Pricing Analysis
Configured-to-order pricing for flame-resistant and antimicrobial specifications commands spreads of 40-60 percent above standard industrial workwear baselines. Three-tier pricing structure across premium certification-grade, standard compliance, and economy unbranded levels stratifies procurement channels, with OSHA and EU PPE directive tiers capturing sticky contract renewals. Cost compression in economy blended-fabric segments is intensifying because cotton price volatility and polyester feedstock concentration prevent margin pass-through to locked annual contracts. Manufacturing sector buyers exhibit highest price sensitivity, while healthcare systems weight total cost of ownership including laundering durability over upfront garment pricing.
Supply Chain Analysis
Export-control regimes on advanced fiber technologies and finishing chemistries limit cross-border equipment transfers, constraining antimicrobial and flame-resistant capacity expansion outside established manufacturing zones. Fabric production concentrates in China, India, and Vietnam, with specialized finishing for protective clothing anchored in German and United States industrial clusters. Raw material flows draw from Middle Eastern petrochemical feedstocks, Australian cotton, and recycled fiber streams under EU Green Deal mandates. Single-source vulnerability in silver-ion antimicrobial chemical supply creates qualification bottlenecks for medical uniform vendors. Distribution runs through direct sales teams for Fortune 500 rental programs, bulk order cooperatives for manufacturing sector procurement, and emerging digital platforms for mid-market corporate attire.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Uniforms and workwears sit in early-cycle expansion as hospital system consolidation and infection-control protocol standardization drive antimicrobial fabric adoption beyond replacement-driven corporate attire demand.
For Market Incumbents: Pre-empt margin erosion in blended-fabric commoditization by embedding RFID-enabled tracking systems into rental-service contracts, creating switching costs that transactional competitors cannot replicate. Accelerate backward integration into specialized laundering infrastructure to capture service revenue pools as hospital systems consolidate vendor panels. Certification investment in dual EPA-FDA antimicrobial registration timelines defends position against emerging textile suppliers lacking regulatory affairs capabilities.
For New Entrants and Emerging Players: Establish a beachhead in India's automotive and food processing workwear segments where BIS certification requirements and PLI scheme incentives attract domestic manufacturing investment yet formal sector penetration remains underdeveloped. Target Maharashtra and Gujarat industrial corridors with direct mill relationships that bypass distributor markups for qualified large-volume accounts. Go-to-market leverage centers on GB standards alignment for cross-border certification that opens Chinese state-owned enterprise procurement platforms.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because rental-service model convergence displaces direct purchase in Fortune 500 accounts, embedding uniform management within facility-services bundling. Acquisition focus targets regional protective-clothing fabricators with documented OSHA and EU PPE certification trails that qualify for hospital system vendor consolidation. Signal to monitor is REACH chemical restriction expansion forcing dye house consolidation and reducing vendor options for institutional buyers.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Certification Investment | Dual EPA-FDA registration unlocks hospital system procurement panels under HAI reduction metrics. |
| Rental-Service Model Expansion | Bundled facility-service contracts displace transactional competitors through embedded RFID tracking systems. |
| GB Standards Alignment | Harmonization with ISO protective clothing specifications opens Chinese state-owned enterprise procurement platforms. |
| Recycled Fiber Substitution | EU Green Deal extended producer responsibility rules preempt procurement lockouts in institutional accounts. |
| Direct-to-Business Platform Development | Self-service specification tools capture mid-market corporate attire contracts through automated replenishment algorithms. |
Research Methodology
A spread of perspectives from procurement directors at hospital systems, plant managers in automotive and food processing facilities, rental-service operations executives, and regulatory affairs specialists at textile finishers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through OSHA enforcement records, EU PPE directive certification databases, Chinese GB standards filings, and customs trade data on cotton and polyester fiber flows. Bottom-up segment sizing across product type, end user, material, and distribution channel dimensions was triangulated against top-down macroeconomic indicators including industrial employment indices and healthcare capital expenditure trends.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling procurement volume trajectories against manufacturing capacity expansion and raw material input availability. Segmentation dimensions included protective clothing versus medical uniforms versus corporate attire, healthcare versus manufacturing versus hospitality end users, blended versus fire-resistant versus antimicrobial materials, and direct sales versus bulk orders versus online retail channels. CAGRs were derived from fitted trend extrapolation adjusted for regulatory inflection points including OSHA compliance deadlines and REACH substance restriction timelines. Industry-specific forecast inputs incorporated hospital system vendor consolidation patterns and shale energy employment cycles in United States oilfield protective clothing demand.
Stress conditions across cotton price volatility bands, polyester feedstock supply disruptions, and antimicrobial chemical registration delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding GB standards harmonization timelines and EU Green Deal implementation pacing. Material shifts in OSHA enforcement intensity, REACH chemical restriction scope expansion, or hospital reimbursement metric changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Industrial Protective Fabrics Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Dry Suits Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Stain-Resistant Fabric Market
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Workwear Market