
 Apparel Supply Chain Market | 2026-2036
Apparel Supply Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Apparel Supply Chain Market Intelligence
The capital-intensity gap between integrated logistics providers and brand-centric operators is collapsing as nearshoring investments demand simultaneous control of freight, warehousing, and last-mile delivery. Deutsche Post DHL Group leverages its multi-modal network to anchor European fast-fashion replenishment cycles. Kuehne + Nagel competes through digital freight platforms that compress ocean-to-rack lead times for seasonal collections. V.F. Corporation differentiates by controlling dedicated distribution centers that bypass traditional wholesale intermediaries.
The apparel supply chain encompasses the coordinated flow of raw textile inputs, intermediate garments, and finished clothing through procurement, manufacturing, finishing, and distribution stages, governed by parameters such as order lead times, inventory turnover velocity, and carbon intensity per unit shipped. Its primary commercial purpose is to match volatile consumer demand patterns with cost-optimized, responsive production and fulfillment. Clothing and footwear categories carry the largest revenue pools but face margin compression from raw material volatility and excess inventory risks. Direct-to-consumer distribution channels represent the fastest-growing structural segment as brands bypass wholesale markups and capture first-party consumer data.
The EU Green Deal's digital product passport requirements and REACH chemical compliance standards are reshaping supplier qualification criteria across European-bound production. The US FAA and DOT regulations govern air and surface freight safety standards that affect cross-border apparel logistics velocity and cost structures. Stakeholders must monitor how carbon border adjustment mechanisms and emerging bio-based material certifications will reconfigure sourcing geography decisions and capital allocation across the supply chain.
Market Dynamics
Fast-fashion order velocity is compressing replenishment cycles from weeks to days, forcing suppliers to abandon batch production for micro-lot manufacturing with embedded quality verification at each node.
Growth Catalysts
- EU Green Deal digital product passport mandates:European-bound suppliers must deploy blockchain-based traceability systems to document fiber origin, chemical inputs, and carbon footprint across tier-2 and tier-3 vendors.
- Nearshoring to Vietnam and Bangladesh:Cut-make-trim capacity expansion in these hubs reduces ocean freight exposure and aligns with tariff-advantaged sourcing strategies for US and EU brands.
- AI-driven demand forecasting:Machine learning platforms analyze social media sentiment and search trends to generate style-level demand signals 8-12 weeks ahead of traditional methods.
Market Restraints
- Cotton price volatility:Weather-driven supply shocks and speculative commodity trading create 15-40% input cost swings that contract manufacturers cannot pass through under fixed-price agreements.
- Supplier concentration in South Asia:Bangladesh and Vietnam together account for the majority of new cut-make-trim capacity, creating single-point-of-failure risk during monsoon disruptions or labor unrest.
- REACH chemical compliance:The EU's restriction on hazardous substances requires expensive laboratory testing and supplier requalification, extending new vendor onboarding timelines.
Strategic Opportunities
- India's integrated textile parks:Government-subsidized manufacturing clusters in Tamil Nadu and Gujarat offer spinning-to-garment verticality that reduces lead times for premium cotton basics.
- Direct-to-consumer micro-fulfillment:Urban dark stores and automated sortation hubs enable same-day delivery for online apparel orders, capturing first-party data abandoned by wholesale channels.
- Bio-based fiber certification:USDA BioPreferred and EU Ecolabel standards create price premiums for brands sourcing from regenerative agriculture and closed-loop chemical recycling systems.
Industry Challenges
- Legacy ERP integration:Tier-2 Asian suppliers operate on fragmented inventory systems that cannot exchange real-time production data with brand PLM platforms, forcing manual spreadsheet reconciliation.
- Skilled pattern-making shortage:Digital pattern engineers who command both 3D CAD software and traditional garment construction knowledge command 3-4x local manufacturing wages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apparel Supply Chain Market |
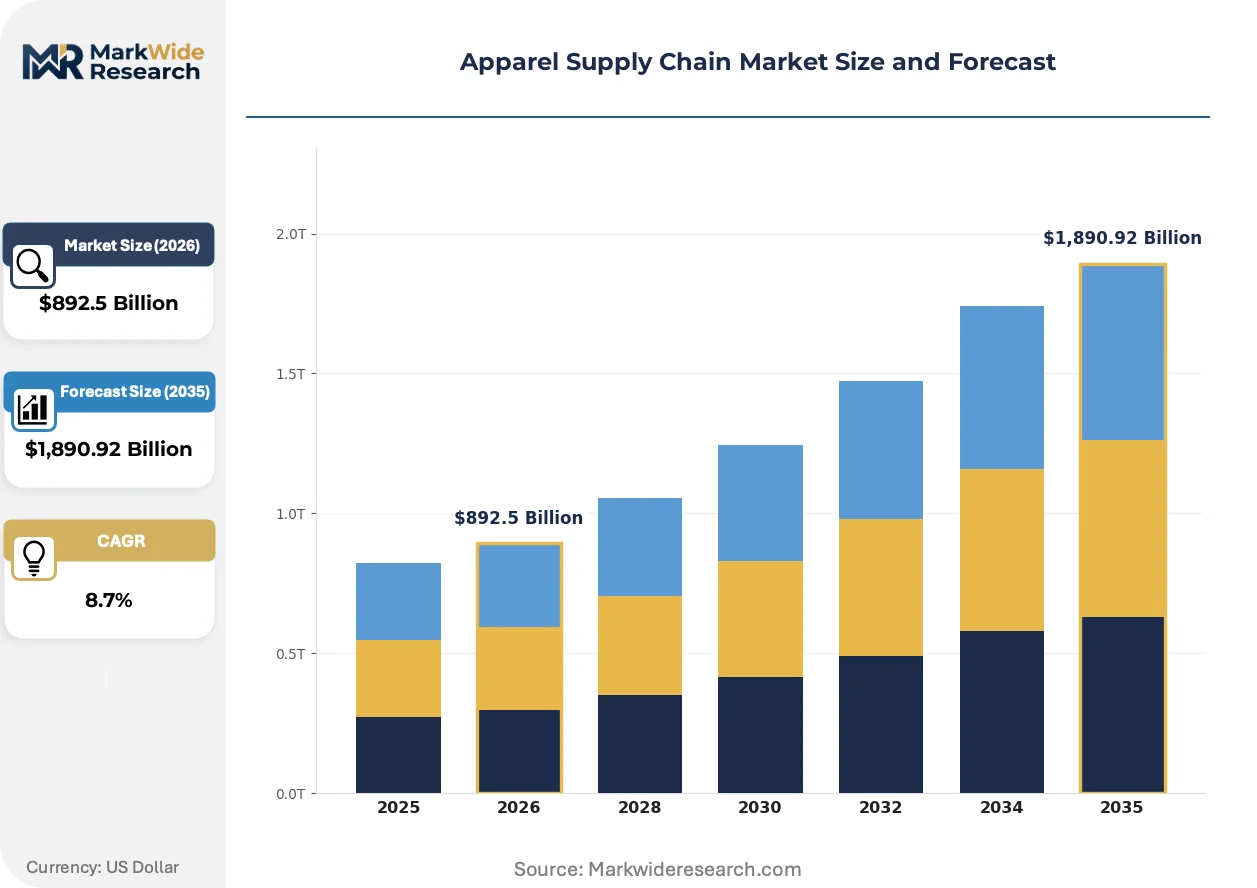
| Market Size in 2026 | $892.5 Billion |
| Market Size in 2035 | $1,890.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Footwear, Accessories, Textiles Distribution Channel: Online Retail, Brick-and-Mortar, Wholesale, Direct-to-Consumer End User: Men, Women, Children, Athletes Manufacturing Stage: Raw Materials, Cutting, Sewing, Finishing |
| Companies Covered | Deutsche Post DHL Group, DSV, PVH Corporation, Ceva Logistics, Kuehne + Nagel, Ralph Lauren Corporation, Kontoor Brands, lululemon, V.F. Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apparel Supply Chain Market Strategic Shifts & Innovations
Automation is penetrating garment finishing and quality inspection, while regulatory pressure and consumer transparency demands reconfigure supplier relationships from transactional to data-integrated partnerships.
3D virtual sampling software is miniaturizing the traditional physical prototyping workflow. Mid-market brands in Los Angeles and Barcelona now approve 80% of styles via digital renders before cutting fabric. This compression eliminates 2-3 weeks from design-to-shelf cycles and reduces sample yardage waste by half.
REACH chemical compliance deadlines are forcing dyehouses to eliminate restricted substances ahead of 2025 enforcement windows. Italian and Portuguese finishing plants are retrofitting wastewater treatment to capture heavy metals and PFCs. Premium outerwear brands now require OEKO-TEX certification as a table-stakes qualification, not a differentiator.
Micro-lot production contracts are displacing seasonal bulk orders among direct-to-consumer brands. Los Angeles-based vertical retailers now place 200-unit test orders before committing to 10,000-unit production runs. This pattern compresses inventory risk but requires Bangladeshi and Vietnamese factories to reconfigure line setups for weekly changeovers rather than monthly campaigns.
Apparel Supply Chain Market Segmentation
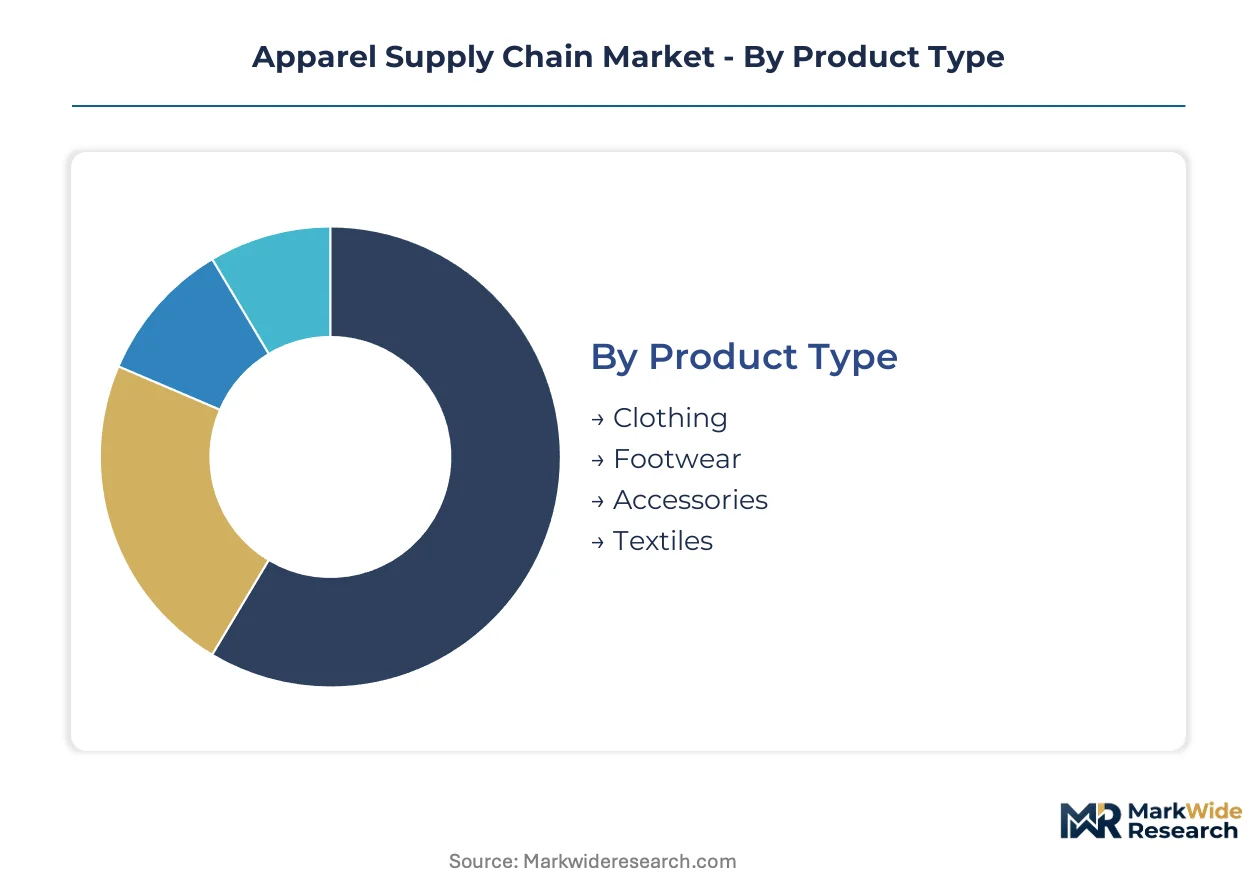
Segmentation in apparel supply chains reveals where capital allocation concentrates and which operational models face displacement from digital-native competitors. Each dimension exposes different vulnerability profiles to margin compression and regulatory compliance costs.
Product Type:
Clothing segments face the strongest substitution pressure from resale platforms and rental models, while accessories resist displacement through gifting demand and impulse purchase patterns.
- Clothing:Cotton, synthetic, and blended fabric garments constitute the volume core, spanning basics through seasonal fashion cycles. Demand concentrates in direct-to-consumer channels where Los Angeles and Barcelona-based brands deploy 3D virtual sampling to compress design-to-shelf timelines. Fast-fashion replenishment cycles now operate on days rather than weeks, forcing micro-lot manufacturing adoption.
- Footwear:Athletic and casual shoe categories require specialized last-making and injection molding capabilities distinct from apparel cut-make-trim operations. Vietnam hosts the majority of new capacity investment for US and EU-bound production, leveraging tariff advantages and reduced ocean freight exposure compared to Chinese alternatives.
- Accessories:Bags, belts, and small leather goods carry higher margin profiles than core apparel with lower size-driven return rates.
- Textiles:Fabric mills and yarn producers supply tier-2 vendors across Bangladesh and India, facing REACH chemical compliance mandates from EU-bound customers.
Clothing anchors the volume base while direct-to-consumer footwear gains share at the steepest rate.
Distribution Channel:
Cost tier differentiation separates capital-intensive fulfillment networks from asset-light wholesale intermediaries, with mid-market brands abandoning the middle ground.
- Online Retail:Third-party marketplace sales through Amazon and Zalando require compliance with platform-specific packaging and returns protocols. European fast-fashion retailers expand dedicated fulfillment networks to match accelerating order velocity, deploying urban dark stores for same-day delivery in Berlin, Paris, and Milan.
- Direct-to-Consumer:Brand-owned e-commerce captures first-party consumer data abandoned by wholesale channels, enabling AI-driven demand forecasting from social media signals. V.F. Corporation and comparable operators control dedicated distribution centers that bypass traditional intermediaries entirely.
- Brick-and-Mortar:Flagship and mall-based retail now function as showrooming nodes with ship-from-store fulfillment integration.
- Wholesale:Department store and boutique intermediaries face margin compression as brands internalize distribution.
Wholesale channels retain legacy volume while direct-to-consumer operations climb the fastest.
End User:
Application-driven segmentation separates performance-grade technical requirements from fashion-oriented discretionary purchases with diverging quality verification protocols.
- Women:The largest addressable segment spanning professional, casual, and occasion wear with the highest SKU proliferation and return rates. Demand concentrates in micro-fulfillment networks serving urban centers where Los Angeles-based vertical retailers place 200-unit test orders before scaling production.
- Athletes:Performance apparel requires OEKO-TEX certification and moisture-wicking technical specifications that command price premiums. Italian and Portuguese finishing plants retrofit wastewater treatment to meet EU Green Deal standards for premium outerwear bound for German and French markets.
- Men:Lower SKU complexity and return rates support standardized fit blocks and predictive inventory models.
- Children:Safety regulations from CPSC in the US and equivalent EU standards govern chemical and choking hazard compliance.
Women's categories anchor the volume base while athlete-focused technical apparel expands most quickly.
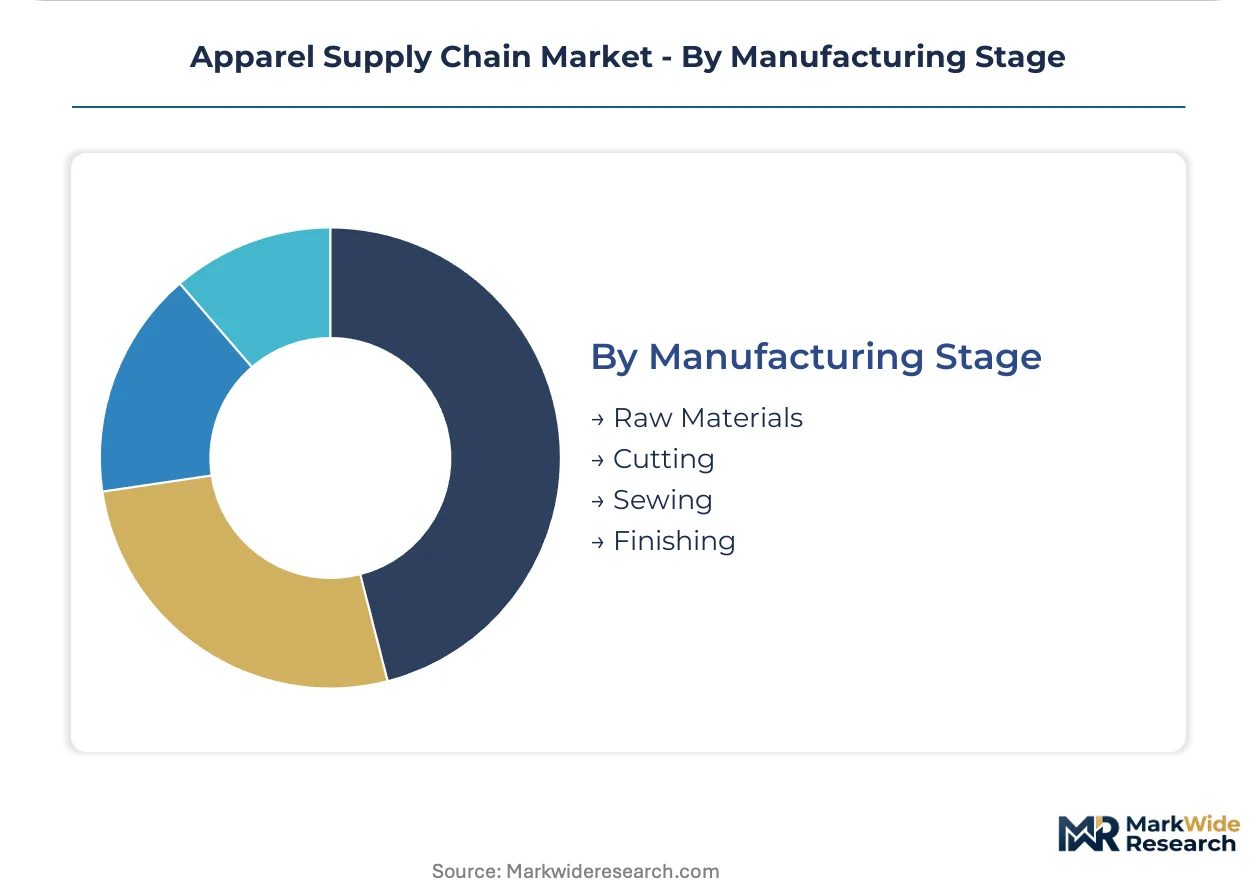
Manufacturing Stage:
Supply concentration across South Asian cut-make-trim hubs creates single-point-of-failure risk that vertical integration strategies attempt to mitigate.
- Cutting:Automated spreading and CNC cutting tables reduce fabric waste in high-volume Bangladeshi and Vietnamese factories. Tier-2 suppliers struggle with legacy ERP integration that cannot exchange real-time production data with brand PLM platforms.
- Sewing:Labor-intensive assembly operations concentrate in Vietnam, Bangladesh, and India's government-subsidized textile parks in Tamil Nadu and Gujarat. Skilled pattern engineers command 3-4x local manufacturing wages, creating capability scarcity.
- Raw Materials:Cotton price volatility from weather-driven supply shocks creates 15-40% input cost swings that contract manufacturers cannot pass through.
- Finishing:Dyeing, washing, and quality inspection face REACH chemical compliance deadlines forcing elimination of restricted substances.
Sewing operations anchor the volume base while integrated raw-materials-to-garment verticality in India gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redrawing apparel supply chain maps as brands seek tariff advantages and freight cost containment. Countries with integrated textile-to-garment infrastructure capture disproportionate capital inflows while regulatory compliance requirements fragment supplier qualification across destination markets.
United States
Direct-to-consumer fulfillment networks absorb the fastest capital deployment as Los Angeles-based vertical retailers compress design-to-shelf cycles. The FAA and DOT govern cross-border air and surface freight safety standards affecting logistics velocity. Urban dark stores in New York and Chicago enable same-day delivery for online apparel orders.
Germany
European fast-fashion replenishment cycles operate on days rather than weeks, demanding multi-modal freight coordination. The EU Green Deal and REACH chemical compliance standards mandate blockchain-based traceability for fiber origin documentation. The Rhine-Ruhr logistics corridor anchors automated sortation hubs serving Berlin, Paris, and Milan distribution networks.
Vietnam
Cut-make-trim capacity expansion concentrates new investment for US and EU-bound production leveraging tariff advantages. The country's national trade regulator administers export certification aligned with destination market requirements. Ho Chi Minh City industrial zones host the majority of new footwear and garment assembly lines.
Bangladesh
Monsoon disruption risks and labor unrest create single-point-of-failure exposure despite volume dominance in basic apparel categories. The central bank manages foreign exchange availability for raw cotton imports that constitute 15-40% of input cost structures. Dhaka and Chittagong manufacturing clusters retrofit production lines for weekly changeovers rather than seasonal bulk campaigns.
India
Government-subsidized textile parks in Tamil Nadu and Gujarat offer spinning-to-garment verticality reducing lead times for premium cotton basics. The BIS certification framework governs quality standards for export-bound production. Mumbai and Bangalore serve as design and demand forecasting hubs analyzing social media sentiment for style-level signals.
Apparel Supply Chain Market Key Industry Players
Concentration sits with integrated logistics providers and brand-centric distribution operators rather than fragmented cut-make-trim contractors. The competitive structure divides between asset-heavy freight networks and asset-light digital platforms, with mid-market players facing margin compression from both directions. Two strategic archetypes dominate: multi-modal carriers controlling ocean-to-last-mile velocity and vertically integrated brands operating captive distribution centers. Capacity expansion and strategic partnerships constitute the primary competitive moves as nearshoring investments demand simultaneous control of freight, warehousing, and fulfillment.
Within the integrated logistics tier, Deutsche Post DHL Group and Kuehne + Nagel occupy positions exemplifying multi-modal network scale, while V.F. Corporation represents the brand-centric archetype controlling dedicated distribution infrastructure that bypasses traditional wholesale intermediaries entirely.
| Leading Market Players |
|---|
| Deutsche Post DHL Group |
| DSV |
| PVH Corporation |
| Ceva Logistics |
| Kuehne + Nagel |
| Ralph Lauren Corporation |
| Kontoor Brands |
| lululemon |
| V.F. Corporation |
| Others |
Cost & Logistics Intelligence
Fixed-price garment manufacturing contracts lock in raw cotton access for Bangladeshi and Vietnamese suppliers while exposing brands to margin erosion when fiber costs spike beyond contract thresholds. This structure transfers price volatility risk downstream to contract manufacturers who cannot pass through input cost swings under multi-season agreements.
Pricing Analysis
Fast-fashion retailers anchor apparel supply chain pricing through high-volume, low-margin offtake agreements that squeeze contract manufacturer profitability. Pricing stratifies across OEKO-TEX certified premium tiers, REACH-compliant standard tiers, and uncertified economy tiers serving price-sensitive wholesale channels. Cost compression in the economy tier is intensifying because cotton price volatility from weather-driven supply shocks feeds directly into unhedged input structures. Direct-to-consumer brands demonstrate the least price sensitivity, absorbing certification premiums to capture first-party data and bypass wholesale markups.
Supply Chain Analysis
Inventory velocity in fast-fashion replenishment cycles has compressed from weeks to days, forcing micro-lot manufacturing with embedded quality verification at each production node. Supply concentrates in Bangladesh, Vietnam, and India's Tamil Nadu textile parks, where cut-make-trim operations draw from cotton, synthetic fiber, and dye chemical inputs. Single-point-of-failure risk from monsoon disruptions and labor unrest in Dhaka and Chittagong manufacturing clusters threatens continuity for basic apparel categories. Distribution runs through brand-owned direct-to-consumer fulfillment networks and third-party marketplace channels, with urban dark stores enabling same-day delivery in Berlin, Paris, and Milan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
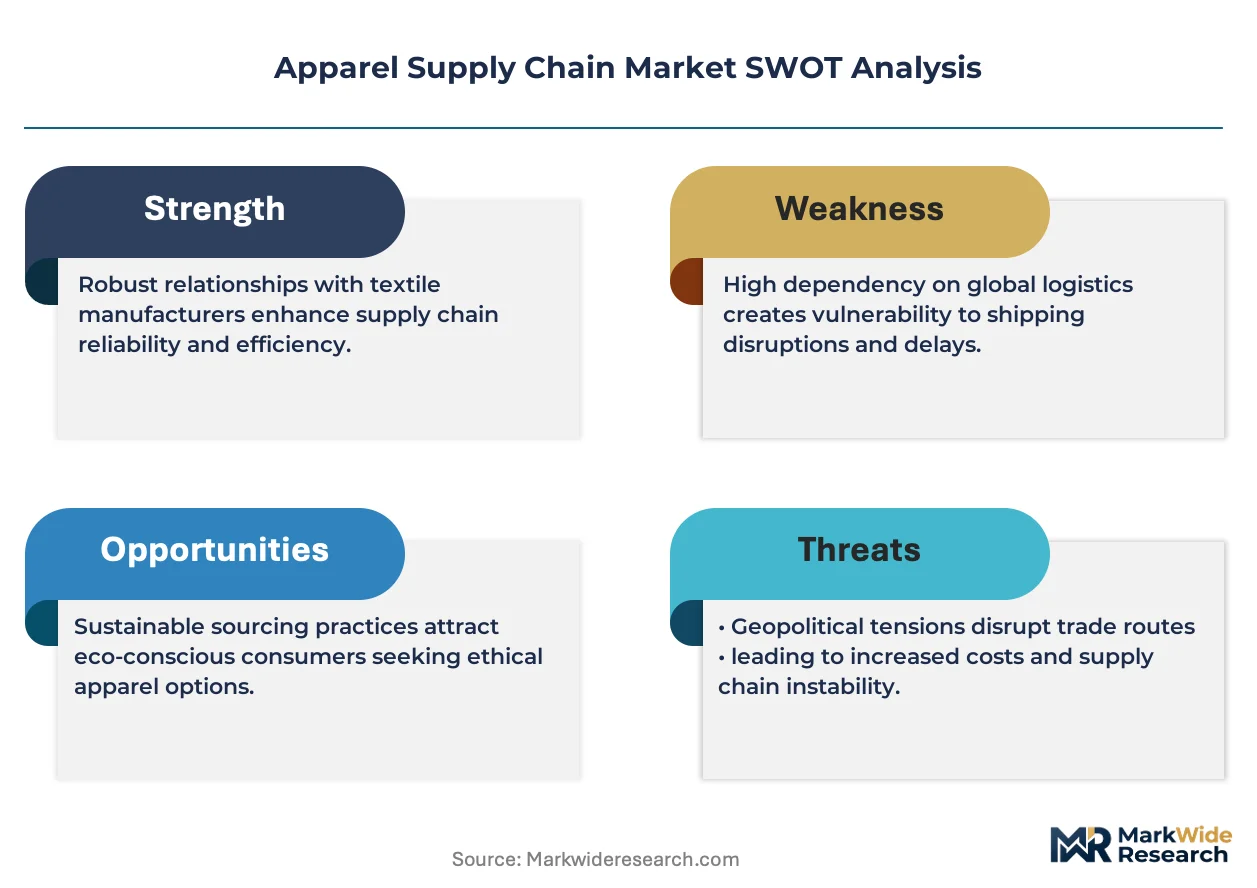
The apparel supply chain market functions as a defensive-moat arena where regulatory entrenchment around EU Green Deal traceability mandates creates sticky supplier relationships that resist displacement. Network effects in multi-modal freight coordination compound this advantage for integrated logistics operators.
For Market Incumbents: Shield market position by accelerating blockchain-based traceability deployment ahead of digital product passport enforcement windows, locking in European brand relationships through compliance entrenchment. Deepen backward integration into Vietnam and Bangladesh cut-make-trim capacity to capture tariff advantages and reduce ocean freight exposure. Invest in AI-driven demand forecasting platforms that analyze social media sentiment to generate style-level signals 8-12 weeks ahead of traditional methods.
For New Entrants and Emerging Players: Differentiate on micro-fulfillment velocity by deploying automated sortation hubs and urban dark stores serving direct-to-consumer brands with same-day delivery capabilities. Target India's government-subsidized textile parks in Gujarat and Tamil Nadu, where spinning-to-garment verticality reduces lead times for premium cotton basics and regulatory compliance costs remain below European alternatives. Pursue bio-based fiber certification as the primary go-to-market angle, capturing USDA BioPreferred and EU Ecolabel price premiums.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated logistics operators controlling ocean-to-last-mile freight networks and brand-centric distribution specialists with captive fulfillment infrastructure. Long-term viability across the projection horizon hinges on exposure to direct-to-consumer channel growth and regulatory-compliant supplier bases. Monitor carbon border adjustment mechanism implementation as the critical inflection signal that would reconfigure sourcing geography decisions and capital allocation across tier-2 and tier-3 vendor networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | EU Green Deal digital product passport mandates force tier-2 supplier system upgrades for fiber origin documentation. |
| Nearshoring Capacity Expansion | Vietnam and Bangladesh cut-make-trim investments capture tariff advantages and reduce ocean freight exposure for US and EU brands. |
| AI-Driven Demand Forecasting | Machine learning platforms analyzing social media sentiment compress design-to-shelf cycles for fast-fashion replenishment. |
| Micro-Fulfillment Network Buildout | Urban dark stores and automated sortation hubs enable same-day delivery and first-party data capture abandoned by wholesale channels. |
| Bio-Based Fiber Certification | USDA BioPreferred and EU Ecolabel standards create price premiums for regenerative agriculture and closed-loop chemical recycling systems. |
Research Approach
A standing panel of supply chain directors at fast-fashion retailers, procurement leads at contract manufacturers in Bangladesh and Vietnam, freight forwarding executives, and sustainability compliance officers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against customs and trade data, EU regulatory filings documenting REACH compliance and digital product passport progress, SEC 10-K disclosures from listed apparel brands, and IATA air freight statistics. Bottom-up segment sizing triangulated against top-down market estimates derived from production capacity data across Tamil Nadu and Gujarat textile parks.
Consistency checks validated volume and value outputs against external benchmarks including freight forwarding industry reports and apparel brand procurement disclosures across the analysis window. Segmentation dimensions modeled encompassed product type, distribution channel, end user category, and manufacturing stage, with additional granularity around certification tier and geographic sourcing cluster. CAGRs were derived from trend extrapolation of historical production and trade flows, incorporating assumptions around nearshoring velocity, direct-to-consumer channel penetration, and regulatory compliance cost pass-through.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal enforcement trajectory and stable cotton supply from major producing regions; material deviation in carbon border adjustment implementation or severe weather disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Global Maternity Innerwear Market
Apparel Textiles
Global Socks Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Rolle Market
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Welding Apparels Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Automotive Textiles Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Asia-Pacific Textile Garment Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Europe Textile Garment Market