
 Global Law Enforcement and Firefighting Protective Clothing Fabrics Market | 2026-2036
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market Foresight
Asset-light leasing models for municipal procurement is rewriting competitive dynamics in protective textiles. DuPont leverages its upstream control over para-aramid polymer supply to sustain margin capture across North American fire departments. W.L. Gore & Associates differentiates through membrane-laminate technology leadership in breathable thermal barriers. Teijin Aramid anchors Asian supply chains with consolidated spinning and weaving operations in Japan.
Law enforcement and firefighting protective clothing fabrics are engineered textile systems combining flame-resistant fibers with moisture barriers and thermal liners to achieve specified heat flux protection measured in cal/cm². Aramid fabrics dominate structural firefighting applications due to established NFPA certification pathways and proven char integrity under flashover conditions. PBI and polybenzimidazole segments command premium positioning in proximity firefighting where radiant heat exposure exceeds standard operational parameters. Ballistic protection applications for police agencies represent the fastest-growing protection level as soft armor requirements expand beyond tactical units into patrol operations.
NFPA standards in the United States, EU PPE Regulation 2016/425, and ISO 11612 thermal hazard certifications collectively mandate third-party testing that creates barriers to uncertified suppliers. The EU AI Act and CSRD reporting requirements are adding traceability obligations for fiber sourcing and chemical content disclosure across European public procurement channels. Stakeholders must monitor convergence between flame resistance and chemical protective standards as hazmat incident frequency reshapes multi-hazard ensemble specifications.
Market Dynamics
DuPont's upstream control over para-aramid polymer supply chains is concentrating margin capture among integrated fiber-to-fabric producers, forcing smaller converters into toll-processing relationships or specialty niche positioning.
Growth Catalysts
- NFPA 1971 recertification cycles:United States fire departments face mandatory ensemble replacement every five years, sustaining baseline demand for structural turnout fabrics regardless of incident frequency.
- Germany's municipal modernization wave:Preparations for updated EU PPE Regulation 2016/425 implementation are accelerating turnout gear procurement across Bavarian and North Rhine-Westphalian fire services.
- Ballistic vest liner upgrades:Flame-resistant aramid blends are displacing cotton-nylon constructions in soft armor applications as patrol units adopt tactical-grade protection.
Market Restraints
- Para-aramid feedstock concentration:Three producers control global meta- and para-aramid polymer supply, exposing fabric converters to allocation risk during demand spikes.
- Petroleum-derived PBI cost volatility:Polybenzimidazole fiber pricing tracks crude oil and acrylonitrile monomer markets, compressing margins for proximity firefighting ensemble manufacturers.
- EU AI Act traceability mandates:Fiber sourcing disclosure requirements are extending procurement timelines by 4-6 months for European public safety agencies.
Strategic Opportunities
- India's state-level police modernization:Maharashtra and Gujarat are issuing tender calls for 200,000+ ballistic vests, creating first-mover advantage for certified exporters.
- Multi-hazard ensemble convergence:Hazmat response protocols are driving demand for fabrics combining NFPA 1991 chemical splash protection with thermal barrier properties.
- Asset-light municipal leasing:Subscription-based turnout gear programs are emerging in cash-constrained US municipalities, shifting capital expenditure to operating budgets.
Industry Challenges
- NFPA third-party certification bottlenecks:UL and SEI testing facility capacity constraints are extending time-to-market for new fabric constructions by 8-12 months.
- Technical textile engineering talent scarcity:Experienced weave designers capable of optimizing tear strength-to-weight ratios in aramid blends command premium compensation.
- Legacy inventory integration:Fire departments with mixed-vendor fleets face interoperability failures between thermal liner attachment systems during emergency repairs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Law Enforcement and Firefighting Protective Clothing Fabrics Market |
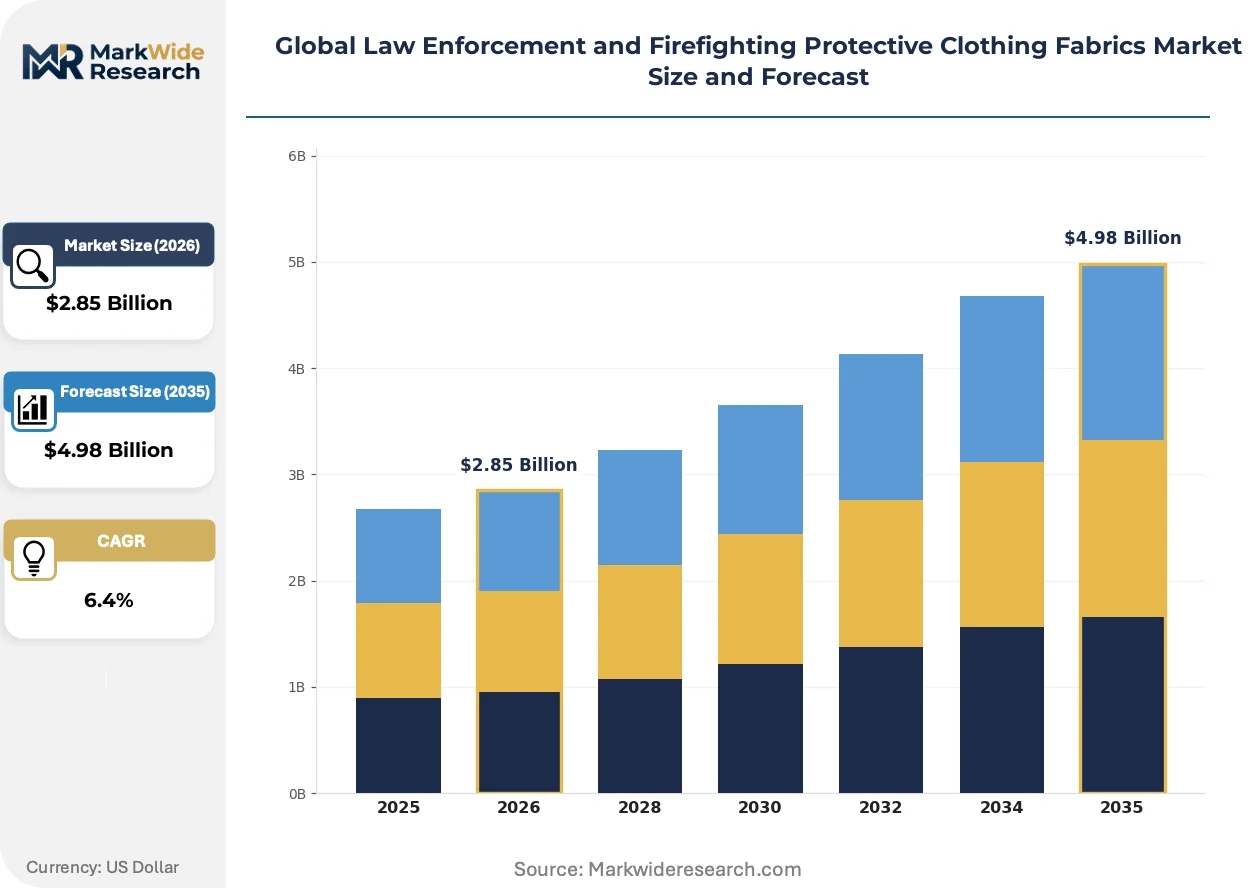
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fabric Type: Aramid, PBI, Carbon Fiber, Modacrylic, Basalt, Polybenzimidazole Protection Level: Thermal, Chemical, Ballistic, Cut Resistance, Flame Resistance, Impact Application: Firefighting, Law Enforcement, Emergency Medical Services, Rescue Operations, Hazardous Material Handling, Bomb Disposal End User: Fire Departments, Police Agencies, Paramedic Units, Rescue Teams, Military Units, Security Contractors |
| Companies Covered | Milliken & Company, Koninklijke Ten Cate, W.L. Gore & Associates, DuPont, Teijin Aramid, Solvay S.A., PBI Performance Products, Glen Raven, Klopman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market Shifts & Advancements
Membrane-laminate thermal barriers and phase-change material integration are redefining thermal protection benchmarks. Fabric systems now balance TPP ratings against total heat loss metrics in ways that strain traditional certification frameworks.
Aramid-PBI hybrid fabrics for proximity firefighting is hybridizing established supply chains. Industrial brigades at petrochemical facilities in Texas and Louisiana are specifying these constructions for radiant heat exposures exceeding 2.0 cal/cm². The technology is compressing the addressable market for pure aramid proximity offerings while expanding premium tier volume.
REACH chemical restriction amendments are forcing reformulation of durable water-repellent finishes used in outer shells. German and French textile finishers are migrating from long-chain fluorocarbons to silicone-based alternatives, sacrificing some oil repellency for regulatory compliance. Scandinavian fire services are accepting this trade-off fastest, prioritizing environmental credentials in public procurement scoring.
Consolidated purchasing cooperatives are aggregating demand across multiple US counties and municipal districts. The Southern California Regional Purchasing Cooperative now negotiates ensemble contracts exceeding 5,000 units annually, extracting volume pricing that individual departments cannot match. This concentration is marginalizing smaller regional fabric converters unable to meet scaled delivery requirements.
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market Segmentation
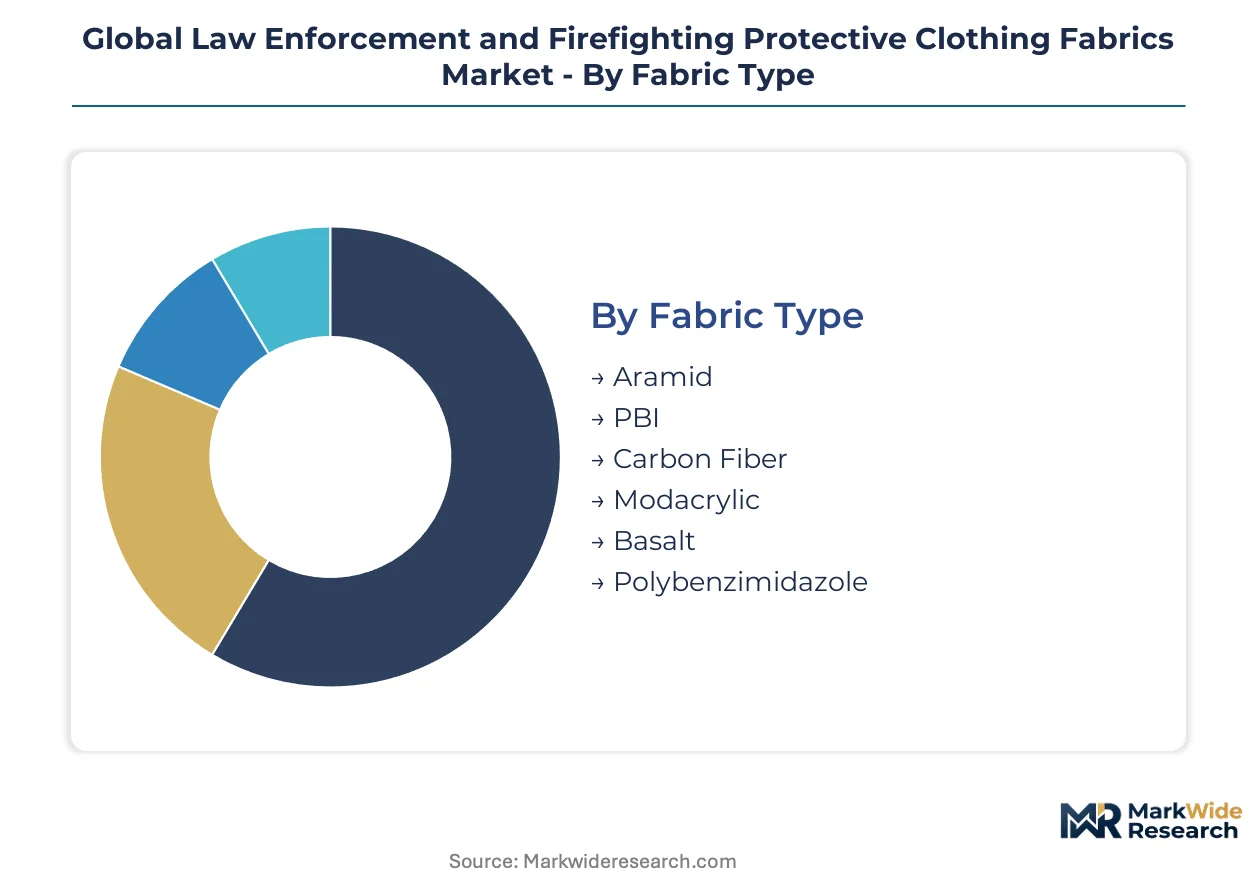
Protective clothing fabrics segment across fiber chemistry, hazard ratings, operational use cases, and institutional procurement channels. Each dimension shapes specification requirements, certification pathways, and margin structures differently.
Fabric Type:
Cost tier stratification across fiber chemistry determines volume accessibility versus performance ceiling.
- Aramid:Para-aramid and meta-aramid blends dominate structural firefighting turnout gear through established NFPA 1971 certification pathways. United States municipal fire departments in Texas and California specify these fabrics for baseline ensemble procurement, with five-year replacement cycles sustaining predictable demand.
- PBI:Polybenzimidazole fibers command premium positioning for proximity firefighting where radiant heat exposure exceeds standard operational parameters. Petrochemical industrial brigades in Louisiana and Texas specify PBI blends for radiant heat ratings above 2.0 cal/cm², accepting petroleum-derived feedstock cost volatility.
- Carbon Fiber:Lightweight high-modulus constructions serve specialized ballistic and impact protection applications.
- Modacrylic:Cost-effective flame-resistant synthetic for secondary protective layers and station wear.
- Basalt:Emerging mineral fiber alternative with thermal stability credentials.
- Polybenzimidazole:High-performance variant for extreme thermal environments.
Aramid commands the established base. The steepest expansion runs through PBI as industrial proximity specifications tighten.
Protection Level:
Application maturity varies sharply across hazard categories, with newer ratings disrupting traditional procurement patterns.
- Thermal:Established heat flux protection measured in cal/cm² remains foundational to structural firefighting ensemble design. German municipal departments ahead of EU PPE Regulation 2016/425 implementation are specifying enhanced thermal barriers with improved total heat loss metrics.
- Ballistic:Soft armor requirements are expanding beyond tactical units into routine patrol operations. Maharashtra and Gujarat state police in India are issuing tender calls exceeding 200,000 units, creating first-mover advantage for certified exporters meeting NIJ Level IIIA specifications.
- Chemical:Hazmat response protocols are driving multi-hazard ensemble convergence with NFPA 1991 splash protection requirements.
- Cut Resistance:Secondary protection for search and rescue operations with sharp debris exposure.
- Flame Resistance:Baseline specification across all public safety textile procurement.
- Impact:Specialized rating for bomb disposal and tactical entry applications.
Thermal protection anchors current procurement volumes. Ballistic specifications are climbing the fastest as patrol-grade soft armor normalizes.
Application:
Operational context dictates fabric system complexity and certification burden.
- Firefighting:Structural, wildland, and proximity sub-segments each demand distinct thermal barrier configurations. NFPA 1971 recertification cycles in the United States mandate ensemble replacement every five years, sustaining baseline fabric demand regardless of incident frequency.
- Law Enforcement:Patrol, tactical, and corrections applications are converging on flame-resistant aramid blends for ballistic vest liners, displacing legacy cotton-nylon constructions.
- Emergency Medical Services:Blood-borne pathogen and chemical exposure protection requirements.
- Rescue Operations:Technical rescue fabrics balancing cut resistance with mobility requirements.
- Hazardous Material Handling:Multi-hazard ensembles combining thermal and chemical protective properties.
- Bomb Disposal:Specialized blast and fragment protection with limited unit volumes.
Firefighting commands the established base. Law enforcement applications are gaining share fastest as patrol protection upgrades accelerate.
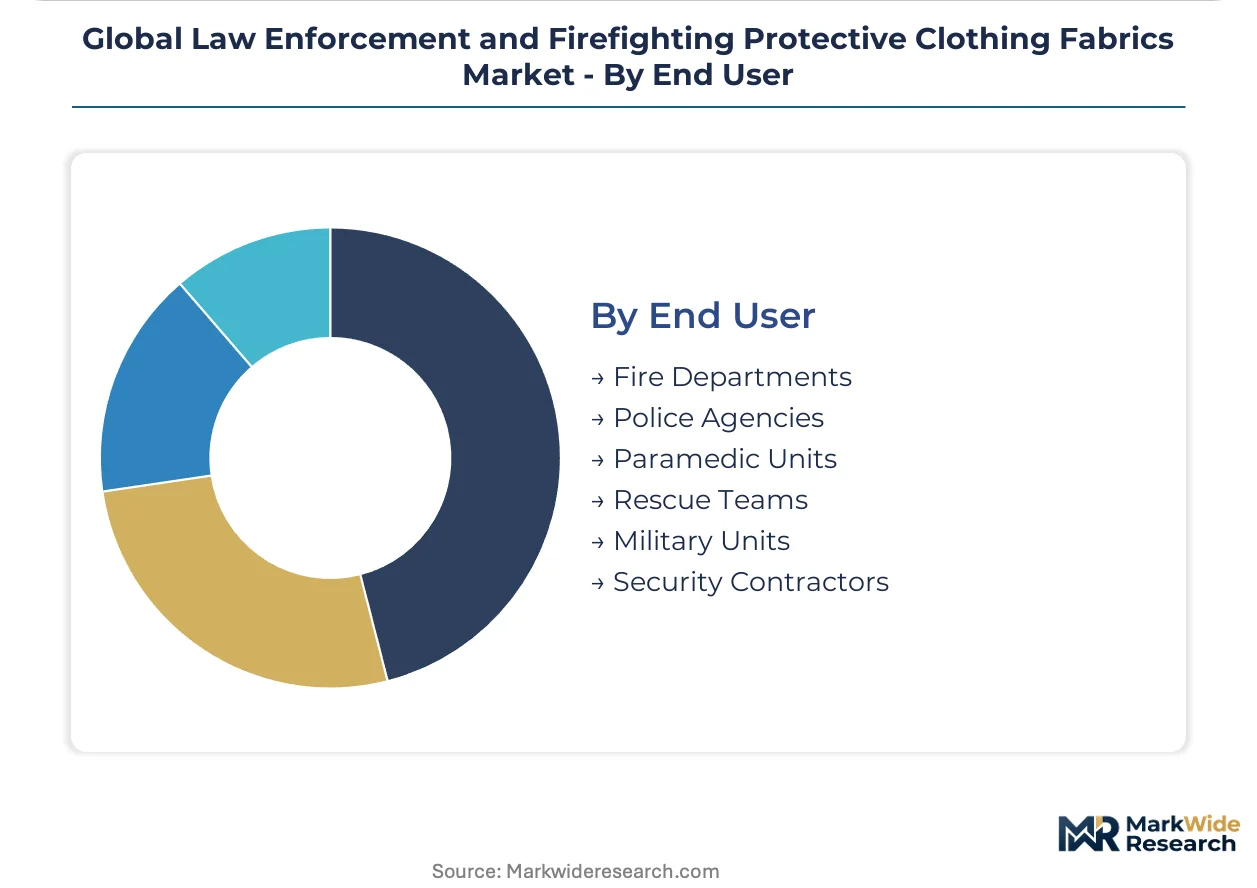
End User:
Procurement scale and decision authority concentrate differently across institutional buyer types.
- Fire Departments:Municipal, industrial, and wildland agencies represent the largest collective procurement volume. Consolidated purchasing cooperatives like the Southern California Regional Purchasing Cooperative now negotiate contracts exceeding 5,000 units annually, extracting volume pricing unavailable to individual departments.
- Police Agencies:Federal, state, and local law enforcement procurement is fragmenting across patrol vest programs and tactical unit specifications.
- Paramedic Units:Hospital-based and fire-integrated EMS services with distinct PPE requirements.
- Rescue Teams:Urban search and rescue and technical rescue specialists.
- Military Units:Specialized protective requirements outside civilian certification frameworks.
- Security Contractors:Private sector procurement with variable specification adherence.
Fire departments command the established base. Police agencies are expanding most quickly as ballistic protection normalizes across patrol operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU PPE Regulation 2016/425 implementation timelines are accelerating procurement cycles across German municipal fire services. NFPA certification requirements in the United States sustain replacement-driven demand through mandatory five-year ensemble cycles. India's state-level police modernization programs are opening new volume opportunities for ballistic fabric exporters.
United States
NFPA 1971 recertification mandates drive predictable replacement demand across Texas and California municipal fire departments. OSHA workplace safety enforcement extends flame-resistant requirements into industrial brigade procurement. Houston petrochemical clusters specify proximity-rated fabrics for radiant heat exposures exceeding standard operational parameters.
Germany
Bavarian and North Rhine-Westphalian fire services are modernizing turnout gear inventories ahead of EU PPE Regulation 2016/425 compliance deadlines. The country's national technical regulator enforces third-party testing protocols that extend procurement timelines. Munich industrial safety textile clusters are scaling membrane-laminate thermal barrier production for regional export.
India
Maharashtra and Gujarat state police departments have issued tender calls exceeding 200,000 ballistic vest units. The Bureau of Indian Standards certifies NIJ-equivalent protection levels for domestic and imported soft armor. Ahmedabad technical textile manufacturing hubs are expanding aramid weaving capacity to capture state procurement volumes.
Japan
METI industrial safety guidelines are tightening thermal protection specifications for petrochemical facility brigades. JIS standards certification creates parallel pathways alongside NFPA and EU frameworks. Nagoya automotive and chemical industry clusters are specifying multi-hazard ensemble fabrics combining flame and chemical splash resistance.
China
GB standards for firefighter protective clothing are converging toward international thermal protection benchmarks. The Ministry of Emergency Management is consolidating procurement across provincial fire services. Yangtze River Delta textile manufacturing zones are developing domestic para-aramid spinning capacity to reduce import dependency.
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market Competitive Landscape
On the supply side, the industry is consolidating around integrated fiber-to-fabric producers with captive polymer supply. Three archetypes dominate competitive positioning: upstream-integrated chemical conglomerates controlling aramid polymer production, membrane-technology specialists commanding thermal barrier laminates, and regional weaving converters serving toll-processing contracts. Dominant competitive moves include backward integration into polymer production and strategic partnerships with municipal purchasing cooperatives.
Among upstream-integrated producers, DuPont and Teijin Aramid exemplify the polymer-to-fabric archetype through captive para-aramid supply chains. W.L. Gore & Associates occupies a position within the membrane-technology tier, differentiating through breathable barrier laminates rather than fiber chemistry. These three anchors represent distinct strategic vectors: chemical feedstock control, material science specialization, and textile engineering scale.
| Leading Market Players |
|---|
| Milliken & Company |
| Koninklijke Ten Cate |
| W.L. Gore & Associates |
| DuPont |
| Teijin Aramid |
| Solvay S.A. |
| PBI Performance Products |
| Glen Raven |
| Klopman International |
| Others |
Supply & Pricing Matrix
Para-aramid polymer undercapacity across Japanese and Chinese spinning facilities is compressing converter margins while amplifying pricing power for integrated fiber producers. This utilization squeeze forces municipal buyers into longer procurement timelines and shifts contract structures toward raw-material-indexed pricing.
Pricing Analysis
Certification level (NFPA/UL/CE-grade) creates the primary spread between standard structural turnout fabrics and premium proximity-rated constructions. Three-tier pricing structure across premium, standard, and economy levels reflects fiber chemistry differentiation, with PBI blends commanding substantial premiums over pure aramid alternatives. Price erosion runs through economy-tier modacrylic offerings as Asian weaving capacity expands. Consolidated purchasing cooperatives exhibit lowest price sensitivity, while individual municipal fire departments face the tightest budget constraints.
Supply Chain Analysis
Single-source vulnerability in para-aramid polymer supply dominates risk profiles, with three producers controlling global meta- and para-aramid output from facilities in the United States, Japan, and the Netherlands. Raw material dependencies center on petroleum-derived acrylonitrile monomer, m-phenylenediamine, and isophthaloyl chloride feedstocks. Tariff exposure between the United States and China complicates membrane-laminate thermal barrier sourcing. Distribution runs through certified converter networks that toll-process fiber into finished fabrics for municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and geographic procurement channels creates multiple niche entry points. The shift toward multi-hazard ensemble specifications is spawning specialized sub-segments underserved by integrated incumbents.
For Market Incumbents: Build certification moats through accelerated NFPA 1971 and NFPA 2112 third-party testing investments. DuPont's upstream control over para-aramid supply demonstrates how captive polymer production defends margin capture against Asian converter competition. Expand toll-processing relationships with European finishers to circumvent EU AI Act traceability bottlenecks. For New Entrants and Emerging Players: India's state-level police modernization programs represent the most penetrable entry point for certified ballistic fabric exporters. Subscription-based municipal leasing models in cash-constrained US counties offer second-mover advantage without capital-intensive inventory builds. Partner with regional purchasing cooperatives to bypass individual department sales cycles. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certification barriers and polymer supply concentration favor scaled integrated producers over fragmented converters. Target membrane-technology specialists with established thermal barrier laminate portfolios. Watch for inflection in India's Bureau of Indian Standards certification timelines as signal for export volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | DuPont and Teijin Aramid demonstrate how captive para-aramid supply secures margin capture across converter tiers. |
| Membrane-Laminate Technology Licensing | W.L. Gore's breathable barrier patents enable differentiation without fiber chemistry competition. |
| Municipal Leasing Program Launch | Subscription-based turnout gear shifts capital expenditure to operating budgets for budget-constrained fire departments. |
| Multi-Hazard Ensemble Certification | NFPA 1991 chemical splash integration with thermal barriers opens premium positioning for hazmat response protocols. |
| Regional Purchasing Cooperative Partnership | Southern California Regional Purchasing Cooperative aggregation extracts volume pricing unavailable to individual departments. |
Research Methodology
A spread of perspectives from fire department procurement officers, technical textile engineers, polymer plant managers, and municipal purchasing cooperative administrators converged on the working assumptions. Primary fieldwork combined structured interviews with NFPA certification testing facility directors and woven fabric converter operations heads. Secondary validation drew from UL and SEI testing records, EU PPE Regulation 2016/425 implementation timelines, Bureau of Indian Standards tender documentation, and customs trade data on aramid fiber imports. Bottom-up demand modeling across municipal replacement cycles triangulated against top-down polymer supply capacity estimates.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation across fiber chemistry, protection level, application, and end-user institutional type. CAGRs derived from replacement cycle elasticity, regulatory implementation schedules, and state-level procurement program announcements. Industry-specific inputs included NFPA recertification timeline adherence rates and EU AI Act traceability compliance cost assumptions.
Macroeconomic conditions sit as an overlay; deviation in petroleum feedstock pricing or municipal budget cycles would shift the trajectory. Forecasts reflect documented assumptions on certification timeline adherence and polymer capacity expansion plans. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Personal Protective Textile Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Industrial Protective Fabrics Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Asbestos Gloves Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Dry Suits Market
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
Industrial Workwear Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Workwear Accessories Market