
 Rainwear Market | 2026-2036
Rainwear Market Size, Share, and Industry Trends Forecast 2026-2036
Rainwear Market Analysis
ISO 20471 high-visibility certification is redrawing competitive boundaries in industrial rainwear procurement, forcing suppliers to retool testing protocols. Columbia Sportswear Company leverages its vertical manufacturing footprint to control Gore-Tex allocation across North American retail channels. Patagonia, Inc. anchors its positioning through Bluesign-approved supply chains that command premium placement in specialty outdoor stores. Arc'teryx specializes in laminated three-layer construction for alpine environments where breathability metrics determine repurchase rates.
Rainwear encompasses waterproof or water-resistant garments engineered with taped seams, hydrostatic head ratings exceeding 10,000 mm, and DWR (durable water repellent) finishes to shed precipitation while managing internal moisture vapor. The primary commercial purpose spans occupational safety compliance, recreational outdoor activity, and urban commuter protection across variable climates. Jackets dominate value contribution due to layering compatibility and year-round utility, while ponchos gain traction in emerging markets where cost-per-use economics favor disposable or entry-level formats. Gore-Tex material commands the highest margin pool through membrane licensing fees that filter down to end-product pricing, whereas polyester volume leads unit shipments across mass-market channels.
REACH restricts perfluorinated compounds in European rainwear DWR treatments, compelling reformulation toward paraffin or silicone-based alternatives. The US EPA oversees stormwater management standards that indirectly shape municipal worker gear specifications, while India's BIS certification mandates IS 4761 visibility standards for highway maintenance crews. Stakeholders must monitor evolving chemical restriction timelines and regional procurement centralization to align R&D pipelines with compliance windows.
Market Dynamics
REACH compliance deadlines are forcing wholesale reformulation of DWR chemistries across European supply chains, compressing margins for PVC-dependent manufacturers while opening margin pools for fluorine-free alternatives.
Growth Catalysts
- High-visibility mandates:ISO 20471 certification requirements for highway maintenance crews in India under BIS standards are pulling specialized industrial rainwear into centralized procurement frameworks.
- Membrane licensing:Gore-Tex's controlled allocation system creates scarcity premiums that sustain manufacturer margins across North American specialty retail channels.
- Monsoon procurement cycles:India's seasonal agricultural labor patterns generate predictable volume spikes that favor established distribution networks with regional warehousing.
Market Restraints
- Petrochemical volatility:Polyester feedstock costs fluctuate with crude oil indices, compressing mass-market margins where price elasticity limits pass-through.
- Membrane supply concentration:ePTFE production clusters in select East Asian facilities create single-source vulnerability for premium laminate manufacturers.
- Perfluorinated compound restrictions:ECHA's tightening PFAS timelines eliminate legacy DWR chemistries before cost-parity alternatives achieve scale.
Strategic Opportunities
- Silicone-based DWR:Paraffin and silicone alternatives to fluorinated treatments command premium positioning as REACH-compliant substitutes with comparable hydrostatic performance.
- Alpine technical wear:Three-layer laminated construction for high-altitude environments creates defensible niches where breathability metrics drive repurchase loyalty.
- Direct-to-worksite distribution:Bypassing retail markup through corporate safety procurement portals captures volume from logistics and agricultural employers.
Industry Challenges
- Bluesign certification timelines:Supply chain auditing for chemical compliance extends product development cycles by 8-14 months for specialty outdoor brands.
- Seam-taping automation:Labor-intensive waterproof taping processes resist full automation, constraining throughput scaling for laminate manufacturers.
- Cross-border formulation registration:Divergent chemical notification requirements between EPA, ECHA, and India's central pollution control frameworks multiply compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rainwear Market |
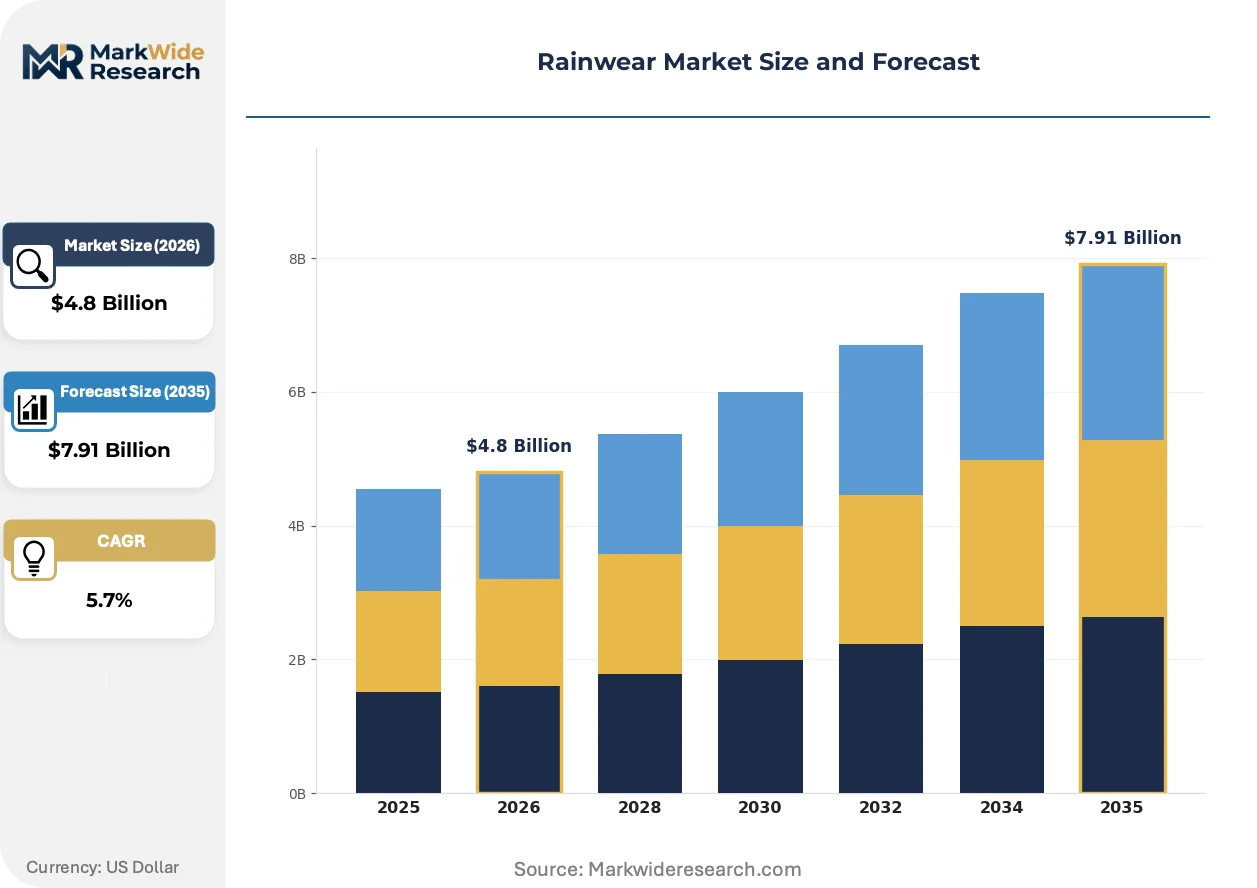
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackets, Ponchos, Umbrellas, Trousers Material: Polyester, Nylon, PVC, Gore-Tex End User: Adults, Kids, Sports Enthusiasts, Outdoor Workers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Wildcraft India Private Limited, Stutterheim, Patagonia, Inc., Marmot Mountain, LLC, Ducktail Rainwear, Columbia Sportswear Company, NZ Seasonalwear Pvt Ltd, Arc’teryx, The North Face, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rainwear Market Emerging Trajectories
Material science advances and regulatory chemistry bans are converging to restructure competitive advantage around supply chain transparency rather than performance metrics alone.
Biomimetic surface treatments modeled on lotus-leaf microstructures are supplanting conventional spray-applied DWR finishes in premium outerwear categories. Alpine equipment manufacturers are adopting these plasma-deposited nanocoatings to eliminate perfluorinated content while maintaining beading performance. The shift is compressing the addressable market for traditional C6 chemistry suppliers and redirecting R&D investment toward plasma deposition equipment.
ECHA's proposed PFAS restriction under REACH Annex XVII is eliminating long-chain fluorinated water repellents from European-sold rainwear by 2026. Manufacturers are reformulating toward short-chain C6 alternatives and silicone-paraffin hybrids, though these require more frequent reapplication. Industrial procurement in Germany and France is already specifying fluorine-free alternatives, pulling the broader European market ahead of regulatory deadlines.
Municipal safety departments are consolidating vendor relationships through multi-year framework agreements that bundle high-visibility rainwear with laundering and replacement services. This service-integrated procurement model displaces transactional spot purchasing through industrial distributors. The pattern is most advanced in US state-level highway authorities and Canadian provincial maintenance operations, where total-cost-of-ownership calculations now dominate specification decisions.
Rainwear Market Segmentation
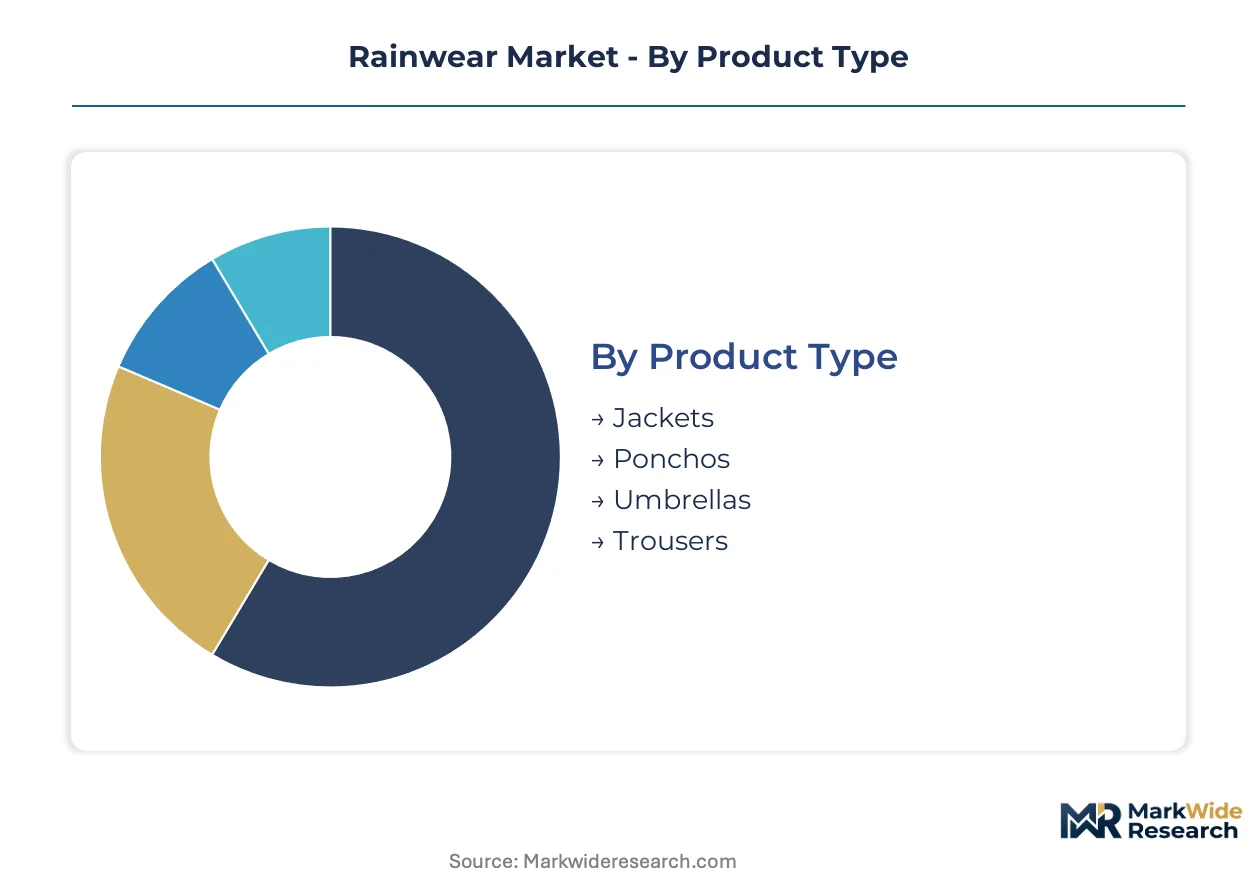
Rainwear segmentation reflects divergent compliance burdens and performance thresholds across occupational, recreational, and mass-consumer applications. Material chemistry and distribution infrastructure shape margin structures more decisively than end-use demographics alone.
Product Type:
REACH and BIS visibility mandates split procurement specifications between industrial certification requirements and consumer convenience priorities.
- Jackets:Three-layer laminated shells with taped seams and adjustable hood systems dominate technical outdoor specifications. Highway maintenance crews in India under BIS IS 4761 standards and European logistics operators under ISO 20471 drive centralized procurement of high-visibility variants with reflective tape integration.
- Ponchos:Single-sheet polyethylene or PVC constructions serve monsoon-season agricultural labor in India where cost-per-use economics favor disposable formats. Wildcraft's regional distribution network captures recurring volume from plantation and construction site bulk orders.
- Umbrellas:Collapsible canopy systems with fiberglass or steel rib structures address urban commuter protection across variable climates. Compact folding formats gain shelf space in Japanese convenience retail channels.
- Trousers:Bib-overall and waist-cut waterproof pants complete ensemble compliance for occupational safety officers specifying full-body coverage. Elasticized ankle seals and reinforced knee panels respond to kneeling-intensive maintenance work.
Established volume favors jackets; emerging adoption favors ponchos.
Material:
Feedstock cost volatility and fluorinated chemistry bans are restructuring supplier relationships around membrane licensing and coating reformulation capabilities.
- Polyester:Woven or knit base fabrics with polyurethane coatings lead unit shipments through mass-market retail channels. Crude oil index fluctuations compress margins where price elasticity limits pass-through to budget-conscious consumers.
- Nylon:High-tenacity ripstop weaves deliver abrasion resistance for tactical and military specifications. Ballistic-grade variants command placement in law enforcement and private security procurement frameworks.
- PVC:Calendered vinyl coatings face REACH restriction timelines eliminating plasticizer chemistries from European-sold product. Remaining volume concentrates in emerging market disposable segments with less stringent chemical oversight.
- Gore-Tex:Expanded polytetrafluoroethylene membranes licensed through controlled allocation sustain scarcity premiums in North American specialty retail. Breathability metrics exceeding 20,000 g/m²/24hr drive repurchase loyalty among alpine enthusiasts.
Polyester captures baseline volume; Gore-Tex claims premium margin pools.
End User:
Procurement centralization patterns separate occupational safety compliance from discretionary recreational spending.
- Adults:Urban commuters and casual outdoor participants drive replacement cycles through seasonal fashion transitions. Waterproof-breathable performance specifications migrate from technical outdoor into mainstream retail assortments.
- Kids:Growth-accommodating designs with adjustable cuffs and reflective safety elements respond to school district visibility mandates. Bright color palettes and licensed character prints influence parent purchase decisions.
- Sports Enthusiasts:Trail runners, cyclists, and mountaineers prioritize grams-per-square-meter weight targets and packability metrics. Direct-to-consumer brand relationships displace traditional retail discovery for this specification-driven segment.
- Outdoor Workers:Agricultural, logistics, and municipal maintenance employers specify IS 20471 or equivalent high-visibility certification with hydrostatic head ratings exceeding 10,000 mm. Framework agreements bundling laundering and replacement services displace transactional procurement.
Outdoor workers concentrate procurement volume; sports enthusiasts drive specification innovation.
Distribution Channel:
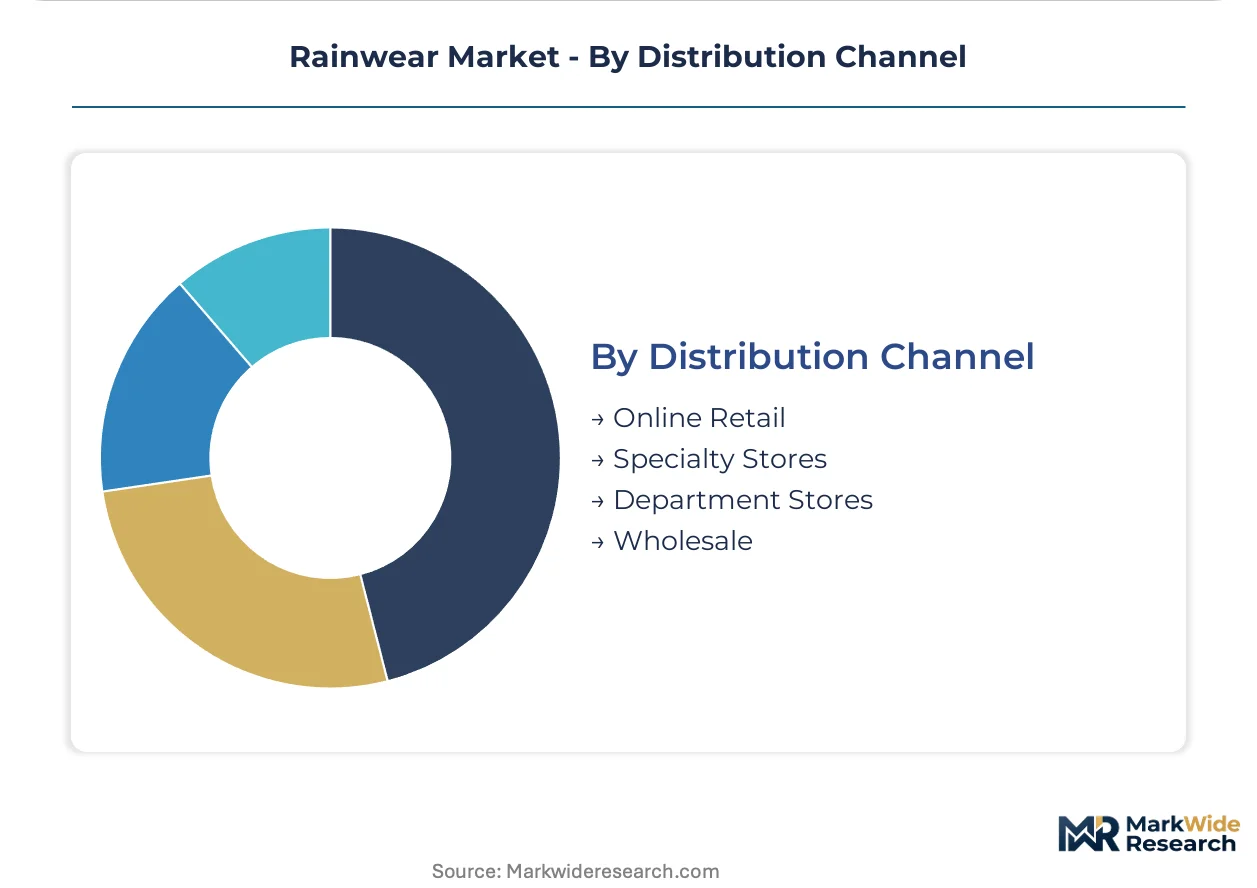
Channel selection determines margin capture and compliance documentation requirements for chemical content disclosure.
- Online Retail:Direct-to-consumer platforms enable specification comparison across hydrostatic head and breathability metrics. Return logistics complexity limits adoption for fit-critical trouser and jacket categories.
- Specialty Stores:Staff technical expertise supports Gore-Tex and comparable membrane brand storytelling. Bluesign and OEKO-TEX certification displays influence premium segment purchase confidence.
- Department Stores:Seasonal floor space allocations favor fashion-forward styling over performance specifications. Private label programs compress brand manufacturer placement during peak monsoon and back-to-school windows.
- Wholesale:Industrial distributors and corporate safety procurement portals bypass retail markup for agricultural and logistics employers. Volume rebates and multi-year framework agreements lock in supplier relationships.
Wholesale channels capture occupational volume; specialty stores defend premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance deadlines and BIS visibility mandates are redrawing procurement specifications across major rainwear consumption centers. National regulators in India, Germany, the United States, and Japan are tightening chemical content rules while expanding occupational safety coverage.
India
Monsoon-driven agricultural labor patterns generate predictable volume spikes from June through September. BIS certification under IS 4761 mandates high-visibility standards for highway maintenance crews, pulling specialized industrial rainwear into centralized government procurement frameworks. Wildcraft's distribution network dominates regional volume through warehousing clusters in Bengaluru and Mumbai that serve plantation and construction site bulk orders.
Germany
ECHA's proposed PFAS restriction under REACH Annex XVII eliminates long-chain fluorinated water repellents from European-sold rainwear by 2026. Industrial procurement in Bavaria and North Rhine-Westphalia already specifies fluorine-free alternatives, pulling the broader continental market ahead of regulatory deadlines. Technical outerwear manufacturers in Munich and Stuttgart are reformulating toward silicone-paraffin hybrid DWR treatments.
United States
EPA stormwater management standards indirectly shape municipal worker gear specifications across state-level highway authorities. Columbia Sportswear Company leverages its vertical manufacturing footprint to control Gore-Tex allocation across North American specialty retail channels. Pacific Northwest alpine equipment clusters in Seattle and Portland drive specification innovation through breathability-centric repurchase patterns.
Japan
METI energy efficiency guidelines influence material selection for urban commuter protection formats. Compact folding umbrella designs gain shelf space in Tokyo and Osaka convenience retail channels. Domestic manufacturers emphasize lightweight polyester constructions with polyurethane coatings that respond to crude oil index fluctuations.
Canada
Provincial maintenance operations in Ontario and Quebec consolidate vendor relationships through multi-year framework agreements bundling high-visibility rainwear with laundering services. Health Canada oversees chemical content disclosure requirements that align with EPA notification frameworks. Total-cost-of-ownership calculations now dominate specification decisions for municipal safety departments.
Rainwear Market Vendor Landscape
Player mix skews toward vertically integrated outdoor specialists and regional distribution-heavy operators. The vendor base separates into membrane-licensed premium brands, compliance-focused industrial suppliers, and cost-optimized mass-market fabricators. Three archetypes dominate: Gore-Tex allocation holders commanding scarcity premiums, BIS-certified industrial specialists capturing government procurement, and monsoon-season distributors leveraging regional warehousing. Competitive moves concentrate on backward integration into coating facilities and direct-to-worksite distribution bypassing retail markup.
Among North American outdoor specialists, Columbia Sportswear Company, Patagonia, Inc., and Arc'teryx occupy distinct positioning vectors. Columbia represents the vertically integrated archetype with captive manufacturing control. Patagonia exemplifies supply chain transparency positioning through certification-forward sourcing. Arc'teryx anchors the technical alpine tier where three-layer laminated construction creates defensible niche loyalty. Indian market penetration clusters around Wildcraft India Private Limited, whose distribution density exemplifies the regional warehousing archetype.
| Leading Market Players |
|---|
| Wildcraft India Private Limited |
| Stutterheim |
| Patagonia, Inc. |
| Marmot Mountain, LLC |
| Ducktail Rainwear |
| Columbia Sportswear Company |
| NZ Seasonalwear Pvt Ltd |
| Arc'teryx |
| The North Face |
| Others |
Supply Flow & Price Mechanics
Multi-year framework agreements with bundled laundering services lock in supply access for municipal highway departments while anchoring price visibility across volatile polyester feedstock cycles. These contracts compress spot-market exposure for industrial procurement officers specifying IS 20471-certified ensembles.
Pricing Analysis
Certification level creates the primary spread between premium laminate systems and mass-market polyurethane-coated alternatives. Three-tier pricing structure across Gore-Tex-licensed alpine shells, mid-tier silicone-DWR jackets, and disposable PVC ponchos reflects performance grade and compliance burden. Cost compression in entry-level segments intensifies because crude oil index fluctuations limit pass-through elasticity. Agricultural employers in India exhibit highest price sensitivity; alpine enthusiasts demonstrate lowest sensitivity to membrane-licensing premiums.
Supply Chain Analysis
Inventory lead times stretch 8-14 months for Bluesign-certified supply chains undergoing chemical compliance auditing. Manufacturing concentrates in China, Vietnam, and Bangladesh for woven base fabrics, while ePTFE membrane production clusters in Japan and the United States. Raw material flows draw from petrochemical feedstocks, fluorinated chemistry precursors, and reflective tape components. Single-source vulnerability in membrane licensing creates concentration risk. Distribution runs through specialty retail channels for premium positioning and wholesale portals for occupational volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rainwear procurement is shifting toward platform-economics logic where membrane-licensing ecosystems and compliance-certification interoperability determine supplier lock-in. The convergence of REACH chemical restrictions and BIS visibility mandates creates winner-take-most dynamics around certified supply chain transparency.
For Market Incumbents: Compound defensible positioning through captive coating facilities that absorb REACH reformulation costs while competitors face margin compression. Deepen framework agreement penetration with state-level highway authorities before procurement centralization completes. Prioritize backward integration into plasma-deposition equipment for fluorine-free DWR alternatives. For New Entrants and Emerging Players: Anchor in direct-to-worksite distribution channels that bypass retail markup for logistics and agricultural employers. Target Indian monsoon procurement cycles where Wildcraft's regional warehousing advantage has not yet extended to secondary plantation belts. Lead with silicone-paraffin hybrid DWR formulations that satisfy ECHA timelines without Gore-Tex licensing overhead. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive testing protocols for ISO 20471 and Bluesign certification. Long-term viability hinges on controlling reformulation pipelines as PFAS restrictions eliminate legacy chemistries. Watch ECHA enforcement patterns as the inflection signal for accelerated consolidation among PVC-dependent fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Facilities | Captive DWR formulation capacity absorbs REACH compliance costs before competitors face reformulation deadlines. |
| Fluorine-Free Chemistry Transition | Silicone-paraffin hybrid development secures ECHA-compliant positioning ahead of Annex XVII enforcement. |
| Direct-to-Worksite Distribution Launch | Bypassing retail markup captures volume from logistics employers consolidating procurement through safety portals. |
| ISO 20471 Certification Investment | High-visibility testing protocols unlock centralized government procurement frameworks in India and Germany. |
| Membrane Licensing Partnership | Gore-Tex allocation agreements sustain scarcity premiums in North American specialty retail channels. |
Methodological Framework
Cross-validation between trade customs data and specialty retail channel audits anchors the qualitative findings on material flow and pricing dynamics. Primary interviews with procurement officers at municipal highway authorities, plant managers at coating facilities, and category buyers at outdoor specialty retailers combined with secondary validation from BIS certification registries, ECHA restriction timelines, and SEC filings from vertically integrated manufacturers. Bottom-up volume modeling and top-down value triangulation reconcile shipment data with membrane-licensing revenue disclosures.
Sensitivity analysis across feedstock cost scenarios and regulatory enforcement timelines shapes the analytical framework. Segmentation dimensions include product type, material chemistry, end-user procurement pattern, and distribution channel structure across the projection horizon. CAGRs derive from modeled unit economics and replacement cycle frequencies. Forecast inputs incorporate monsoon seasonality patterns and REACH compliance phase-in schedules.
Decision-makers should treat outputs as directional under base assumptions of steady petrochemical pricing and phased regulatory enforcement; material deviation in crude oil volatility or accelerated PFAS bans would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
Sun Protective Clothing Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Fabric Protection Market
Protective and Workwear Textiles
High Visibility Clothing Market
Protective and Workwear Textiles
Global Industrial Protective Clothing Fabrics Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Winter Hats Market
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
Stain-Resistant Fabric Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Industrial Curtains Market