
 Welding Curtains Market | 2026-2036
Welding Curtains Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Curtains Market Analytics
Aftermarket service revenue for welding curtain maintenance and replacement is reshaping margin distribution across the value chain. Lincoln Electric leverages its integrated welding equipment ecosystem to bundle curtain solutions with system sales. Singer Safety specializes in custom-engineered industrial partitioning, occupying a niche in high-temperature fabrication environments. 3M sustains technology leadership through advanced polymer films that extend product lifecycles in heavy-duty applications.
Welding curtains are engineered protective barriers, typically constructed from PVC, polycarbonate, or coated vinyl composites in thicknesses ranging from 0.35 mm to 1.5 mm, designed to contain ultraviolet radiation, sparks, and molten spatter in welding and cutting operations. Their primary purpose is to establish modular safety perimeters that protect adjacent workers and equipment while maintaining visual access to welding zones. Flame retardant variants command premium positioning due to stricter facility insurance requirements, while portable configurations represent the fastest-expanding format as job shops prioritize reconfigurable floor layouts. Polycarbonate materials lead in optical clarity applications, though PVC dominates on unit economics across high-volume manufacturing end users.
OSHA General Industry Standards and ANSI Z49.1 welding safety codes directly shape product specifications, mandating minimum opacity ratings and flame resistance certifications that determine market access. The EPA monitors volatile compound emissions from vinyl curtain manufacturing, influencing material substitution trends toward lower-emission polymer formulations. Stakeholders must monitor evolving state-level workplace safety amendments and polymer recycling mandates that will redefine cost structures and supplier qualification criteria.
Market Dynamics
Facility retrofit cycles in automotive and heavy equipment manufacturing are compressing replacement timelines for welding curtains as OSHA intensifies spark containment inspections and insurers tighten coverage requirements for uncertified barriers.
Growth Catalysts
- ANSI Z49.1 compliance deadlines:Fabrication shops across the United States face mandated upgrades to flame-resistant barrier systems, forcing systematic replacement of legacy vinyl curtains with certified polycarbonate alternatives.
- Reshoring of metal fabrication:Domestic production capacity expansion in the United States is generating greenfield facility construction and welding bay modernization at scale.
- Polycarbonate optical clarity:Advanced polymer formulations enable continuous weld monitoring without curtain repositioning, accelerating adoption in precision aerospace component manufacturing.
Market Restraints
- Petrochemical input volatility:PVC and vinyl composite feedstock costs fluctuate with crude oil derivatives, compressing margins for standardized curtain producers.
- Specialized coating supplier concentration:Flame-retardant additive production clusters in Germany and China, creating geographic vulnerability in supply continuity.
- Technical limitation in extreme heat:Polycarbonate variants degrade above sustained 120°C exposure, restricting deployment in plasma cutting operations.
Strategic Opportunities
- Underpenetrated Mexican manufacturing:Nearshoring investments in automotive stamping and appliance metalworking lack standardized welding safety infrastructure, creating first-mover positioning for certified suppliers.
- Regulatory tailwind from EPA vinyl emissions rules:Lower-emission polymer formulations gain preferential qualification status in federal procurement, advantaging reformulation-capable manufacturers.
- Technology convergence with IoT-enabled facility monitoring:Smart curtain systems integrating occupancy sensors and air quality feeds command premium positioning in automated fabrication environments.
Industry Challenges
- Weld safety technician certification gaps:Qualified inspectors for ANSI Z49.1 compliance verification remain scarce in secondary manufacturing markets, delaying facility certification timelines.
- Integration complexity with legacy crane systems:Overhead material handling equipment in established plants requires custom curtain mounting retrofits, extending installation cycles and labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Curtains Market |
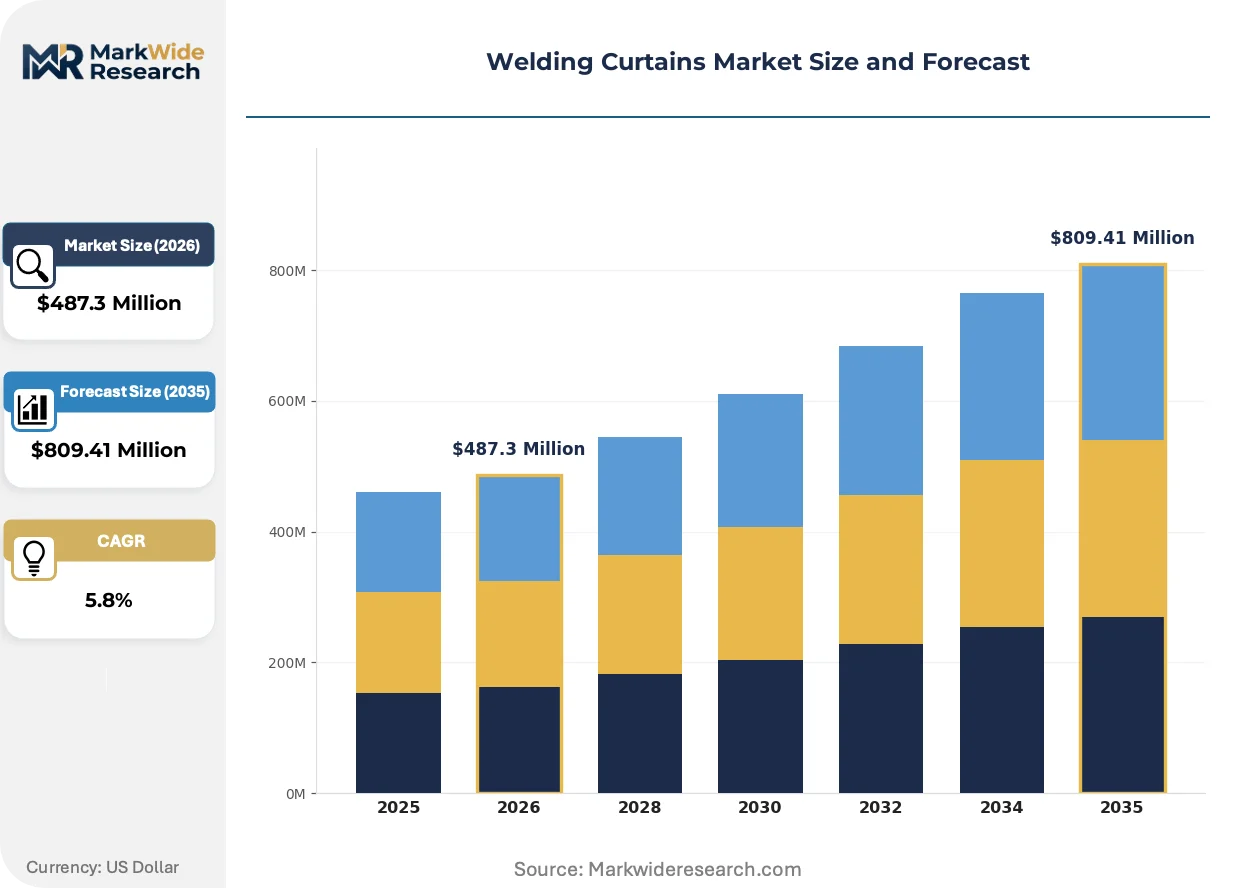
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Flame Retardant, Fixed, Portable Material: Polycarbonate, PVC, Canvas, Vinyl Thickness: Lightweight, Standard, Heavy-Duty, Extra Heavy-Duty End User: Manufacturing, Construction, Automotive, Metal Fabrication |
| Companies Covered | Lincoln Electric, 3M, ESAB, Honeywell, Kemper, Chase Doors, Singer Safety, Aerservice Equipments, Weldas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Curtains Market Evolving Landscape
Digital specification tools and modular installation systems are compressing procurement-to-deployment cycles for welding safety infrastructure, while material science advances extend product lifecycles in high-duty-cycle environments.
Transparent ceramic-coated films are virtualizing traditional opaque barrier functions by enabling real-time weld pool visibility through smartphone-connected augmented reality overlays. Automotive OEMs in Michigan and Ohio pilot these systems in electric vehicle battery tray welding lines, reducing operator neck strain from repeated curtain repositioning while maintaining UV protection ratings. The technology is virtualizing quality control workflows by integrating weld seam documentation directly into production monitoring systems.
REACH restrictions on halogenated flame retardants are forcing reformulation of vinyl curtain coatings across European fabrication facilities, with ECHA substance evaluations accelerating substitution timelines for chlorinated additives. German automotive suppliers now specify phosphorus-based alternatives in supplier qualification documents, while Italian job shops face inventory obsolescence risks from non-compliant legacy stock.
Subscription-based barrier replacement programs are displacing capital purchase models among mid-sized metalworking shops in the United States, with distributors bundling scheduled curtain exchanges into facility maintenance contracts. This reconfiguration shifts margin capture toward service providers and compresses manufacturer direct sales channels, particularly in the Great Lakes industrial corridor where multi-site fabrication groups prioritize predictable operating expenditures over asset ownership.
Welding Curtains Market Segmentation
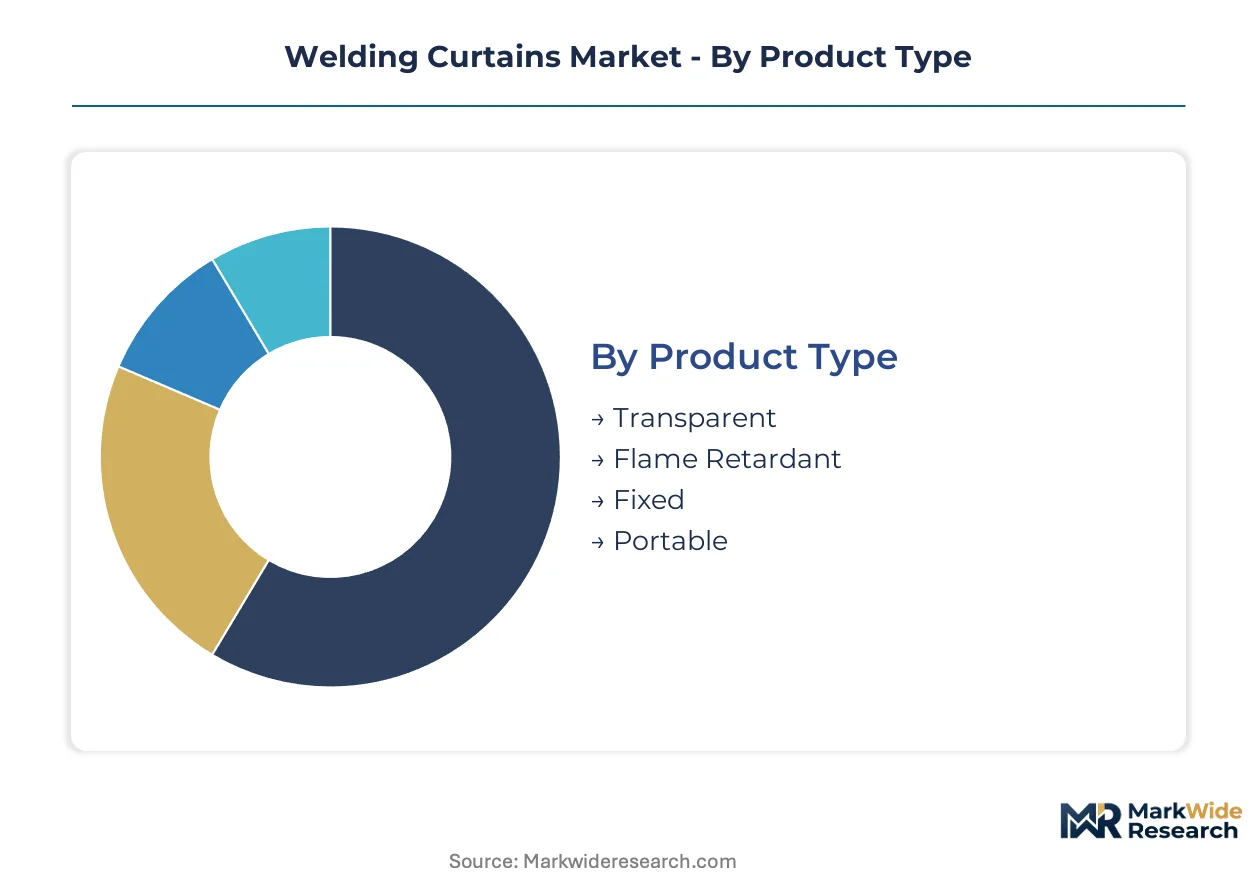
Welding curtain segmentation reflects divergent performance requirements across fabrication environments. Material selection and mobility configuration determine compliance eligibility and lifecycle economics for facility operators.
Product Type:
Mature formats dominate installed base while emerging configurations capture retrofit demand.
- Transparent:Optical-grade polycarbonate or coated vinyl formulations enable continuous weld pool monitoring without curtain repositioning. Precision aerospace component manufacturers in the United States specify these for robotic welding cells where visual verification is mandatory.
- Flame Retardant:Halogenated or phosphorus-based chemical treatments elevate ignition resistance ratings to meet ANSI Z49.1 and insurance underwriting requirements. Heavy equipment manufacturers in the Great Lakes corridor face mandated upgrades to these certified variants.
- Fixed:Permanent track-mounted installations anchor high-throughput production lines with minimal reconfiguration needs.
- Portable:Rolling frame and magnetic base configurations serve job shops prioritizing flexible floor layouts.
Fixed configurations handle the majority of throughput; portable variants are gaining share fastest as contract fabricators adopt agile production models.
Material:
Cost tiers separate commodity substitutes from performance-engineered polymers.
- Polycarbonate:Superior optical clarity and impact resistance position this polymer for precision welding applications. Automotive battery tray welding lines in Michigan and Ohio specify polycarbonate for its UV filtration and spark containment balance.
- PVC:Unit economics favor this vinyl composite across high-volume manufacturing end users despite REACH-driven reformulation pressures. Standardized thicknesses from 0.35 mm to 1.5 mm cover most industrial duty cycles.
- Canvas:Cotton-polyester blends with flame-retardant treatments serve temporary construction site applications.
- Vinyl:Coated polyester substrates offer intermediate durability for mid-duty fabrication environments.
PVC commands the dominant volume position; polycarbonate is expanding most quickly in certified safety applications.
Thickness:
Application severity and equipment intensity dictate specification selection.
- Lightweight:Sub-0.5 mm gauges suit occasional stick welding in maintenance shops.
- Standard:0.5 mm to 0.8 mm thicknesses balance portability with spark protection for general fabrication.
- Heavy-Duty:0.8 mm to 1.2 mm constructions withstand continuous MIG and TIG operations in production environments.
- Extra Heavy-Duty:1.2 mm to 1.5 mm reinforced composites contain plasma cutting spatter and sustained high-amperage arc exposure.
Standard thickness satisfies most procurement volume; extra heavy-duty specifications are climbing the fastest as plasma cutting adoption spreads.
End User:
Customer type segmentation reveals divergent purchasing authority and replacement cadence.
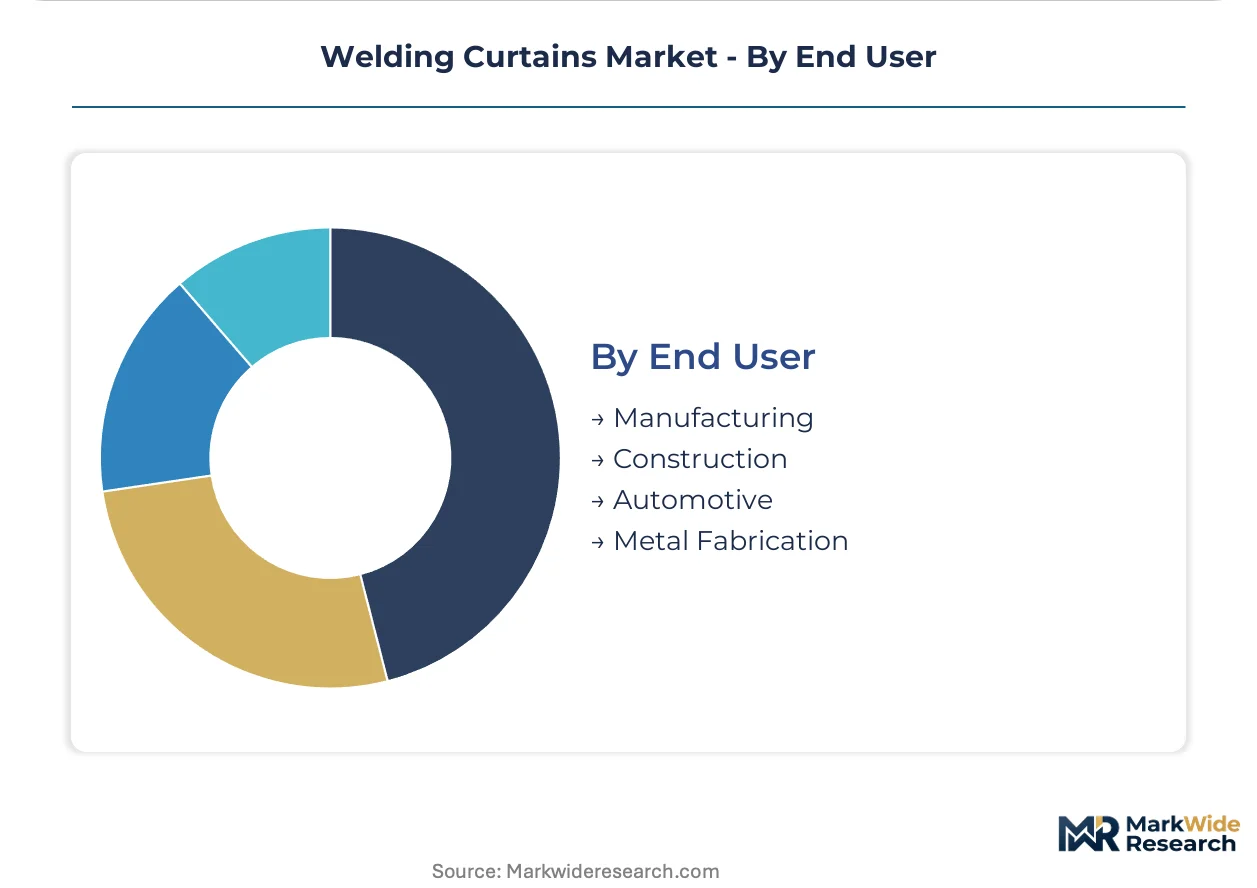
- Manufacturing:OEM welding bays and contract metalworking facilities drive systematic replacement cycles tied to OSHA inspection schedules. Tier-1 automotive suppliers in the United States represent concentrated demand for certified barrier systems.
- Automotive:Electric vehicle battery tray and chassis welding operations require optical clarity for quality documentation. Reshoring investments in Ohio, Michigan, and South Carolina are accelerating facility buildouts.
- Construction:Temporary installation needs and theft exposure favor lower-cost portable configurations with shorter replacement horizons.
- Metal Fabrication:Job shops with mixed-process capabilities prioritize reconfigurable curtain systems over fixed installations.
Manufacturing absorbs the dominant procurement volume; automotive end users are expanding fastest as domestic production capacity scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States exhibit the lowest price elasticity as OSHA compliance deadlines force certified upgrades, while Mexican fabricators remain highly sensitive to unit costs amid nearshoring infrastructure buildouts.
United States
Reshoring of automotive and battery manufacturing is accelerating greenfield welding bay construction across Ohio, Michigan, and South Carolina. OSHA General Industry Standards mandate ANSI Z49.1-certified barrier systems, eliminating uncertified vinyl alternatives from federal contractor facilities. Tier-1 suppliers in Detroit-Warren-Dearborn cluster are systematically retrofitting legacy curtain installations ahead of inspection cycles.
Germany
REACH restrictions on halogenated flame retardants are forcing coating reformulations across automotive supplier networks. ECHA substance evaluations are accelerating substitution timelines for chlorinated additives in vinyl curtain production. Stuttgart industrial corridor suppliers now specify phosphorus-based alternatives in procurement documents, creating inventory transition pressures for fabricators.
China
Domestic electric vehicle battery tray welding capacity is expanding in Yangtze River Delta manufacturing zones. GB standards for workplace radiation protection are tightening opacity requirements for welding zone barriers. Suzhou and Changzhou metalworking clusters are importing polycarbonate formulations for precision robotic welding cells serving European automotive OEMs.
Mexico
Nearshoring investments in Nuevo León and Bajío Region automotive stamping lack standardized welding safety infrastructure. Mexican federal labor law amendments are elevating spark containment requirements toward ANSI-equivalent standards. Monterrey-based contract fabricators represent first-mover opportunity for certified barrier suppliers as OEMs impose supplier qualification mandates.
Japan
Precision aerospace component manufacturing in Nagoya industrial corridor demands optical-grade polycarbonate for continuous weld monitoring. METI industrial safety guidelines are harmonizing with ISO 25980 welding screen standards. Osaka-Kobe manufacturing belt suppliers are integrating IoT-enabled curtain systems into automated fabrication environments for quality documentation workflows.
Welding Curtains Market Competitive Landscape
Integrated welding equipment manufacturers and specialized industrial partitioning suppliers split the market along bundled-versus-standalone procurement patterns. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates leveraging cross-product ecosystems, mid-cap specialists in high-temperature fabrication environments, and regional fabricators serving construction-site temporary installations. Competitive moves center on backward integration into polymer film production and geographic expansion through distributor network capture.
Within the diversified industrial tier, Lincoln Electric exemplifies ecosystem bundling by anchoring curtain solutions within integrated welding system sales. Singer Safety occupies a specialist position in custom-engineered partitioning for high-temperature fabrication environments. 3M anchors the advanced materials tier through polymer film technology leadership in heavy-duty applications.
| Leading Market Players |
|---|
| Lincoln Electric |
| 3M |
| ESAB |
| Honeywell |
| Kemper |
| Chase Doors |
| Singer Safety |
| Aerservice Equipments |
| Weldas |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Shanghai to Long Beach transmit petrochemical feedstock cost volatility directly into domestic distributor markups, compressing margins for standardized PVC curtain producers while amplifying price differentiation between certified polycarbonate tiers and commodity vinyl alternatives.
Pricing Analysis
Aftermarket service revenue from scheduled curtain replacement programs and ANSI Z49.1 compliance certification services now drives lifetime value capture. Three-tier pricing structure across premium flame-retardant polycarbonate, standard PVC formulations, and economy canvas alternatives separates procurement budgets by end-use criticality. Cost compression in commodity vinyl tiers is intensifying because of crude oil derivative fluctuations, while Tier-1 automotive suppliers in Michigan exhibit the lowest price sensitivity due to mandated safety upgrades.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for halogenated flame-retardant additive imports. Specialty chemical production clusters in Germany and China anchor global supply for phosphorus-based coating formulations, while raw material dependencies center on polyvinyl chloride resin, polycarbonate pellets, and flame-retardant masterbatches. Single-source vulnerability in certified polymer film extrusion capacity creates qualification bottlenecks for new entrants. Distribution runs through industrial safety distributors and OEM welding equipment channels serving fabrication facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Welding curtains constitute a regulatory-entrenchment defensive moat: ANSI Z49.1 certification requirements create switching costs that lock facilities into qualified supplier relationships and resist price-based displacement.
For Market Incumbents: Harden compliance infrastructure through captive ANSI Z49.1 testing laboratories to accelerate customer certification timelines and repel uncertified low-cost imports. Deepen backward integration into polymer film extrusion to secure supply continuity against German and Chinese additive concentration. Channel control through exclusive distributor arrangements in the Great Lakes automotive corridor defends margin position against emerging regional fabricators.
For New Entrants and Emerging Players: Monterrey-based contract fabricators in Nuevo León represent the most penetrable entry point as nearshoring OEMs impose supplier qualification mandates lacking established local infrastructure. Mid-sized metalworking shops in the United States Great Lakes corridor shifting to subscription-based maintenance contracts offer service-bundle disruption angles against capital-sale incumbents. Target IoT-enabled smart curtain integration as a differentiated go-to-market wedge in automated fabrication environments.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core welding safety divisions lacking ecosystem integration with primary welding equipment sales. Long-term viability rests on regulatory entrenchment deepening through anticipated state-level workplace safety amendments and polymer recycling mandates. Watch for EPA vinyl emissions rule enforcement acceleration as the inflection signal for reformulation-capable manufacturer valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Film Production | Captive polycarbonate extrusion capacity insulates against German-Chinese additive supply concentration. |
| ANSI Z49.1 Certification Laboratory Investment | In-house compliance testing accelerates customer facility qualification timelines ahead of OSHA inspection cycles. |
| IoT-Enabled Smart Curtain Development | Occupancy sensor integration commands premium positioning in automated Michigan and Ohio EV battery welding lines. |
| Subscription-Based Replacement Program Launch | Scheduled curtain exchange contracts shift margin capture from capital sales to recurring service revenue. |
| Mexican Distributor Network Capture | First-mover positioning in Nuevo León nearshoring corridors ahead of federal labor law harmonization. |
Research Methodology
A standing panel of plant safety managers, welding equipment procurement leads, OSHA compliance officers, and industrial distributor account executives provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, OSHA enforcement databases, customs trade records, and ANSI standards documentation. Bottom-up facility-level demand estimation triangulated against top-down polymer consumption data from petrochemical industry associations.
Scenario bracketing around reshoring intensity and regulatory enforcement pace framed the analytical approach across the projection horizon. Segmentation dimensions modeled include material type, mobility configuration, thickness grade, end-use industry, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated base-year estimates, with industry-specific inputs incorporating automotive production capacity announcements and EPA rulemaking timelines.
Macroeconomic conditions sit as an overlay; deviation in industrial construction spending and crude oil price trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding OSHA inspection cycle intensity and state-level workplace safety amendment adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Camouflage Suit Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
Industrial Wearable Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Global Protective Fabrics Market
Protective and Workwear Textiles
Global Industrial Protective Clothing Fabrics Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Dry Suits Market
Protective and Workwear Textiles
Sun Protective Clothing Market
Protective and Workwear Textiles
Compression Garments Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Functional Workwear Apparel Market