
 Industrial Wearable Market | 2026-2036
Industrial Wearable Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wearable Market Outlook
The EU Green Deal's worker safety provisions is hardening compliance timelines for connected equipment across European manufacturing. Honeywell International leverages its automation heritage to integrate gas detection into wearable form factors. Microsoft anchors enterprise mixed reality through its industrial cloud stack. Zebra Technologies competes on ruggedized hardware durability in warehouse and logistics environments.
Industrial wearables encompass body-worn computing devices, sensor-embedded garments, and powered exoskeletons engineered to withstand IEC 60529 ingress protection ratings while delivering real-time biometric, environmental, or spatial data to operators and supervisors. Their primary purpose is to reduce injury incidence, compress task completion times, and capture process telemetry in hazardous or precision-dependent workflows. Smart Glasses command the largest revenue pool due to AR-assisted maintenance applications, while Exoskeletons represent the fastest-expanding category as automotive and heavy assembly lines deploy load-reducing suits. Wearable Sensors penetrate deepest in logistics, where Bluetooth and RFID tags track picker location and ergonomic strain across fulfillment networks.
OSHA's General Industry Standards and the EU Machinery Directive jointly dictate minimum functional safety and electromagnetic compatibility thresholds for devices operating near heavy machinery. The FDA regulates biometric monitoring claims when wearables cross into physiological diagnostic territory, particularly in healthcare-adjacent industrial settings. Stakeholders must weigh certification breadth against vertical specialization as regulatory fragmentation across jurisdictions threatens to fragment product roadmaps and delay market entry.
Market Dynamics
The EU Machinery Directive revision is compressing certification timelines for connected worker equipment while automotive OEMs in Germany accelerate exoskeleton procurement to reduce musculoskeletal injury rates on assembly lines.
Growth Catalysts
- EU Green Deal worker safety provisions:Hardened compliance timelines for environmental and occupational health monitoring are mandating biometric sensor deployment across European manufacturing facilities.
- AR-assisted maintenance protocols:Oil and gas operators are standardizing head-mounted displays for remote expert guidance during upstream equipment servicing, reducing technician dispatch requirements.
- Stuttgart-Wolfsburg industrial cluster concentration:Germany's automotive heartland is consolidating demand for powered exoskeletons as BMW, Mercedes-Benz, and Volkswagen integrate load-reducing suits into final assembly operations.
Market Restraints
- Lithium-polymer battery cost volatility:Energy density requirements for all-day industrial wearables tie device economics to raw material price swings in cobalt and nickel markets.
- Display module supply concentration:Micro-OLED and waveguide optics production clusters in Taiwan and South Korea create single-source vulnerability for AR headset manufacturers.
- IEC 60529 ingress protection certification friction:Multi-jurisdiction testing requirements for dust and liquid resistance extend product launch timelines by months.
Strategic Opportunities
- Underpenetrated French nuclear maintenance sector:EDF's reactor refurbishment program lacks standardized connected worker platforms, creating first-mover space for radiation-hardened wearable vendors.
- 5G-private network convergence with edge AI:Real-time biometric inference at the network edge enables predictive fatigue alerts without cloud dependency, opening high-reliability manufacturing applications.
- Outcome-based safety contracting:Insurance carriers are piloting premium reduction models tied to wearable-verified injury prevention, shifting procurement from capital expenditure to risk-transfer mechanisms.
Industry Challenges
- Embedded systems firmware talent scarcity:Industrial wearable development requires rare cross-functional expertise in low-power signal processing, biomechanical modeling, and IEC 62304 medical device software standards.
- FDA 510(k) pathway complexity for diagnostic claims:Wearables crossing from wellness monitoring into cardiac or respiratory diagnostic territory face elongated regulatory review and clinical validation requirements.
- Legacy SCADA integration friction:Brownfield manufacturing environments running proprietary industrial protocols require costly middleware development to stream wearable telemetry into existing supervisory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wearable Market |
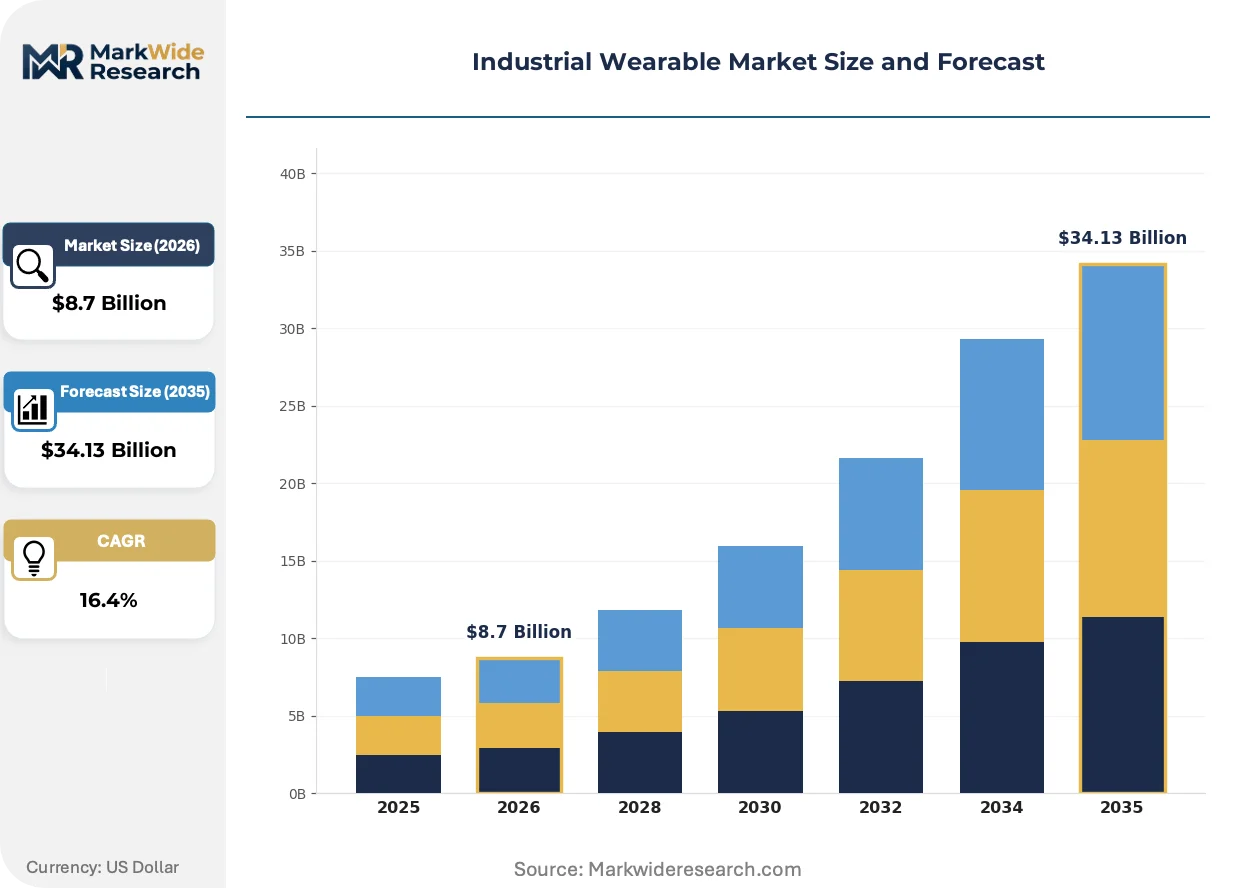
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Helmets, Smart Glasses, Wearable Sensors, Exoskeletons End User: Manufacturing, Construction, Healthcare, Logistics Technology: Augmented Reality, RFID, Bluetooth, Biometric Sensors Application: Safety Monitoring, Training, Remote Assistance, Performance Tracking |
| Companies Covered | RealWear, Vuzix, Honeywell International, Zebra Technologies, Daqri, ProGlove, Microsoft, Seiko Epson, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wearable Market Strategic Shifts
Edge-native AI inference is compressing response latency for safety-critical alerts while regulatory pressure on worker exposure limits accelerates sensor miniaturization. Procurement criteria are hardening around interoperability certifications.
Computer vision embedded in smart glasses is automating quality inspection workflows on automotive assembly lines. Tier-1 suppliers in Germany and Japan are deploying AR-guided torque verification systems at workstation scale. The technology is automating defect detection that previously required dedicated metrology stations, collapsing inspection cycle times from minutes to seconds.
The EU AI Act's risk classification framework is redefining liability for autonomous safety systems in industrial settings. High-risk biometric monitoring applications now require conformity assessment by notified bodies before CE marking. Exoskeleton vendors with predictive collision avoidance are restructuring technical documentation to satisfy Annex III transparency obligations.
Buyer consolidation among multinational automotive OEMs is forcing wearable vendors to unbundle hardware from software subscriptions. Procurement teams at Stellantis and Renault are rejecting bundled SaaS pricing in favor of perpetual licensing with maintenance options. This pattern is most visible in Western European manufacturing, where enterprise IT governance mandates on-premise data residency for biometric archives.
Industrial Wearable Market Segmentation
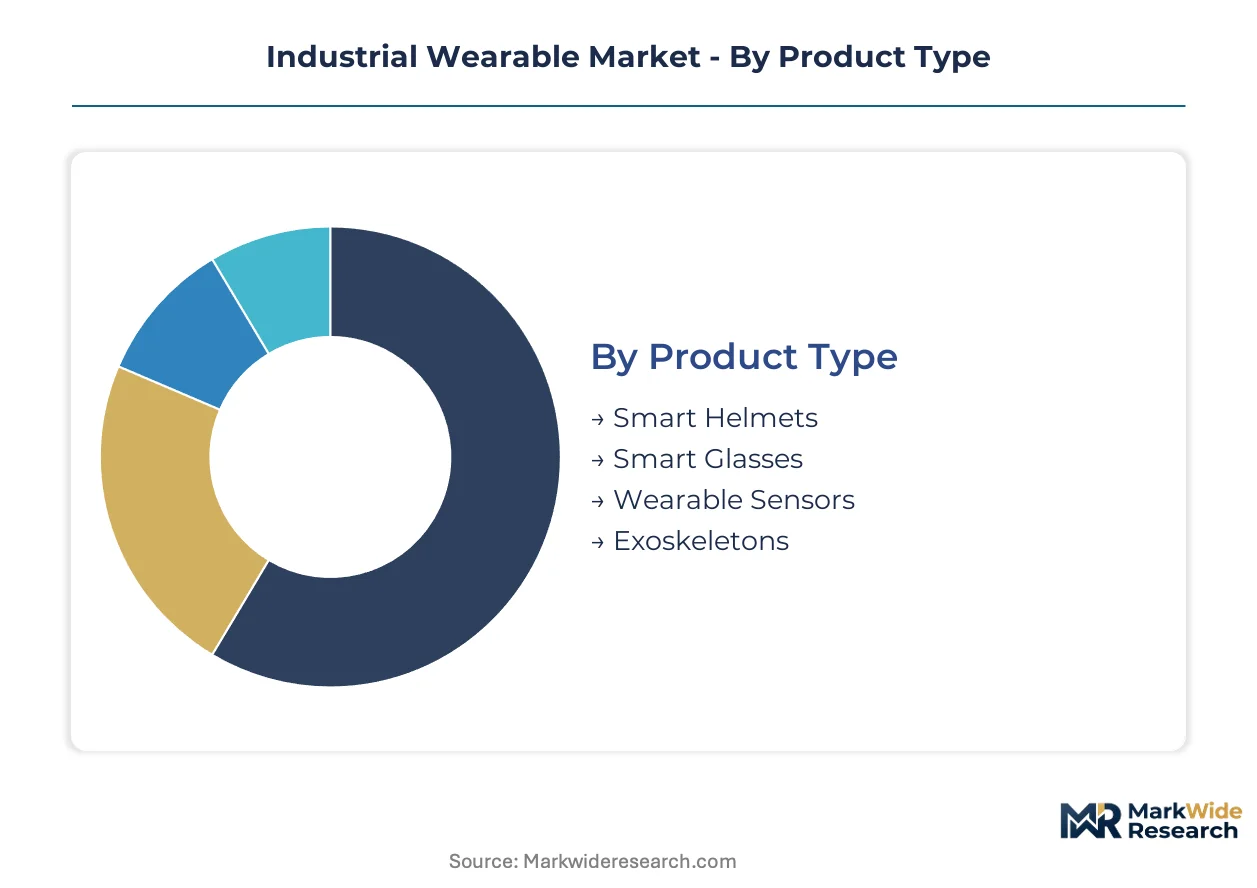
Industrial wearable procurement varies sharply by operational hazard profile and data integration depth. Segment boundaries blur as vendors bundle AR headsets with biometric backends, yet buyer budgets still flow through discrete technology categories.
Product Type:
Technical specifications around ingress protection and battery chemistry define procurement tiers across form factors.
- Smart Glasses:Waveguide optics and micro-OLED displays deliver monocular or binocular AR overlays for hands-free maintenance protocols. Demand concentrates in German automotive final assembly, where BMW and Mercedes-Benz technicians access torque specifications without breaking workflow continuity.
- Exoskeletons:Powered and passive load-reducing suits incorporate force sensors and actuator networks to attenuate musculoskeletal strain during repetitive lifting. Stuttgart-Wolfsburg automotive clusters drive fastest category expansion as Volkswagen integrates hip-mounted support systems into battery pack installation stations.
- Smart Helmets:Integrated gas detection, thermal imaging, and bone-conduction audio serve hazardous environment workers.
- Wearable Sensors:Bluetooth and RFID tags embedded in garments or wristbands stream location and ergonomic data.
Smart Glasses leads on scale; Exoskeletons leads on momentum.
End User:
Operational intensity and regulatory exposure shape deployment velocity across verticals.
- Manufacturing:Continuous-motion assembly lines demand real-time fatigue monitoring and AR-guided quality verification. German automotive OEMs anchor procurement volume through exoskeleton standardization programs.
- Logistics:Pick-path optimization and picker safety drive Bluetooth beacon and smart glasses adoption. Fulfillment networks in the Netherlands and Belgium deploy location-aware wearables to compress order cycle times.
- Construction:Fall detection and proximity alert systems dominate specification sheets.
- Healthcare:Sterile-compatible biometric monitors serve pharmaceutical manufacturing adjacent to cleanroom operations.
Manufacturing captures largest installed base; Logistics posts steepest expansion trajectory.
Technology:
Connectivity protocols and sensing modalities determine integration cost and data fidelity.
- Augmented Reality:Spatial computing platforms overlay 3D schematics and remote expert video feeds onto physical equipment. Oil and gas operators in Norway standardize AR maintenance protocols for offshore platform servicing.
- Biometric Sensors:Photoplethysmography and galvanic skin response circuits enable predictive fatigue modeling. EU Machinery Directive compliance timelines accelerate deployment across French and Italian metalworking facilities.
- RFID:Passive and active radio-frequency tags anchor inventory and personnel location systems.
- Bluetooth:Low-energy mesh networks connect distributed sensor arrays to edge gateways.
Augmented Reality commands premium pricing; Biometric Sensors scales fastest.
Application:
Use case maturity correlates with measurable safety outcome attribution and IT integration depth.
- Safety Monitoring:Real-time gas exposure, fall detection, and collision avoidance systems trigger automated shutdowns or supervisor alerts. German chemical processors mandate connected worker platforms under revised occupational health frameworks.
- Remote Assistance:Two-way video and annotation tools connect field technicians with centralized engineering expertise. Upstream oil maintenance in the North Sea reduces helicopter dispatch through AR-guided repair validation.
- Training:Immersive simulation and guided task repetition accelerate skill transfer.
- Performance Tracking:Motion capture and task timing analytics optimize workstation ergonomics.
Safety Monitoring dominates current deployment; Remote Assistance gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial wearable industry traces its commercial roots to early 2010s deployments in German automotive plants, where pilot programs for AR-assisted maintenance and passive exoskeletons established the operational templates now replicated worldwide.
Germany
Stuttgart and Wolfsburg anchor European demand through BMW, Mercedes-Benz, and Volkswagen exoskeleton standardization programs. The EU Machinery Directive revision compresses certification timelines for connected worker equipment. Baden-Württemberg's automotive cluster drives fastest regional adoption of powered load-reducing suits for battery pack installation stations.
United States
OSHA's General Industry Standards mandate minimum functional safety thresholds for devices operating near heavy machinery. Honeywell International leverages its automation heritage to integrate gas detection into wearable form factors. Oil and gas operators in Texas and the Gulf Coast expand head-mounted display procurement for upstream equipment servicing.
France
EDF's reactor refurbishment program lacks standardized connected worker platforms, creating first-mover space for radiation-hardened wearable vendors. The EU AI Act's risk classification framework redefines liability for autonomous safety systems in industrial settings. Île-de-France concentrates demand for biometric monitoring in nuclear maintenance and aerospace manufacturing.
Japan
METI promotes industrial IoT adoption through subsidy programs targeting SME manufacturers. Seiko Epson anchors enterprise mixed reality through optical component supply to regional headset assemblers. The Kansai industrial corridor around Osaka deploys AR-guided quality verification for automotive tier-1 suppliers.
Netherlands
Fulfillment networks in the Randstad deploy location-aware wearables to compress order cycle times. REACH compliance requirements shape material selection for sensor-embedded garments. Rotterdam's port logistics cluster drives Bluetooth beacon adoption for picker safety and pick-path optimization.
Industrial Wearable Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the industrial wearable value chain, with vertically integrated hardware manufacturers facing pressure from software-centric platform developers. The vendor base spans three tiers: diversified industrial conglomerates with automation heritage, specialized wearable-native firms, and component suppliers extending into systems integration. Consolidation pressure intensifies as automotive OEM procurement teams reject bundled SaaS pricing in favor of perpetual licensing. Geographic expansion and strategic partnerships constitute the dominant competitive vectors as vendors chase certification reciprocity across jurisdictions.
Among diversified industrial technology providers, Honeywell International and 3M Company exemplify the conglomerate archetype leveraging existing safety equipment distribution channels. Zebra Technologies occupies a position within the ruggedized hardware specialist tier, competing on durability metrics in warehouse and logistics environments. Microsoft anchors the enterprise software platform vector, integrating industrial cloud capabilities with mixed reality endpoints.
| Leading Market Players |
|---|
| RealWear |
| Vuzix |
| Honeywell International |
| Zebra Technologies |
| Daqri |
| ProGlove |
| Microsoft |
| Seiko Epson |
| 3M Company |
| Others |
Value Chain & Pricing Dynamics
Firmware engineers with IEC 62304 expertise in Taiwan and South Korea command 40-60% wage premiums over general embedded systems developers, compressing margins for AR headset manufacturers and widening spreads between premium-certified and economy-tier industrial wearables.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation driven by IEC 60529 ingress protection certification grade and after-sales service bundling. Price erosion runs through the economy tier as Chinese contract manufacturers scale waveguide optics production. Automotive OEM procurement teams exhibit lowest price sensitivity due to outcome-based safety contracting pilots, while logistics operators in the Benelux region resist SaaS subscription models.
Supply Chain Analysis
Specialized optical coating technicians and micro-assembly specialists concentrate in Taiwan, South Korea, and Japan, creating recruitment bottlenecks for waveguide display production. Manufacturing draws from lithium-polymer battery cells, micro-OLED substrates, and rare-earth magnet actuators. Single-source vulnerability in Taiwan's semiconductor packaging nodes threatens exoskeleton sensor module availability. Distribution runs through industrial safety equipment distributors with certified service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement teams at German automotive OEMs now specify IP67 minimums and 5-year service lifecycles, displacing price-first buying patterns.
For Market Incumbents: Anticipate margin compression from software-unbundling demands by Stellantis and Renault procurement teams. Defend position through backward integration into optical component supply and accelerated EU AI Act conformity assessment investment. Channel control via certified service networks remains essential as buyer consolidation intensifies.
For New Entrants and Emerging Players: Capture the underpenetrated French nuclear maintenance sector where EDF's reactor refurbishment program lacks standardized connected worker platforms. Target radiation-hardened exoskeleton development for decommissioning applications. Go-to-market through engineering services partnerships with established nuclear contractors.
For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers with captive optical manufacturing and medical device software certification. Long-term viability hinges on cross-jurisdiction regulatory reciprocity and automotive OEM platform standardization. Watch for FDA 510(k) clearance announcements in cardiac diagnostic wearables as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | CE marking for high-risk biometric systems requires notified body validation before market entry. |
| Optical Component Backward Integration | In-house waveguide manufacturing reduces Taiwan supply concentration exposure for AR headset vendors. |
| Outcome-Based Safety Contracting | Insurance premium reduction models shift procurement from capital expenditure to risk-transfer mechanisms. |
| 5G-Private Network Edge AI Deployment | Real-time fatigue inference without cloud dependency opens high-reliability manufacturing applications. |
| Perpetual Licensing Model Unbundling | Western European enterprise IT governance mandates on-premise data residency for biometric archives. |
Study Parameters
Coverage spans Germany, United States, France, Japan, and Netherlands, with primary inputs from each. The analysis combines interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads with secondary validation from SEC filings, customs trade data, EU Machinery Directive revision texts, and hospital procurement databases. Bottom-up unit economics triangulate against top-down industry spend estimates.
Rate-of-change decomposition separates volume growth from value-per-unit shifts across the projection horizon. Segmentation dimensions modeled include product type, end-use vertical, connectivity protocol, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and penetration rate trajectories. Forecast inputs incorporate automotive OEM exoskeleton standardization timelines and EU Green Deal worker safety compliance deadlines.
Regulatory enforcement variance, battery raw material price volatility, and automotive production schedule disruptions are the dominant revision risks. Forecasts reflect documented assumptions about certification timeline compression and buyer consolidation trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Anti-Stain Fabrics Market
Protective and Workwear Textiles
Rain Coat Market
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Percussion Vests Market
Protective and Workwear Textiles
Workwear Market
Protective and Workwear Textiles
Fashion Face Mask Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Fabric Protection Market
Protective and Workwear Textiles
Uniforms and Workwears Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Workwear Accessories Market
Protective and Workwear Textiles
US UPF Sun Protective Clothing Market
Protective and Workwear Textiles
North America Western Wear Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market