
 Anti-Stain Fabrics Market | 2026-2036
Anti-Stain Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Stain Fabrics Market Analytics
The EU Green Deal's chemical restrictions is shifting procurement specifications across European hospitality chains toward fluorine-free alternatives. Crypton Fabric leverages proprietary barrier technology to sustain premium positioning in healthcare and contract furniture. Milliken and Company anchors North American supply through integrated finishing operations in South Carolina. Applied Textiles specializes in licensed treatment programs that extend brand reach without captive mill investments.
Anti-stain fabrics are textile substrates engineered with surface-modified fiber architectures or applied barrier chemistries, typically achieving oil repellency ratings of 8+ and water repellency of 90+ on the AATCC spray test scale, designed to resist penetration by aqueous and oleophilic substances in high-use commercial environments. Polyester and nylon substrates dominate volume due to inherent hydrophobicity and compatibility with fluoropolymer and silicone-based finishes, while cotton treatments command margin premiums in fashion and home textile channels where natural fiber aesthetics drive selection. Nanotechnology-based finishes represent the fastest-growing technology segment as brands seek durable performance without perfluorinated chemistry, though stain repellent coatings retain the largest installed base across automotive and upholstery applications.
The EPA oversees chemical safety review under TSCA for stain-resistant chemistries entering US commerce, while REACH restricts long-chain perfluorinated substances in European textile finishing, and OEKO-TEX Standard 100 certification shapes buyer qualification thresholds across both markets. China's GB standards for textile safety, administered by SAMR, increasingly incorporate anti-stain performance testing protocols that exporters must satisfy for domestic market access. Stakeholders must monitor the trajectory of fluorine-free chemistry scale-up against performance parity benchmarks to time capacity commitments and formulation transitions.
Market Dynamics
The transition from fluoropolymer-based finishes to fluorine-free alternatives constitutes the dominant structural force reshaping competitive positioning across hospitality, healthcare, and contract furniture procurement channels.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH Annex XVII limitations on long-chain perfluorinated substances compel mill reformulation toward silicone and hydrocarbon-based repellents, opening premium positioning for early movers.
- Shaoxing textile cluster expansion:China's integrated dyeing and finishing infrastructure around Zhejiang province concentrates export-oriented anti-stain capacity serving European and North American contract furniture buyers.
- Nanotechnology barrier systems:Sol-gel and layer-by-layer deposition methods achieve oil repellency parity with legacy fluorochemistry while satisfying OEKO-TEX Standard 100 certification thresholds.
Market Restraints
- Silicone raw material volatility:Organosilicon precursor costs fluctuate with energy-intensive chlorosilane production concentrated in Chinese and German chemical parks.
- Performance durability gap:Fluorine-free alternatives demonstrate 15-30% faster degradation in abrasion testing under AATCC protocols, limiting warranty terms in high-traffic hospitality applications.
- South Carolina finishing concentration:North American supply depends heavily on integrated mill operations in the southeastern US, creating hurricane and logistics vulnerability.
Strategic Opportunities
- Indian hospitality buildout:Premium hotel development in Mumbai and Bangalore generates specification demand for stain-resistant upholstery meeting Fire Retardant standards under BIS certification.
- Automotive interior pivot:Electric vehicle cabin redesigns prioritize light-colored sustainable textiles requiring oleophobic protection against cosmetics and food contact.
- Licensed treatment programs:Applied finishing technologies allow regional converters to access proprietary chemistries without captive capital investment in coating lines.
Industry Challenges
- Fluorine-free formulation expertise:Mill technical staff require retraining in silicone emulsion stability and crosslinking chemistry to achieve batch consistency.
- Dual certification timelines:Simultaneous pursuit of OEKO-TEX Standard 100 and Cradle to Cradle approval extends product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Stain Fabrics Market |
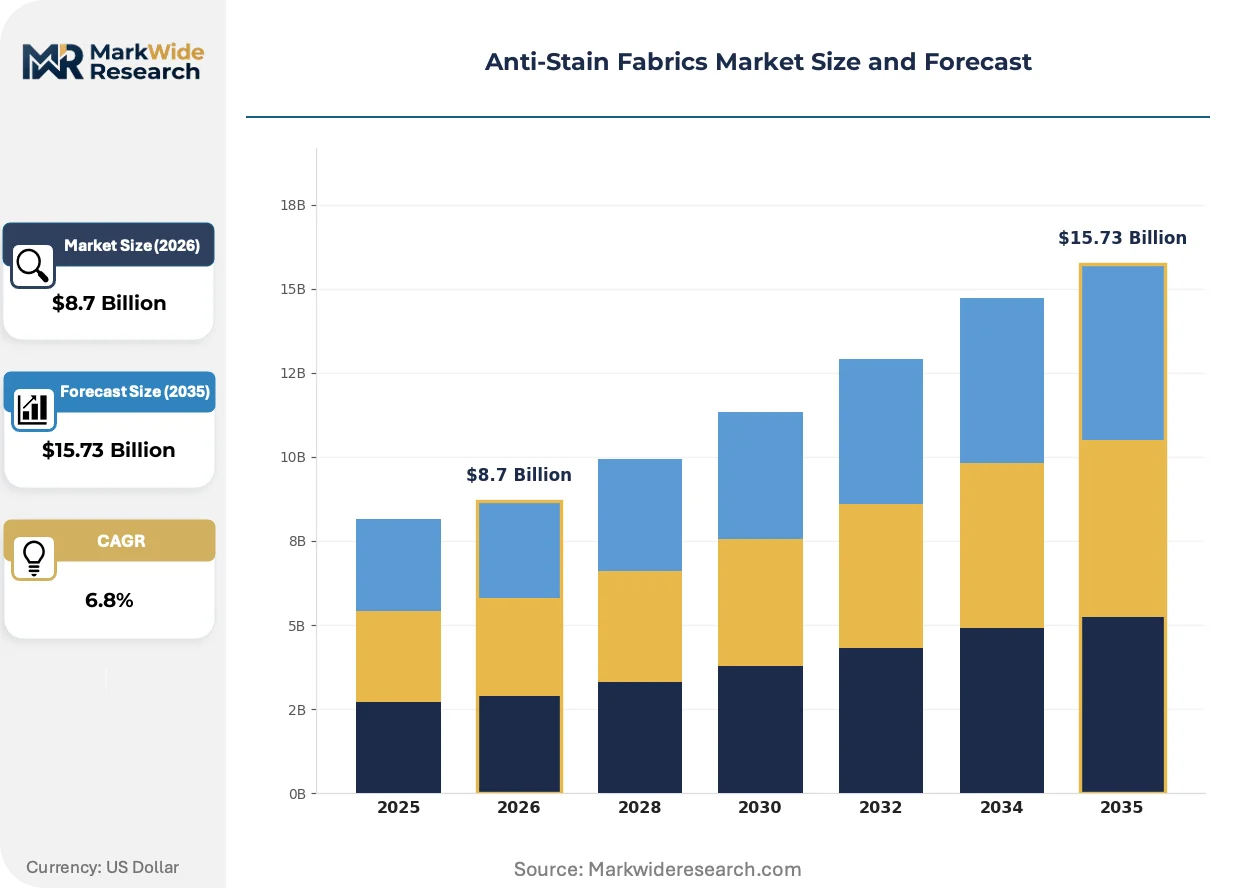
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Nylon, Microfiber Technology: Stain Repellent Coatings, Nanotechnology, Water-Repellent Treatments, Durable Water Repellents End User: Fashion Industry, Hospitality, Automotive Sector, Home Textiles Application: Clothing, Upholstery, Table Linens, Outdoor Gear |
| Companies Covered | Crypton Fabric, Applied Textiles, DuPont, Nano-Tex, Sunbrella, Milliken and Company, 3M, The Chemours Company, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Stain Fabrics Market Evolving Landscape
Surface engineering advances and regulatory chemistry bans are compressing the viable technology set while opening margin capture for performance-verified alternatives.
Plasma-enhanced chemical vapor deposition is electrifying the functionalization of polyester and nylon substrates by creating nanoscale topographies without wet chemistry. Medical upholstery manufacturers in Germany and the US are adopting these systems to satisfy both EPA TSCA reporting requirements and hospital infection control protocols. The technology is electrifying regional supply strategies by enabling smaller-batch, higher-mix production closer to end-use markets.
REACH restrictions on per- and polyfluoroalkyl substances are forcing systematic reformulation across European textile finishing operations. The regulation eliminates C8 fluorotelomer-based repellents from contract furniture and automotive textile supply chains by 2025. Italian and Portuguese mills are responding with accelerated silicone-hydrocarbon hybrid development programs targeting hospitality specification channels.
Specification-driven procurement is consolidating decision authority within hospitality and healthcare corporate sustainability offices. Traditional distributor relationships are giving way to direct mill engagement with procurement teams demanding full material health disclosure. This pattern is most pronounced among North American hotel chains implementing Science Based Targets initiative commitments requiring Scope 3 chemical footprint reduction.
Anti-Stain Fabrics Market Segmentation
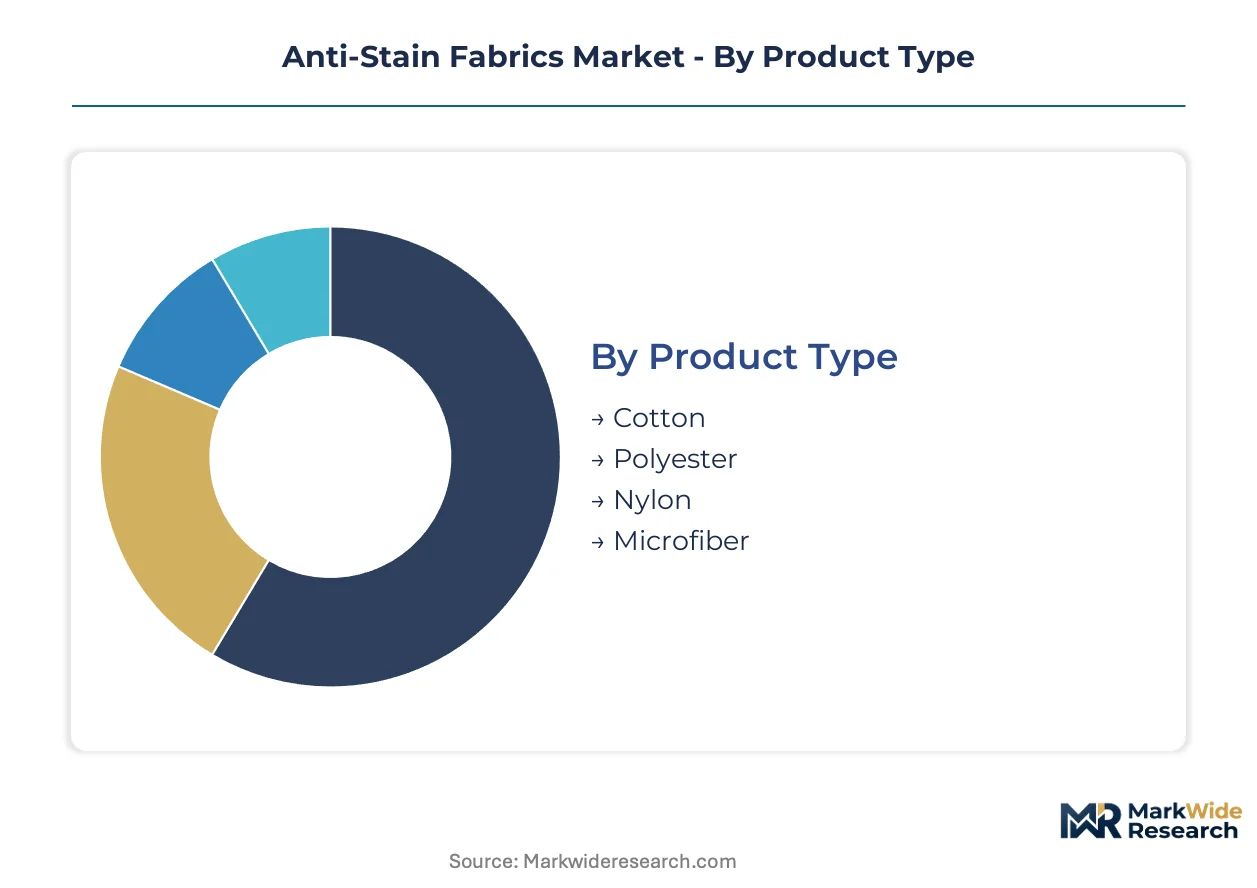
Anti-stain fabric procurement hinges on matching substrate chemistry to end-use durability requirements. Certification burdens vary sharply across segments, with healthcare and hospitality channels demanding OEKO-TEX Standard 100 while automotive buyers prioritize REACH-compliant fluorine-free formulations.
Product Type:
Cotton requires the most intensive finishing certification due to hydrophilic fiber structure demanding barrier chemistry validation under EPA TSCA and REACH Annex XVII.
- Polyester:Inherent hydrophobicity reduces finishing load while achieving AATCC oil repellency 8+ ratings. Hospitality procurement in the United States concentrates specification demand here for upholstery and drapery applications requiring 50,000+ double rub durability.
- Nylon:High tenacity substrates dominate automotive seating and contract furniture where abrasion resistance must coexist with oleophobic protection. German automotive suppliers specify nylon base cloths for light-colored sustainable interiors in electric vehicle cabins.
- Cotton:Natural fiber aesthetics command margin premiums in fashion and home textile channels despite higher treatment costs. Italian mills specialize in cotton finishing for premium hospitality linens requiring simultaneous softness and spill resistance.
- Microfiber:Ultra-fine denier constructions create dense surface architectures that amplify repellent performance. Shaoxing manufacturers export microfiber upholstery to North American contract furniture buyers seeking cost-optimized durability.
Polyester sits at the top of the volume ranking, with microfiber climbing the fastest.
Technology:
Cost tiers separate legacy fluoropolymer systems from premium silicone-hydrocarbon hybrids and emerging plasma-deposited nanolayers.
- Stain Repellent Coatings:Solvent-based and aqueous fluoropolymer formulations retain the largest installed base across automotive and upholstery applications. Portuguese mills maintain coating lines for contract furniture exports to European hospitality chains.
- Nanotechnology:Sol-gel and layer-by-layer deposition methods achieve oil repellency parity with legacy fluorochemistry. German medical upholstery manufacturers adopt plasma-enhanced chemical vapor deposition to satisfy both EPA TSCA reporting and hospital infection control protocols.
- Water-Repellent Treatments:Silicone emulsion and paraffin-based finishes serve cost-sensitive home textile and outdoor gear channels. Chinese finishing houses around Nantong specialize in water-repellent cotton treatments for domestic apparel brands.
- Durable Water Repellents:C6 fluorotelomer and silicone-hydrocarbon hybrids target the transition window before REACH C8 bans take full effect. Italian mills accelerate hybrid development for hospitality specification channels demanding warranty-backed performance.
Stain repellent coatings command the highest current volume, while nanotechnology gains share fastest.
End User:
Application maturity determines whether buyers accept fluorine-free performance trade-offs or demand legacy chemistry waivers.
- Hospitality:Corporate sustainability offices consolidate procurement authority, mandating full material health disclosure and Scope 3 chemical footprint reduction. North American hotel chains implementing Science Based Targets initiative commitments drive fluorine-free specification.
- Automotive Sector:Electric vehicle cabin redesigns prioritize light-colored sustainable textiles requiring oleophobic protection against cosmetics and food contact. German and Japanese OEMs specify REACH-compliant finishes for seat and interior panel fabrics.
- Home Textiles:Retail channel price sensitivity favors cost-optimized water-repellent treatments over premium nanotechnology finishes. Indian home textile exporters target European mass-market retailers with BIS-certified cotton treatments.
- Fashion Industry:Seasonal collection cycles limit qualification timelines, restricting adoption to established finishing chemistries with existing OEKO-TEX certification. Portuguese and Italian fashion mills focus on cotton and viscose substrates for premium outerwear.
Hospitality generates the highest specification intensity, with automotive climbing fastest.
Application:
Customer type fragmentation separates specification-driven contract channels from price-sensitive retail procurement.
- Upholstery:Contract furniture and automotive seating demand the most stringent abrasion and repellency combinations. North American hospitality procurement teams expand fabric replacement cycles, concentrating demand in high-durability polyester and nylon substrates.
- Clothing:Performance outerwear and workwear segments prioritize breathability alongside stain resistance. German and Japanese brands specify nanotechnology finishes for technical apparel requiring OEKO-TEX Standard 100 certification.
- Table Linens:Commercial hospitality laundries drive demand for cotton treatments surviving industrial wash cycles. Italian mills specialize in silicone-finished cotton table linens for European restaurant chains.
- Outdoor Gear:Tent and backpack manufacturers balance water repellency with environmental marketing claims. Chinese manufacturers around Shaoxing supply fluorine-free durable water repellents to North American outdoor brands.
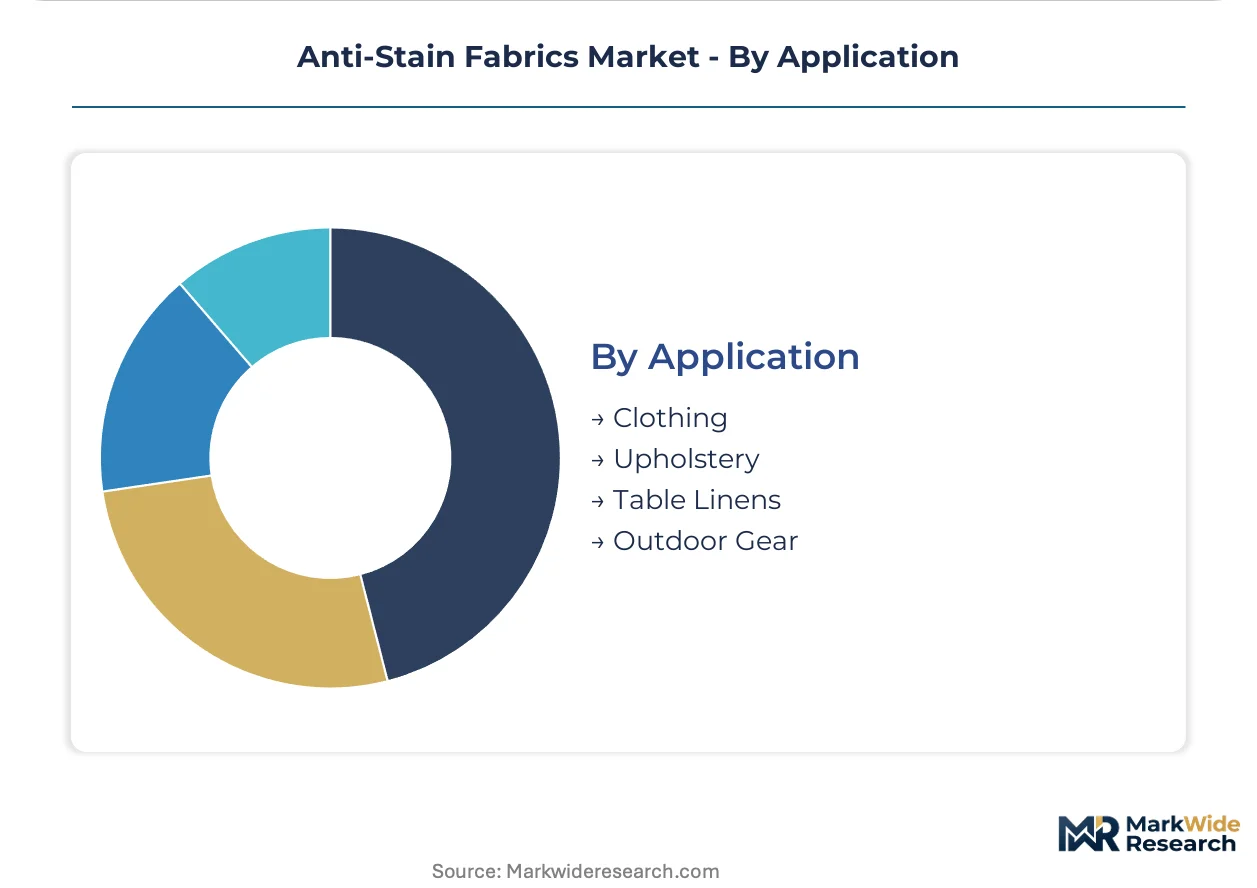
Upholstery holds the top volume position, with outdoor gear expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Textile chemists and finishing engineers concentrate in Germany's industrial belt, China's coastal manufacturing zones, and the southeastern United States, anchoring regional capability clusters.
United States
Hospital upholstery procurement and hospitality chain sustainability mandates drive specification demand. EPA TSCA reporting requirements govern stain-resistant chemistry imports. South Carolina hosts integrated finishing operations supplying North American contract furniture manufacturers.
Germany
Medical upholstery manufacturers and automotive OEMs prioritize infection control and sustainable cabin materials. REACH Annex XVII restrictions eliminate C8 fluorotelomer-based repellents by 2025. Bavarian chemical parks host plasma-enhanced deposition systems for nanoscale barrier production.
China
Export-oriented contract furniture and domestic apparel brands scale fluorine-free treatment adoption. SAMR-administered GB standards incorporate anti-stain performance testing for market access. Shaoxing and Nantong clusters concentrate dyeing and finishing infrastructure serving global buyers.
Italy
Premium hospitality linen and fashion outerwear segments command margin premiums for natural fiber aesthetics. EU Green Deal chemical restrictions accelerate silicone-hydrocarbon hybrid development. Como and Prato finishing districts specialize in cotton treatments for European restaurant chains.
India
Mumbai and Bangalore hotel construction generates specification demand for fire-retardant stain-resistant upholstery. BIS certification requirements shape product qualification for domestic hospitality procurement. Gujarat textile belt expands finishing capacity for export-oriented home textile producers.
Anti-Stain Fabrics Market Competitive Landscape
Capital-heavy integrated mills compete with asset-light licensed treatment providers across hospitality and healthcare procurement channels. The vendor base separates into captive finishers operating coating lines, technology licensors extending brand reach through regional converters, and chemical suppliers providing formulated repellent systems. Three archetypes dominate: integrated textile manufacturers controlling substrate-to-finish pipelines, specialty finishing houses licensing proprietary barrier chemistries, and diversified chemical conglomerates supplying formulated systems. Capacity expansion in Chinese coastal clusters and strategic partnerships between European mills and automotive OEMs represent the dominant competitive moves.
Within the integrated manufacturer tier, Milliken and Company anchors North American supply through South Carolina-based operations, while Crypton Fabric exemplifies premium positioning through proprietary barrier technology. Applied Textiles occupies the asset-light licensing position, enabling regional converters to access proprietary chemistries without captive capital investment.
| Leading Market Players |
|---|
| Crypton Fabric |
| Applied Textiles |
| DuPont |
| Nano-Tex |
| Sunbrella |
| Milliken and Company |
| 3M |
| The Chemours Company |
| Huntsman Corporation |
| Others |
Value Network & Pricing Analysis
Hospitality procurement teams mandating fluorine-free chemistry specifications are forcing mills to absorb reformulation costs while maintaining performance warranties, compressing margins in standard-tier finishing and widening spreads to premium nanotechnology tiers.
Pricing Analysis
Bundled substrate-plus-treatment contracts dominate hospitality and automotive channels, while unbundled chemical supply agreements serve regional converters accessing licensed finishing programs. Three-tier pricing structure across premium, standard, and economy levels separates plasma-deposited nanolayer systems from silicone-hydrocarbon hybrids and conventional water-repellent treatments. Cost compression in standard-tier silicone emulsions is intensifying because Shaoxing cluster capacity expansion outpaces specification-grade demand growth. Home textile retail channels exhibit highest price sensitivity, while healthcare upholstery buyers accept premium positioning for OEKO-TEX Standard 100 certified barrier systems.
Supply Chain Analysis
Finishing chemist and coating technician shortages in Zhejiang province and South Carolina constrain batch consistency at scale-up fluorine-free lines. Raw material flows draw from German chlorosilane production, Chinese organosilicon precursor synthesis, and Italian specialty chemical formulation. Single-source vulnerability concentrates in C6 fluorotelomer intermediates as REACH Annex XVII eliminates C8 alternatives. Distribution runs through direct mill engagement with hospitality sustainability offices, bypassing traditional textile distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-stain fabrics constitute a late-cycle quality story as procurement authority consolidates in corporate sustainability offices demanding verified fluorine-free performance without durability trade-offs.
For Market Incumbents: Anticipate accelerated silicone-hydrocarbon hybrid patent filings by Italian and Portuguese mills seeking to lock in hospitality specification channels before REACH deadlines eliminate legacy chemistry options. Prioritize backward integration into plasma-enhanced deposition equipment to capture nanotechnology tier premiums and defend against asset-light licensed treatment providers eroding mid-market share. For New Entrants and Emerging Players: EU Green Deal chemical restrictions in European markets open a window for fluorine-free formulation specialists to capture contract furniture specification demand from mills struggling with batch consistency. Target Indian hospitality buildout in Mumbai and Bangalore where BIS certification requirements create qualification barriers for established European suppliers. Lead with licensed treatment program models minimizing captive capital investment. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty finishing houses possessing validated fluorine-free chemistries and existing OEKO-TEX Standard 100 certification infrastructure. Five-to-ten-year viability hinges on performance parity achievement against legacy fluoropolymer benchmarks. Monitor AATCC abrasion testing data from early nanotechnology deployments as the inflection signal for warranty-backed scale-up readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Chemistry Scale-Up | REACH Annex XVII compliance secures European hospitality and automotive specification channels. |
| Plasma-Enhanced Deposition Investment | Bavarian and South Carolina equipment installations enable smaller-batch regional production. |
| Licensed Treatment Program Expansion | Applied Textiles model extends proprietary barrier reach without converter capital burden. |
| Indian Hospitality Certification Buildout | BIS fire-retardant stain-resistant qualification captures Mumbai and Bangalore hotel construction. |
| Silicone-Hydrocarbon Hybrid Development | Italian and Portuguese mill R&D targets durability parity before C8 chemistry elimination. |
Research Methodology
Multiple input streams — mill technical director interviews, hospitality procurement manager discussions, chemical supplier formulation briefings, and regulatory compliance officer consultations — were reconciled against customs trade data, OEKO-TEX certification registries, SEC textile sector filings, and GB standards administration records. Bottom-up volume estimates from substrate-specific finishing throughput were cross-validated against top-down chemical consumption patterns reported by chlorosilane and fluorotelomer precursor suppliers.
Historical capacity utilization trends across Shaoxing and South Carolina finishing clusters were cross-referenced with panel input from procurement directors at North American hospitality chains and German automotive OEM textile engineers. Segmentation modeling spanned substrate chemistry, barrier technology tier, end-use durability requirement, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and substitution rate assumptions across the analysis window, with fluorine-free formulation penetration curves calibrated to REACH enforcement timelines and EPA TSCA review trajectories.
Revisions become necessary when REACH Annex XVII enforcement intensity deviates, plasma-deposited nanolayer cost curves inflect, or Shaoxing cluster expansion outpaces specification-grade quality control capacity. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective and Workwear Textiles
Garment Active Insulation Market
Protective and Workwear Textiles
Global Flame Resistant Fabric Market
Protective and Workwear Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Protective and Workwear Textiles
Stain-Resistant Fabric Market
Protective and Workwear Textiles
Industrial Curtains Market
Protective and Workwear Textiles
Rainwear Market
Protective and Workwear Textiles
Flame Resistant (FR) Coveralls Market
Protective and Workwear Textiles
Functional Workwear Apparel Market
Protective and Workwear Textiles
Industrial Protective Fabrics Market
Protective and Workwear Textiles
Water-Proof Dust Covers Market
Protective and Workwear Textiles
Winter Wear Market
Protective and Workwear Textiles
Global Industrial Protective Clothing Fabrics Market
Protective and Workwear Textiles
Global Fire Resistant Fabric Market
Protective and Workwear Textiles
Winter Hats Market
Protective and Workwear Textiles
Cut Resistant Fabrics Market
Protective and Workwear Textiles
Fashion Face Mask Market