
 Global Epsom Salt Market | 2026-2036
Global Epsom Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Global Epsom Salt Market Foresight
Pharmaceutical distribution channels is narrowing as compounders and direct-to-manufacturer contracts replace traditional wholesale intermediaries. K+S Kali GmbH anchors European supply through captive magnesium deposits in Germany. Tata Chemicals Limited leverages integrated soda ash-magnesium operations to compete on bulk industrial pricing. Church & Dwight Co., Inc. sustains North American retail shelf presence through branded consumer positioning.
Epsom salt, chemically magnesium sulfate heptahydrate, crystallizes from brine evaporation or dolomite acid treatment and delivers magnesium ions for agricultural soil amendment, pharmaceutical compounding, and cosmetic formulation at minimum 99.5 percent purity for pharmaceutical applications. Pharmaceutical grade commands the deepest margin pool due to USP certification requirements and limited qualified supply, while cosmetic grade experiences the fastest volume expansion as clean-label personal care brands reformulate with mineral actives. Agricultural grade remains mature with price-transparent bulk contracts dominating procurement between fertilizer distributors and farming cooperatives.
FDA monograph standards govern US pharmaceutical-grade magnesium sulfate purity and labeling, while REACH registration in Europe mandates full toxicological dossiers for cosmetic and industrial volumes above one ton annually. India's CDSCO enforces IP-grade certification for injectable applications, creating a three-tier regulatory landscape that filters market access by compliance capability. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards to avoid stranded inventory in cross-border pharmaceutical trade.
Market Dynamics
REACH compliance in Europe is tightening purity thresholds for cosmetic-grade material, forcing supply chain requalification and compressing qualified supplier pools across pharmaceutical and personal care channels.
Growth Catalysts
- Therapeutic bath programs:Wellness centers across Germany and Japan are expanding magnesium sulfate procurement for hydrotherapy and recovery protocols, pulling premium-grade volumes into hospitality channels.
- Pharmaceutical manufacturing corridors:Demand is concentrating in India's pharmaceutical manufacturing corridor around Hyderabad and Ahmedabad, where CDSCO IP-grade certification for injectable applications drives qualified supply expansion.
- Clean-label personal care reformulation:Cosmetic brands are reformulating with mineral actives, accelerating cosmetic-grade volume expansion as mineral-based positioning displaces synthetic alternatives in premium personal care.
Market Restraints
- Brine evaporation input volatility:Agricultural-grade epsom salt remains exposed to energy cost swings in thermal brine processing, compressing margin buffers for bulk fertilizer distributors.
- German supply concentration:Captive magnesium deposits in Germany anchor European pharmaceutical-grade supply, creating geographic single-point vulnerability for USP-certified material.
- Dolomite acid treatment substitution:Synthetic magnesium sulfate from chemical processing competes on price in industrial applications, pressuring natural-source producers in non-pharmaceutical segments.
Strategic Opportunities
- Underpenetrated Southeast Asian wellness infrastructure:Spa and thermal bath development in Thailand and Indonesia presents white space for cosmetic-grade epsom salt distribution partnerships.
- EU Green Deal chemical sustainability mandates:REACH-registered natural-source magnesium sulfate gains preference in cosmetic formulations as brands document renewable feedstock credentials.
- Direct-to-manufacturer compounding contracts:Pharmaceutical distribution channels are narrowing as compounders replace wholesale intermediaries, enabling margin capture for qualified producers with CDSCO and USP dual certification.
Industry Challenges
- Pharmacopeial harmonization complexity:Cross-border pharmaceutical trade requires simultaneous compliance with USP, EP, and JP standards, creating inventory stranding risk during specification transitions.
- CDSCO certification timeline compression:Injectable-grade qualification in India demands extended stability testing protocols, delaying market entry for new production facilities by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Epsom Salt Market |
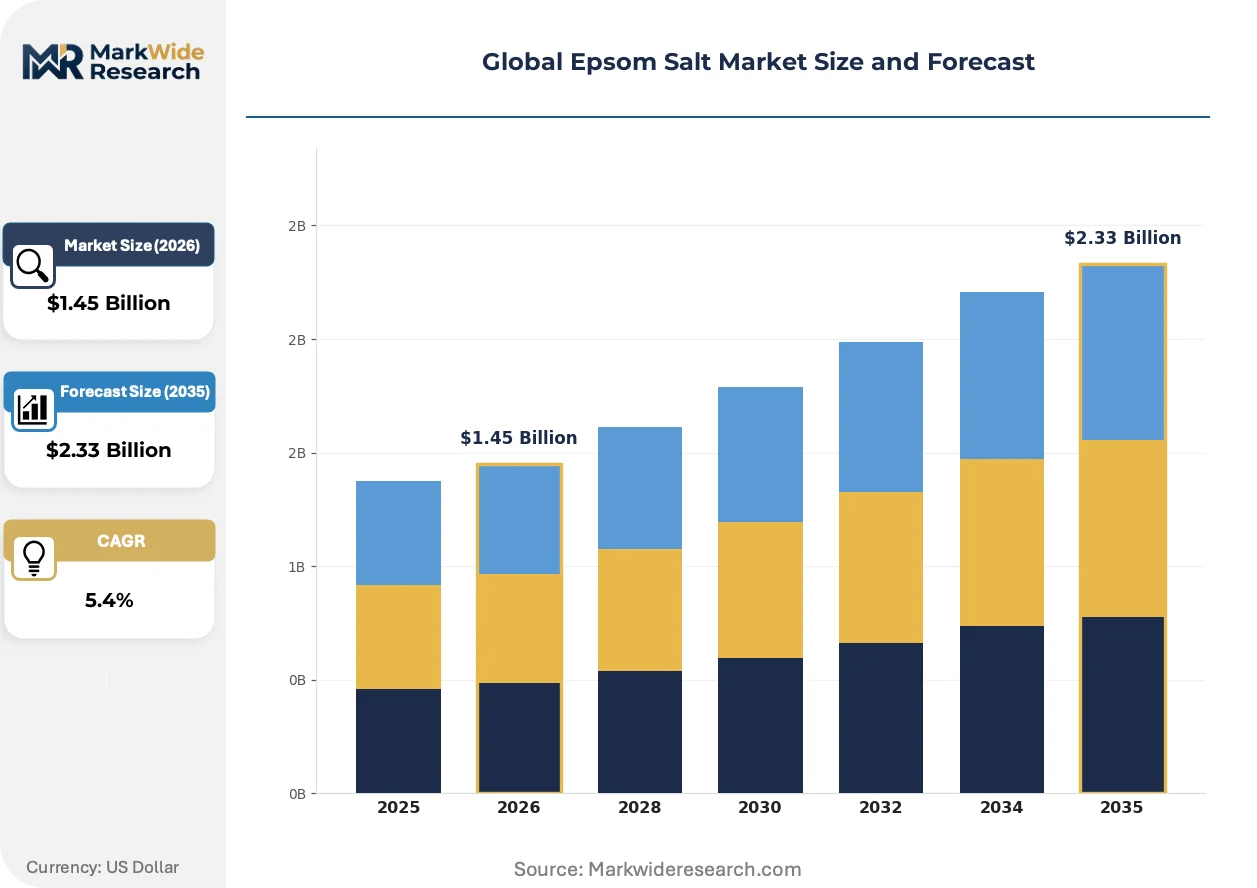
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Grade, Pharmaceutical Grade, Industrial Grade, Agricultural Grade, Cosmetic Grade Application: Soil Fertilizer, Bath & Spa, Medical Treatment, Beauty Care, Food Additive End User: Gardeners, Wellness Centers, Pharmaceutical Manufacturers, Cosmetic Companies, Food Processing Units Packaging Type: Plastic Bags, Paper Bags, Cartons, Bulk Containers, Sachets |
| Companies Covered | Church & Dwight Co., Inc., K+S Kali Gmbh, Compass Minerals International, Shiseido Company Limited, Unilever PLC, Solvay S.A., Tata Chemicals Limited, Giles Chemical, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Epsom Salt Market Shifts & Advancements
Continuous crystallization technology is collapsing batch processing economics in magnesium sulfate production, while regulatory harmonization pressures and channel consolidation are rewiring how pharmaceutical-grade material reaches end-formulators.
Membrane filtration-assisted crystallization is collapsing energy requirements in brine evaporation operations. Agricultural and industrial-grade producers across the United States and China are retrofitting facilities with continuous processing modules that cut thermal input by half. This technology is collapsing the cost gap between natural-source and synthetic magnesium sulfate in bulk fertilizer applications.
REACH registration mandates in Europe now require full toxicological dossiers for cosmetic and industrial volumes above one ton annually. ECHA's expanded substance evaluation program is disqualifying legacy suppliers lacking comprehensive safety data. Cosmetic-grade producers with pre-registered dossiers are capturing shelf space as clean-label brands demand documented compliance for mineral actives.
Compounders and direct-to-manufacturer contracts are displacing traditional wholesale intermediaries in pharmaceutical distribution. Bulk buyers in India's injectable manufacturing sector now negotiate directly with K+S Kali GmbH and Tata Chemicals Limited for qualified supply. This channel compression is most visible in Hyderabad, where pharmaceutical clusters have consolidated procurement functions to secure USP-certified volumes under long-term offtake agreements.
Global Epsom Salt Market Segmentation
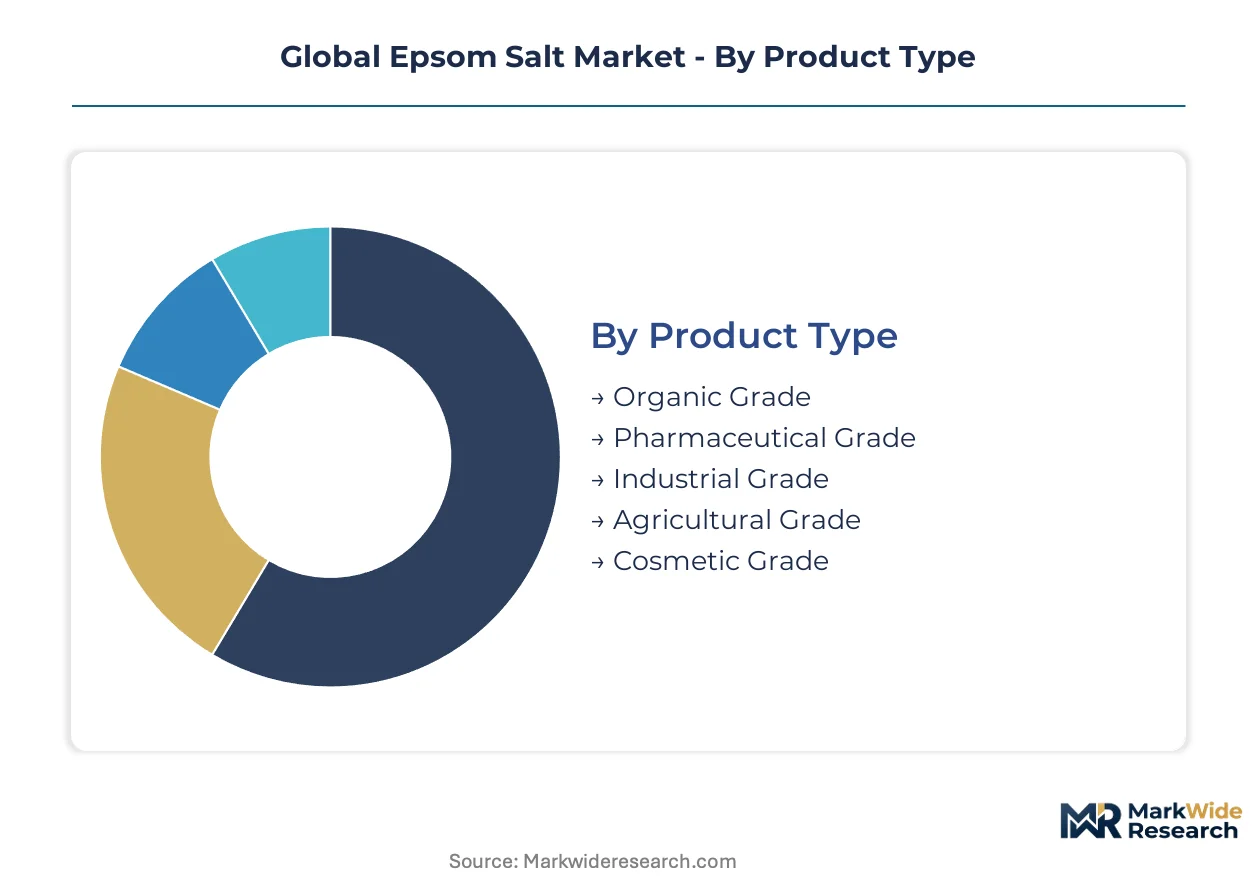
Epsom salt segmentation reflects divergent purity requirements and regulatory pathways across end-use channels. Grade certification determines margin capture, while packaging and distribution configurations adapt to procurement scale from bulk agricultural offtake to unit-dose pharmaceutical dispensing.
Product Type:
Mature industrial and agricultural grades anchor volume, while emerging cosmetic and pharmaceutical certifications command premium positioning.
- Pharmaceutical Grade:USP-certified magnesium sulfate heptahydrate meets injectable and compounding specifications with minimum 99.5 percent purity. Hyderabad and Ahmedabad pharmaceutical corridors concentrate demand for CDSCO IP-grade material under long-term offtake agreements with qualified producers.
- Cosmetic Grade:REACH-registered material serves clean-label personal care reformulation with documented toxicological dossiers. Wellness centers across Germany and Japan pull premium volumes into hospitality channels as mineral-based positioning displaces synthetic alternatives.
- Organic Grade:Agricultural certification for organic farming cooperatives requiring natural-source documentation.
- Industrial Grade:Bulk chemical processing feedstock competing with synthetic magnesium sulfate from dolomite acid treatment.
- Agricultural Grade:Mature fertilizer amendment segment with price-transparent contracts between distributors and farming cooperatives.
Agricultural Grade retains volume leadership; Cosmetic Grade holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity soil amendment from certified therapeutic and pharmaceutical uses.
- Medical Treatment:Injectable magnesium sulfate for eclampsia and arrhythmia management requires simultaneous USP, EP, and JP compliance. CDSCO certification timelines in India extend stability testing protocols, compressing qualified supplier pools.
- Bath & Spa:Hydrotherapy and recovery protocols in Germany and Japan wellness infrastructure drive cosmetic-grade procurement. Thailand and Indonesia spa development presents distribution partnership white space.
- Soil Fertilizer:Bulk agricultural amendment with energy-cost exposure in thermal brine processing.
- Beauty Care:Mineral-active personal care formulations requiring REACH dossier documentation.
- Food Additive:FCC-grade magnesium sulfate for beverage and supplement applications.
Soil Fertilizer dominates tonnage; Bath & Spa climbs the fastest on wellness infrastructure expansion.
End User:
Customer type determines procurement channel structure from wholesale agricultural distribution to direct pharmaceutical compounding.
- Pharmaceutical Manufacturers:Compounders in India's injectable sector negotiate directly with qualified producers, displacing traditional wholesale intermediaries. Dual USP-CDSCO certification enables margin capture through channel compression.
- Wellness Centers:Germany and Japan therapeutic bath programs expand magnesium sulfate procurement for hydrotherapy protocols.
- Gardeners:Retail consumer segment served through branded shelf presence in North American markets.
- Cosmetic Companies:Clean-label brands demanding REACH-registered mineral actives with renewable feedstock credentials.
- Food Processing Units:FCC-grade material for fortification and processing applications.
Pharmaceutical Manufacturers concentrate value capture; Wellness Centers gain share fastest on hospitality channel development.
Packaging Type:
Volume scale dictates format from unit-dose sachets to bulk container agricultural offtake.
- Bulk Containers:Agricultural-grade fertilizer distributors and farming cooperatives procure through transparent price contracts. Energy cost volatility in thermal brine processing compresses margin buffers at this scale.
- Plastic Bags:Retail consumer and garden center distribution for branded Epsom salt positioning.
- Paper Bags:Sustainability-aligned cosmetic and wellness channel packaging.
- Cartons:Pharmacy and professional spa channel presentation formats.
- Sachets:Unit-dose pharmaceutical and hospitality amenity applications.
Bulk Containers retain volume leadership; Sachets hold the steepest expansion curve on pharmaceutical unit-dose growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA monograph standards anchor the United States as the dominant geography for pharmaceutical-grade magnesium sulfate certification, while REACH registration in Europe and CDSCO enforcement in India create a three-tier regulatory landscape filtering market access by compliance capability.
United States
Pharmaceutical compounding and injectable manufacturing drive USP-certified demand through FDA-regulated channels. FDA monograph standards govern purity and labeling requirements for pharmaceutical-grade material. Houston and New Jersey pharmaceutical corridors concentrate bulk procurement under long-term offtake agreements with qualified producers.
Germany
Wellness centers across Bavaria and Baden-Württemberg expand magnesium sulfate procurement for therapeutic bath programs and hydrotherapy protocols. REACH compliance tightens purity thresholds for cosmetic-grade material, forcing supply chain requalification. Captive magnesium deposits in Lower Saxony anchor European pharmaceutical-grade supply through integrated chemical operations.
India
Injectable-grade manufacturing concentrates in Hyderabad and Ahmedabad pharmaceutical corridors where CDSCO enforces IP-grade certification. CDSCO certification timelines demand extended stability testing protocols, delaying market entry for new facilities by 18-24 months. Direct-to-manufacturer contracts displace wholesale intermediaries as compounders negotiate directly with qualified producers for USP-certified volumes.
Japan
Wellness infrastructure in Kanto and Kansai regions pulls premium cosmetic-grade volumes into hospitality channels for hydrotherapy and recovery protocols. METI standards align with pharmacopeial harmonization pressures between USP, EP, and JP specifications. Tokyo and Osaka spa development accelerates mineral-active personal care reformulation with documented compliance credentials.
China
Membrane filtration-assisted crystallization retrofits thermal brine processing facilities across Shandong and Jiangsu provinces. NMPA standards govern pharmaceutical-grade certification while GB standards regulate industrial applications. Yangtze River Delta chemical clusters compete on bulk fertilizer pricing against synthetic magnesium sulfate from dolomite acid treatment.
Global Epsom Salt Market Competitive Landscape
Integrated chemical conglomerates and specialty mineral processors split the market between bulk industrial supply and certified pharmaceutical channels. K+S Kali GmbH anchors European supply through captive magnesium deposits, while Tata Chemicals leverages integrated soda ash-magnesium operations. Three archetypes dominate: vertically integrated chemical majors, regional brine evaporation specialists, and branded consumer goods marketers. Competitive moves concentrate on direct-to-manufacturer contract consolidation and REACH dossier pre-registration for cosmetic-grade shelf space capture.
Among German-based chemical majors, K+S Kali GmbH exemplifies the captive-resource archetype through integrated magnesium deposit control. Tata Chemicals Limited occupies a position representing integrated soda ash-magnesium operations competing on bulk industrial pricing. Church & Dwight Co., Inc. anchors the branded consumer positioning archetype sustaining North American retail shelf presence.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| K+S Kali Gmbh |
| Compass Minerals International |
| Shiseido Company Limited |
| Unilever PLC |
| Solvay S.A. |
| Tata Chemicals Limited |
| Giles Chemical |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Undercapacity in USP-certified pharmaceutical-grade capacity across Germany and India is driving supplier discipline and sustaining premium pricing power for qualified producers. Contract renegotiations in Hyderabad and Ahmedabad pharmaceutical corridors reflect this tightness, with compounders accepting longer-term offtake commitments to secure CDSCO IP-grade volumes.
Pricing Analysis
Geographic price spreads between European REACH-registered cosmetic-grade material and bulk agricultural-grade volumes in China and the United States exceed threefold, reflecting certification burden differentials. Three-tier pricing structure across pharmaceutical, cosmetic, and agricultural grades separates USP-certified injectable material from wellness-channel cosmetic volumes from commodity fertilizer amendment. Cost compression in agricultural-grade brine evaporation is intensifying because membrane filtration retrofits in Shandong and Jiangsu provinces are collapsing synthetic-natural cost gaps. Fertilizer distributors and farming cooperatives exhibit highest price sensitivity, while pharmaceutical compounders demonstrate lowest sensitivity due to regulatory switching costs.
Supply Chain Analysis
Contract manufacturing concentration for pharmaceutical-grade material rests with K+S Kali GmbH in Lower Saxony and Tata Chemicals Limited across Gujarat and Tamil Nadu. Germany, India, and China anchor global supply, with captive magnesium deposits in Germany, CDSCO-certified facilities in India, and membrane-filtered brine operations in China. Raw material dependencies include dolomite ore, sulfuric acid, and thermal energy inputs. Single-source vulnerability concentrates in German pharmaceutical-grade supply, where captive deposit control limits qualified alternatives. Distribution runs through direct-to-manufacturer contracts displacing wholesale intermediaries in pharmaceutical channels, while bulk agricultural offtake moves through fertilizer distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Epsom salt market is recovering from cyclical lows in agricultural-grade pricing, with wellness infrastructure investment and pharmaceutical compounding demand providing cyclical lift. Membrane filtration cost reductions and REACH regulatory tightening are restructuring competitive economics across grade tiers.
For Market Incumbents: Harden USP-CDSCO dual certification positions through accelerated stability testing investments, compressing the 18-24 month Indian regulatory timeline that threatens supply security. Defend margin buffers in cosmetic-grade channels by pre-registering REACH dossiers ahead of ECHA substance evaluation disqualifications. Backward integration into captive brine sources in Germany or continuous crystallization retrofits in India reduces energy cost exposure that synthetic competitors exploit. For New Entrants and Emerging Players: Mid-market wellness infrastructure in Thailand and Indonesia represents the most penetrable entry point for cosmetic-grade distribution partnerships, as hospitality channel development outpaces qualified local supply. Southeast Asian spa operators lack documented REACH-registered mineral active sourcing, creating shelf space for compliant entrants. Direct distribution agreements with thermal bath developers in Bali and Phuket bypass established wholesale structures that incumbents control. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across membrane filtration-assisted crystallization operations, enabling mid-scale entrants to achieve cost parity with legacy thermal brine facilities. Long-term viability over the next decade favors producers with dual pharmacopeial certification and pre-registered REACH dossiers. Acquisition targets should display USP-EP-JP harmonization capability and direct pharmaceutical compounding relationships. The signal to watch is CDSCO approval timeline compression for new Indian facilities, which would indicate regulatory capacity expansion and qualified supply inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Pre-registration | Cosmetic-grade producers with ECHA-compliant toxicological data capture shelf space as clean-label brands demand documented mineral active credentials. |
| Continuous Crystallization Retrofit | Membrane filtration-assisted processing cuts thermal energy requirements by half, collapsing synthetic-natural cost gaps in bulk fertilizer applications. |
| Direct-to-Manufacturer Contracting | Pharmaceutical compounders in Hyderabad negotiate long-term offtake agreements with qualified producers, displacing wholesale intermediaries and capturing margin. |
| Dual Certification Investment | USP-CDSCO qualified supply enables premium positioning in India's injectable manufacturing corridor where regulatory switching costs limit competition. |
| Southeast Asian Distribution Partnership | Wellness infrastructure development in Thailand and Indonesia creates white space for cosmetic-grade entrants lacking established hospitality channel relationships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical compounding, cosmetic formulation, and agricultural distribution channels. Primary interviews captured perspectives from plant managers at brine evaporation facilities, procurement leads at Indian injectable manufacturers, regulatory affairs directors navigating CDSCO timelines, and wellness center operators in Germany and Japan. Secondary validation drew from FDA monograph filings, ECHA REACH registration databases, CDSCO approval records, and customs trade data for magnesium sulfate flows. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers to ensure consistency across grade-tier projections.
Calibration against historical capacity utilization patterns and regulatory approval timelines anchored forward projections across the analysis window. Segmentation dimensions modeled include grade certification tier, end-use application channel, packaging format scale, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating wellness infrastructure buildout rates, pharmaceutical manufacturing corridor expansion, and agricultural fertilizer amendment cyclicality. Industry-specific forecast inputs captured membrane filtration adoption curves in Chinese brine processing and REACH dossier registration velocity in European cosmetic supply.
Practitioners should monitor CDSCO certification timeline compression, ECHA substance evaluation disqualifications, and energy cost volatility in thermal brine processing for early signals of forecast revision. Assumptions underlying projections reflect current regulatory frameworks, technology adoption trajectories, and channel structure evolution. Quarterly review of pharmacopeial harmonization negotiations, wellness center procurement patterns, and synthetic magnesium sulfate price spreads is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
China Feed Minerals Market
Industrial Minerals
Strategic Mineral Materials Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
Limestone Market
Industrial Minerals
Slate Market
Industrial Minerals
Perlite Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
North America Silica Sand Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Mineral Sand Market
Industrial Minerals
Nepheline Syenite Market