
 Potash Ores Market | 2026-2036
Potash Ores Market Size, Share, and Industry Trends Forecast 2026-2036
Potash Ores Market Analysis
The EU Green Deal is repositioning European fertilizer procurement toward low-carbon potash sources. Nutrien Ltd. leverages its Saskatchewan mining footprint to supply certified-sustainable product to EU buyers. K+S GmbH anchors its position through German potash processing and salt diversification. EuroChem Group AG competes via Russian-Kazakh mining assets and ammonia integration.
Potash ores are potassium-bearing sedimentary or evaporite deposits, typically containing 15-30% K2O equivalent, extracted through conventional underground mining or solution mining followed by flotation and crystallization to produce fertilizer-grade salts. Muriate of Potash dominates volume flows into commodity grain agriculture across North America and the Black Sea region. Sulfate of Potash commands premium positioning in specialty horticulture and chloride-sensitive crops where margin pools exceed standard fertilizer grades. The Distribution Channel dimension shows Direct Sales capturing bulk procurement from cooperatives and national fertilizer distributors, while Online Sales remains nascent outside developed agricultural economies.
Environment and Climate Change Canada enforces federal methane and tailings standards that shape extraction investment timelines for new Saskatchewan projects. The EPA regulates phosphate and potash mining waste under the Mineral Mining and Processing effluent guidelines, affecting US domestic production economics. ISO 14001 certification increasingly gates contract eligibility with European and East Asian offtakers. Stakeholders must track how carbon border adjustment mechanisms reshape competitive access for producers with divergent emission profiles.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is redirecting procurement flows toward certified low-carbon potash, forcing extraction investments in Saskatchewan and German processing assets to decarbonize ahead of 2026 compliance deadlines.
Growth Catalysts
- Brazilian sustainable agriculture mandates:ANVISA and MAPA regulations on soil health certification are accelerating offtake from potash producers able to document supply chain emissions. Fertilizer cooperatives in Mato Grosso and Paraná now require ISO 14001 documentation.
- Solution mining technology:Selective dissolution and crystallization methods reduce surface disturbance and water intensity versus conventional shaft mining. Saskatchewan regulators favor these techniques for new lease approvals.
- REACH registration completion:ECHA's full chemical safety dossier requirements for imported fertilizers have cleared the pathway for standardized EU-wide product acceptance. This eliminates previous national-level fragmentation.
Market Restraints
- Natural gas cost volatility:Solution mining and processing operations in Germany and Russia face input cost instability tied to TTF and Henry Hub pricing. Energy intensity per tonne of K2O equivalent remains structurally high.
- Saskatchewan supply concentration:Over 60% of exportable reserves sit within a 300-kilometer radius, creating single-point-of-failure exposure for Asian buyers dependent on Vancouver port infrastructure.
- Chloride substitution in specialty crops:Organic and high-value horticulture operations are shifting toward compost-based potassium sources. Sulfate of Potash premiums cannot fully offset volume erosion.
Strategic Opportunities
- Thai and Vietnamese rice belt expansion:Double-cropping intensification in the Mekong Delta and Central Plains creates demand for chloride-tolerant Muriate of Potash at scale. Local blending facilities remain underdeveloped.
- EU Carbon Border Adjustment Mechanism phase-in:CBAM's 2026-2034 transition period rewards early movers with verified low-carbon production. Saskatchewan producers with methane capture qualify for preferential tariff treatment.
- Direct-to-cooperative digital platforms:Agritech marketplaces in Brazil and Australia are disintermediating traditional distributor networks. Producers with logistics integration capture 8-12 point margin expansion.
Industry Challenges
- Solution mining brine management expertise:The specialized hydrogeology and reservoir engineering skill set required for safe cavern operation is concentrated among a narrow cohort of Saskatchewan and Utah practitioners. Training pipelines lag project timelines.
- ISO 14001 certification timeline compression:European offtakers now demand 18-month documentation cycles versus previous 36-month windows. Third-party auditor capacity creates bottlenecks for mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potash Ores Market |
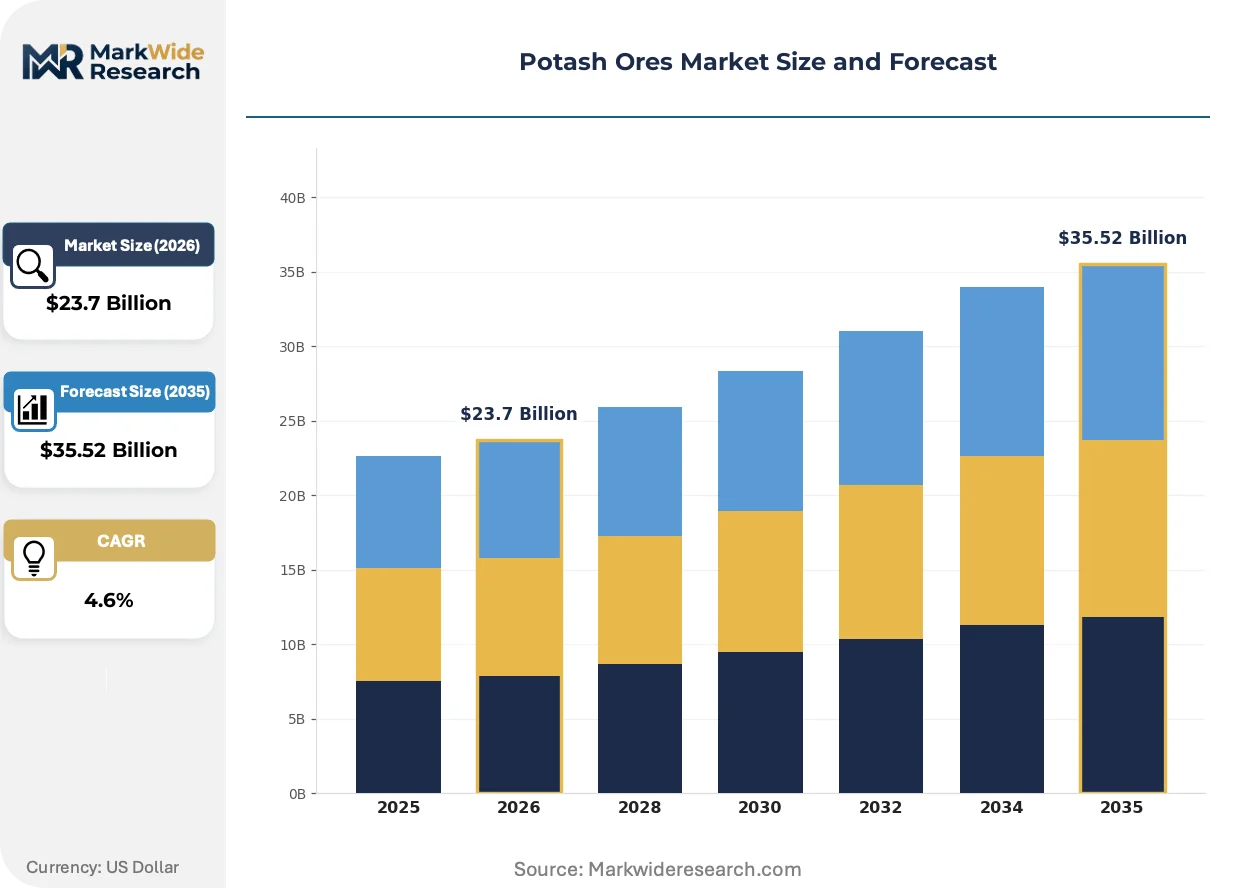
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $35.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Potash, Muriate of Potash, Sulfate of Potash, Potassium Nitrate End User: Agriculture, Horticulture, Gardening, Industrial Distribution Channel: Direct Sales, Retail, Online Sales, Distributors Packaging Type: Bags, Bulk, Drums, Containers |
| Companies Covered | Nutrien Ltd., The Mosaic Company, K+S GmbH, Uralkali PJSC, ICL Israel Chemicals Ltd., Compass Minerals International Inc., Intrepid Potash Inc., Vale S.A., EuroChem Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potash Ores Market Emerging Trajectories
Extraction and processing technologies are converging around emissions verification and water recycling, while regulatory frameworks in Europe and North America harden compliance thresholds. These shifts favor capital-rich incumbents with integrated logistics.
Selective dissolution mining combined with modular crystallization units is unifying extraction and beneficiation into single-site operations. Mid-tier Saskatchewan producers are piloting these systems to eliminate rail haul to remote processing plants. This compression reduces scope-three emissions and qualifies output for EU CBAM preferential entry.
Environment and Climate Change Canada's updated methane performance standards for underground mining operations now mandate continuous monitoring and quarterly reporting. Producers must retrofit ventilation and degasification infrastructure or face lease suspension. The regulation most heavily affects conventional shaft mines in the Lanigan and Esterhazy districts, where operators are accelerating solution mining transitions.
Buyer consolidation among Brazilian agricultural cooperatives is compressing procurement cycles and unbundling technical advisory services from product supply. Large cooperatives in Goiás and Mato Grosso now negotiate direct annual contracts with producers, displacing regional distributors. This pattern is most visible in the cerrado soybean belt, where three cooperatives control over 40% of imported potash offtake.
Potash Ores Market Segmentation
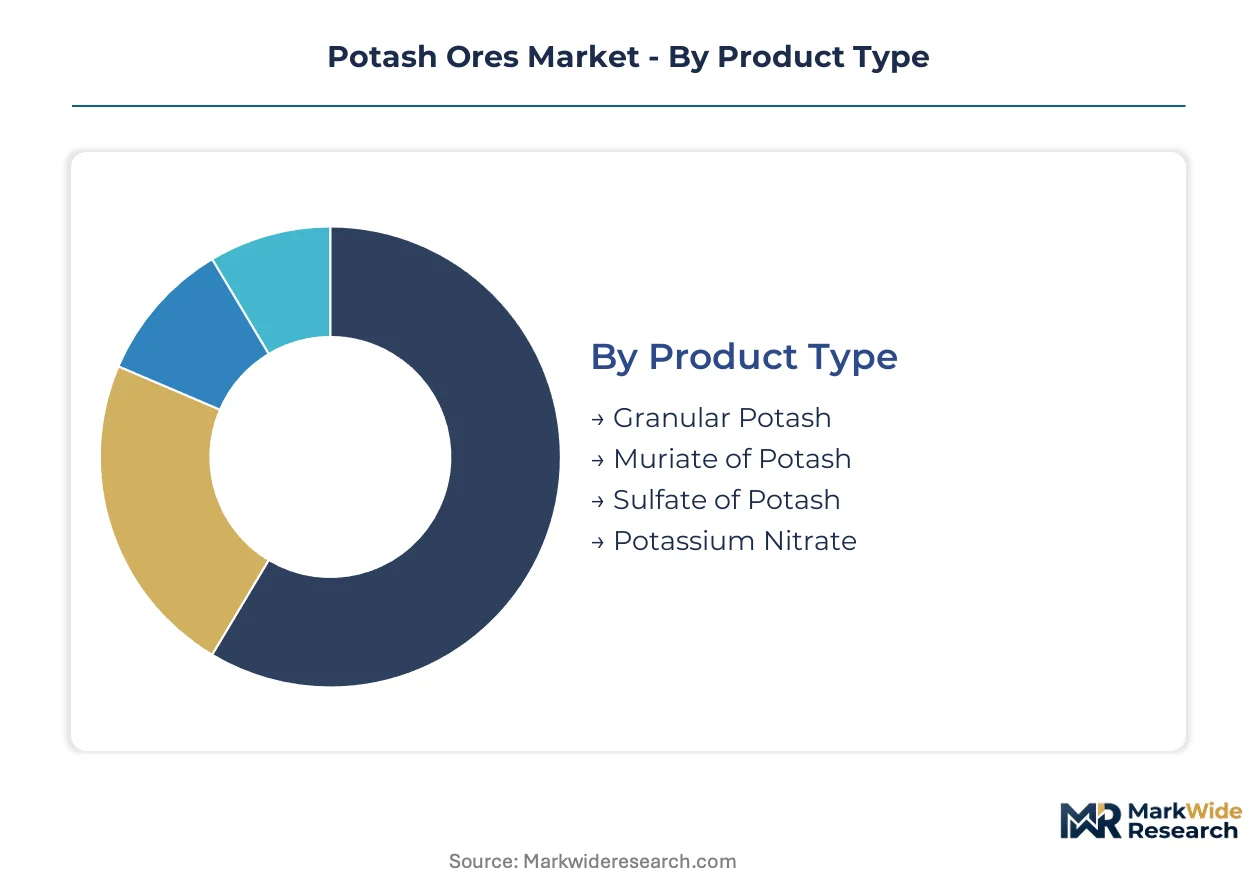
Potash ore differentiation hinges on chemical specification and handling requirements. Each segmentation axis shapes procurement economics, logistics configuration, and compliance pathways for producers and buyers.
Product Type:
Chemical composition and processing intensity define the product hierarchy, with chloride versus sulfate chemistry determining crop compatibility and margin structure.
- Granular Potash:Compact, free-flowing crystals sized for mechanical spreading equipment. Brazilian soybean cooperatives in Mato Grosso specify this grade for aerial application efficiency during narrow planting windows.
- Muriate of Potash:Potassium chloride concentrate containing 60-62% K2O equivalent. Thai and Vietnamese rice intensification programs absorb this grade at volume, though chloride sensitivity limits deployment on certain high-value vegetable rotations.
- Sulfate of Potash:Potassium sulfate with negligible chloride content commands premium positioning in specialty horticulture. Organic certification requirements in European markets sustain price premiums above standard fertilizer grades.
- Potassium Nitrate:Dual-nutrient salt supplying potassium and nitrogen in soluble form. Fertigation systems in protected greenhouse operations specify this grade for precision nutrient delivery.
Muriate of Potash leads on scale; Sulfate of Potash leads on momentum.
End User:
Application intensity and crop value stratify demand across volume-commodity and precision-agriculture segments.
- Agriculture:Broad-acre grain and oilseed production consumes standardized grades through cooperative procurement networks. Saskatchewan producers serve this segment via Vancouver port infrastructure bound for Asian buyers.
- Horticulture:High-value fruit, vegetable, and ornamental operations require chloride-free or low-chloride specifications. EU Green Deal carbon accounting favors certified-sustainable product in this segment.
- Gardening:Consumer-scale packaging through retail channels. This segment shows nascent digital platform penetration in developed agricultural economies.
- Industrial:Glass manufacturing, pharmaceuticals, and chemical feedstock applications. Quality specifications diverge sharply from agricultural grades, requiring separate processing lines.
Agriculture dominates tonnage; Horticulture expands most quickly.
Distribution Channel:
Channel selection determines working capital requirements and margin capture for producers navigating buyer consolidation trends.
- Direct Sales:Annual contracts between producers and national fertilizer cooperatives. Brazilian agricultural cooperative consolidation has compressed procurement cycles in this channel.
- Retail:Regional distributor networks providing technical advisory and last-mile logistics. This channel faces disintermediation pressure from digital platforms in Brazil and Australia.
- Online Sales:Agritech marketplaces enabling direct producer-to-cooperative transactions. Logistics integration remains underdeveloped outside developed agricultural economies.
- Distributors:Independent intermediaries aggregating smallholder demand. Margin compression from buyer consolidation limits growth in this channel.
Direct Sales commands volume; Online Sales gains share fastest.
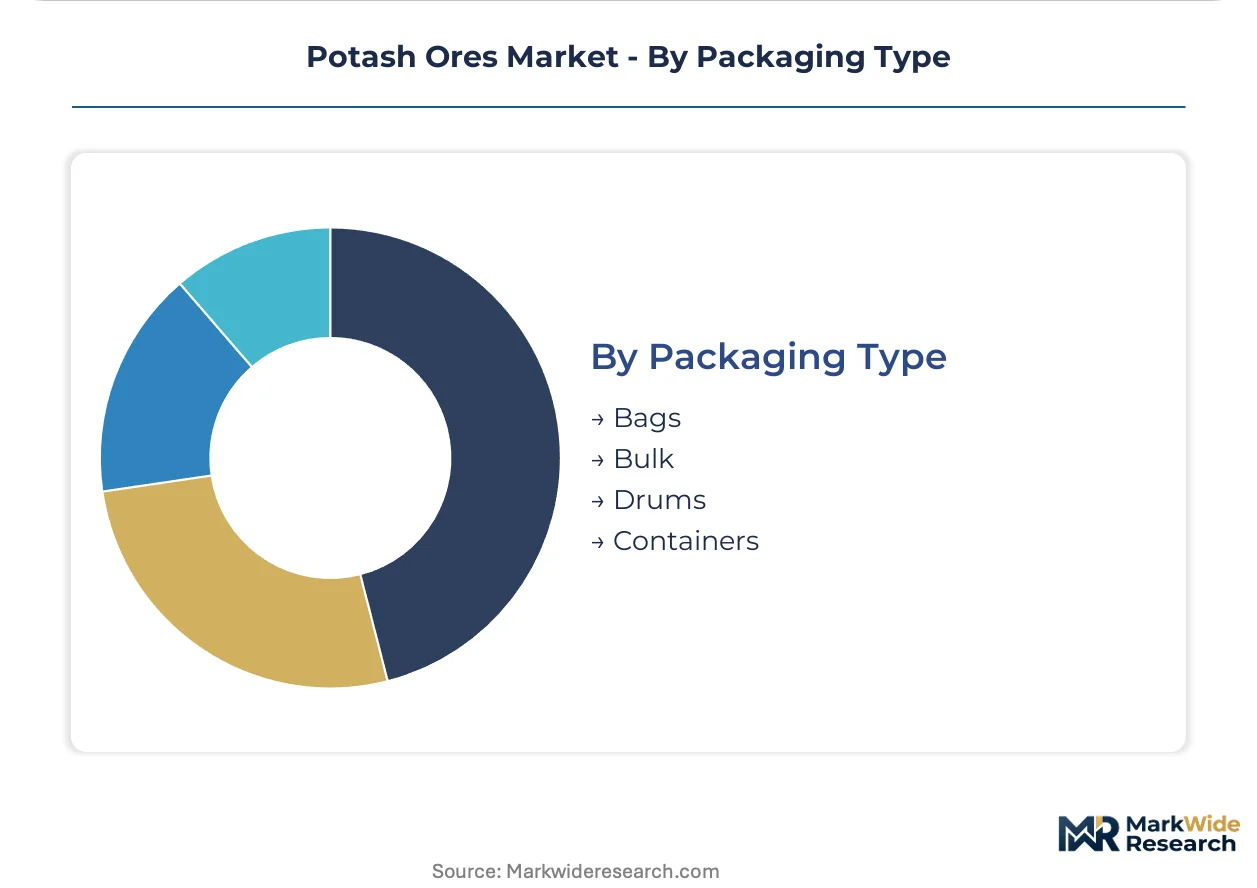
Packaging Type:
Handling economics and contamination risk shape packaging selection across bulk commodity and precision-application segments.
- Bags:50-kilogram woven polypropylene units for smallholder and retail distribution. This format dominates horticulture and gardening segments where batch precision matters.
- Bulk:Unpackaged product moved via rail, vessel, and pneumatic handling systems. Vancouver port infrastructure and Saskatchewan rail networks optimize this format for Asian agricultural buyers.
- Drums:Sealed steel or fiber containers for moisture-sensitive industrial grades. Limited deployment in agricultural applications due to cost premium.
- Containers:Intermediate bulk containers and flexitanks for specialized liquid or soluble formulations. Fertigation and hydroponic operations specify this handling format.
Bulk leads on scale; Containers climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized mining engineers and hydrogeologists concentrate in Saskatchewan's potash belt, where solution mining expertise underpins continental supply security. This workforce concentration shapes investment timelines and technology transfer patterns across producing regions.
Canada
Saskatchewan's Lanigan and Esterhazy districts host conventional shaft mines transitioning to solution methods under Environment and Climate Change Canada methane rules. The provincial mining regulator favors selective dissolution for new lease approvals. Vancouver port infrastructure channels certified-sustainable product toward Asian fertilizer cooperatives.
Brazil
Mato Grosso and Paraná agricultural cooperatives drive offtake as ANVISA and MAPA tighten soil health certification requirements. The national fertilizer regulator now mandates ISO 14001 documentation for import eligibility. Cerrado soybean belt procurement consolidation compresses annual contracting cycles.
Germany
K+S GmbH processing assets in Hesse and Lower Saxony face EU Green Deal carbon border pressure. ECHA REACH registration clears standardized EU-wide acceptance pathways. The Werra-Fulda potash district sustains salt diversification amid energy cost volatility.
Thailand
Central Plains rice intensification absorbs Muriate of Potash for double-cropping systems. The national agricultural extension service promotes chloride-tolerant varieties. Bangkok-based blending facilities remain underdeveloped against Mekong Delta demand growth.
United States
Utah solution mining practitioners supply specialty Sulfate of Potash to western horticulture operations. EPA Mineral Mining and Processing effluent guidelines structure domestic production economics. The Great Salt Lake corridor concentrates brine extraction expertise.
Potash Ores Market Vendor Landscape
Capital-heavy producers compete with asset-light traders across extraction, processing, and distribution functions. The market structure consolidates around integrated miners with captive logistics, while mid-tier operators face margin compression from certification timeline compression. Three archetypes dominate: Saskatchewan-based solution mining specialists with Vancouver port access, German diversified processors with salt co-production, and Russian-Kazakh integrated miners with ammonia linkages. Capacity expansion and direct-to-cooperative digital platform development represent the dominant competitive vectors.
Within the integrated mining tier, Nutrien Ltd. and The Mosaic Company occupy positions defined by Saskatchewan basin concentration and North American distribution scale. K+S GmbH exemplifies the European processor archetype with German asset bases and EU regulatory compliance positioning. These three entities anchor competitive dynamics through divergent carbon intensity profiles and certification readiness against EU Carbon Border Adjustment Mechanism phase-in deadlines.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| The Mosaic Company |
| K+S GmbH |
| Uralkali PJSC |
| ICL Israel Chemicals Ltd. |
| Compass Minerals International Inc. |
| Intrepid Potash Inc. |
| Vale S.A. |
| EuroChem Group AG |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in Saskatchewan and family-owned mid-caps in Germany anchor supply discipline through long-term offtake contracting, insulating spot-market volatility while compressing margin capture for non-integrated traders. This ownership concentration tightens pricing power around Vancouver port logistics and EU carbon-border qualification thresholds.
Pricing Analysis
The bundled-versus-unbundled service split separates contract-based long-term offtake with embedded logistics from spot-market transactions carrying freight pass-through exposure. Price differentiation hinges on ISO 14001 certification tier and volume scale, with certified-sustainable product commanding freight-equivalent premiums into EU buyers. Cost compression in standard Muriate of Potash is intensifying because Brazilian cooperative consolidation squeezes distributor markups. Smallholder distributors in Thailand and Vietnam show highest price sensitivity; EU horticulture operations demonstrate lowest sensitivity due to organic certification requirements.
Supply Chain Analysis
Certification and qualification gating now determines contract eligibility, with ISO 14001 documentation and EU CBAM carbon intensity thresholds filtering supplier pools before price negotiation begins. Supply concentrates in Canada, Russia, and Germany, with extraction drawing from potash-bearing evaporite deposits and energy inputs resting on natural gas pricing volatility. Single-source vulnerability runs through Vancouver port infrastructure for Asian buyers. Distribution runs through direct annual contracts between producers and national fertilizer cooperatives, displacing traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
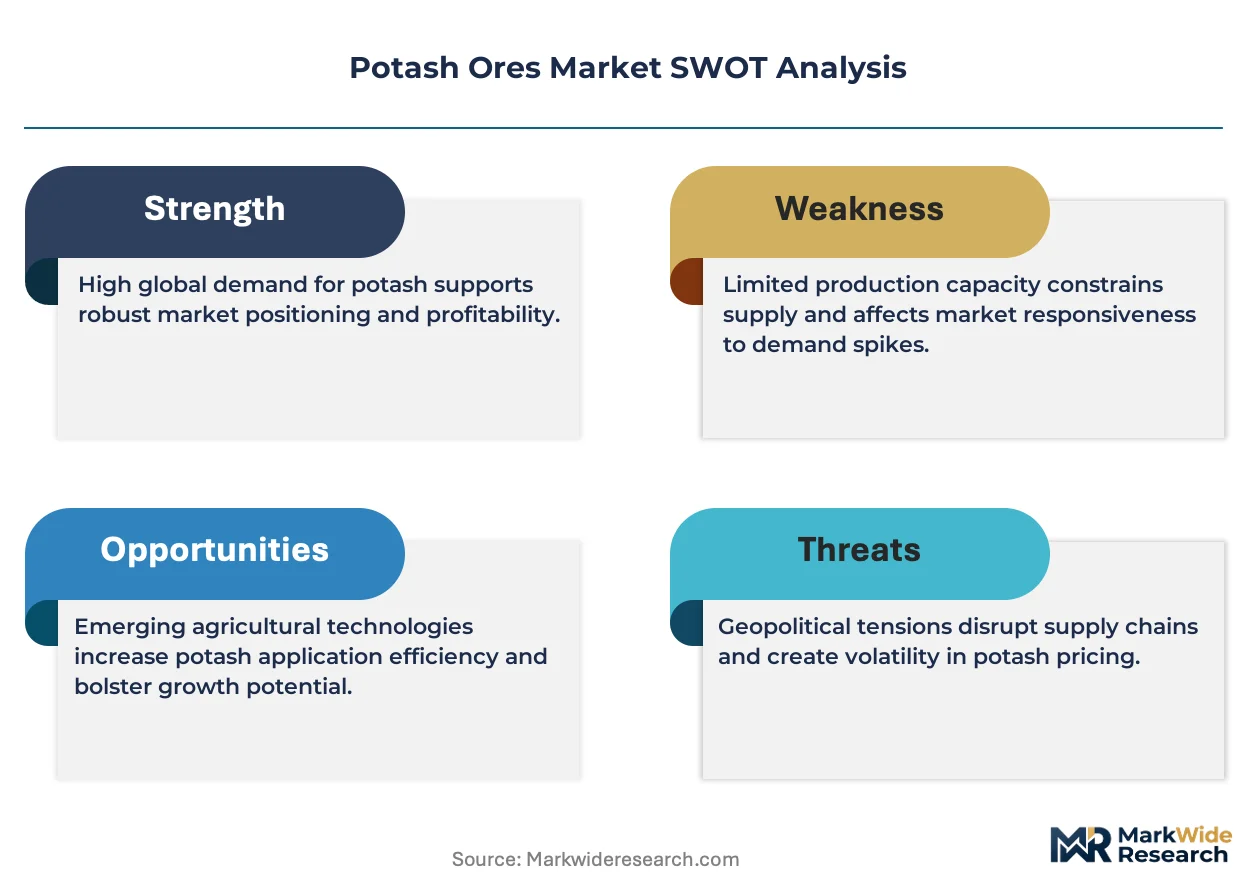
This market functions as a regulatory compounder, with EU Carbon Border Adjustment Mechanism phase-in and Brazilian ANVISA soil health mandates structurally expanding demand for certified-low-carbon product.
For Market Incumbents: Anticipate margin compression from solution mining technology diffusion by accelerating selective dissolution transitions in Saskatchewan's Lanigan and Esterhazy districts. Lock in backward integration into Vancouver port logistics to defend position against digital platform disintermediation. Prioritize methane capture retrofitting to maintain EU CBAM preferential tariff eligibility.
For New Entrants and Emerging Players: Agritech marketplace operators represent the most penetrable channel partner type for bypassing consolidated Brazilian cooperatives. Target underdeveloped blending facilities in Thailand's Central Plains and Vietnam's Mekong Delta where double-cropping intensification outpaces local processing capacity. Lead with direct-to-cooperative digital platforms offering logistics integration to capture margin expansion.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Saskatchewan producers lacking ISO 14001 certification but holding solution mining lease approvals. Long-term viability favors integrated miners with captive logistics and verified low-carbon production profiles. The signal to watch is Environment and Climate Change Canada lease suspension enforcement accelerating consolidation among conventional shaft mine operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Solution Mining Transition | Reduces methane exposure and qualifies output for EU CBAM preferential entry. |
| Direct-to-Cooperative Digital Platform | Disintermediates Brazilian distributor networks and captures 8-12 point margin expansion. |
| ISO 14001 Certification Investment | Gates contract eligibility with European and East Asian fertilizer cooperatives. |
| Backward Integration into Port Logistics | Secures Vancouver infrastructure access against Asian buyer concentration risk. |
| Methane Capture Retrofitting | Satisfies Environment and Climate Change Canada standards and sustains lease continuity. |
Methodological Framework
Coverage spans North America, Europe, South America, and Southeast Asia, with primary inputs from each region combined with secondary validation. Primary interviews engaged potash mine operations directors, Brazilian agricultural cooperative procurement managers, German processing plant engineers, and Thai rice extension service agronomists. Secondary sources included Environment and Climate Change Canada regulatory filings, ANVISA import documentation databases, ECHA REACH registration records, and Vancouver port authority trade statistics. Bottom-up reserve estimates and top-down demand modeling were triangulated against export flow data.
Rate-of-change decomposition separates volume growth from price trajectory shifts across the analysis window. Segmentation dimensions modeled include product chemistry tier, end-use crop intensity, distribution channel structure, and regional regulatory cluster. CAGRs were derived from production capacity expansion schedules, crop acreage intensification patterns, and carbon border mechanism phase-in assumptions. Industry-specific inputs incorporated solution mining technology adoption curves and Brazilian cooperative consolidation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU CBAM enforcement stringency and natural gas cost volatility in German processing. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology transfer rates. A model refresh is warranted upon material change in Environment and Climate Change Canada methane performance standard implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Limestone Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Strategic Mineral Materials Market
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Global Commercial Perlite Market
Industrial Minerals
Mineral Sand Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Boron Minerals and Chemicals Market
Industrial Minerals
Feldspar Mining Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Global and US Inorganic Salt Market