
 Global Water Clarifiers Market | 2026-2036
Global Water Clarifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water Clarifiers Market Foresight
Buyer concentration in the water clarifiers space is shifting as municipal utilities consolidate procurement through regional water authorities while industrial end users fragment across mid-sized chemical plants and food processing facilities. Evoqua Water Technologies leverages its integrated service model to anchor large-scale municipal contracts across North America. SUEZ competes through technology leadership in high-rate clarifier designs for dense urban installations. Veolia Water Technologies sustains its position via geographic dominance in European utility frameworks and extending into Middle Eastern desalination pretreatment.
Water clarifiers are separation units that remove suspended solids from liquid streams through gravitational settling, chemical coagulation, or flocculation, typically achieving turbidity reduction below 5 NTU for downstream filtration. Coagulants and flocculants dominate product-type revenue due to recurring chemical consumption, while sedimentation aids capture margin pools in high-solids industrial applications. Municipal water treatment remains the largest application segment though wastewater reuse is accelerating fastest as water-stressed regions mandate closed-loop systems. Fixed installations control deployment-type volume, yet cloud-based monitoring is displacing traditional oversight in advanced utility networks.
The EPA enforces effluent limitation guidelines that mandate tertiary clarification for specific industrial dischargers, while China's MEE implements dual carbon goals that tighten water reuse requirements and expand clarifier demand. REACH in Europe governs chemical clarifier formulations, restricting certain polyacrylamide chemistries and redirecting R&D toward bio-based alternatives. Stakeholders must monitor how regulatory divergence across these jurisdictions reshapes product certification burdens and determines which suppliers can operate across multiple compliance regimes.
Market Dynamics
Municipal procurement consolidation and tightening effluent standards are compressing vendor margins while expanding addressable volume for clarifier systems capable of meeting dual carbon and water reuse mandates.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Tertiary clarification mandates for specific industrial dischargers in the United States are forcing facility retrofits and expanding replacement demand.
- China MEE Dual Carbon Enforcement:Stricter water reuse requirements under China's dual carbon goals are expanding clarifier installation across chemical and power generation facilities.
- India Jal Jeevan Mission:Rural water supply infrastructure rollout is driving clarifier procurement across state water boards and district-level treatment plants.
Market Restraints
- Alum and ferric chloride price volatility:Primary coagulant input costs fluctuate with bauxite and steel industry cycles, squeezing chemical clarifier margins.
- European REACH compliance burden:Polyacrylamide restrictions redirect R&D spending toward bio-based alternatives, extending product development timelines.
- Membrane bioreactor substitution:Compact MBR systems encroach on clarifier share in space-constrained urban retrofit applications.
Strategic Opportunities
- Saudi Arabia desalination pretreatment:Gigaproject scale and Red Sea coastal development create demand for high-rate clarifiers ahead of reverse osmosis trains.
- Cloud-based monitoring convergence:IoT sensor networks and predictive analytics are integrating with legacy clarifier infrastructure to enable remote optimization.
- Brazil ANVISA pharmaceutical water standards:Tightening purified water specifications for drug manufacturing expand high-purity clarifier demand.
Industry Challenges
- Coagulation chemistry expertise gap:Utilities struggle to recruit operators capable of optimizing dose-response curves across variable raw water quality.
- Legacy SCADA integration friction:Brownfield clarifier upgrades require protocol bridging with decades-old control architectures, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water Clarifiers Market |
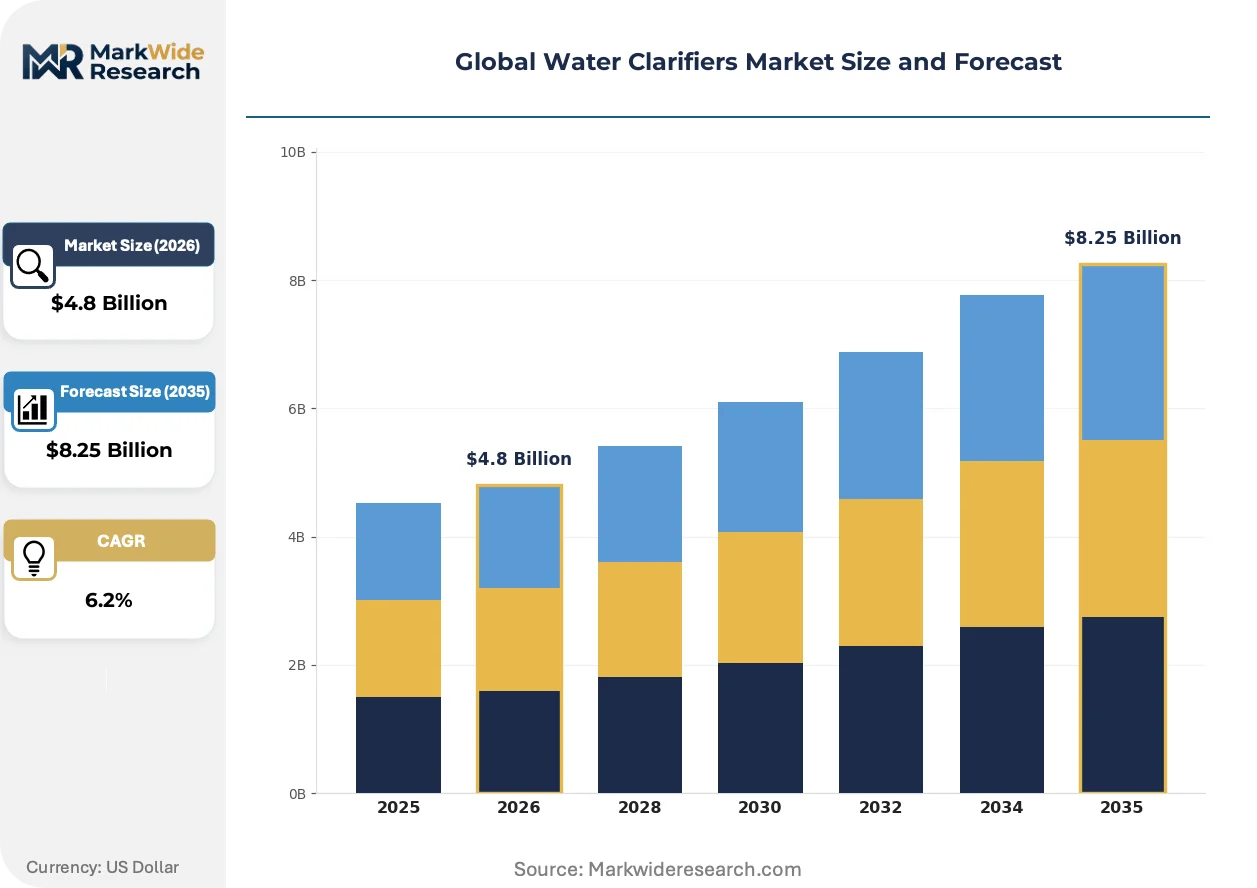
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flocculants, Coagulants, Sedimentation Aids, Filtration Enhancers, pH Adjusters Application: Municipal Water Treatment, Industrial Effluent Treatment, Wastewater Reuse, Drinking Water Purification, Irrigation Systems End User Industry: Public Utilities, Chemical Plants, Food & Beverage Facilities, Textile Manufacturing, Power Generation Deployment Type: On-Premises, Cloud-Based Monitoring, Mobile Units, Fixed Installations |
| Companies Covered | Evoqua Water Technologies LLC, SUEZ, Veolia Water Technologies, WesTech Engineering Inc., Ecolab Inc., Kurita Water Industries Ltd., BASF SE, Kemira OYJ, Solenis LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water Clarifiers Market Shifts & Advancements
Digitalization of clarifier operations and chemistry reformulation dominate vendor roadmaps as buyers demand predictive capability and regulatory-proof formulations.
Ballasted sedimentation technology is integrating high-density microsand with conventional flocculation to compress hydraulic retention time by an order of magnitude. Water-stressed utilities in Australia and the southwestern United States are adopting these systems for capacity expansion within existing footprints. The technology is integrating real-time turbidity feedback to automate coagulant dosing, reducing chemical overfeed and sludge production.
REACH authorization processes are restricting certain cationic polyacrylamide chemistries used in sludge dewatering applications across European municipal contracts. Formulators are redirecting development toward chitosan and starch-based alternatives that bypass SVHC classification. German and Dutch water authorities are piloting these bio-based flocculants in advance of anticipated 2027 sunset dates for conventional chemistries.
Regional water authority consolidation is compressing supplier counts as aggregated procurement favors vendors with multi-site service capabilities. North American utilities are unbundling clarifier maintenance from capital purchase contracts, creating standalone aftermarket revenue pools. This restructuring is most visible in California and Texas, where regionalization has reduced active vendor lists by half across major metropolitan service areas.
Global Water Clarifiers Market Segmentation
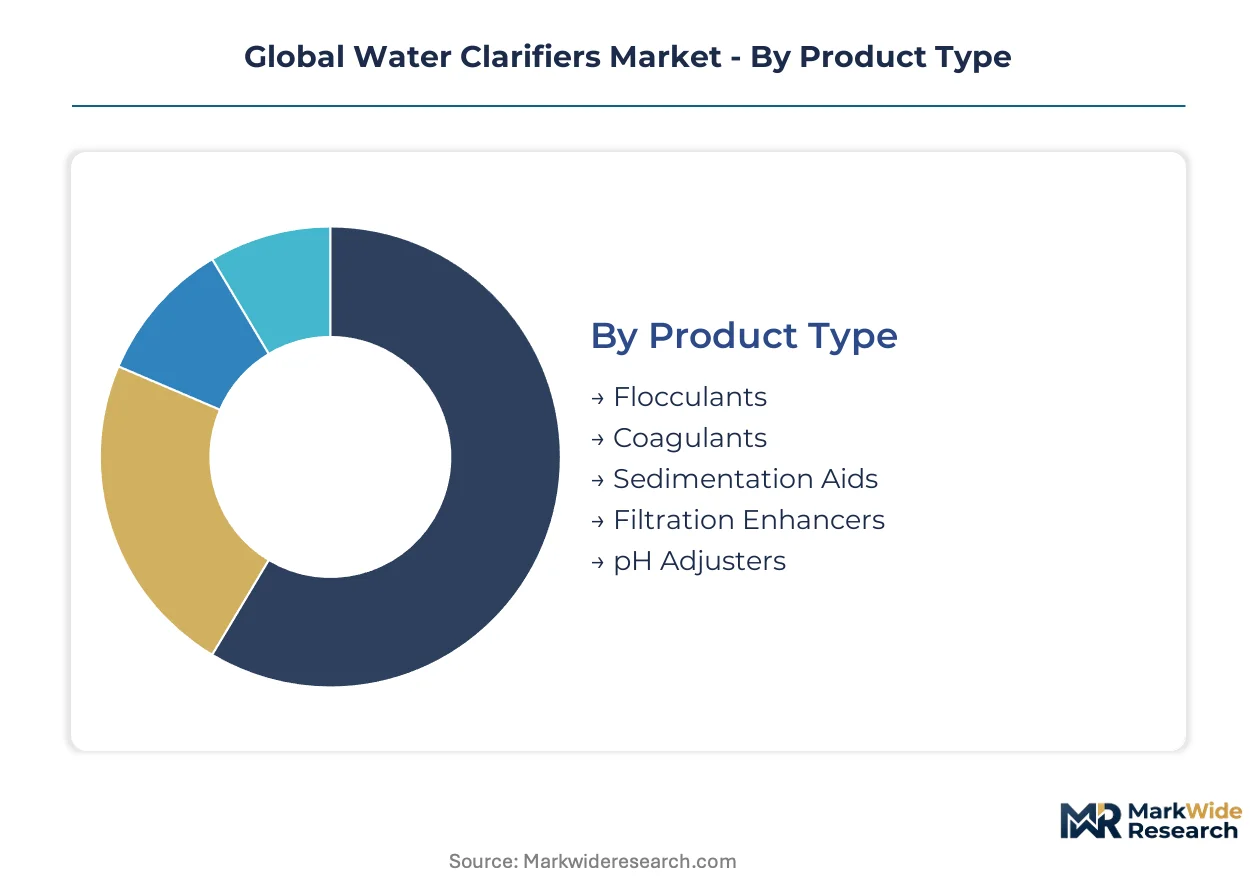
Water clarifier procurement decisions hinge on regulatory compliance tiers, operational scale, and chemistry compatibility with local effluent standards. Segmentation reveals where certification burdens concentrate and which product configurations command premium positioning across municipal and industrial buyer pools.
Product Type:
REACH authorization processes in Europe and EPA discharge mandates in the United States impose divergent formulation requirements across chemistry classes, fragmenting supplier certification portfolios.
- Coagulants:Alum and ferric chloride formulations precipitate suspended solids through charge neutralization, achieving rapid settling in conventional basins. Demand concentrates in U.S. municipal utilities facing EPA tertiary clarification mandates for phosphorus removal, though bauxite price volatility squeezes procurement budgets.
- Flocculants:Polyacrylamide-based polymers bridge destabilized particles into settleable flocs, enabling high-rate clarification in space-constrained installations. European water authorities are pivoting toward bio-based alternatives as ECHA restricts cationic chemistries ahead of scheduled sunset dates.
- Sedimentation Aids:High-density microsand and ballast media compress hydraulic retention times for capacity expansion within existing footprints.
- Filtration Enhancers:Pre-treatment chemistries optimize downstream membrane performance in desalination and reuse trains.
- pH Adjusters:Acid and alkali dosing stabilizes coagulation kinetics across variable raw water chemistries.
Leading the category by volume: Coagulants. Growing fastest: Flocculants.
Application:
Capital intensity and regulatory scrutiny vary sharply across use cases, with reuse mandates driving technology upgrade cycles faster than conventional treatment replacements.
- Municipal Water Treatment:Surface water and groundwater clarification for potable supply represents the largest installed base, with regional water authority consolidation in California and Texas compressing vendor lists while expanding contract scale.
- Wastewater Reuse:Closed-loop systems for industrial and agricultural non-potable applications are expanding most quickly as China's MEE dual carbon goals and Australia's drought protocols mandate water recovery rates above 70 percent in new developments.
- Industrial Effluent Treatment:Pre-discharge clarification for chemical, textile, and food processing facilities faces tightening COD and TSS limits.
- Drinking Water Purification:Final polishing stages for turbidity reduction below 1 NTU in sensitive supply zones.
- Irrigation Systems:Agricultural runoff treatment and tailwater recovery for salinity management in arid regions.
Dominant by installed base: Municipal Water Treatment. Steepest expansion trajectory: Wastewater Reuse.
End User Industry:
Buyer sophistication and service expectations diverge between consolidated public procurement and fragmented industrial maintenance budgets.
- Public Utilities:Regional water authorities aggregate clarifier procurement across treatment trains serving millions of connections, unbundling capital purchase from long-term service contracts to lock in chemical supply and predictive maintenance.
- Chemical Plants:Process water and effluent treatment requirements scale with capacity expansions on the U.S. Gulf Coast and China's coastal industrial corridors, where dual carbon enforcement tightens reuse obligations.
- Food & Beverage Facilities:High-organic-load wastewater requires specialized coagulation chemistry for BOD reduction ahead of discharge.
- Textile Manufacturing:Dye and finishing effluent demands color removal capabilities through advanced flocculation.
- Power Generation:Cooling tower blowdown and flue gas desulfurization wastewater clarification for zero-liquid-discharge compliance.
Highest contract value concentration: Public Utilities. Fastest procurement cycle acceleration: Chemical Plants.
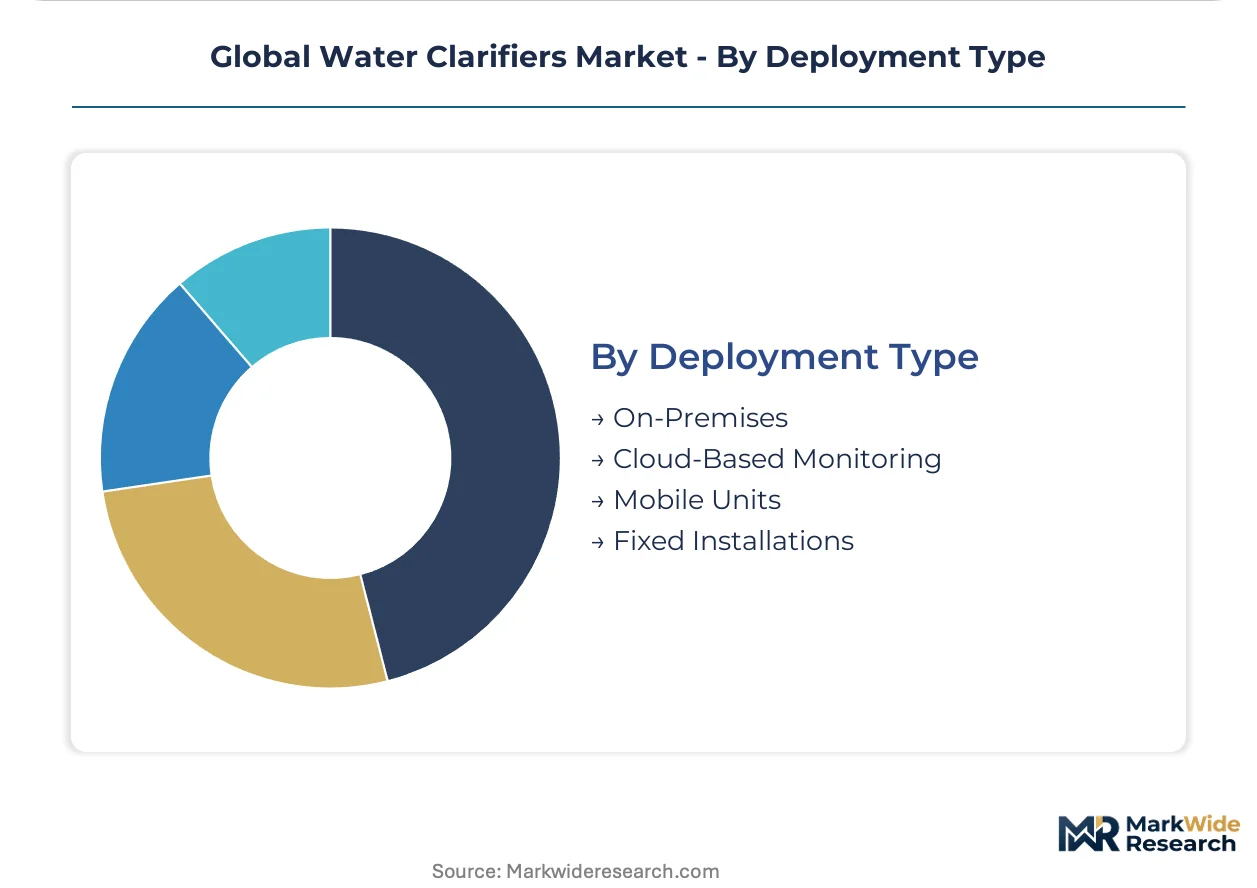
Deployment Type:
Physical infrastructure requirements and digital integration depth determine total cost of ownership across brownfield and greenfield installations.
- Fixed Installations:Conventional concrete basins with mechanical sludge collection dominate volume, though legacy SCADA integration friction extends commissioning timelines for upgrades.
- Cloud-Based Monitoring:IoT sensor networks and predictive analytics platforms are displacing traditional oversight in advanced utility networks, enabling remote coagulant dose optimization based on real-time turbidity feedback.
- On-Premises:Local control architectures persist in security-sensitive industrial facilities and smaller utilities with limited IT infrastructure.
- Mobile Units:Containerized clarifier systems for emergency response, construction dewatering, and temporary capacity augmentation.
Controlling deployment volume: Fixed Installations. Gaining share fastest: Cloud-Based Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest share of clarifier procurement volume as industrial corridor expansion and municipal upgrades strain existing treatment infrastructure. India's rural water supply programs and chemical sector growth are accelerating installation rates across state utilities. Saudi Arabia's gigaproject pipeline and desalination expansion are reshaping demand toward high-rate pretreatment systems.
United States
EPA effluent limitation guidelines are forcing tertiary clarification retrofits across phosphorus-impaired watersheds in the Great Lakes and Chesapeake Bay regions. The agency's tightening discharge standards for specific industrial categories are expanding replacement demand for aging municipal infrastructure. California's regional water authority consolidation is compressing vendor lists while expanding contract scale across Los Angeles and San Diego metropolitan service areas.
China
MEE enforcement of dual carbon goals is tightening water reuse requirements across chemical and power generation facilities in the Yangtze River Delta. The ministry's stricter discharge standards are compelling clarifier upgrades in coastal industrial corridors. Shandong Province's petrochemical clusters are installing high-rate clarification systems ahead of reverse osmosis trains for zero-liquid-discharge compliance.
India
Jal Jeevan Mission rollout is driving clarifier procurement across state water boards in Maharashtra, Gujarat, and Tamil Nadu. The national rural water supply program is accelerating district-level treatment plant construction. Gujarat's chemical manufacturing belt is expanding clarifier installation for effluent treatment as state pollution control boards enforce stricter COD limits.
Germany
ECHA REACH authorization processes are restricting cationic polyacrylamide chemistries used in sludge dewatering applications across municipal contracts. The regulatory body is redirecting formulation development toward chitosan and starch-based alternatives ahead of 2027 sunset dates. North Rhine-Westphalia's Ruhr Valley utilities are piloting bio-based flocculants in advance of anticipated chemistry restrictions.
Saudi Arabia
NEOM gigaproject scale and Red Sea coastal development are creating demand for high-rate clarifiers ahead of reverse osmosis trains in desalination pretreatment. The kingdom's national water strategy is mandating closed-loop systems for new industrial cities. Jubail Industrial City's expansion is integrating ballasted sedimentation technology to compress hydraulic retention times within existing treatment footprints.
Global Water Clarifiers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital monitoring integration and bio-based chemistry portfolios. The vendor base stratifies across three archetypes: integrated water service providers with multi-site maintenance capabilities, specialized chemical formulators with regulatory-certified product lines, and regional engineering fabricators with localized installation expertise. Competitive positioning hinges on M&A activity consolidating regional service networks and strategic partnerships bridging legacy SCADA systems with cloud-based analytics platforms.
Within the integrated service tier, Evoqua Water Technologies LLC and SUEZ exemplify vendors anchoring large-scale municipal contracts through bundled equipment and long-term maintenance agreements. Veolia Water Technologies occupies a position bridging European utility frameworks with Middle Eastern desalination pretreatment markets. Among chemical specialists, BASF SE and Kemira OYJ represent formulators navigating REACH compliance burdens while redirecting R&D toward bio-based alternatives. These archetypes illustrate how certification breadth and geographic service density determine competitive viability across divergent regulatory regimes.
| Leading Market Players |
|---|
| Evoqua Water Technologies LLC |
| SUEZ |
| Veolia Water Technologies |
| WesTech Engineering Inc. |
| Ecolab Inc. |
| Kurita Water Industries Ltd. |
| BASF SE |
| Kemira OYJ |
| Solenis LLC |
| Others |
Supply & Pricing Matrix
Process control engineers and coagulation chemistry specialists concentrate in Germany's Ruhr Valley and the Netherlands' Randstad corridor, creating labor-cost differentials that widen pricing-tier spreads between European REACH-compliant formulations and commodity chemical alternatives sourced from lower-cost manufacturing zones.
Pricing Analysis
Volume concentrates in standardized alum and ferric chloride coagulants where procurement runs through annual municipal tenders with thin margins, while margin pools concentrate in specialized flocculant formulations carrying ECHA REACH certification premiums. Price differentiation hinges on regulatory compliance tier and after-sales service bundling, with certified bio-based alternatives commanding substantial premiums over conventional polyacrylamide chemistries. Cost compression in the commodity coagulant tier is intensifying because bauxite and steel industry cycles feed raw material volatility. Public utilities exhibit highest price sensitivity due to consolidated regional procurement, while desalination operators in Saudi Arabia show lowest sensitivity given gigaproject scale and performance-critical specifications.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturers of specialized cationic polyacrylamide monomers, which feed European formulators facing impending REACH sunset dates. Geographic supply concentration centers on China for polymer intermediates, Germany for precision dosing equipment, and the United States for high-rate clarifier mechanical components. Raw material dependencies rest on bauxite-derived alumina, acrylonitrile for polymer synthesis, and high-grade stainless steel for sludge collection mechanisms. Tariff exposure on Chinese chemical imports threatens formulator margins in Europe and North America. Distribution runs through regional water authority procurement hubs in California and Texas, with chemical supply contracted separately from capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
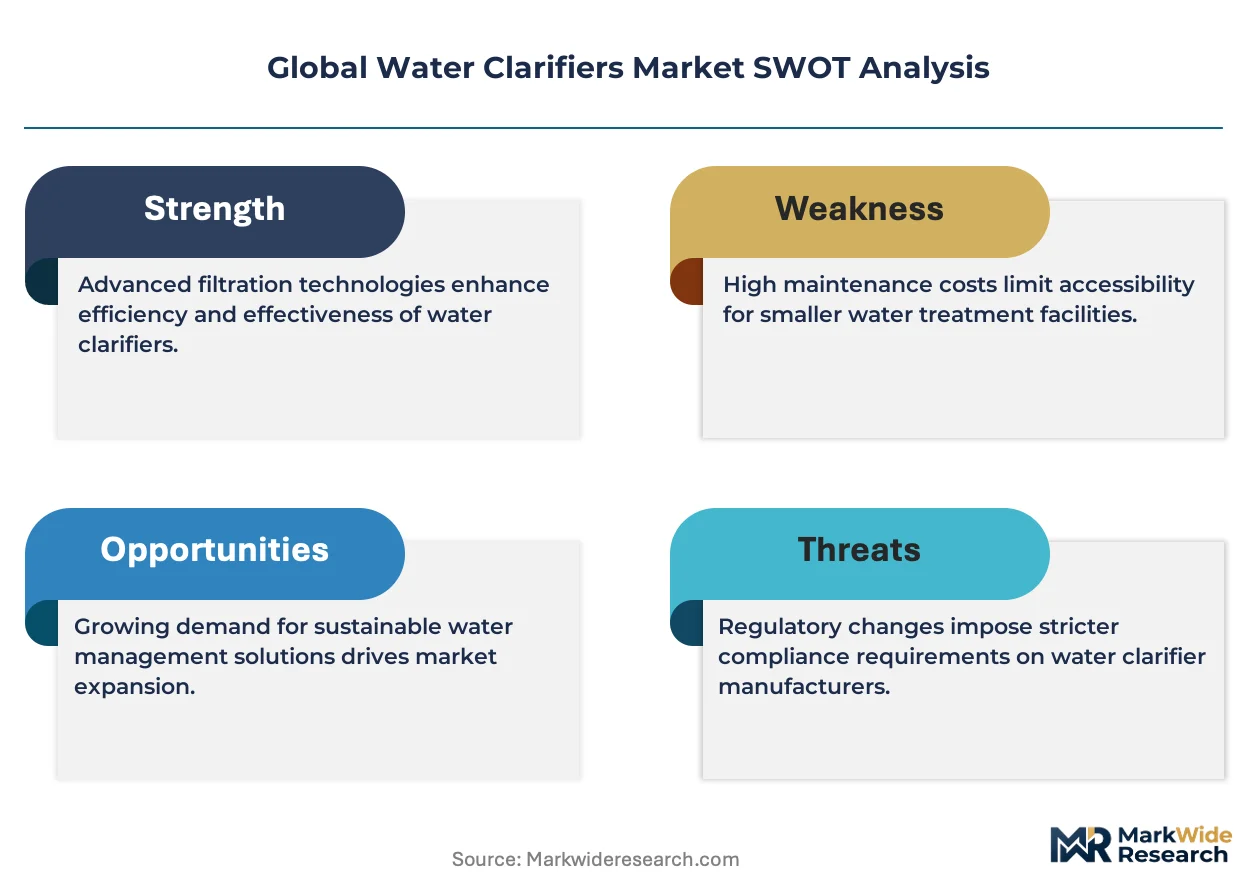
This market reads as a cost-of-compliance story where ECHA REACH authorization processes erect barrier-to-entry moats favoring formulators with certified bio-based portfolios and multi-jurisdictional regulatory expertise.
For Market Incumbents: Lock in regional water authority service contracts through predictive maintenance platforms that integrate cloud-based monitoring with legacy SCADA infrastructure. Deepen backward integration into bio-based polymer feedstocks to secure supply chains ahead of anticipated chemistry restrictions. Membrane bioreactor substitution in space-constrained urban retrofits threatens clarifier share; counter by embedding ballasted sedimentation technology into capacity expansion proposals.
For New Entrants and Emerging Players: Capture aftermarket revenue pools created by unbundled maintenance contracts in North American municipal utilities. White-space sits in cloud-based clarifier optimization platforms serving mid-sized chemical plants lacking in-house coagulation expertise. Target India's Jal Jeevan Mission district-level installations with containerized mobile units paired with operator training services.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized chemical formulators navigating REACH compliance burdens given regulatory divergence across jurisdictions. Long-term viability favors vendors with multi-site service capabilities and certified bio-based R&D pipelines. Watch for inflection in European municipal tender specifications mandating SVHC-free flocculants as the signal for accelerated portfolio rotation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures supply chains for chitosan and starch-based alternatives ahead of REACH sunset dates. |
| Cloud-Based Monitoring Platform Launch | Enables remote coagulant optimization for utilities struggling with operator recruitment gaps. |
| Regional Water Authority Service Contract | Locks in multi-site chemical supply and predictive maintenance across consolidated procurement hubs. |
| High-Rate Clarifier Technology Licensing | Accelerates penetration in Saudi desalination pretreatment and China's zero-liquid-discharge installations. |
| Mobile Unit Deployment for Emergency Response | Captures construction dewatering and temporary capacity augmentation demand in India's infrastructure rollout. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with municipal water utility procurement directors, chemical plant maintenance managers, and clarifier OEM technical sales engineers. Bottom-up and top-down triangulation combined EPA effluent limitation guideline enforcement timelines, ECHA REACH authorization status updates, and India Jal Jeevan Mission budget allocations with equipment shipment manifests and coagulant import volumes.
Segmentation-level modeling tracked chemistry class, application end-use, and deployment architecture across the projection horizon. CAGRs derived from regression analysis against named regulatory enforcement schedules and infrastructure investment programs. Industry-specific inputs included regional water authority consolidation patterns, dual carbon goal implementation intensity in China's Yangtze River Delta, and desalination gigaproject development timelines in Saudi Arabia.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization timeline shifts and alum price volatility. Deviation in EPA effluent guideline enforcement intensity or MEE dual carbon inspection rigor would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Process Water Treatment Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Produced Water Treatment Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Global Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
Membrane Filtration Systems Market