
 Limestone Mill Market | 2026-2036
Limestone Mill Market Size, Share, and Industry Trends Forecast 2026-2036
Limestone Mill Market Insights
Multi-source procurement among integrated cement groups is consolidating around qualified limestone mill suppliers with captive quarry access. Carmeuse leverages its North American quarry network to sustain long-term supply contracts with infrastructure-grade buyers. Lhoist Group anchors European demand through specialized quicklime production for steel desulfurization. Graymont Limited competes across the Pacific Rim with vertically integrated hydration and grinding assets.
A limestone mill processes calcium carbonate-bearing rock through crushing, grinding, and classification to produce powders meeting 45-micron to 90-micron fineness specifications for industrial use. Ground limestone dominates construction-grade filler applications where cost sensitivity favors bulk material over precipitated alternatives. Quicklime commands premium positioning in steel and chemical manufacturing due to its reactivity and energy-intensive calcination requirements. Hydrated lime occupies specialized niches in water treatment and soil stabilization where controlled slaking yields superior handling properties.
EPA air quality standards and OSHA silica exposure limits shape mill design requirements for dust collection and worker safety in United States operations. India's CEA mandates flue-gas desulfurization installations at thermal power plants, directly expanding hydrated lime procurement volumes. China's MEE enforces stricter SO2 emission ceilings that push steelmakers toward higher-purity quicklime consumption. Stakeholders must weigh quarry reserve depletion rates against regulatory compliance investments when evaluating long-term milling capacity additions.
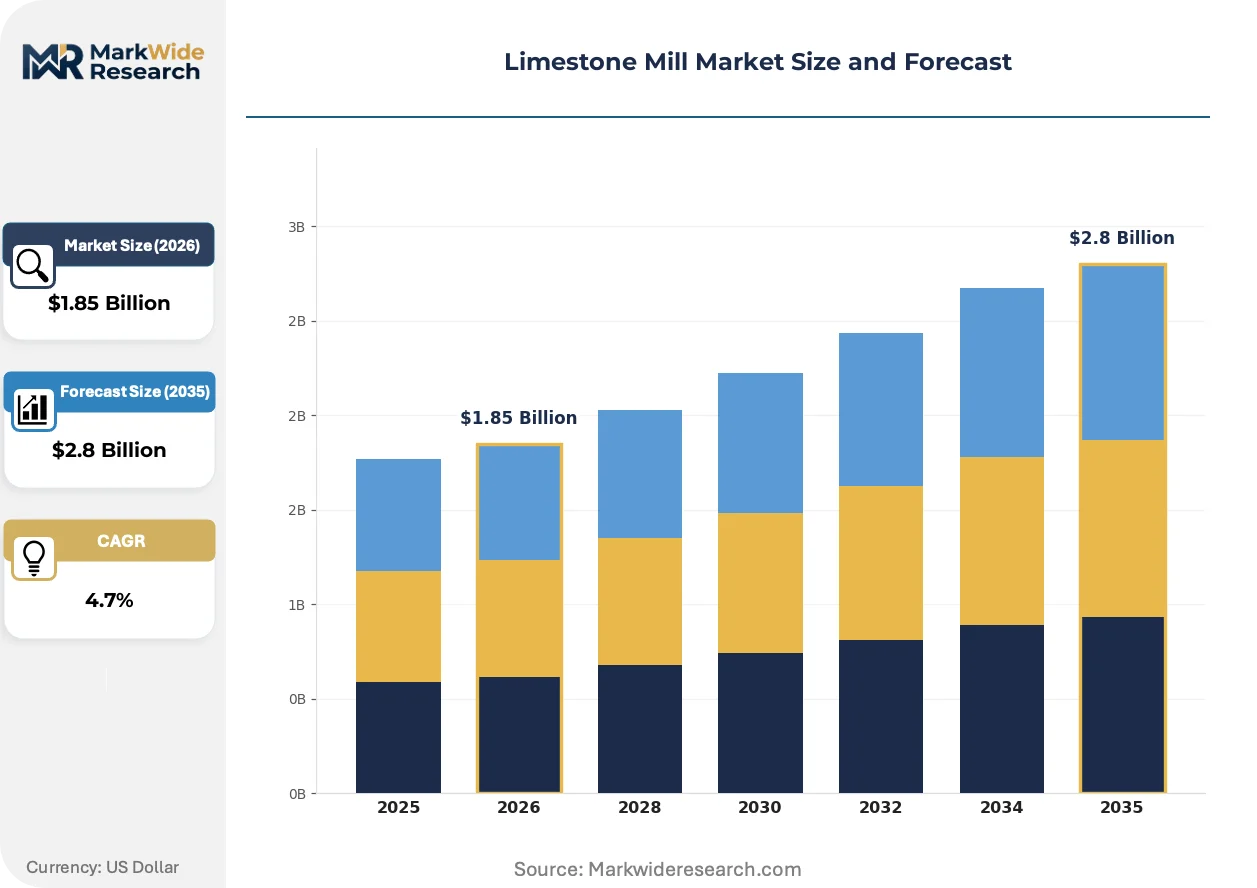
Market Dynamics
Flue-gas desulfurization mandates across Asia are compressing procurement timelines for high-reactivity quicklime, forcing cement and steel producers to pre-qualify mill suppliers with captive calcination capacity and proven emission-control integration.
Growth Catalysts
- China's MEE SO2 Ceilings:Steelmakers in Hebei and Shandong provinces are retrofitting sinter plants with advanced desulfurization systems that specify 90%+ calcium oxide purity, directly expanding premium quicklime offtake from integrated mills.
- India's CEA FGD Mandate:Thermal power utilities must install limestone-based scrubbers at plants exceeding 500MW capacity, creating sustained hydrated lime demand through 2030 with procurement tied to BIS-certified suppliers.
- Steel-Integrated Cement Complexes:Vietnam's northern industrial corridor is anchoring multi-product limestone consumption where single-site slag grinding and clinker production share milling infrastructure and quality control protocols.
Market Restraints
- Energy Cost Volatility:Natural gas and metallurgical coke price swings directly compress calcination margins, particularly for rotary kiln operators without long-term fuel hedging or access to waste-heat recovery systems.
- Quarry Reserve Depletion:High-calcium limestone deposits in mature mining districts face declining ore grades, forcing mills to extend haul distances or accept lower feedstock purity with downstream beneficiation costs.
- Precipitated Calcium Carbonate Substitution:Specialty paper and polymer compounders are switching to PCC for controlled particle morphology, eroding ground limestone share in premium filler applications above 5-micron fineness thresholds.
Strategic Opportunities
- Indonesia's Unpenetrated FGD Market:Coal-dependent power generation in Java and Sumatra lacks mandated scrubber installation, creating first-mover advantage for mills establishing hydrated lime supply ahead of anticipated CEA-style regulation.
- Carbon Capture Integration:Direct air capture and post-combustion mineralization projects are piloting spent lime as a regenerable sorbent, opening circular-economy revenue streams for calcination operators with carbon-negative positioning.
- Digital Procurement Platforms:Bulk commodity exchanges are enabling spot-market limestone purchasing for mid-sized concrete producers, bypassing traditional annual contract structures and expanding addressable customer bases.
Industry Challenges
- Process Control Expertise Gap:Automated kiln operation and predictive maintenance systems require instrumentation specialists scarce in traditional mining regions, forcing mills to compete for talent with broader industrial automation sectors.
- Multi-Jurisdictional Certification Lag:Cross-border supply contracts demand simultaneous compliance with EPA air standards, REACH chemical registration, and BIS quality marks, extending qualification timelines by 12-18 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Limestone Mill Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Limestone, Quicklime, Hydrated Lime, Calcium Carbonate End User: Cement Industry, Agriculture, Water Treatment, Chemical Manufacturing Application: Construction, Soil Stabilization, Desulfurization, Industrial Filler Distribution Channel: Direct Sales, Wholesale, Retail, E-commerce |
| Companies Covered | Carmeuse, Lhoist Group, Graymont Limited, Imerys, Minerals Technologies Inc., Omya AG, United States Lime & Minerals Inc., LafargeHolcim, National Lime & Stone Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Limestone Mill Market Trends and Innovations
Digital process control and emission-monitoring technologies are compressing the gap between raw quarry output and specification-grade lime products, enabling real-time quality adjustment that was previously batch-dependent.
Advanced grinding circuits with high-pressure roller presses and dynamic classifiers are converging with online particle-size analyzers to deliver consistent 45-micron fineness with 40% lower specific energy consumption. Cement producers in Vietnam and Thailand are retrofitting existing ball mill trains with this technology to meet stricter concrete admixture specifications. The convergence is compressing capital recovery periods from seven years to four years for mid-scale operations.
EPA's updated National Ambient Air Quality Standards for particulate matter are forcing US-based mills to deploy continuous emissions monitoring systems tied to automated kiln shutdown protocols. Non-attainment status designations in Pennsylvania and Ohio are accelerating scrubber retrofits at legacy calcination facilities. Integrated operators with pre-installed baghouse and wet scrubber infrastructure are capturing displaced volumes from non-compliant competitors.
Specification-driven procurement is displacing relationship-based supply agreements as infrastructure project owners mandate mill test reports with every bulk delivery. Engineering-procurement-construction firms in Saudi Arabia and UAE are unbundling lime supply from broader construction material packages, forcing mills to certify directly to Aramco and ADNOC technical standards. This behavioral shift is most visible in Gulf Cooperation Council megaprojects where traceability requirements exceed regional norms.
Limestone Mill Market Segmentation
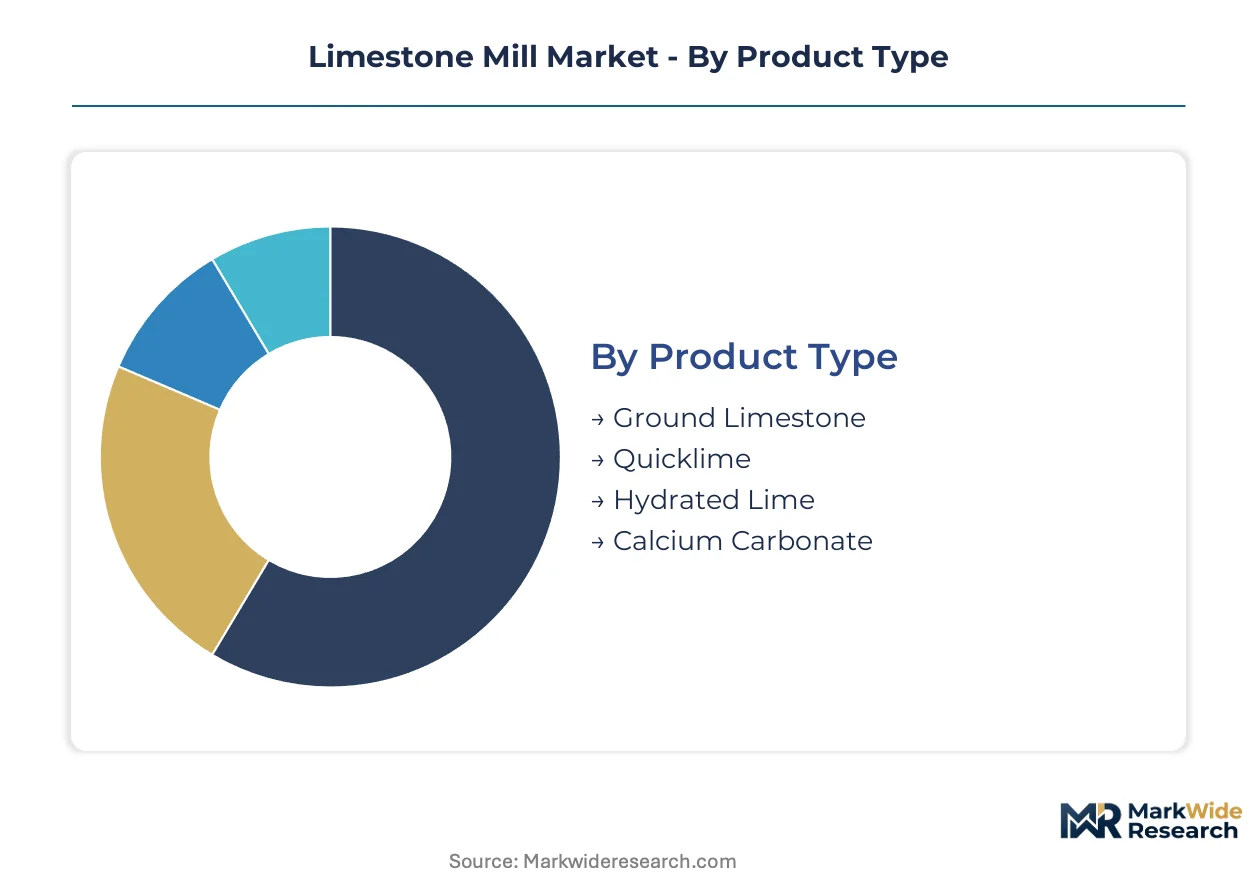
Segmentation in limestone milling reveals how specification requirements, procurement scale, and regulatory exposure fragment demand across distinct buyer profiles. Product purity thresholds, end-use reactivity demands, and channel cost structures each create separate competitive arenas with divergent margin and volume characteristics.
Product Type:
Cost tier separates commodity ground material from calcined premium grades with divergent energy intensity and pricing power.
- Ground Limestone:Mechanical grinding of calcium carbonate-bearing rock to 45-90 micron fineness serves construction filler and cement extender applications. Bulk procurement by Vietnamese and Thai cement producers favors this lowest-cost category where specification tolerances permit higher silica content. India's expanding clinker capacity drives regional volume concentration.
- Quicklime: High-temperature calcination yields 90%+ calcium oxide reactivity essential for steel desulfurization and chemical processing. Hebei and Shandong steelmakers under China's MEE SO2 mandates specify this premium grade, compressing supplier qualification timelines to captive calcination operators.
- Hydrated Lime: Controlled slaking of quicklime produces calcium hydroxide for water treatment and flue-gas scrubbing. India's CEA-mandated FGD installations at 500MW+ thermal plants anchor procurement volumes.
- Calcium Carbonate: Ultra-fine precipitated grades serve specialty paper and polymer compounding where controlled morphology commands price premiums over ground alternatives.
Ground limestone leads volumes today; quicklime is gaining share fastest.
End User:
Application maturity and regulatory exposure differentiate buyers from infrastructure-scale cement plants to fragmented agricultural spreaders.
- Cement Industry:Integrated clinker-grinding complexes consume limestone as both raw feed and finished cement additive. Southeast Asian capacity expansion, particularly Vietnam's northern industrial corridor, concentrates multi-product procurement at single sites sharing milling infrastructure and quality protocols.
- Agriculture: Soil pH correction and livestock feed supplementation drive seasonal, price-sensitive demand through distributor networks rather than direct mill relationships.
- Water Treatment: Municipal and industrial utilities specify hydrated lime for alkalinity control and phosphorus precipitation, with procurement tied to AWWA certification requirements.
- Chemical Manufacturing: Reactivity-sensitive processes in caustic soda and sugar refining specify consistent calcium oxide content, favoring long-term contracts with proven calcination operators.
Cement industry procurement dominates absolute tonnage; water treatment utilities are expanding most quickly on regulatory mandates.
Application:
Performance specification separates commodity construction fill from emission-control reactivity requirements with divergent quality premiums.
- Construction:Concrete admixture and asphalt filler applications accept variable purity ground limestone where cost minimization overrides specification stringency. Thai and Vietnamese producers retrofitting high-pressure grinding circuits target this volume segment.
- Soil Stabilization: Highway base modification and expansive clay treatment employ hydrated lime for immediate strength gain and long-term durability.
- Desulfurization: Flue-gas scrubbing at coal-fired power plants and steel sinter operations demands high-reactivity quicklime with rapid slaking rates. India's CEA mandates and China's MEE ceilings are compressing procurement toward pre-qualified suppliers.
- Industrial Filler: Plastics, rubber, and paint compounding specify controlled particle size distribution, with precipitated calcium carbonate eroding ground limestone share above 5-micron thresholds.
Construction absorbs the greatest raw tonnage; desulfurization is climbing the fastest on Asian regulatory enforcement.
Distribution Channel:
Customer scale and specification complexity determine whether buyers access mills directly or through intermediaries with inventory and blending services.
- Direct Sales:Annual and multi-year supply contracts link integrated cement and steel producers to captive quarry operations with guaranteed quality and logistics coordination.
- Wholesale: Regional distributors aggregate fragmented agricultural and mid-sized industrial demand, holding inventory for seasonal peaks and specification blending.
- Retail: Bagged hydrated lime for contractor and small agricultural users moves through construction supply and farm cooperative channels with significant markup over bulk equivalents.
- E-commerce: Digital procurement platforms are emerging for spot-market ground limestone purchasing by mid-sized concrete producers bypassing traditional contract structures.
Direct sales anchor revenue concentration today; e-commerce channels are expanding most quickly on platform infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's northern industrial corridor anchors limestone mill demand through steel-integrated cement complexes that share milling infrastructure and quality protocols across multi-product operations.
China
Hebei and Shandong steelmakers drive premium quicklime consumption under MEE SO2 emission ceilings that mandate 90%+ calcium oxide purity for sinter plant desulfurization. The MEE enforces stricter scrubber retrofits, compressing supplier qualification timelines toward captive calcination operators with proven emission-control integration.
India
Thermal power utilities exceeding 500MW capacity anchor hydrated lime procurement volumes under CEA-mandated flue-gas desulfurization installations through 2030. BIS certification requirements tie procurement to pre-qualified suppliers, concentrating demand around mills with documented quality systems and logistics coordination.
United States
Pennsylvania and Ohio calcination facilities face EPA non-attainment status designations for particulate matter, accelerating scrubber retrofits at legacy operations. Integrated operators with pre-installed baghouse infrastructure capture displaced volumes from non-compliant competitors in these industrial corridors.
Indonesia
Coal-dependent power generation in Java and Sumatra creates first-mover positioning for hydrated lime supply ahead of anticipated CEA-style regulation. The absence of mandated scrubber installation leaves procurement patterns fragmented, with spot-market ground limestone dominating current concrete producer purchasing.
Germany
Ruhr industrial basin steelmakers and chemical processors specify consistent calcium oxide content for reactivity-sensitive operations, favoring long-term contracts with proven calcination operators. REACH chemical registration requirements extend cross-border qualification timelines for new market entrants seeking supply contracts.
Limestone Mill Market Competitive Landscape
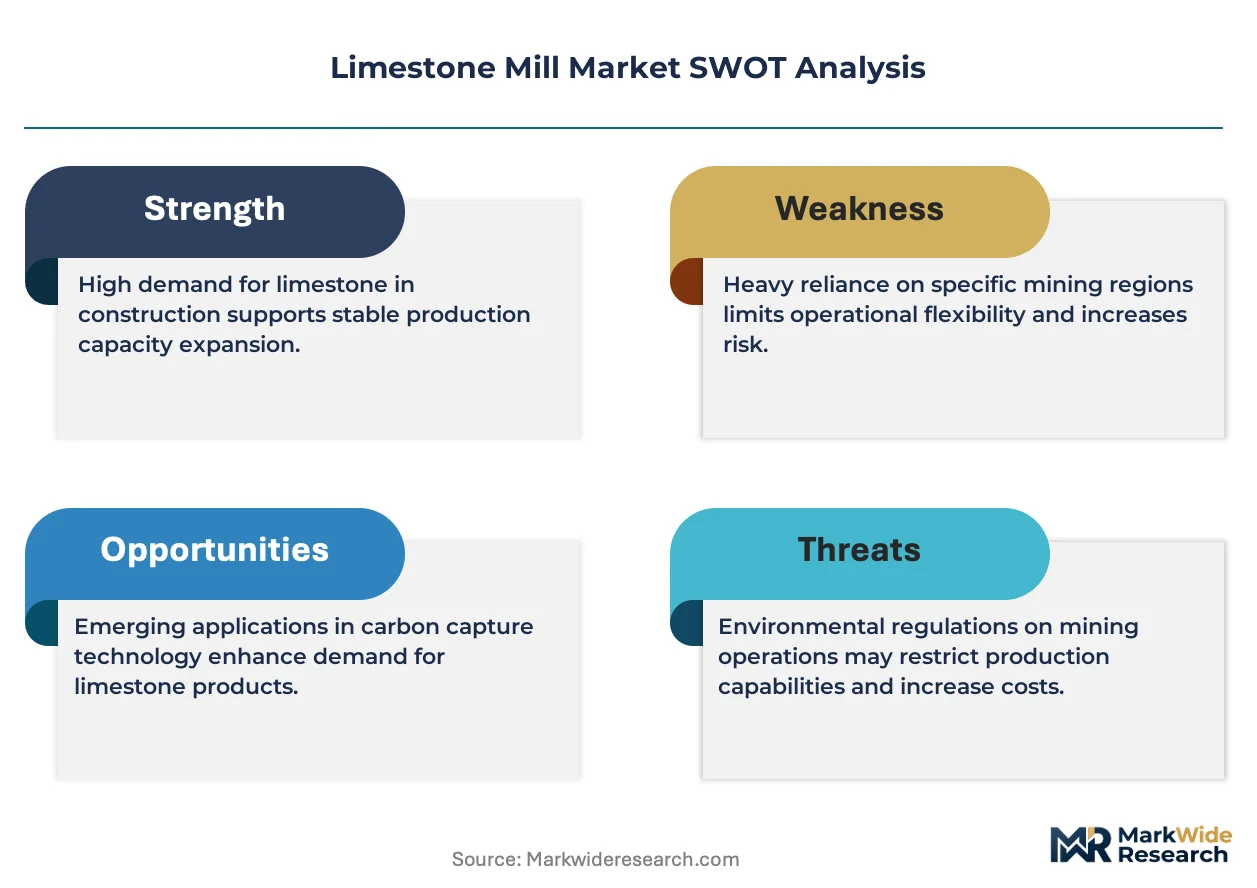
Global majors compete with regional champions across quarry access and calcination capacity. The market structures around three tiers: integrated quarry-to-mill operators with captive reserves, specialized quicklime producers serving steel desulfurization, and construction-grade grinding specialists. Strategic moves concentrate on backward integration into quarry assets and emission-control technology licensing to meet tightening regulatory thresholds.
Among North American integrated operators, Carmeuse and Graymont Limited exemplify the quarry-captive archetype, while Lhoist Group anchors European positioning through specialized calcination assets. These three represent distinct geographic anchoring strategies—North American network density, Pacific Rim vertical integration, and European premium-grade focus—without overlapping operational footprints.
| Leading Market Players |
|---|
| Carmeuse |
| Lhoist Group |
| Graymont Limited |
| Imerys |
| Minerals Technologies Inc. |
| Omya AG |
| United States Lime & Minerals Inc. |
| LafargeHolcim |
| National Lime & Stone Company |
| Others |
Pricing and Supply Chain Analysis
Metallurgical coke price benchmarks cascade through limestone mill economics, compressing calcination margins for rotary kiln operators while rewarding integrated quarry-to-mill networks with captive fuel hedging and waste-heat recovery infrastructure. This cost pass-through dynamic stratifies pricing power across three tiers: premium quicklime commands quality premiums under China's MEE purity mandates, mid-grade hydrated lime tracks utility procurement cycles under India's CEA directives, and ground limestone competes on bulk logistics efficiency for Vietnamese cement extender applications.
Pricing Analysis
Input-cost pass-through dominates limestone mill pricing, with natural gas and metallurgical coke volatility compressing margins for non-integrated calcination operators. Three-tier pricing structure across premium, standard, and economy levels separates quicklime for steel desulfurization from hydrated lime for water treatment and ground limestone for construction filler. Pricing pressure stems from energy cost volatility and declining ore grades in mature quarry districts. Cement producers exhibit highest price sensitivity due to bulk volume procurement, while steelmakers under emission mandates absorb premium pricing for certified purity grades.
Supply Chain Analysis
Domestic-content mandates in India's CEA-mandated FGD procurement and China's MEE enforcement are reshaping sourcing toward pre-qualified local suppliers with BIS certification and documented quality systems. Geographic supply concentrates in Vietnam, China, and India, with Vietnam's northern industrial corridor anchoring steel-integrated cement complex demand. Raw material dependencies center on high-calcium limestone feedstock, metallurgical coke for calcination, and specialized grinding media. Single-source vulnerability runs through captive quarry reserve depletion in mature mining districts. Distribution runs through direct annual contracts for integrated cement and steel producers, with wholesale channels serving fragmented agricultural and mid-sized industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limestone milling has shifted to a late-cycle quality story as Asian emission mandates compress procurement toward pre-qualified suppliers with certified purity and integrated emission-control infrastructure. This demand pivot favors operators with documented quality systems over commodity grinding specialists.
For Market Incumbents: Anchor defensive positioning through backward integration into captive quarry assets with proven reserve life and calcination capacity expansion in Vietnam's northern industrial corridor. Invest in continuous emissions monitoring systems to capture displaced volumes from non-compliant competitors facing EPA non-attainment designations. Cement industry price sensitivity and precipitated calcium carbonate substitution in specialty fillers represent converging margin threats requiring quality certification differentiation.
For New Entrants and Emerging Players: Mid-sized concrete producers in Indonesia's unpenetrated FGD market represent the most penetrable buyer archetype, with spot-market purchasing patterns bypassing traditional annual contract structures. Target hydrated lime supply ahead of anticipated CEA-style regulation in Java and Sumatra coal-dependent power generation. Establish digital procurement platform relationships to access fragmented demand without legacy distributor markups.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated quarry-to-mill operators with captive calcination capacity and established emission-control infrastructure. Five-to-ten year viability hinges on reserve-to-production ratios and regulatory compliance positioning rather than commodity volume exposure. Monitor India's CEA enforcement pace and Indonesia's regulatory trajectory as inflection indicators for hydrated lime demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Captive limestone reserves secure feedstock quality and hedge against ore grade decline in mature districts. |
| Calcination Capacity Expansion | Additional rotary kiln infrastructure captures premium quicklime demand from Hebei and Shandong steelmakers under MEE ceilings. |
| Emission-Control Technology Licensing | Baghouse and wet scrubber expertise transfers to competitors facing EPA non-attainment retrofits in Pennsylvania and Ohio. |
| Digital Procurement Platform Partnership | Platform integration accesses spot-market ground limestone demand from mid-sized Indonesian concrete producers. |
| Carbon Capture Sorbent Pilot Programs | Spent lime regeneration trials position calcination operators for circular-economy revenue in direct air capture mineralization. |
Research Methodology
Multiple input streams — primary interviews with quarry operations managers, cement procurement directors, and steel desulfurization specialists; secondary validation through customs trade data, CEA and MEE regulatory filings, and SEC disclosures from integrated operators — were reconciled through bottom-up and top-down triangulation. Plant-level capacity assessments, reserve life documentation, and emission-control infrastructure audits grounded volume estimates. Secondary sources included Vietnam Ministry of Industry and Trade production statistics, India Central Electricity Authority FGD installation trackers, and EPA air quality non-attainment designations.
Data-stream reconciliation across product type, end user, application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by purity-grade pricing differentials. Forecast inputs incorporated regulatory enforcement timelines for MEE SO2 ceilings and CEA scrubber mandates, steel-integrated cement complex capacity expansion in Vietnam's northern industrial corridor, and precipitated calcium carbonate substitution rates in specialty paper and polymer compounding.
Underlying measurement precision varies by segment; quicklime and hydrated lime carry tighter precision due to regulatory certification requirements and documented procurement contracts, while ground limestone estimates reflect greater spot-market variability. Forecasts reflect assumptions around enforcement continuity for Asian emission mandates and reserve depletion curves in mature quarry districts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Talc Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Dolomite Mining Market
Industrial Minerals
China Feed Minerals Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Barite Mining Market
Industrial Minerals
Asia Pacific Bentonite Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Slate Market
Industrial Minerals
North America Limestone Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Limestone Market