
 Slate Market | 2026-2036
Slate Market Size, Share, and Industry Trends Forecast 2026-2036
Slate Market Outlook
Digital quarry mapping and precision cutting automation is reconfiguring extraction economics across the slate industry. Cupa Pizarras leverages proprietary vein-mapping software to optimize block recovery rates in Spanish deposits. Welsh Slate anchors heritage-specification supply through its monopoly on Penrhyn and Ffestiniog quarry output. Vermont Slate Company specializes in domestic purple and green varietals for high-end architectural clients.
Slate is a fine-grained, metamorphic rock composed primarily of quartz, muscovite, and illite, formed under low-grade regional metamorphism of shale or mudstone; it splits along natural cleavage planes into thin, durable sheets valued for waterproofing, thermal stability, and aesthetic longevity. Natural slate dominates volume flows but commands compressed margins amid labor-intensive extraction, while artificial slate captures specification-driven commercial roofing with lighter weight and standardized installation. Composite slate represents the fastest-growing structural pocket as developers seek Class A fire ratings with reduced structural load.
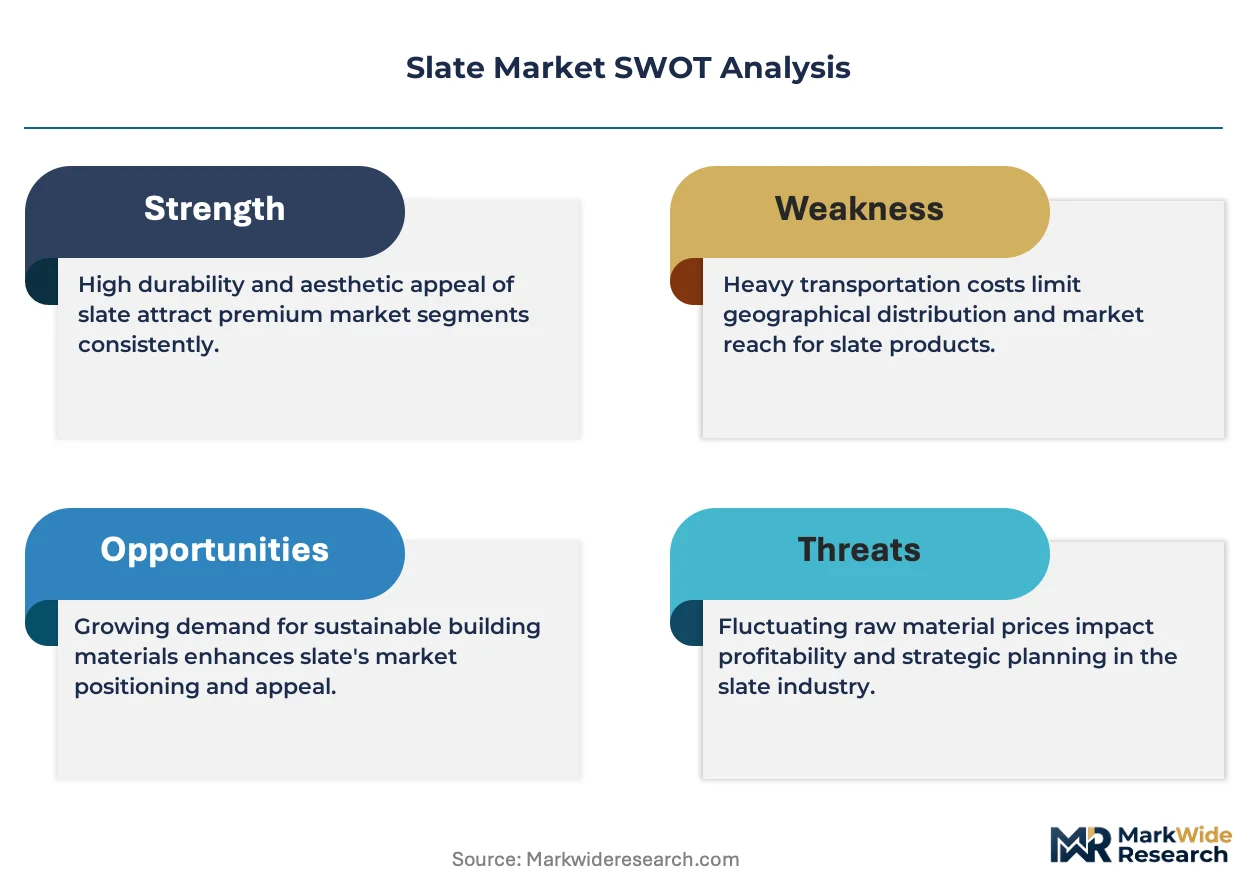
EPA stormwater regulations in the United States restrict runoff from quarry operations, elevating compliance costs for domestic producers. REACH and CE marking requirements in Europe govern silica exposure limits and structural performance certification for roofing applications. Stakeholders must monitor evolving embodied-carbon accounting rules that threaten to disadvantage natural stone against synthetic alternatives in public procurement frameworks.
Market Dynamics
REACH compliance in the European Union is tightening chemical disclosure requirements for imported stone products, forcing extraction operations to reconfigure supply documentation and testing protocols. This regulatory pressure compounds with labor-intensive quarry economics to reshape competitive positioning across natural and synthetic slate segments.
Growth Catalysts
- Heritage roofing mandates:Western European conservation frameworks now require authentic materials for listed building restoration, locking in procurement preferences for Galician and Welsh slate deposits.
- Composite slate innovation:Class A fire-rated synthetic formulations are capturing commercial roofing specifications previously closed to natural stone due to structural load constraints.
- EPA stormwater enforcement:Stricter runoff controls at US quarry sites are accelerating capital deployment toward closed-loop water systems, filtering marginal producers from the supply base.
Market Restraints
- Silica exposure limits:European ECHA guidelines on respirable crystalline silica are elevating occupational health compliance costs for dimension stone operations.
- Depository concentration:Premium architectural-grade slate extraction clusters in Spain's Galicia region, creating geographic supply vulnerability to localized labor disputes or transport disruptions.
- Artificial slate substitution:Polymer-composite and fiber-cement alternatives are displacing natural stone in volume-driven new construction segments through standardized installation and reduced structural engineering.
Strategic Opportunities
- Embodied-carbon accounting rules:EU Green Deal procurement frameworks threaten to disadvantage natural stone against synthetic alternatives, creating urgency for slate producers to develop verified lifecycle assessments and sequestration claims.
- Precision cutting automation:Integration of vein-mapping software with CNC splitting equipment is opening recovery-rate improvements in previously marginal deposits.
- Architectural specification channels:Direct engagement with sustainability-focused design firms is bypassing traditional distributor networks for high-margin custom projects.
Industry Challenges
- Master craftsman scarcity:Traditional hand-splitting expertise is concentrating among aging workforces in Wales and Galicia, constraining output elasticity for heritage-grade material.
- CE marking timeline compression:Roofing slate certification against harmonized European standards requires extended freeze-thaw and transverse strength testing, delaying new quarry commercialization by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slate Market |
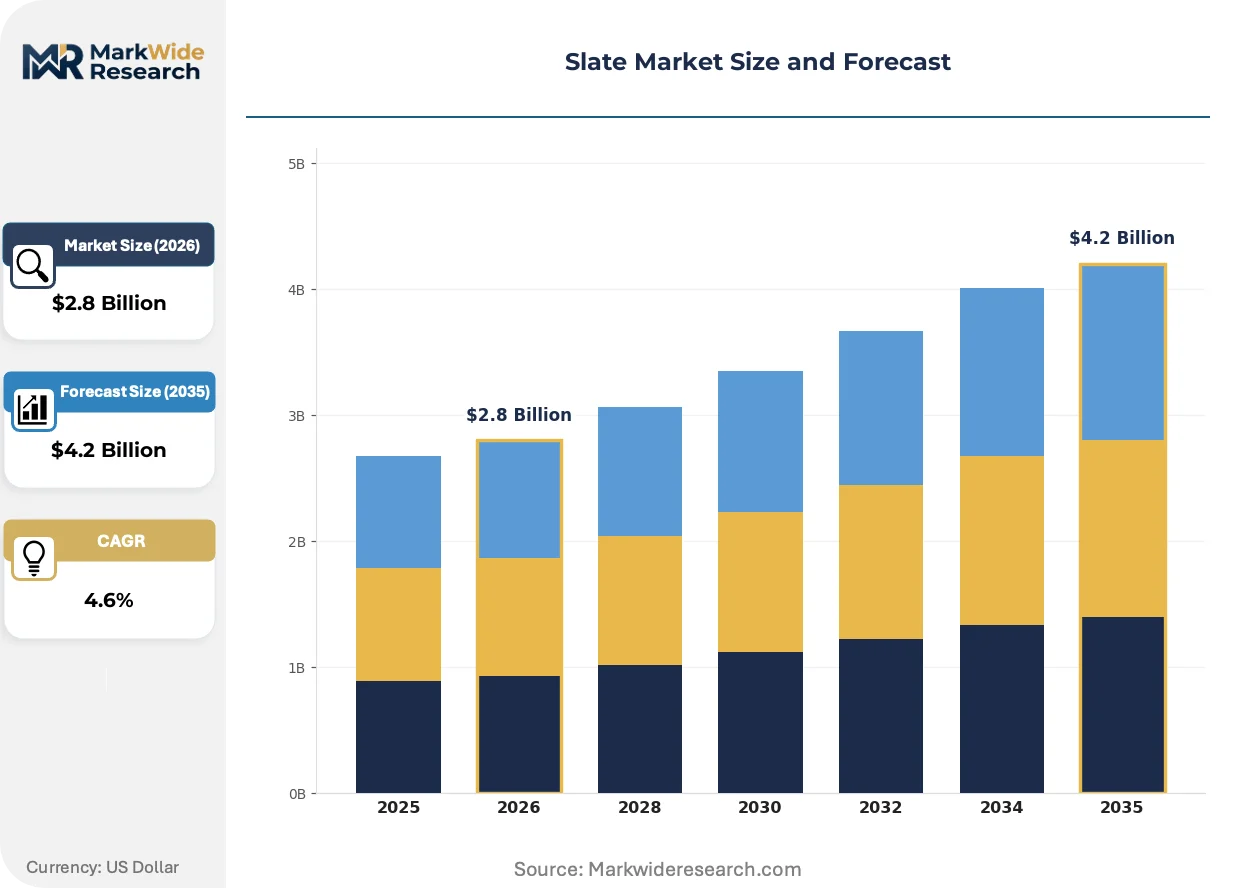
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Slate, Artificial Slate, Recycled Slate, Composite Slate Application: Construction, Interior Design, Roofing, Landscaping End User: Contractors, Architects, Homeowners, Developers Distribution Channel: Direct Sales, Online Retail, Wholesalers, Specialty Stores |
| Companies Covered | Burlington Stone, Greenstone Slate Company, Cupa Pizarras, China National Building Material Group, Welsh Slate, Vermont Slate Company, The Siam Cement Public Company Limited, Delabole Slate Company, Etex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slate Market Strategic Shifts
Digital quarry mapping and precision cutting automation is reconfiguring extraction economics across the slate industry. Three interconnected developments are compressing traditional competitive advantages while opening new specification territory.
Composite slate formulations incorporating recycled rubber and mineral fillers is hybridizing performance characteristics previously split between natural and artificial categories. Commercial roofing contractors in the US Southeast are specifying these materials for Class A fire-rated assemblies without structural reinforcement. The technology is hybridizing procurement decisions by delivering natural slate aesthetics with synthetic installation economics.
REACH registration requirements for imported stone products are extending chemical disclosure obligations to quarry runoff and processing effluent. European importers now face documentary burdens previously limited to manufactured construction materials. Spanish exporters to Germany and France are consolidating testing partnerships with accredited laboratories to maintain clearance velocity at Rotterdam and Hamburg ports.
Heritage conservation officers are tightening material authenticity requirements for grant-funded restoration projects. Specification authority is migrating from general contractors to conservation architects with direct quarry relationships. This concentration is most visible in UK church and municipal building programs, where Cupa Pizarras and Welsh Slate maintain specification archives dating to nineteenth-century installations.
Slate Market Segmentation
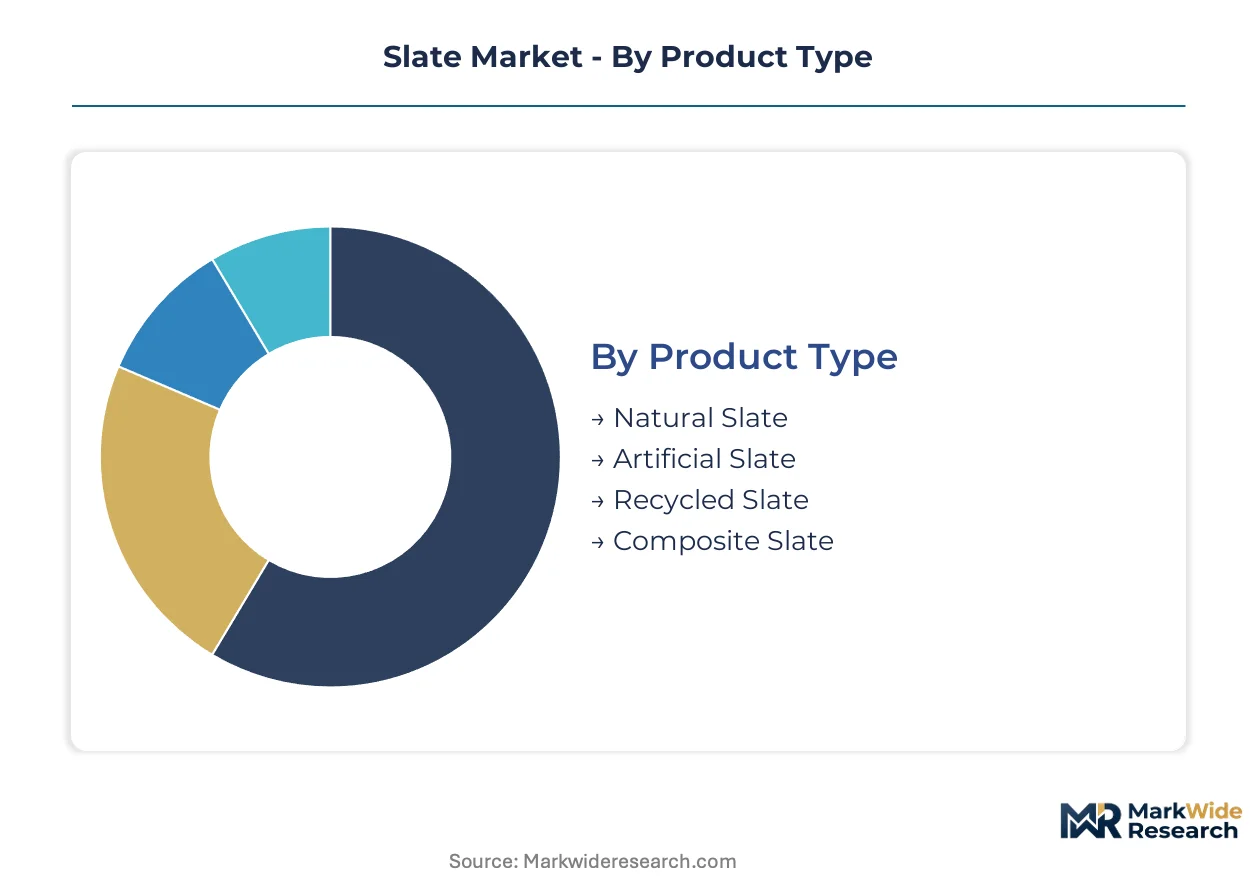
Slate procurement decisions split across material authenticity, installation economics, and specification authority. Understanding these segment boundaries clarifies where natural stone retains pricing power versus where synthetics capture volume.
Product Type:
Product selection spans heritage-mandated authenticity to performance-optimized substitutes, with cost tier and structural load driving divergence.
- Natural Slate:Metamorphic rock formed under low-grade regional metamorphism, splitting along natural cleavage planes into thin, durable sheets. Heritage roofing mandates across Western Europe lock in procurement for listed building restoration, though labor-intensive extraction constrains output elasticity.
- Composite Slate:Polymer-mineral hybrid formulations delivering Class A fire ratings with reduced structural load. Commercial roofing contractors in the US Southeast specify these materials for assemblies previously requiring reinforcement, expanding most quickly as developers seek installation standardization.
- Artificial Slate:Fiber-cement and polymer-based alternatives displacing natural stone in volume-driven new construction through standardized dimensions and reduced engineering requirements.
- Recycled Slate:Reclaimed material from demolition streams, concentrated in UK conservation projects where authenticity requirements override cost considerations.
Established volume favors natural slate; emerging adoption favors composite formulations.
Application:
Application scope ranges from weather-exposed structural envelopes to decorative interior surfaces, with specification authority migrating by use case.
- Roofing:Waterproofing assemblies demanding thermal stability and century-scale durability. Heritage conservation officers in the UK and France now require material authenticity documentation for grant-funded restoration, locking in procurement from Galician and Welsh quarries.
- Construction:Structural cladding and facade applications where load-bearing capacity and freeze-thaw resistance govern selection. CE marking requirements extend testing timelines for new quarry commercialization.
- Interior Design:Decorative flooring, wall cladding, and architectural features prioritizing aesthetic variation over structural performance.
- Landscaping:Paving, stepping stones, and garden features where cost sensitivity permits artificial slate substitution.
Specification authority concentrates in roofing; margin expansion concentrates in interior design.
End User:
Customer types fragment by technical sophistication, procurement scale, and regulatory exposure.
- Architects:Design professionals with direct quarry relationships bypassing traditional distributors for sustainability-focused projects. Conservation architects in the UK maintain specification archives dating to nineteenth-century installations.
- Developers:Volume-driven procurement seeking standardized installation and reduced structural engineering, favoring composite and artificial alternatives.
- Contractors:Installation specialists balancing material cost against labor efficiency and warranty exposure.
- Homeowners:Retail purchasers concentrated in renovation segments, price-sensitive and specification-light.
Direct relationships favor architects; volume scale favors developers.
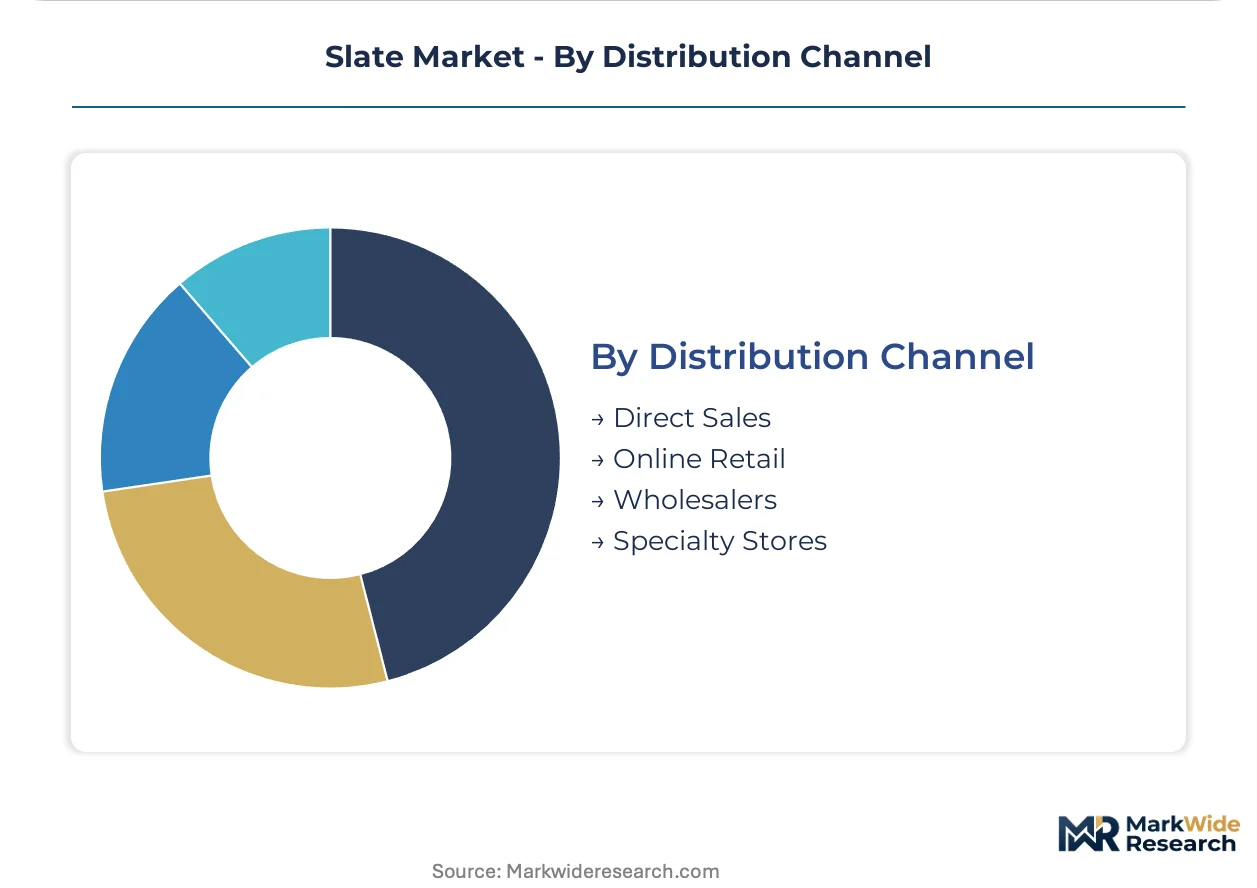
Distribution Channel:
Channel structure reflects customer technical requirements and order fragmentation.
- Direct Sales:Quarry-to-project relationships for heritage-grade material with authenticity documentation requirements. Cupa Pizarras and Welsh Slate maintain specification archives for conservation architects.
- Wholesalers:Regional distributors handling volume flows to contractors and developers, consolidating logistics for standardized dimensions.
- Specialty Stores:Retail outlets serving renovation homeowners with display samples and installation guidance.
- Online Retail:Digital channels capturing small-order replacement and DIY segments with limited technical support.
Documentation requirements favor direct sales; replacement volume favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heritage conservation architects and commercial roofing contractors represent the dominant buyer archetypes, with procurement patterns diverging sharply between authenticity-mandated restoration and performance-optimized new construction.
Spain
Galicia's slate quarries supply the bulk of European heritage-grade material, with Cupa Pizarras and regional operators extracting from deposits near Ourense. REACH compliance through ECHA mandates chemical disclosure for processed stone exports to Germany and France. The Valdeorras sub-region anchors extraction expertise, where vein-mapping software now guides precision cutting investments.
United Kingdom
Welsh Slate maintains monopoly supply from Penrhyn and Ffestiniog quarries for UK conservation projects requiring documented provenance. Heritage Lottery Fund grants now mandate material authenticity verification, locking in procurement from certified deposits. North Wales clusters extraction and hand-splitting craftsmanship, though master craftsman scarcity constrains output elasticity for cathedral and municipal restorations.
United States
Vermont Slate Company and Greenstone Slate Company serve high-end architectural clients seeking domestic purple and green varietals. EPA stormwater enforcement under the Clean Water Act elevates compliance costs for quarry runoff management, filtering marginal producers from Appalachian and New England deposits. The Slate Valley region spanning New York and Vermont retains concentrated extraction infrastructure.
China
China National Building Material Group anchors synthetic and natural slate production for domestic construction and export markets. GB standards for roofing materials govern fire resistance and freeze-thaw performance certification. Shandong and Hebei provinces cluster manufacturing capacity, with automated pressing lines displacing labor-intensive extraction for volume-driven commercial specifications.
Belgium
Etex Group's fiber-cement and synthetic slate operations serve European contractors seeking standardized installation economics. CE marking requirements under EU harmonized standards extend testing timelines for roofing slate commercialization. The Flanders region concentrates manufacturing and distribution infrastructure for composite formulations targeting Class A fire-rated assemblies.
Slate Market Competitive Environment
Channel-controlling players compete with product-specialist players across a structure that concentrates heritage-grade supply while fragmenting synthetic alternatives. Natural slate extraction clusters around Galician and Welsh deposits where quarry ownership and craftsmanship scarcity create defensive moats. Three archetypes dominate: vertically integrated quarry operators with specification archives, composite material manufacturers with standardized distribution, and regional fabricators serving contractor networks. Competitive moves center on backward integration into quarry assets and direct architect engagement bypassing traditional wholesale channels.
Among heritage-grade specialists, Cupa Pizarras and Welsh Slate exemplify the specification-archive archetype, anchoring conservation architect relationships through documented deposit provenance. Vermont Slate Company occupies a position within the domestic premium-tier segment for North American architectural clients. These named entities represent how geographic deposit control and certification infrastructure create positioning durability against synthetic substitution pressures.
| Leading Market Players |
|---|
| Burlington Stone |
| Greenstone Slate Company |
| Cupa Pizarras |
| China National Building Material Group |
| Welsh Slate |
| Vermont Slate Company |
| The Siam Cement Public Company Limited |
| Delabole Slate Company |
| Etex Group |
| Others |
Value Chain & Pricing Dynamics
Galicia's slate quarries anchor heritage-grade supply, concentrating margin capture with Cupa Pizarras and Welsh Slate while downstream distributors compete on logistics efficiency. Cost-plus contracts with fuel-indexed adjustments dominate procurement for natural stone, whereas composite formulations trade on fixed-price annual agreements.
Pricing Analysis
Cost-plus contracts with diesel-indexed haulage adjustments dominate natural slate procurement, linking delivered prices to Iberian fuel benchmarks. Price differentiation rests on CE marking tier and hand-splitting certification, with Penrhyn-grade Welsh material commanding premiums over machine-processed Galician output. Pricing pressure intensifies in commercial roofing as fiber-cement alternatives displace specification share. Developers exhibit acute price sensitivity; conservation architects show inelastic demand for documented provenance.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities support quarry-to-project direct sales for heritage-grade material. Extraction concentrates in Spain, the United Kingdom, and the United States, with each jurisdiction feeding distinct specification tiers. Raw material dependencies span diesel fuel for haulage, diamond-wire cutting consumables, and timber crating for transoceanic shipment. Single-source vulnerability runs through Galicia's Valdeorras sub-region, where labor disputes would cascade through European restoration pipelines. Distribution runs through certified wholesaler networks for standardized dimensions and direct quarry relationships for authenticity-documented projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against polymer-composite formulations capturing commercial roofing share through Class A fire ratings and reduced structural load. Natural stone producers must anchor heritage-mandated demand while composite manufacturers scale installation-standardized output.
For Market Incumbents: Pre-empt synthetic substitution by deepening specification-archive relationships with conservation architects in the United Kingdom and France. Invest in vein-mapping automation to improve block recovery rates at marginal Galician deposits. Secure backward integration into transport fleets to control diesel-indexed cost volatility.
For New Entrants and Emerging Players: Establish a beachhead in recycled slate aggregation for UK conservation projects where authenticity requirements override cost considerations. Target interior design specifications where aesthetic variation commands premium positioning without heritage-grade certification burdens. Pursue direct-to-architect channels bypassing consolidated wholesale networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed composite roofing manufacturers seeking geographic expansion into European Class A fire-rated assemblies. Five-to-ten year viability hinges on EU Green Deal embodied-carbon accounting rules disadvantaging natural stone. Monitor ECHA silica exposure guideline enforcement as a signal for occupational health cost inflection across dimension stone operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Vein-Mapping Software Deployment | Cupa Pizarras leverages proprietary algorithms to optimize block recovery at Ourense deposits. |
| CE Marking Certification Investment | Etex Group accelerates freeze-thaw testing timelines for composite slate commercialization. |
| Direct Architect Channel Development | Welsh Slate maintains specification archives dating to nineteenth-century installations for conservation officers. |
| Closed-Loop Water System Capital Deployment | Vermont Slate Company filters marginal Appalachian producers through EPA stormwater compliance. |
| Recycled Slate Aggregation Partnership | Delabole Slate Company secures demolition stream access for UK heritage restoration authenticity mandates. |
Study Parameters
The analysis maps natural slate extraction, composite formulation, and recycled material aggregation, each validated through quarry operations managers, conservation architect specification leads, roofing contractor procurement officers, and ECHA regulatory affairs specialists. Primary fieldwork combined with secondary validation from customs trade databases, SEC 10-K filings of listed building material groups, and harmonized European standard test reports. Bottom-up quarry output estimates triangulated against top-down construction spend allocation across residential, commercial, and heritage restoration segments.
Assumptions held fixed include REACH compliance timelines and heritage conservation grant funding levels, while fuel price volatility and silica exposure limit enforcement were varied across scenarios. Segmentation modeling spanned product type, application, end user archetype, and distribution channel, with regional regulatory clusters treated as distinct forecast inputs. CAGRs derived from regression against construction output indices and restoration spend patterns. Industry-specific inputs included quarry labor availability curves and CE marking test duration distributions.
Sensitivities concentrate around EU Green Deal procurement framework implementation and ECHA silica guideline enforcement timelines. Forecasts reflect documented assumptions regarding heritage mandate durability and composite fire-rating certification velocity. Macroeconomic construction cycle deviation, regulatory threshold adjustment, or synthetic formulation breakthrough would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Mineral Sand Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
China Feed Minerals Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
Europe Diatomite Market
Industrial Minerals
Unexpanded Perlite Market
Industrial Minerals
Limestone Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Asia Pacific Bentonite Market
Industrial Minerals
Gluconate Mineral Market