
 Band Ligators Market | 2026-2036
Band Ligators Market Size, Share, and Industry Trends Forecast 2026-2036
Band Ligators Market Outlook
EU MDR compliance deadlines are restructuring procurement criteria across European healthcare systems, forcing distributors to validate supply chains for CE-marked disposable ligators. Cook Medical leverages its endoscopy portfolio depth to sustain hospital contracting relationships across Germany and France. Medtronic anchors the multi-band segment through proprietary loading mechanisms that reduce operative time in high-volume gastroenterology suites. Johnson & Johnson competes on brand recognition among academic medical centers, though its reusable ligator lines face pricing pressure from single-use conversion trends.
Band ligators are mechanical devices designed to deploy elastic bands around tissue, typically during endoscopic procedures, with specifications including band diameter (commonly 9-13 mm), shaft length (160-240 cm for colonoscope compatibility), and loading capacity (single-band to six-band configurations); they function to achieve hemostasis or tissue necrosis by strangulating blood flow to targeted lesions such as esophageal varices or internal hemorrhoids. The disposable product category leads unit volume as reprocessing costs and cross-contamination liability reshape total cost-of-ownership calculations for procurement committees. Multi-band configurations represent the fastest-growing format among outpatient surgery centers, where throughput efficiency directly correlates with facility revenue per procedure block.
The FDA regulates band ligators as Class II medical devices under 510(k) premarket notification requirements, while the EU MDR imposes stricter clinical evidence standards for reusable variants that manufacturers must address through biocompatibility testing and sterilization validation documentation. Health Canada and Australia's TGA maintain reciprocal recognition frameworks that accelerate market entry for devices already cleared by the FDA, though in-country labeling and adverse event reporting obligations create distinct compliance layers. Stakeholders must monitor how CMS reimbursement adjustments for ambulatory surgical procedures influence capital allocation between disposable and reusable platform commitments.
Market Dynamics
The conversion from reusable to disposable band ligators is compressing procurement cycles and rewiring supplier relationships across ambulatory surgical networks. Facilities now prioritize total cost-of-ownership over capital expenditure, accelerating format turnover.
Growth Catalysts
- CMS reimbursement expansion:Ambulatory surgical centers in the United States capture higher procedure margins when colonoscopy volumes rise, directly lifting ligator consumption per site.
- EU MDR compliance deadlines:European healthcare systems are retiring reusable inventory ahead of clinical evidence requirements, opening procurement windows for validated single-use alternatives.
- Infection control protocols:Outpatient surgery centers tighten sterilization standards, making disposable band ligators the default specification for variceal and hemorrhoidal procedures.
Market Restraints
- Raw material concentration:Medical-grade elastomer supply for band production clusters in Southeast Asian polymer processors, exposing manufacturers to shipping cost volatility.
- Reusable legacy infrastructure:Academic medical centers with captive sterilization departments resist full conversion, extending replacement timelines for existing capital equipment.
- Biocompatibility testing burdens:EU MDR demands extensive sterilization validation documentation for any reusable variant, raising regulatory friction against multi-use formats.
Strategic Opportunities
- Underpenetrated LATAM markets:Brazil's ANVISA pathway for FDA-cleared devices accelerates entry for manufacturers with existing 510(k) documentation.
- Telemedicine-integrated screening:Remote colonoscopy referral networks in rural United States counties expand addressable procedure volumes without requiring urban hospital partnerships.
- Green procurement mandates:EU Green Deal criteria for medical waste reduction create openings for bioabsorbable band materials in sustainability-focused health systems.
Industry Challenges
- GI technician certification gaps:Multi-band loading mechanisms demand specialized training that community hospitals struggle to staff consistently.
- Legacy EMR integration:Disposable ligator inventory tracking systems must interface with hospital procurement platforms built around reusable asset management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Band Ligators Market |
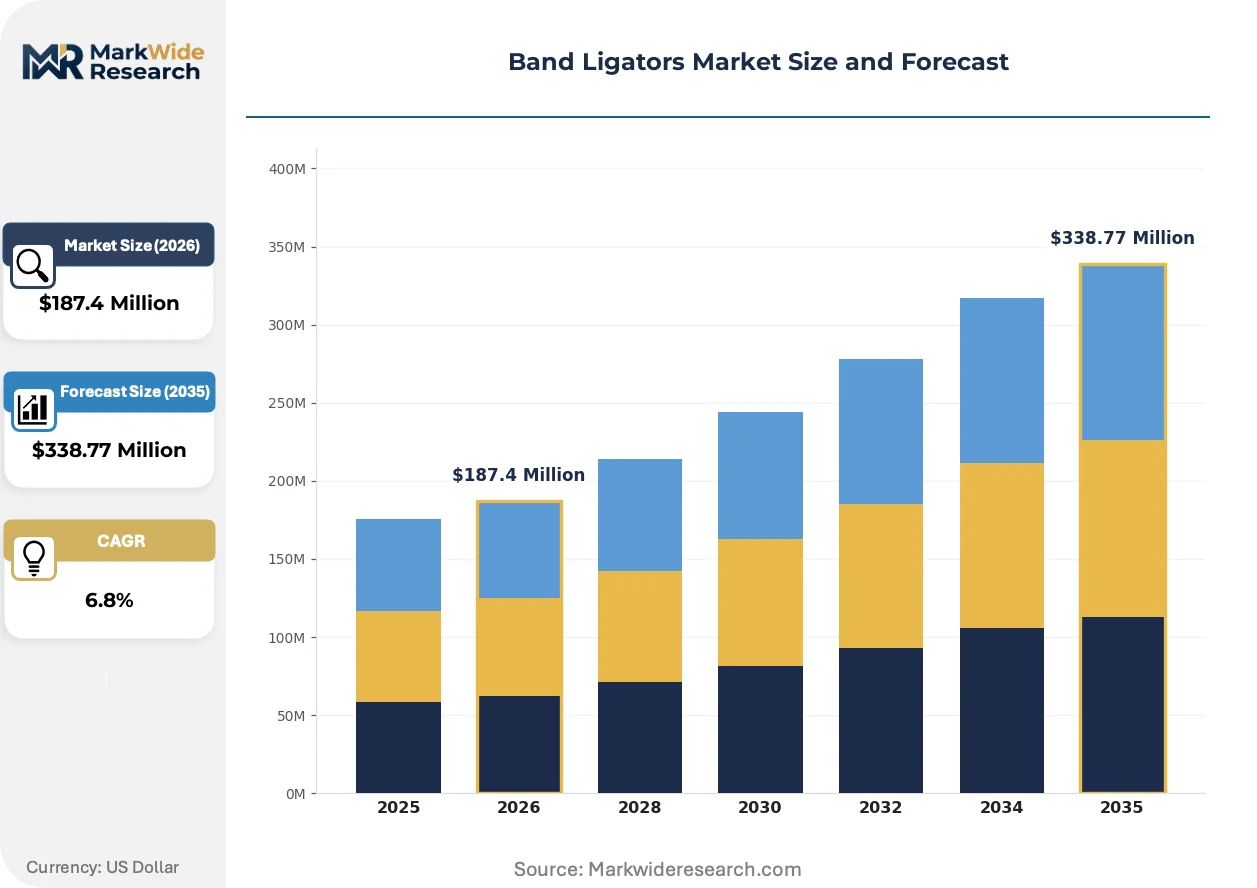
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Multi-Band, Single-Band Application: Gastroenterology, Surgical Procedures, Endoscopy, Hemorrhoid Treatment Customer Type: Hospitals, Clinics, Outpatient Surgery Centers, Specialty Practices Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Medline Industries, Cook Medical, Johnson & Johnson, Integra LifeSciences Corporation, Medtronic, CONMED Corporation, Boston Scientific Corporation, Cantel, Wellspect HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Band Ligators Market Strategic Shifts
Band ligator design is converging on throughput optimization as outpatient facilities measure revenue per procedure minute. Manufacturers are compressing loading cycles and expanding band capacity to match this operational metric.
Six-band disposable configurations are unifying the high-volume gastroenterology suite standard, replacing sequential single-band deployments. Ambulatory surgery centers in the United States adopt these systems fastest, cutting operative time by eliminating device exchanges. The format is unifying procurement specifications across multi-site networks, forcing smaller manufacturers to match capacity or exit contracting pools.
The FDA's updated reprocessing guidance for endoscopic accessories is tightening documentation requirements for any reusable device category. Manufacturers must now submit sterilization validation data with each 510(k) renewal, raising compliance costs disproportionately for reusable ligator lines. Hospital systems are responding by accelerating disposable conversion timelines, particularly in California and Texas where liability exposure drives conservative interpretation.
Group purchasing organizations are consolidating supplier panels around bundled endoscopy contracts that privilege full-procedure disposables. Independent ambulatory centers face exclusion from these networks unless they commit to standardized SKU ranges. The concentration is most visible in the southeastern United States, where regional GPOs now cover over half of non-hospital GI procedure volume.
Band Ligators Market Segmentation
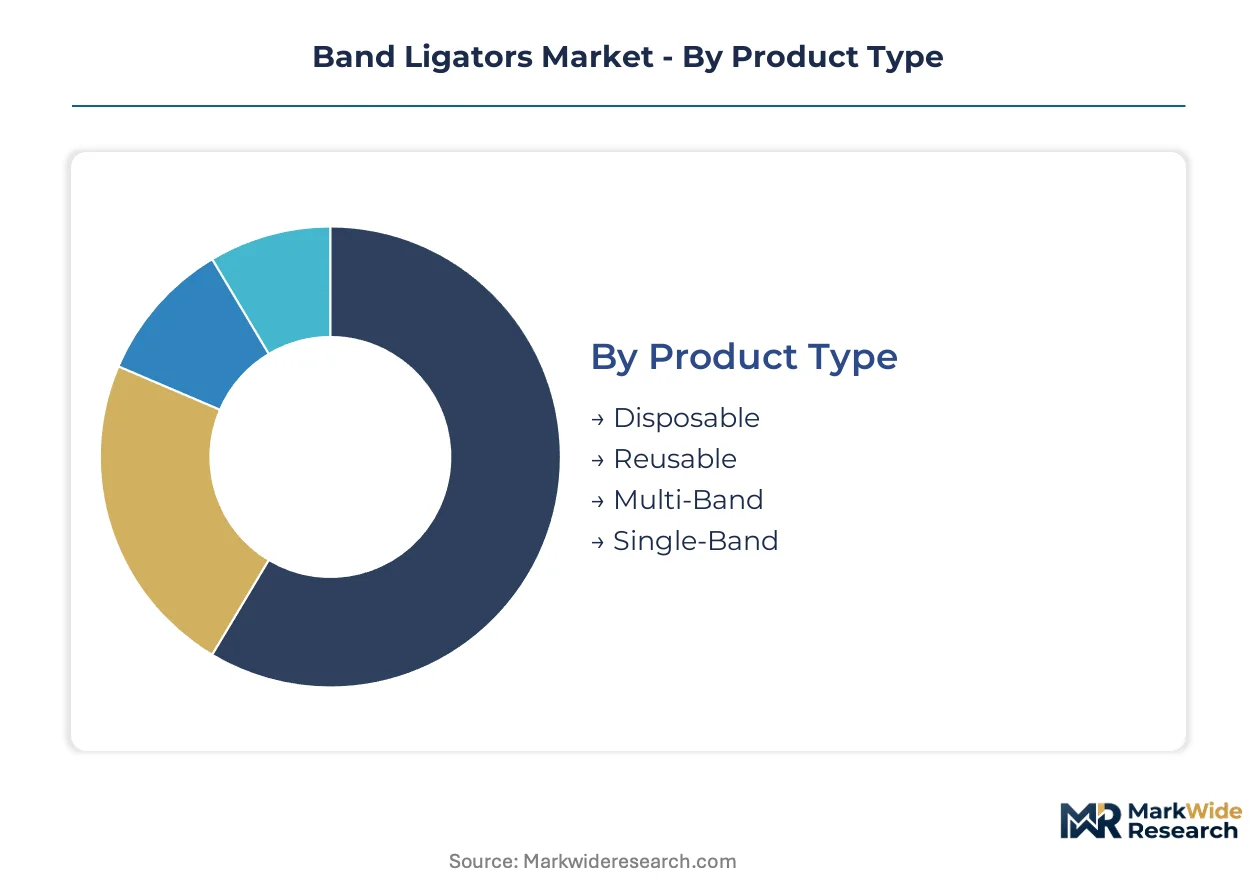
Band ligator procurement committees evaluate segments through divergent cost-of-ownership lenses. FDA 510(k) pathways and EU MDR clinical evidence requirements create asymmetric compliance burdens across product formats, reshaping purchasing hierarchies.
Product Type:
FDA Class II designation governs all variants, yet EU MDR imposes sterilization validation documentation only on reusable formats, tilting procurement toward single-use alternatives.
- Disposable:Single-use polymer shafts with pre-loaded elastic bands eliminate reprocessing labor and cross-contamination liability. Outpatient surgery centers in the United States specify these as default equipment, driven by CMS reimbursement structures that reward throughput efficiency over capital conservation.
- Multi-Band:Six-band configurations compress operative time by eliminating device exchanges during sequential ligation. Ambulatory surgical networks in Texas and California standardize on this format, where procedure volume per block directly correlates with facility revenue.
- Reusable:Stainless steel shafts with detachable band cartridges require sterilization validation under EU MDR biocompatibility testing protocols. Academic medical centers with captive sterilization departments maintain these lines despite rising compliance documentation costs.
- Single-Band:Sequential deployment devices with lower unit cost suit low-volume practices. Community hospitals in rural United States counties retain this format where capital budgets constrain multi-band conversion.
Leading the category by volume: Disposable. Growing fastest: Multi-Band.
Application:
Procedure reimbursement codes determine segment prioritization, with colonoscopy-linked interventions commanding higher facility fees than standalone hemorrhoid treatments.
- Gastroenterology:Variceal banding during diagnostic endoscopy represents the highest-volume indication. United States ambulatory surgery centers perform these procedures under CMS-covered screening protocols, driving ligator consumption per site.
- Endoscopy:Diagnostic and therapeutic colonoscopy platforms require compatible shaft lengths and diameter specifications. German hospital procurement frameworks favor devices validated under EU MDR for endoscopic accessory bundles.
- Hemorrhoid Treatment:Rubber band ligation for internal hemorrhoids occurs in office-based settings with lower reimbursement tiers. French clinics perform these procedures under national health insurance fee schedules that constrain equipment expenditure.
- Surgical Procedures:Operating room deployment for complex variceal cases demands six-band capacity and rapid loading mechanisms. Academic medical centers in Japan utilize these configurations for trainee education in hepatobiliary surgery.
Highest reimbursement capture: Gastroenterology. Expanding most quickly: Endoscopy.
Customer Type:
Capital allocation patterns separate institutional buyers, with outpatient facilities prioritizing total cost-of-ownership while hospital systems balance disposable conversion against legacy sterilization infrastructure.
- Outpatient Surgery Centers:Independent ambulatory facilities in the southeastern United States procure through regional GPOs that mandate standardized SKU ranges across multi-site networks.
- Hospitals:Integrated delivery networks in California face liability exposure that accelerates disposable conversion timelines ahead of national averages.
- Clinics:Office-based gastroenterology practices in Brazil access ANVISA-fast-tracked FDA-cleared devices for hemorrhoid ligation procedures.
- Specialty Practices:Hepatology-focused groups in France manage variceal screening programs under national cancer plan reimbursement frameworks.
Dominant procurement volume: Outpatient Surgery Centers. Steepest adoption curve: Hospitals.
Distribution Channel:
Channel selection reflects customer scale, with direct relationships reserved for high-volume hospital systems and distributor networks serving fragmented clinic demand.
- Distributors:Regional medical device distributors in Germany validate EU MDR-compliant supply chains for CE-marked disposable ligators, capturing hospital contracting relationships.
- Direct Sales:Multi-hospital systems in the United States negotiate bundled endoscopy contracts that privilege full-procedure disposables and exclude independent ambulatory centers.
- Wholesalers:Inventory aggregation for low-volume community hospitals in rural United States counties reduces per-unit shipping costs from Southeast Asian polymer processors.
- Online Retail:Emergency replenishment channels for specialty practices requiring rapid band cartridge replacement outside standard procurement cycles.
Primary volume pathway: Distributors. Gaining share fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors the North American band ligator supply chain through Medtronic's operational footprint and the dense cluster of ambulatory surgical networks across the Upper Midwest.
United States
CMS reimbursement expansion for colonoscopy screening drives procedural volume growth across Texas and California ambulatory surgery centers. FDA Class II 510(k) pathways govern device clearance, with updated reprocessing guidelines accelerating disposable conversion timelines. The southeastern United States concentrates procurement through regional GPOs covering over half of non-hospital GI procedure volume.
Germany
Hospital procurement frameworks favor EU MDR-validated endoscopic accessory bundles across Bavaria and North Rhine-Westphalia. EU MDR sterilization validation requirements impose asymmetric compliance burdens on reusable formats, tilting purchasing toward single-use alternatives. Cook Medical leverages its endoscopy portfolio depth to sustain contracting relationships with major hospital systems in Frankfurt and Munich clusters.
France
National health insurance fee schedules constrain equipment expenditure for office-based hemorrhoid procedures in Île-de-France and Auvergne-Rhône-Alpes. ANSM oversees medical device market surveillance alongside CE marking requirements under EU MDR. Academic medical centers in Paris maintain hepatology-focused variceal screening programs under national cancer plan reimbursement frameworks.
Japan
Academic medical centers in Tokyo and Osaka utilize six-band configurations for trainee education in hepatobiliary surgery. PMDA maintains stringent clinical evidence standards for reusable variants requiring biocompatibility documentation. The Kanto region concentrates demand for complex variceal cases requiring rapid loading mechanisms in operating room settings.
Brazil
ANVISA's fast-track pathway for FDA-cleared devices accelerates market entry for manufacturers with existing 510(k) documentation. Office-based gastroenterology practices in São Paulo and Rio de Janeiro access hemorrhoid ligation procedures through simplified regulatory routes. Southeast industrial corridors concentrate distributor networks serving fragmented clinic demand across Minas Gerais and Paraná.
Band Ligators Market Competitive Environment
Premium-margin players sit above commodity-margin players across the disposable-reusable spectrum, with infection control liability and reprocessing cost differentials widening the spread. The vendor base stratifies into three tiers: diversified medtech conglomerates with full endoscopy portfolios, mid-cap specialists focused on ligation accessories, and regional fabricators serving price-sensitive procurement committees. Two dominant competitive moves define current positioning: GPO-driven supplier panel consolidation around bundled contracts, and accelerated disposable SKU expansion to capture EU MDR-driven replacement cycles.
Among diversified medtech conglomerates, Medtronic and Johnson & Johnson exemplify contrasting strategic postures within the premium tier. Medtronic anchors the multi-band segment through proprietary loading mechanisms that reduce operative time in high-volume gastroenterology suites. Johnson & Johnson competes on brand recognition among academic medical centers, though its reusable ligator lines face pricing pressure from single-use conversion trends. Boston Scientific Corporation occupies a position within the same tier, representing the scale-driven end of portfolio diversification strategies.
| Leading Market Players |
|---|
| Medline Industries |
| Cook Medical |
| Johnson & Johnson |
| Integra LifeSciences Corporation |
| Medtronic |
| CONMED Corporation |
| Boston Scientific Corporation |
| Cantel |
| Wellspect HealthCare |
| Others |
Value Chain & Pricing Dynamics
Six-band disposable configurations are compressing unit economics and concentrating procurement power among high-volume ambulatory networks across the United States. The shift from reusable to single-use formats simultaneously elevates material input costs and reduces sterilization labor liabilities, rewiring how manufacturers price across customer tiers.
Pricing Analysis
Throughput-based pricing anchors procurement decisions, with outpatient surgery centers calculating cost per procedure minute rather than unit acquisition cost. Three-tier pricing structure across premium multi-band, standard disposable, and economy single-band levels separates academic medical centers from community hospitals and rural clinics. Cost compression in the reusable tier is intensifying because EU MDR sterilization validation documentation raises compliance overhead disproportionately. Price sensitivity peaks among independent ambulatory centers in the southeastern United States, where regional GPOs mandate standardized SKU ranges that limit vendor flexibility.
Supply Chain Analysis
Medical-grade elastomer supply rests on Southeast Asian polymer processors in Thailand, Malaysia, and Vietnam, with specialty latex and synthetic rubber formulations requiring certified cleanroom production environments. Raw material dependencies center on nitrile compounds, silicone band substrates, and medical-grade adhesives for cartridge assembly. Single-source vulnerability concentrates in Thai nitrile butadiene rubber facilities serving multiple ligator manufacturers simultaneously. Distribution runs through regional medical device distributors in Germany and the United States, with direct sales channels capturing multi-hospital system contracts that exclude smaller ambulatory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Band ligator procurement operates as a cost-of-compliance market where EU MDR sterilization validation requirements erect barrier-to-entry moats favoring manufacturers with established clinical evidence dossiers and validated supply chains.
For Market Incumbents: Anticipate accelerated disposable conversion timelines in California and Texas by expanding six-band capacity ahead of GPO panel consolidation deadlines. Defensive positioning requires backward integration into medical-grade elastomer supply to offset Southeast Asian shipping volatility, while certification investment in EU MDR technical documentation protects European hospital contracting relationships against mid-tier challengers. For New Entrants and Emerging Players: Regional distributors in Brazil represent the most penetrable channel partner type for ANVISA-fast-tracked FDA-cleared devices, given simplified regulatory routes for hemorrhoid ligation procedures. White-space targets concentrate on São Paulo office-based gastroenterology practices and Minas Gerais clinic networks underserved by bundled endoscopy contracts. A direct-to-clinic go-to-market angle bypasses GPO exclusion barriers that block independent ambulatory center access in the United States. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified medtech conglomerates seeking full endoscopy portfolio coverage. Long-term viability favors manufacturers with validated EU MDR supply chains and multi-band loading mechanism IP, given the irreversible shift toward throughput-optimized disposable formats. The signal to watch is CMS reimbursement adjustments for ambulatory surgical procedures, which would accelerate capital allocation shifts between disposable and reusable platform commitments.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | CE marking validation under EU MDR secures hospital procurement frameworks across Germany and France. |
| Six-Band Capacity Expansion | Multi-band loading mechanisms reduce operative time for high-volume gastroenterology suites in Texas. |
| ANVISA Fast-Track Registration | FDA-cleared devices access simplified Brazilian regulatory routes for São Paulo clinic networks. |
| Regional GPO Partnership | Southeastern United States GPO contracts cover over half of non-hospital GI procedure volume. |
| Backward Integration into Elastomer Supply | Captive nitrile sourcing mitigates shipping cost volatility from Southeast Asian polymer processors. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and ambulatory surgery center administrators. Secondary validation drew from CMS Medicare reimbursement data, ANVISA regulatory pathway documentation, and customs records tracking medical-grade elastomer imports. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Segment-level outputs reflect modeling across product type, application, customer type, and distribution channel dimensions, with geographic clustering by regulatory framework. CAGRs were derived from procedure volume projections tied to CMS colonoscopy screening expansion and EU MDR-driven replacement cycle timing. Industry-specific forecast inputs incorporated ambulatory surgery center construction pipelines and GPO contract renewal calendars.
Caveats apply where raw material shipping disruptions, CMS reimbursement recalibration, or EU MDR enforcement variability could materially shift the outlook. Forecasts reflect assumptions about disposable conversion velocity and sterilization cost trajectories. A small set of named triggers—including polymer supply chain volatility and ambulatory center consolidation rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Hemodynamic Flow Alteration Devices Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Biologic Injectors Market
Medical Devices
Dialysis Catheters Market
Medical Devices
Catheter Coatings Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
South Korea ECG Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Minimally Invasive Deformity Correction System Market