
 Pressotherapy Systems Market | 2026-2036
Pressotherapy Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pressotherapy Systems Market Intelligence
China is reconfiguring its manufacturing base for pressotherapy equipment through expanded domestic assembly lines serving both local clinics and export channels. DJO Global Incorporated leverages its orthopedic rehabilitation footprint to sustain distribution advantages across North American rehabilitation centers. Arjo AB anchors its competitive position through hospital-grade engineering standards and established procurement relationships with European healthcare networks.
Pressotherapy systems employ pneumatic compression garments that deliver calibrated sequential or pulsating pressure waves to peripheral limbs, typically operating at pressures between 30 and 100 mmHg to mobilize interstitial fluid. These devices serve therapeutic objectives spanning lymphatic drainage, venous insufficiency management, and cosmetic tissue conditioning in clinical and wellness environments. Sequential systems dominate installed bases in hospital and rehabilitation settings where protocol-driven treatment consistency commands premium positioning. Smart systems incorporating electronic control modules and treatment logging represent the fastest-expanding technology tier, particularly among spa and home care segments where user experience differentiation drives replacement cycles. Portable units occupy a narrower but growing niche serving traveling clinicians and affluent home users seeking mobility.
The FDA classifies pneumatic compression devices as Class II medical equipment, requiring premarket notification and adherence to electrical safety benchmarks under 21 CFR 870.5800. The EU Medical Device Regulation mandates CE marking with enhanced clinical evidence requirements for compression therapy systems marketed across member states. Japan's PMDA enforces Good Manufacturing Practice audits for imported pressotherapy devices, creating compliance thresholds that filter market entrants. Stakeholders must weigh regulatory pathway investments against segment-specific margin profiles when prioritizing geographic expansion or technology tier transitions.
Market Dynamics
Smart pressotherapy systems with embedded electronic control modules are compressing replacement cycles across spa and home care segments, forcing sequential-system incumbents to accelerate software roadmaps or surrender premium positioning.
Growth Catalysts
- EU Medical Device Regulation (MDR):Enhanced clinical evidence requirements for compression therapy systems are filtering out marginal competitors and concentrating procurement among certified manufacturers serving European healthcare networks.
- Post-operative lymphatic drainage protocols:Medical spas in Germany are expanding pressotherapy adoption as standard post-surgical care, creating protocol-driven demand that locks in equipment specifications and service contracts.
- Cosmetic surgery volumes:Rising aesthetic procedure counts in the United States are pulling pressotherapy devices into wellness clinic networks as mandatory recovery-stage interventions.
Market Restraints
- Biocompatibility certification costs:Pneumatic garment materials must meet escalating electrical safety and skin-contact standards under FDA 21 CFR 870.5800 and EU MDR, elevating R&D burn rates for new market entrants.
- Supply concentration in pneumatic componentry:Precision air pump and valve assemblies concentrate among East Asian contract manufacturers, exposing procurement timelines to regional logistics volatility.
- Manual lymphatic drainage substitution:Trained therapist-delivered massage retains preference in high-touch luxury spa segments, capping automated system penetration where labor arbitrage favors human delivery.
Strategic Opportunities
- Portable unit mobility:Traveling clinicians and affluent home users in North American urban corridors represent an underserved niche where battery-operated, garment-integrated designs command price premiums.
- China domestic assembly expansion:Local manufacturing lines serving both clinic networks and export channels offer tariff-advantaged production positioning for brands with established distribution.
- Sequential-pulsating hybrid architectures:Convergence of hospital-grade protocol precision with spa-segment user experience customization opens white space between installed-base sequential systems and emerging smart platforms.
Industry Challenges
- PMDA Good Manufacturing Practice audits:Japan's pharmaceutical and medical device agency imposes extended compliance timelines on imported pressotherapy equipment, stretching market entry cycles to 18-24 months.
- Legacy electronic control integration:Rehabilitation centers with embedded sequential system fleets face capital-intensive retrofit requirements to adopt treatment-logging and connectivity features now standard in smart-tier offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressotherapy Systems Market |
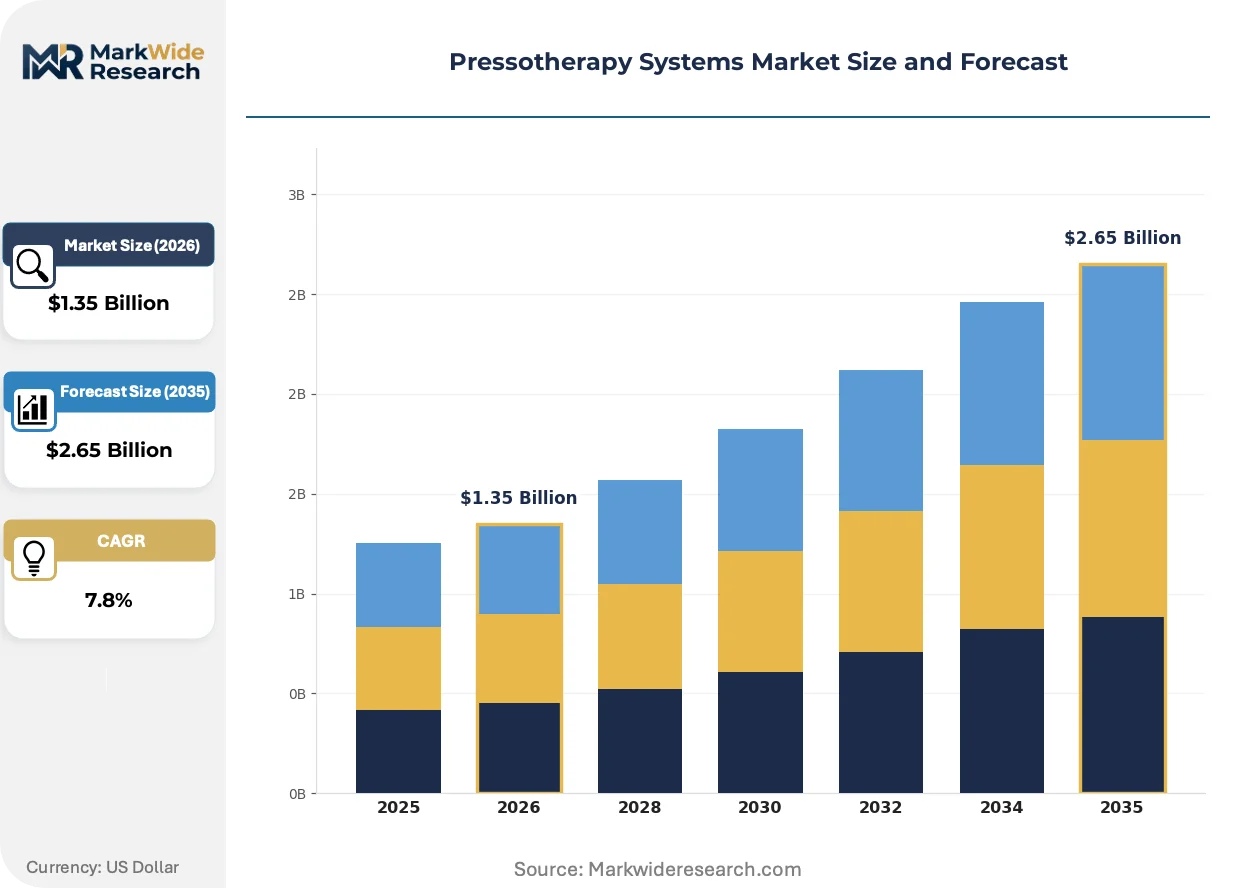
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequential Systems, Pulsating Systems, Combination Systems, Standalone Units End User: Clinics, Spas, Home Care, Rehabilitation Centers Application: Lymphatic Drainage, Cellulite Reduction, Post-Surgery Recovery, Cosmetic Treatments Technology: Electronic Control, Manual Control, Smart Systems, Portable Units |
| Companies Covered | Mego Afek AC Limited, Arjo AB, DJO Global Incorporated, Physiomed Elektromedizin AG, Zimmer MedizinSysteme GmbH, Tactile Medical Systems Incorporated, NormaTec Recovery Systems LLC, Enraf Nonius B V, Bio Compression Systems Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressotherapy Systems Market Strategic Shifts & Innovations
Pressotherapy equipment is bifurcating into hospital-grade precision platforms and consumer-accessible smart garments, with software-defined treatment protocols displacing mechanical calibration as the primary value differentiator.
Bluetooth-enabled pressure modulation is collapsing the boundary between clinical and home-use segments. Spa operators are adopting these connected garments to extend treatment protocols beyond facility walls. The compression therapy market is compressing into two tiers: FDA-cleared medical devices and wellness-registered lifestyle products with diverging margin structures.
Japan's PMDA has tightened electrical safety documentation requirements for imported pneumatic compression devices, extending premarket review timelines. Manufacturers are responding by establishing local quality management system subsidiaries or partnering with domestic distributors bearing existing PMDA registrations. The regulatory friction most impacts mid-tier European exporters lacking captive Japan infrastructure.
Wellness clinic procurement is gravitating toward outcome-verified equipment leases rather than capital purchases, with payment tied to documented patient session completion. Equipment financiers and clinic networks are negotiating service-level agreements that bundle device maintenance, garment replacement, and software updates. This shift is most pronounced in United States metropolitan markets where clinic rollups concentrate buying power.
Pressotherapy Systems Market Segmentation
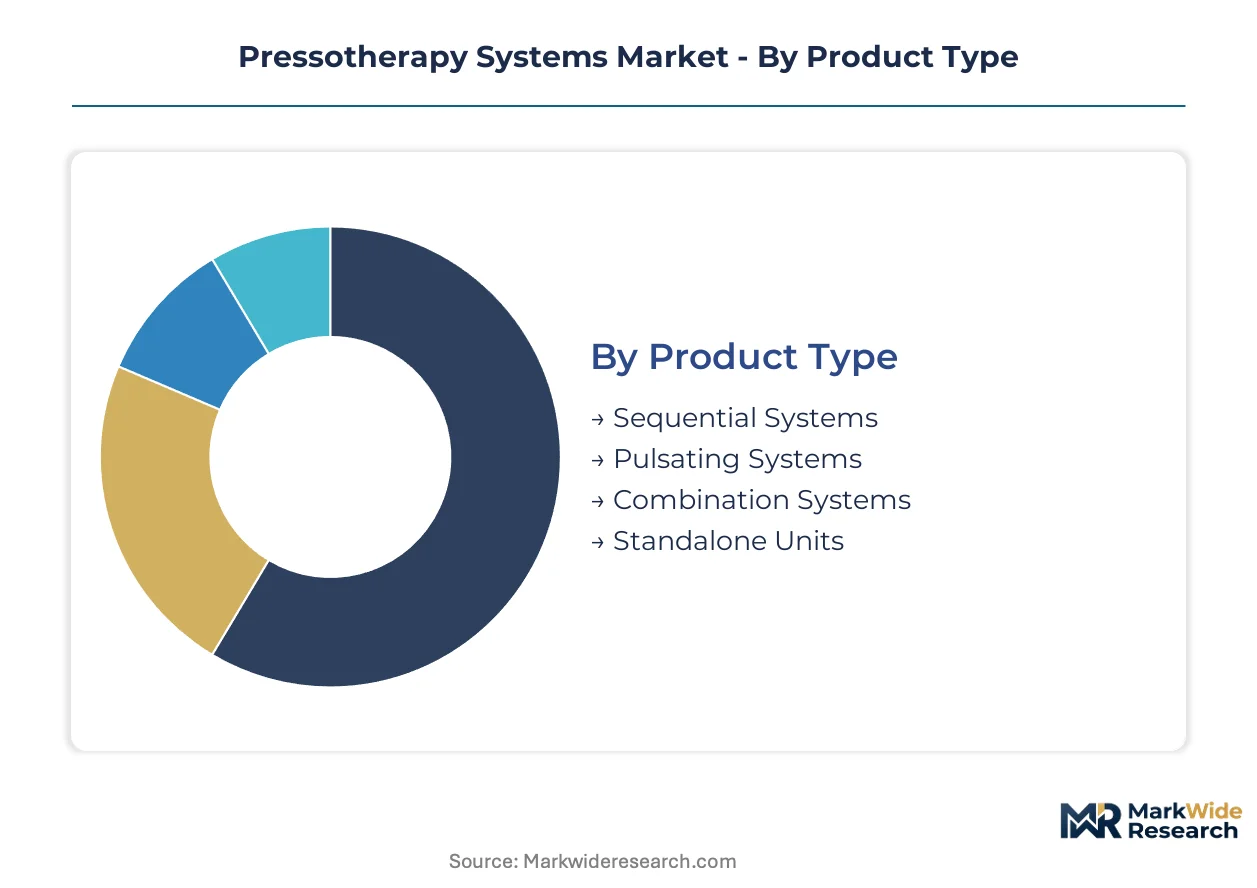
Pressotherapy equipment segments by pressure delivery mechanism, care setting, therapeutic objective, and control architecture. Each dimension shapes procurement specifications, reimbursement pathways, and replacement cycle timing across clinical and wellness environments.
Product Type:
Sequential systems turn over slowest due to hospital capital budget cycles, while smart-enabled portable units refresh fastest as spa operators chase user experience upgrades.
- Sequential Systems:These devices deliver calibrated pressure waves through multi-chamber garments in fixed distal-to-proximal sequences, typically operating at 30-100 mmHg for protocol-driven lymphatic drainage. Demand concentrates in German rehabilitation centers and US hospital networks where treatment consistency and liability documentation override upfront cost considerations. Replacement cycles stretch 7-10 years due to capital equipment amortization schedules and embedded staff training investments.
- Pulsating Systems:Intermittent compression cycles characterize these units, generating rhythmic pressure variations rather than progressive chamber sequencing. French and Italian medical spas favor pulsating architectures for cellulite treatment protocols where patient comfort perception drives repeat visit rates. These systems face faster obsolescence pressure as Bluetooth-enabled competitors enter the wellness segment.
- Combination Systems:Hybrid architectures merging sequential and pulsating modes serve multi-protocol clinics seeking equipment versatility across drainage and cosmetic applications.
- Standalone Units:Single-function devices without modular garment expansion capabilities occupy budget-conscious entry-level positioning in independent spa operations.
Sequential systems dominate installed base. Pulsating and combination architectures are where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive clinical procurement from lease-oriented wellness operators and direct-to-consumer home purchases.
- Clinics:Physician-supervised lymphology and vascular medicine practices in the United States and Germany anchor demand for FDA-cleared and CE-marked medical-grade systems. These buyers prioritize electrical safety documentation, biocompatibility certifications, and service contract availability over unit aesthetics.
- Spas:Wellness and aesthetic treatment facilities across France, Italy, and California drive volume for design-forward systems with treatment logging and client management software. Lease financing and outcome-based payment structures are reshaping spa procurement toward operational expenditure models.
- Home Care:Affluent consumers in North American urban corridors and Japanese metropolitan areas purchase portable units for post-surgical recovery and chronic condition management.
- Rehabilitation Centers:Physical therapy networks in Germany and the United States maintain embedded sequential system fleets with extended replacement horizons.
Clinics and rehabilitation centers dominate installed base. Spas and home care segments are climbing the fastest.
Application:
Volume concentration varies by therapeutic category, with cosmetic applications showing steepest expansion trajectory and post-surgical protocols locking in longest equipment lifecycles.
- Lymphatic Drainage:The foundational therapeutic application addressing lymphedema, chronic venous insufficiency, and post-operative fluid mobilization. German medical spas and US vascular clinics specify these systems as mandatory post-surgical infrastructure, creating protocol-driven demand with limited price elasticity.
- Cellulite Reduction:Cosmetic tissue conditioning applications concentrate in French and Italian wellness markets where consumer willingness-to-pay for aesthetic outcomes supports premium equipment positioning.
- Post-Surgery Recovery:Protocol-standardized deployment in cosmetic surgery clinics across California, Florida, and Texas creates recurring revenue streams through garment replacement and maintenance contracts.
- Cosmetic Treatments:Broad aesthetic applications including skin tightening and contouring drive spa segment procurement with fastest technology refresh cycles.
Lymphatic drainage dominates installed base. Cellulite reduction and cosmetic treatments are gaining share fastest.
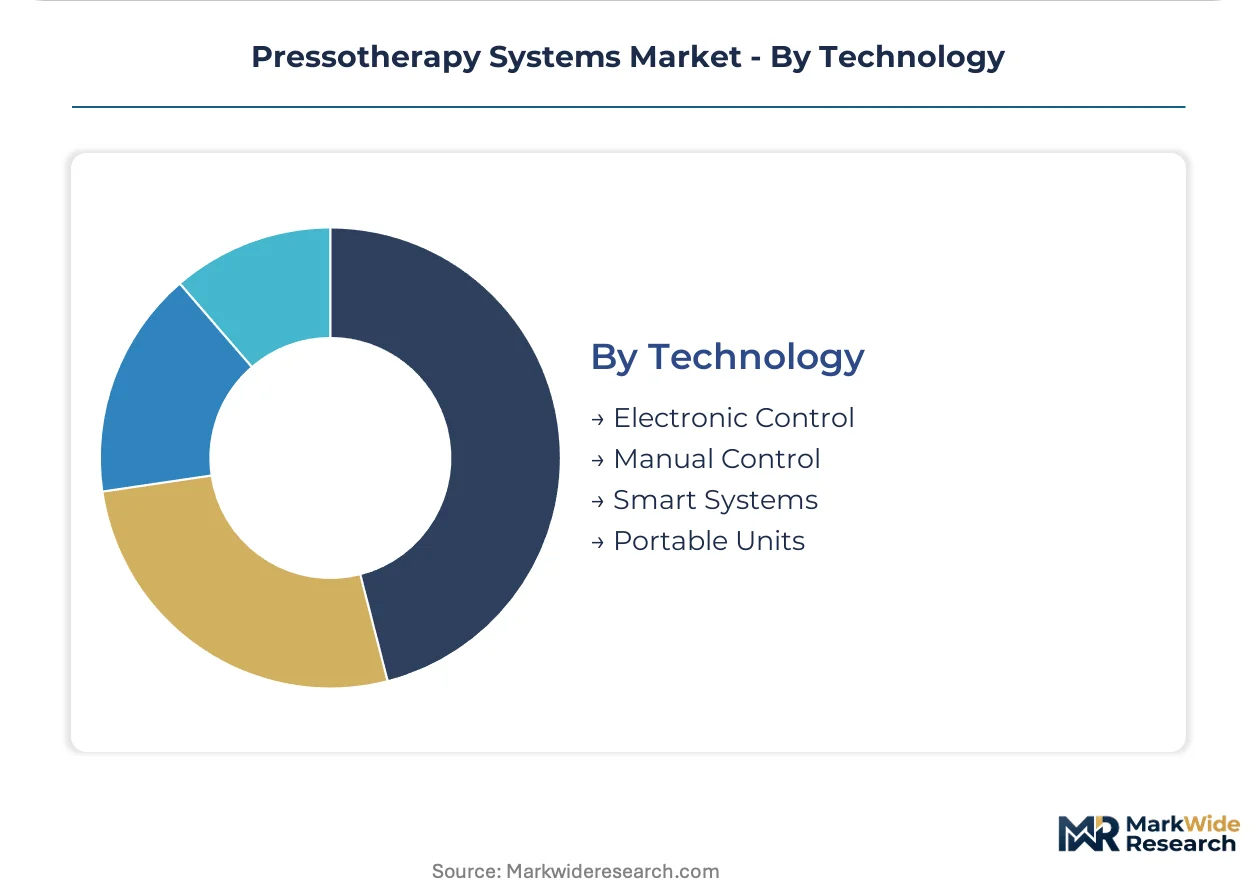
Technology:
Customer type bifurcation separates institutional buyers seeking protocol precision from wellness operators and consumers prioritizing connectivity and mobility.
- Electronic Control:Microprocessor-regulated pressure modulation enables precise treatment parameter storage and replication across sessions. German hospital procurement and US clinic networks require electronic control architectures for malpractice risk mitigation and outcome documentation.
- Manual Control:Mechanical pressure adjustment systems without digital interfaces persist in price-sensitive spa segments and emerging market installations where capital constraints override feature requirements.
- Smart Systems:Connected platforms with Bluetooth pressure modulation, treatment logging, and mobile application integration represent the steepest expansion trajectory across spa and home care segments.
- Portable Units:Battery-operated, garment-integrated designs serve traveling clinicians and affluent home users in North American and Japanese urban corridors.
Electronic control systems dominate installed base. Smart systems and portable units are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between clinical and wellness applications across major markets. German medical spas deploy pressotherapy as mandatory post-operative infrastructure, while US aesthetic clinics integrate devices into cosmetic surgery recovery protocols. Japanese buyers demand extended compliance documentation, compressing import velocity.
United States
Cosmetic surgery volumes in California, Florida, and Texas pull pressotherapy devices into wellness clinic networks as recovery-stage interventions. FDA 21 CFR 870.5800 governs pneumatic compression device classification, requiring premarket notification for Class II medical equipment. The Greater Los Angeles corridor hosts dense clinic rollups negotiating outcome-based equipment leases tied to patient session completion.
Germany
Medical spas across Bavaria and North Rhine-Westphalia specify pressotherapy as standard post-surgical lymphatic drainage infrastructure. EU Medical Device Regulation mandates CE marking with enhanced clinical evidence requirements for compression therapy systems. The Baden-Baden wellness cluster anchors procurement relationships with hospital-grade engineering specialists serving rehabilitation networks.
China
Domestic assembly lines in the Yangtze River Delta serve both local clinic networks and export channels, reconfiguring manufacturing positioning. NMPA medical device registration governs pneumatic compression equipment for clinical use, while wellness products fall under lighter consumer goods oversight. Shanghai-based distributors are consolidating procurement for spa chains across Southeast Asian markets.
Japan
Affluent home users in the Tokyo metropolitan area purchase portable units for chronic condition management and post-surgical recovery. PMDA Good Manufacturing Practice audits stretch market entry cycles to 18-24 months for imported pressotherapy equipment. Osaka-based quality management subsidiaries are emerging as compliance gateways for European manufacturers lacking captive Japan infrastructure.
France
Medical spas in Provence-Alpes-Côte d'Azur favor pulsating compression architectures for cellulite treatment protocols where patient comfort drives repeat visit rates. ANSM vigilance requirements apply to medical-grade pneumatic compression devices marketed for lymphatic drainage. The Cannes-Nice aesthetic corridor concentrates design-forward system procurement with fastest technology refresh cycles.
Pressotherapy Systems Market Key Industry Players
Capability concentration sits with hospital-grade engineering specialists; scale advantage sits with rehabilitation equipment distributors with embedded North American networks. The vendor base organizes around three archetypes: European precision manufacturers with CE-marking authority, US clinic-network distributors with orthopedic rehabilitation footprints, and emerging Asian assemblers with tariff-advantaged export positioning. Consolidation pressure is accelerating through strategic partnerships between garment fabricators and electronic control module suppliers, plus geographic expansion via local quality management subsidiaries in regulated Asian markets.
Among European precision manufacturers, Arjo AB and Zimmer MedizinSysteme GmbH exemplify the hospital-grade engineering tier with established procurement relationships across German and Swiss healthcare networks. DJO Global Incorporated anchors the North American distribution vector, leveraging orthopedic rehabilitation infrastructure to sustain clinic-network penetration. These three entities represent divergent competitive positioning: European engineering certification, North American channel density, and the convergence pressure forcing technology roadmap acceleration.
| Leading Market Players |
|---|
| Mego Afek AC Limited |
| Arjo AB |
| DJO Global Incorporated |
| Physiomed Elektromedizin AG |
| Zimmer MedizinSysteme GmbH |
| Tactile Medical Systems Incorporated |
| NormaTec Recovery Systems LLC |
| Enraf Nonius B V |
| Bio Compression Systems Incorporated |
| Others |
Cost & Logistics Intelligence
Shanghai-Ningbo port freight corridors transmit cost volatility from East Asian pneumatic component clusters into European and North American landed prices, compressing margins for mid-tier manufacturers while amplifying differentiation premiums for FDA-cleared and CE-marked medical-grade systems.
Pricing Analysis
Long-term service contracts dominate hospital and rehabilitation center procurement, locking in garment replacement schedules and preventive maintenance over 5-7 year horizons. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared medical devices from wellness-registered lifestyle products and unbranded entry-level units. Pricing pressure stems from biocompatibility certification costs under EU MDR and FDA 21 CFR 870.5800, which elevate R&D burn rates. Independent spa operators exhibit highest price sensitivity, while German medical spas and US hospital networks prioritize electrical safety documentation over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for brands dependent on Yangtze River Delta assembly. Precision air pump and valve assemblies concentrate among Chinese, South Korean, and Japanese contract manufacturers, with silicone bladder materials and medical-grade PVC fabrics drawing from specialized Taiwanese and German suppliers. Single-source vulnerability in electronic control module fabrication creates procurement timeline exposure. Distribution runs through orthopedic rehabilitation equipment distributors in North America, direct hospital procurement in Germany, and consolidated spa chain buyers in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled pressure modulation is compressing replacement cycles and forcing technology roadmap acceleration, while EU MDR enhanced clinical evidence requirements filter out marginal competitors and concentrate procurement among certified manufacturers.
For Market Incumbents: Entrench hospital-grade engineering credibility through accelerated software roadmaps that embed treatment logging and connectivity features now standard in smart-tier offerings. Deepen CE-marking authority investments to exploit EU MDR compliance thresholds that marginal competitors cannot clear. Prioritize backward integration into pneumatic garment fabrication to control biocompatibility certification timelines and reduce exposure to East Asian component volatility. For New Entrants and Emerging Players: Build out portable unit capabilities targeting affluent home users in North American urban corridors and Japanese metropolitan areas, where battery-operated designs command price premiums and regulatory pathways remain less congested than clinical segments. Target outcome-based equipment lease financing for US wellness clinic rollups, where operational expenditure models are displacing capital purchases. Pursue partnerships with established quality management subsidiaries in Osaka to bypass PMDA audit timelines. For Investors and Strategic Acquirers: Hospital-grade engineering specialists with embedded European healthcare procurement relationships represent the most defensible acquisition archetype, given protocol-driven demand stickiness and extended replacement cycles. Long-term viability hinges on software-defined treatment protocol capabilities that span clinical and wellness segments. Watch for FDA 510(k) clearance velocity as an inflection indicator distinguishing scalable platforms from lifestyle product vendors.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks procurement relationships with German rehabilitation networks. |
| Software Companion Development | Bluetooth-enabled mobile applications extend treatment protocols beyond facility walls for spa operators. |
| Hospital System Partnership | GPO contracts with US vascular medicine practices secure protocol-driven demand with limited price elasticity. |
| Backward Integration into Garment Fabrication | In-house silicone bladder production controls biocompatibility certification timelines under FDA 21 CFR 870.5800. |
| Reimbursement Strategy | Documentation standards for lymphatic drainage protocols align with Medicare and private payer requirements. |
Research Approach
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and spa chain procurement directors and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and customs trade records. Bottom-up equipment shipment estimates triangulated with top-down addressable market sizing across pressure delivery mechanism, care setting, and control architecture dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume and value outputs through segmentation by product type, end user, therapeutic application, and technology tier. CAGRs were derived from installed base turnover rates, replacement cycle compression from smart system adoption, and protocol-driven demand elasticity in clinical segments. Industry-specific forecast inputs included cosmetic surgery volume trajectories in California, Florida, and Texas, plus EU MDR implementation timelines affecting competitive filtration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian assemblers with tariff-advantaged export positioning would shift outcomes through accelerated price competition in wellness segments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Indian Laparoscopy Devices Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Disposable Lancets Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Chest Drainage System Market