
 Peritoneal Catheter Systems Market | 2026-2036
Peritoneal Catheter Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Peritoneal Catheter Systems Market Analytics
Aftermarket service revenue is rewriting profitability dynamics across the peritoneal catheter value chain. Baxter International Inc. leverages its integrated dialysis delivery platform to capture recurring consumable sales alongside capital equipment placements. Fresenius Medical Care AG & Co. KGaA anchors its position through vertical control over dialysate supply and catheter distribution networks in Western Europe. Medtronic competes by specializing in minimally invasive insertion technologies that reduce procedural complication rates.
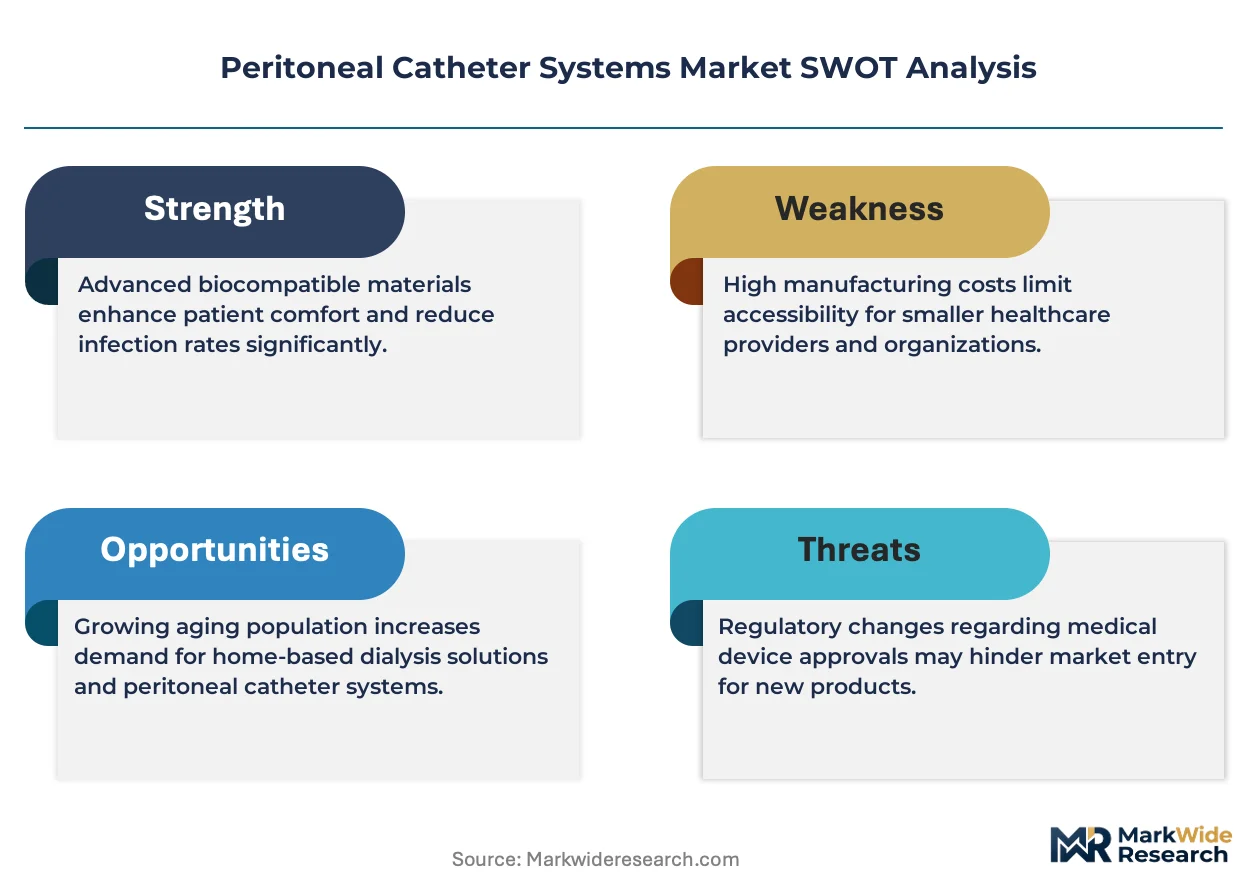
Peritoneal catheter systems are silicone or polyurethane tubes surgically implanted into the peritoneal cavity to enable dialysate exchange in renal replacement therapy, typically featuring radiopaque stripes and multiple side holes to optimize fluid distribution and imaging visibility. Tenckhoff catheters dominate installed base volumes due to decades of clinical familiarity and established reimbursement codes, while antimicrobial-coated variants represent the fastest-growing technology segment as infection-related hospitalization costs drive preference shifts. Dialysis centers currently occupy the largest end-user share, though homecare providers are gaining structural importance as payors incentivize site-of-care migration.
The FDA regulates these devices under Class II medical device pathways with 510(k) clearance requirements, while the EU Medical Device Regulation mandates notified body conformity assessments and post-market surveillance systems that extend compliance obligations for manufacturers. The EPA oversees antimicrobial agent environmental release profiles embedded in coated catheter formulations. Stakeholders must monitor evolving reimbursement parity between peritoneal and hemodialysis modalities as Medicare Advantage plans recalibrate site-of-care incentives.
Market Dynamics
Homecare migration is compressing traditional dialysis center procurement cycles while antimicrobial coating mandates from the FDA and EU MDR force simultaneous product redesign and clinical evidence generation across manufacturer pipelines.
Growth Catalysts
- Site-of-care policy incentives:Medicare Advantage plans in the United States now structure reimbursement to favor home-based renal replacement therapy, accelerating patient discharge from in-center hemodialysis.
- Antimicrobial coating technology:Silver-ion and antibiotic-impregnated catheter surfaces reduce peritonitis incidence, satisfying payor demands for hospitalization cost containment.
- Silicone material advances:Biocompatible formulations with enhanced tensile strength extend catheter functional lifespan, reducing exchange frequency and total cost of ownership.
Market Restraints
- Silicone raw material concentration:Specialty medical-grade silicone supply concentrates among a limited set of chemical manufacturers, exposing catheter producers to input volatility and allocation risk.
- EU MDR compliance burden:Extended notified body review timelines and strengthened post-market surveillance requirements delay product launches and elevate regulatory overhead for European market access.
- Hemodialysis substitution threat:Wearable and portable hemodialysis devices under development offer alternative renal replacement modalities that could displace peritoneal dialysis in select patient populations.
Strategic Opportunities
- Rural United States penetration:Geographic areas distant from dialysis centers present underserved demand for home-based therapy supported by telemedicine-enabled clinical monitoring.
- Pediatric application expansion:Smaller-diameter catheter designs adapted for neonatal and pediatric patients address an underdeveloped segment with specialized clinical requirements.
- Integrated delivery platform convergence:Combination of automated peritoneal dialysis cyclers with cloud-connected catheter monitoring systems creates bundled service offerings.
Industry Challenges
- Interventional nephrologist training gaps:Percutaneous catheter insertion techniques require specialized procedural skills that remain concentrated among limited specialist cohorts, constraining placement capacity.
- 510(k) clearance timeline compression:FDA review of antimicrobial-coated variants demands extensive biocompatibility and efficacy data, extending development cycles.
- Legacy EHR integration friction:Home dialysis monitoring data streams face interoperability barriers with established hospital information systems, complicating care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peritoneal Catheter Systems Market |
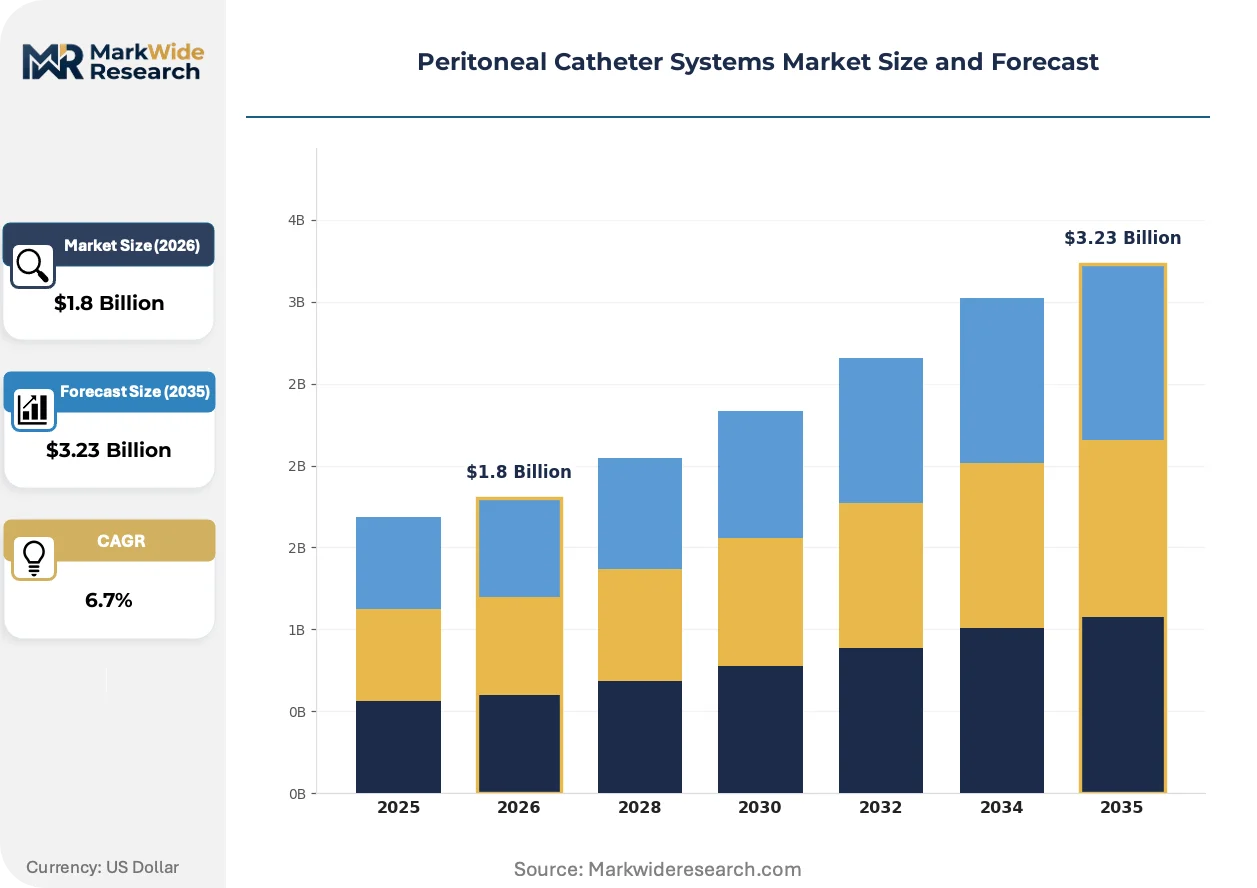
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tenckhoff Catheters, Dual-Lumen Catheters, Coiled Catheters, Pediatric Catheters End User: Hospitals, Dialysis Centers, Homecare Providers, Specialty Clinics Technology: Antimicrobial Catheters, Biocompatible Materials, Ultrasound Guidance, Laparoscopic Techniques Application: Chronic Kidney Disease, End-Stage Renal Disease, Peritoneal Dialysis, Cancer Treatment |
| Companies Covered | Baxter International Inc., Fresenius Medical Care AG & Co. KGaA, Medtronic, Terumo Corporation, Utah Medical Products, Inc., Merit Medical Systems, Cook Medical, Polymedicure, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peritoneal Catheter Systems Market Evolving Landscape
Antimicrobial surface engineering and connected care infrastructure are converging to redefine catheter lifecycle economics, while regulatory frameworks on both sides of the Atlantic accelerate differentiation between coated and standard device categories.
Antimicrobial catheter technology is migrating from premium positioning toward standard-of-care expectation. Dialysis centers in the United States now specify silver-impregnated or antibiotic-coated variants in routine procurement tenders. The FDA's updated guidance on antimicrobial device coatings is compressing the competitive window for manufacturers lacking validated coating platforms.
EU Medical Device Regulation post-market surveillance mandates now require systematic collection of real-world performance data across implanted device cohorts. Manufacturers must maintain vigilance systems tracking catheter-related infection rates and mechanical failure modes. German and French notified bodies are enforcing these obligations most stringently, driving consolidation among suppliers with limited pharmacovigilance infrastructure.
Patient self-management platforms are displacing traditional nurse-led training models for catheter care and exchange procedures. Homecare providers in the United States and United Kingdom now license digital education modules that reduce in-person clinical touchpoints. This behavioral shift concentrates procurement influence among payors and integrated delivery networks rather than individual dialysis facilities.
Peritoneal Catheter Systems Market Segmentation
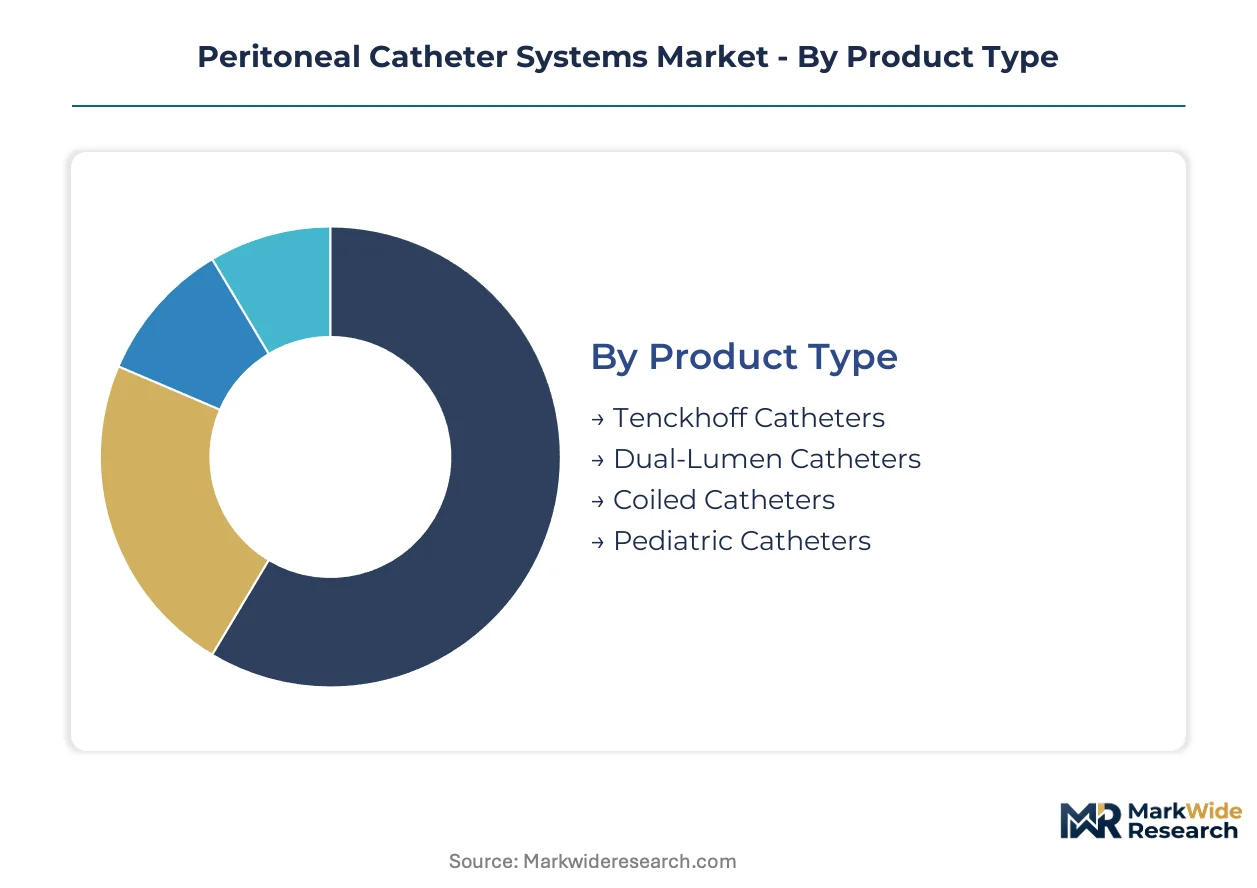
Peritoneal catheter procurement patterns diverge sharply across clinical settings and patient acuity levels. Product specifications, insertion techniques, and reimbursement pathways create distinct demand clusters that manufacturers must address through targeted portfolio strategies.
Product Type:
Cost tier differentiation separates commodity catheter placements from premium device selections in procurement workflows.
- Tenckhoff Catheters:Silicone or polyurethane tubes feature radiopaque stripes and multiple side holes for dialysate distribution. Dialysis centers in the United States specify these in bulk purchasing agreements due to established reimbursement codes and decades of clinical familiarity.
- Dual-Lumen Catheters:Twin-channel designs enable simultaneous inflow and outflow, reducing exchange cycle times. Homecare providers in rural areas favor these configurations to minimize patient handling complexity during self-administered therapy.
- Coiled Catheters:Intraperitoneal spiral configurations reduce omental entrapment and catheter migration rates.
- Pediatric Catheters:Reduced-diameter variants address neonatal and adolescent anatomical requirements with specialized tunneling techniques.
Tenckhoff Catheters command the established base. The steepest expansion runs through Pediatric Catheters.
End User:
Customer type determines volume concentration, with site-of-care migration redistributing purchasing influence across provider categories.
- Hospitals:Acute care facilities handle emergent catheter placements and complication management for peritonitis or mechanical failure. These institutions concentrate demand for advanced antimicrobial-coated variants and interventional radiology support.
- Dialysis Centers:Outpatient facilities perform scheduled catheter exchanges and routine maintenance. Medicare Advantage reimbursement structures in the United States are compressing their procurement volumes as patients transition to home-based modalities.
- Homecare Providers:Organizations delivering remote clinical monitoring and patient training for self-administered peritoneal dialysis.
- Specialty Clinics:Nephrology-focused practices offering percutaneous insertion services and long-term catheter management.
Hospitals anchor the current installed base. Homecare Providers are gaining share fastest.
Technology:
Maturity gradients separate validated clinical standards from emerging insertion and material innovations.
- Antimicrobial Catheters:Silver-ion and antibiotic-impregnated surfaces reduce peritonitis incidence. FDA guidance on coating validation is compressing competitive windows for manufacturers lacking established platforms.
- Biocompatible Materials:Enhanced silicone formulations extend functional lifespan through improved tensile strength and reduced protein adhesion. Specialty chemical manufacturers in Germany and Japan control supply of medical-grade feedstocks.
- Ultrasound Guidance:Real-time imaging for percutaneous insertion reduces procedural complications and fluoroscopy exposure.
- Laparoscopic Techniques:Minimally invasive surgical placement enables direct visualization for complex anatomical cases.
Biocompatible Materials command the established base. Antimicrobial Catheters are climbing the fastest.
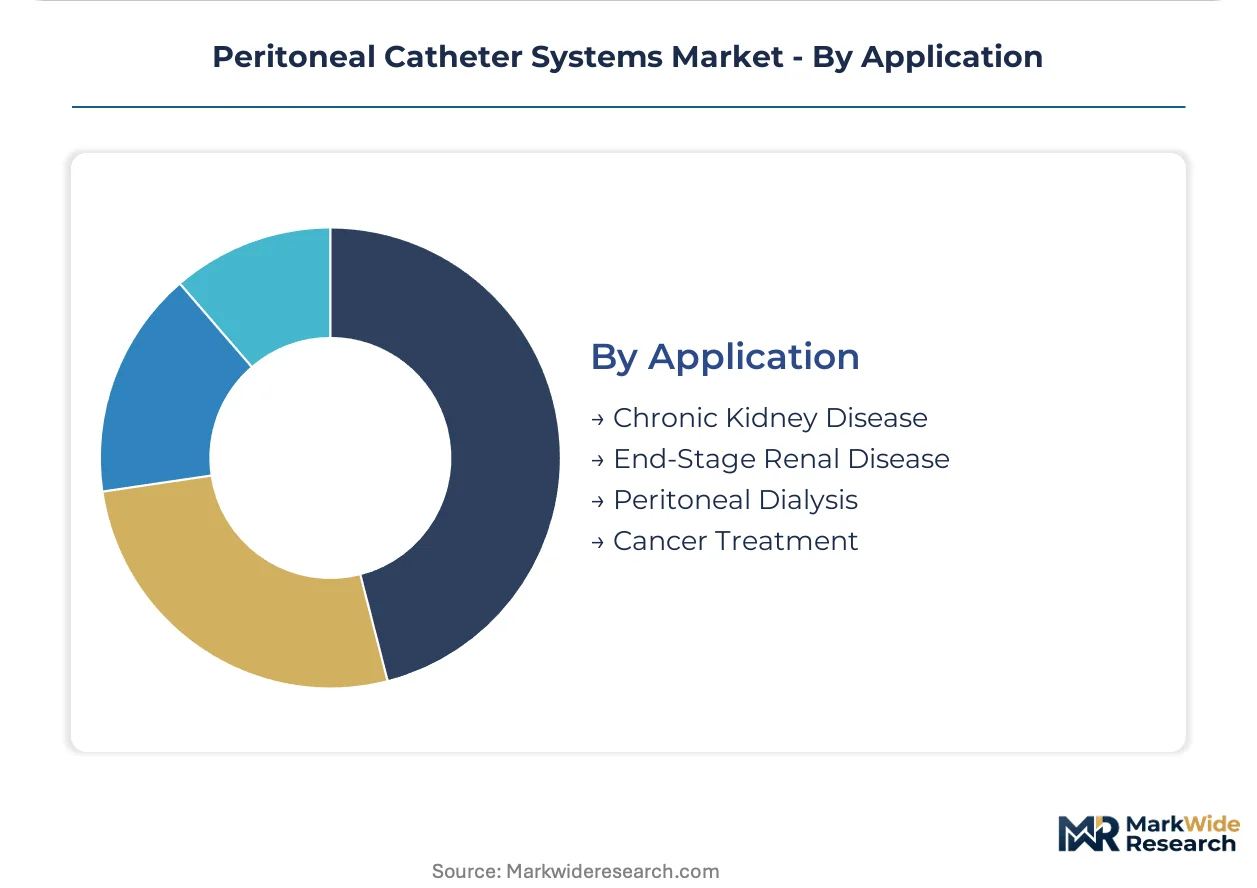
Application:
Volume concentration tracks disease prevalence and treatment modality selection patterns across patient populations.
- Chronic Kidney Disease:Progressive renal function decline creates longitudinal catheter requirements spanning months to years. Patient education programs in the United Kingdom and Australia emphasize early peritoneal dialysis initiation to preserve residual renal function.
- End-Stage Renal Disease:Complete kidney failure necessitates permanent renal replacement therapy. United States Medicare reimbursement parity between peritoneal and hemodialysis modalities is expanding device demand in this segment.
- Peritoneal Dialysis:Ongoing dialysate exchange therapy for maintenance renal replacement.
- Cancer Treatment:Intraperitoneal chemotherapy delivery via indwelling catheters for ovarian and gastric malignancies.
End-Stage Renal Disease commands the established base. Peritoneal Dialysis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peritoneal catheter utilization patterns diverge sharply by geography. The United States favors home-based modalities with telemedicine support, while Western European systems emphasize hospital-anchored insertion networks and antimicrobial coating mandates.
United States
Medicare Advantage reimbursement parity and rural access gaps drive homecare provider expansion. The FDA's updated antimicrobial device coating guidance compresses product development timelines for manufacturers. Dialysis delivery networks concentrate in Texas, Florida, and the Midwest, where nephrology practice consolidation accelerates catheter placement capacity.
Germany
Notified bodies under the EU Medical Device Regulation enforce stringent post-market surveillance for implanted devices. EMA pharmacovigilance requirements elevate compliance overhead for catheter manufacturers. Medical technology clusters in Baden-Württemberg and North Rhine-Westphalia host specialized silicone processing capabilities serving European device producers.
Japan
PMDA regulatory pathways emphasize biocompatibility validation for extended-dwelling implants. METI industrial policy supports domestic production of medical-grade polymers to reduce import dependency. Osaka-based chemical manufacturers supply specialty silicone formulations to regional catheter fabricators.
United Kingdom
NHS England's renal replacement therapy guidelines emphasize early peritoneal dialysis initiation to preserve residual kidney function. MHRA conformity assessment procedures align with EU MDR standards post-Brexit. London and Manchester academic medical centers pioneer ultrasound-guided insertion training programs for interventional nephrologists.
Australia
TGA medical device regulations mandate systematic tracking of catheter-related infection outcomes through national registries. Remote patient monitoring infrastructure supports home dialysis adoption in Queensland and Western Australia. Sydney-based nephrology networks coordinate telemedicine-enabled catheter management for rural Indigenous populations.
Peritoneal Catheter Systems Market Competitive Landscape
Capability concentration sits with specialized coating technology developers; scale advantage sits with integrated dialysis delivery platforms. The market structure tiers between multinational medical device conglomerates with captive distribution and regional catheter specialists with process expertise. Three archetypes dominate: integrated therapy platform operators, interventional device specialists, and antimicrobial material technology licensors. Competitive moves center on backward integration into silicone supply and strategic partnerships with automated dialysis cycler manufacturers.
Among integrated platform operators, Baxter International Inc. and Fresenius Medical Care AG & Co. KGaA exemplify the therapy-systems archetype, occupying positions that bundle catheter supply with consumable and equipment revenue streams. Medtronic represents the interventional technology tier, anchoring a position derived from minimally invasive insertion device portfolios. These three companies illustrate how competitive positioning stratifies between therapy-integrated and procedure-focused business models.
| Leading Market Players |
|---|
| Baxter International Inc. |
| Fresenius Medical Care AG & Co. KGaA |
| Medtronic |
| Terumo Corporation |
| Utah Medical Products, Inc. |
| Merit Medical Systems |
| Cook Medical |
| Polymedicure |
| Becton, Dickinson and Company |
| Others |
Value Network & Pricing Analysis
Single-source dependency on German and Japanese specialty chemical manufacturers for medical-grade silicone feedstocks compresses margin buffers at both premium and economy pricing tiers while forcing catheter producers into multi-year supply commitments that lock in cost structures regardless of demand fluctuations.
Pricing Analysis
Long-term offtake agreements dominate procurement between dialysis delivery platforms and catheter manufacturers, with spot purchasing limited to emergency replenishment scenarios. Pricing stratifies across antimicrobial-coated premium variants, standard Tenckhoff configurations, and economy dual-lumen designs based on FDA 510(k) clearance tier and coating validation status. Cost compression in standard uncoated segments is intensifying because Medicare Advantage reimbursement parity eliminates site-of-care premiums. Dialysis centers exhibit highest price sensitivity due to volume consolidation pressures, while homecare providers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized silicone extrusion houses in Germany, Japan, and the United States that hold validated medical device production certifications. Raw material sourcing draws from platinum-cured silicone elastomers, radiopaque barium sulfate additives, and silver-ion antimicrobial agents. Single-source vulnerability pervades medical-grade polymer supply, with specialty chemical producers allocating capacity based on long-term contractual relationships. Distribution runs through integrated dialysis delivery platforms that bundle catheter supply with automated cycler equipment and consumable dialysate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as automated peritoneal dialysis cyclers and cloud-connected catheter monitoring systems converge into bundled service offerings that lock in recurring revenue streams.
For Market Incumbents: Harden antimicrobial coating capabilities through backward integration into silver-ion formulation chemistry or exclusive licensing arrangements with specialty material developers. Expand placement capacity by funding interventional nephrology fellowship programs at academic medical centers in Texas and Florida. Wearable hemodialysis prototypes threaten displacement in mobile patient segments.
For New Entrants and Emerging Players: Establish a beachhead in pediatric catheter applications where specialized diameter requirements and limited competitor presence create pricing power. Target rural United States geographies distant from dialysis center infrastructure where telemedicine-enabled homecare models reduce incumbent distribution advantages. Pursue FDA breakthrough device designation for novel insertion technologies to accelerate market access.
For Investors and Strategic Acquirers: FDA's updated antimicrobial device coating guidance reshapes the acquisition landscape by elevating pharmacovigilance infrastructure requirements and compressing competitive windows for coating-naive targets. Five-to-ten-year viability favors vertically integrated platform operators with captive dialysate supply and established GPO contracting relationships. Monitor quarterly FDA 510(k) clearance velocity for antimicrobial variants as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Platform Development | FDA guidance on coating validation compresses competitive windows for manufacturers lacking established silver-ion or antibiotic-impregnated surface technologies. |
| Telemedicine-Enabled Homecare Integration | Cloud-connected catheter monitoring systems bundled with automated cyclers create recurring revenue streams and reduce patient attrition. |
| Interventional Nephrologist Training Expansion | Percutaneous insertion capacity constraints limit placement volume; fellowship program funding secures preferred provider relationships. |
| Pediatric Application Portfolio Extension | Reduced-diameter catheter designs address underserved neonatal and adolescent segments with specialized clinical requirements and limited competition. |
| EU MDR Post-Market Surveillance Investment | German and French notified bodies enforce stringent pharmacovigilance obligations that drive consolidation among suppliers with limited vigilance infrastructure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, CMS Medicare reimbursement filings, and EU MDR notified body conformity assessments. Primary interviews engaged interventional nephrologists, hospital purchasing committee members, biomedical engineers at dialysis delivery platforms, GPO contracts managers, and regulatory affairs leads at catheter manufacturers. Bottom-up demand modeling triangulated against top-down market sizing derived from dialysis patient registry data and equipment installation records.
Forecast inputs include antimicrobial coating adoption curves, site-of-care migration rates under Medicare Advantage reimbursement structures, and silicone raw material allocation patterns across medical device producers. Segmentation dimensions encompass product type, end-user setting, coating technology tier, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical placement volumes adjusted for policy-driven modality shifts. Industry-specific inputs incorporate peritonitis incidence reduction targets and EU MDR transition timelines.
Sensitivities concentrate around FDA antimicrobial guidance implementation pace, specialty silicone supply allocation decisions, and wearable hemodialysis technology maturation. Forecasts reflect assumptions regarding reimbursement parity stability and regulatory clearance velocity. Quarterly review of FDA 510(k) submission volumes for coated variants and German notified body review queue depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Struts Implants Market
Medical Devices
Allografts Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
China General Surgical Devices Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
Cryoablation System Market
Medical Devices
Urinary Collection Device Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market
Medical Devices
Global Deep Brain Stimulation Devices Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Radiotherapy Positioning Devices Market