
 Medical Polyimide Tubing Market | 2026-2036
Medical Polyimide Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Polyimide Tubing Market Foresight
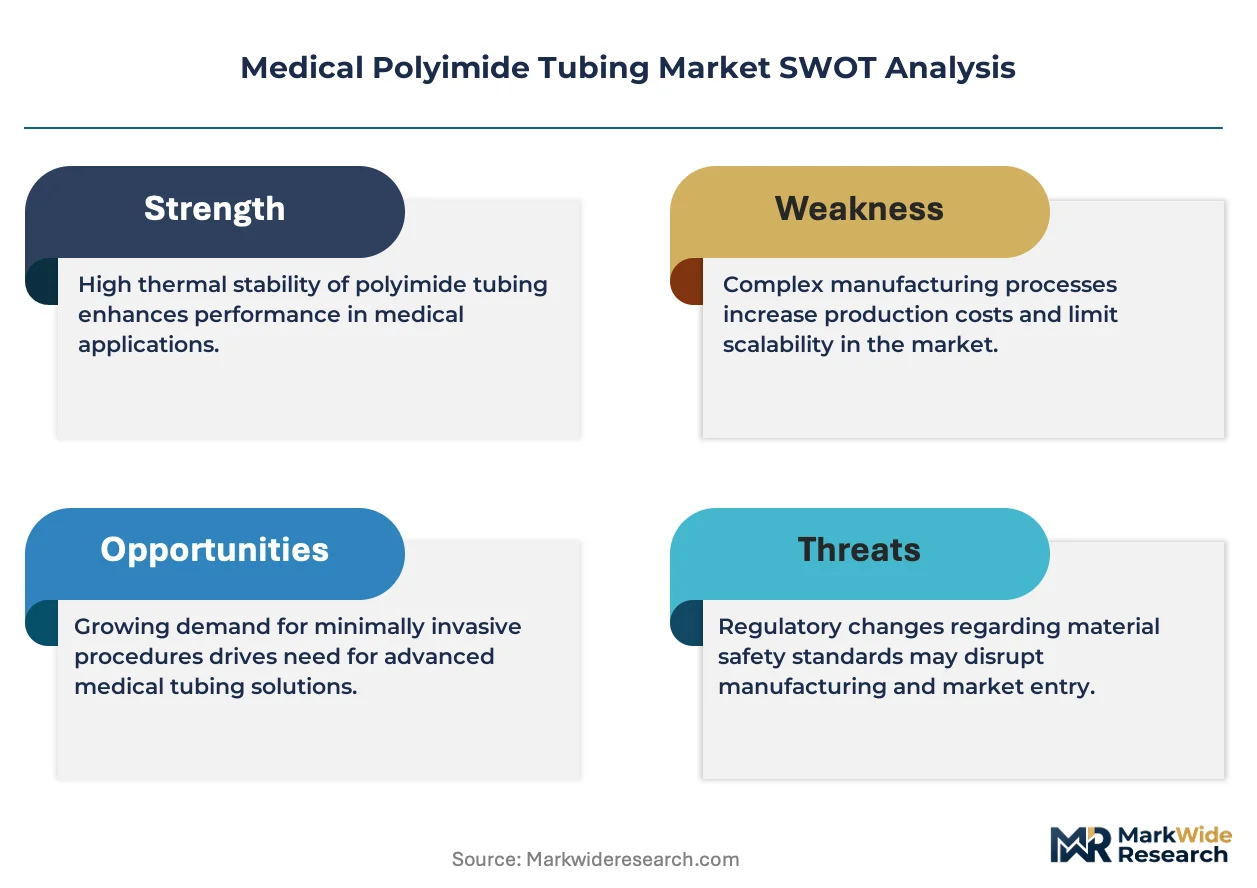
REACH compliance is broadening the cost-of-entry calculus for European suppliers of medical polyimide tubing. Zeus Industrial Products leverages vertical integration across resin compounding and precision extrusion to sustain cost discipline. Nordson Corporation anchors its position through advanced co-extrusion technology platforms. Furukawa Electric competes on geographic dominance in Asian catheter supply chains.
Medical polyimide tubing comprises high-performance thermoplastic extrusions with wall thicknesses routinely below 0.001 inch, engineered for thermal stability exceeding 400°C and dielectric strength critical to electrosurgical applications. Standard tubes occupy mature volume pools while multi-lumen configurations command premium positioning in neurovascular catheter architectures. Custom tubes represent the fastest-growing product type as OEMs specify proprietary lumen geometries for next-generation biopsy devices.
FDA 21 CFR Part 820 quality system regulations, EU MDR technical documentation requirements, and ISO 10993 biocompatibility standards collectively shape material selection and validation protocols for market access. The EU AI Act introduces emerging compliance dimensions for smart catheter systems incorporating sensor-integrated polyimide constructs. Stakeholders must monitor convergence between polymer innovation and evolving software-as-medical-device classifications.
Market Dynamics
Catheter OEM procurement consolidation around thin-walled specifications is compressing supplier margins while simultaneously filtering out non-specialized extrusion houses. This demand-side concentration forces tubing manufacturers to absorb validation costs or exit the medical tier entirely.
Growth Catalysts
- EU MDR technical documentation mandates:Device manufacturers now require batch-level material traceability, forcing tubing suppliers to upgrade quality systems and locking in preferred vendor relationships.
- Electrosurgical catheter expansion:Dielectric-grade polyimide formulations enable higher-frequency ablation platforms, pulling volume from PTFE alternatives in cardiac and oncology applications.
- Minimally invasive procedure migration:Neurovascular and peripheral interventions in the United States and Japan demand sub-millimeter lumen architectures that only precision polyimide extrusion delivers.
Market Restraints
- Monomer supply concentration:Pyromellitic dianhydride and 4,4'-oxydianiline feedstocks concentrate among Asian chemical producers, exposing converters to freight volatility and tariff exposure.
- ISO 10993-18 chemical characterization costs:Extractables and leachables testing for each resin lot adds twelve to eighteen weeks to qualification timelines, freezing smaller OEMs out of custom sourcing.
- PEEK and liquid crystal polymer substitution:High-temperature thermoplastics with comparable mechanical properties compete in non-electrical catheter shafts where dielectric performance is secondary.
Strategic Opportunities
- Sensor-integrated catheter architectures:Conductive ink deposition and embedded pressure transducers create demand for multi-layer co-extruded tubing with embedded conductive traces.
- India CDSCO manufacturing-linked incentives:The PLI scheme for medical devices attracts catheter assembly investment, creating localized demand for imported precision tubing with domestic finishing.
- Single-use endoscope channel tubing:Disposable duodenoscope and bronchoscope designs specify thin-walled polyimide for instrument channels, opening volume pools outside traditional vascular applications.
Industry Challenges
- Micro-extrusion operator scarcity:Process technicians capable of maintaining sub-0.001 inch wall tolerances command premium wages, constraining capacity expansion at mid-scale converters.
- FDA 510(k) predicate device drift:Evolving substantial equivalence standards for catheter tubing require renewed biocompatibility data, resetting validation clocks for legacy product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Polyimide Tubing Market |
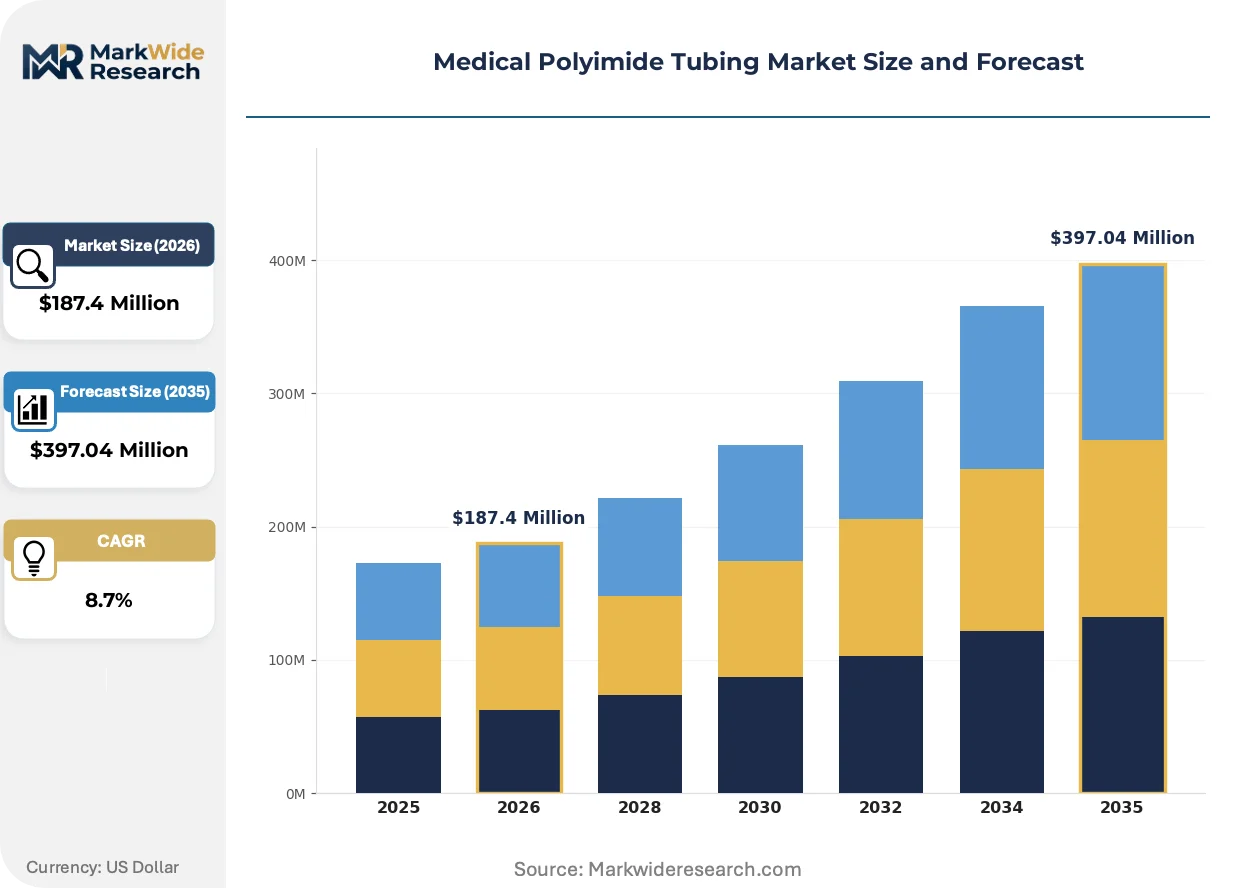
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tubes, Custom Tubes, Reinforced Tubes, Multi-lumen Tubes Application: Resistance Arms, Catheters, Biopsy Devices, Surgical Instruments End User: Hospitals, Clinics, Research Laboratories, Medical Device Manufacturers Manufacturing Stage: Extrusion, Co-extrusion, Thermal Treatment, Assembly |
| Companies Covered | Zeus Industrial Products, Inc., Nordson Corporation, Teleflex Incorporated, Furukawa Electric, MicroLumen, Inc., Putnam Plastics, HPC Medical Products, Duke Extrusion, Optima International AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Polyimide Tubing Market Shifts & Advancements
Multi-layer co-extrusion platforms are collapsing the traditional separation between structural and functional tubing layers, enabling device engineers to specify integrated performance in single-component designs. This convergence compresses bill-of-materials complexity while raising the technical barrier for suppliers.
Laser-ablated surface texturing is consolidating grip and lubricity performance into base polyimide substrates without secondary coating processes. Neurovascular catheter manufacturers adopt these modified surfaces to eliminate PTFE liner delamination risks in tortuous anatomy. The technology is consolidating supplier value capture by internalizing what previously required outsourced coating operations.
REACH SVHC candidate list expansion is forcing reformulation of traditional polyimide catalyst systems, particularly tin-based curing agents. European tubing converters must validate alternative chemistries or risk market exclusion, with neurovascular and pediatric device segments most exposed due to heightened biocompatibility scrutiny. Suppliers are responding with accelerated ISO 10993-5 cytotoxicity screening to front-load regulatory acceptance.
Device OEMs are consolidating vendor panels around tubing suppliers capable of delivering finished catheter sub-assemblies rather than commodity extrusion. This procurement compression favors converters with in-house tipping, flaring, and marker band swaging capabilities. The shift is most visible in United States catheter clusters where labor arbitrage for secondary operations has diminished.
Medical Polyimide Tubing Market Segmentation
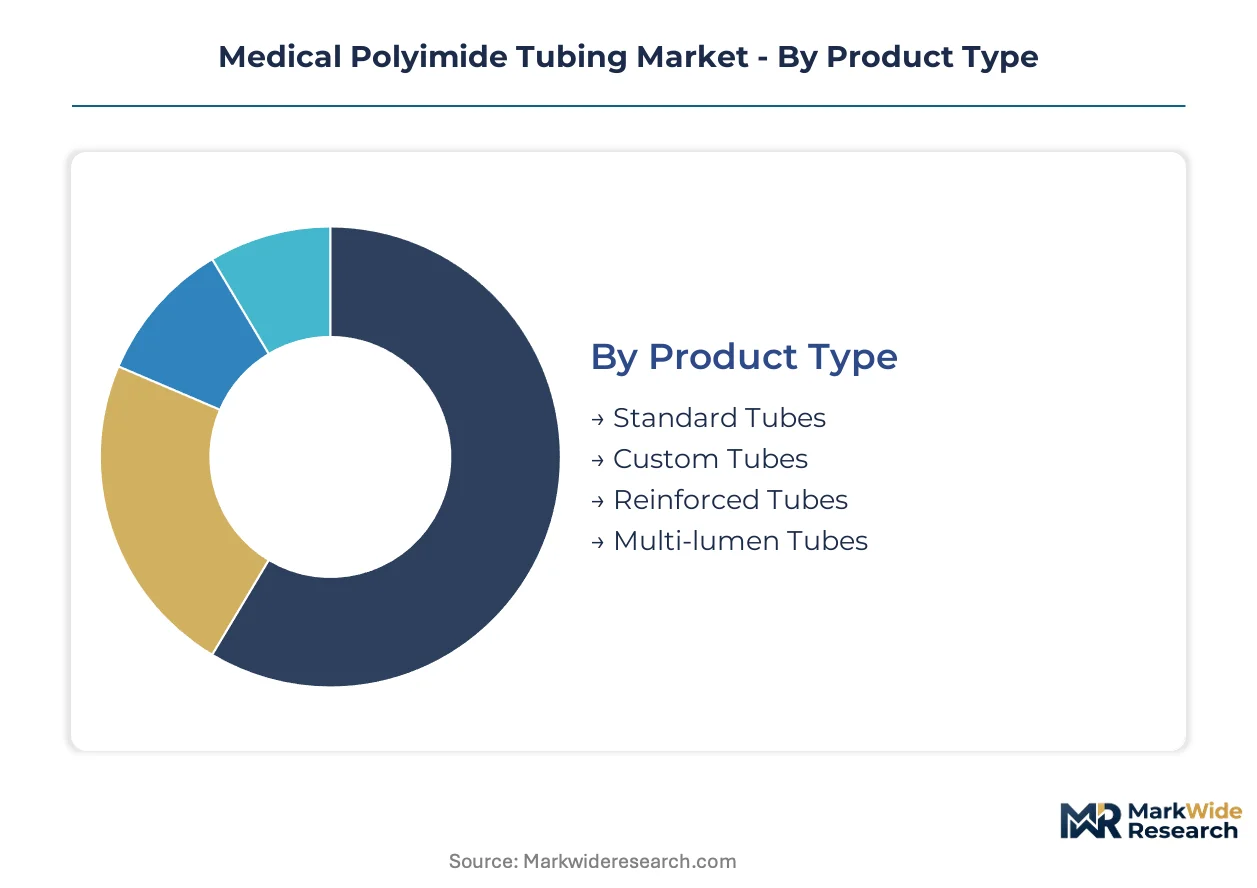
Medical polyimide tubing procurement splits sharply between commodity extrusion and precision-engineered configurations. OEM specification sheets now demand sub-millimeter tolerances that only segmented manufacturing capabilities can deliver.
Product Type:
Device engineers select tubing grade based on lumen complexity and regulatory validation burden.
- Standard Tubes:Single-lumen extrusions with fixed OD/ID ratios serve mature catheter platforms where design stability outweighs customization needs. Volume concentrates in United States cardiac catheter OEMs seeking validated, off-the-shelf supply for 510(k) predicate devices.
- Custom Tubes:Proprietary geometries with non-circular lumens and variable wall thickness enable next-generation biopsy forceps and aspiration catheters. German neurovascular device manufacturers drive specification intensity here, requiring batch-level material traceability under EU MDR Article 10.
- Reinforced Tubes:Braided or coiled wire-embedded constructions add torque response for interventional platforms.
- Multi-lumen Tubes:Parallel or concentric channel architectures consolidate irrigation, aspiration, and sensor pathways.
Volume sits with Standard Tubes; growth tilts toward Custom Tubes.
Application:
End-use specification determines dielectric grade, lubricity requirements, and sterilization compatibility.
- Catheters:Thin-walled polyimide shafts deliver dielectric insulation for electrosurgical ablation and structural support for balloon-mounted stent delivery. Japanese PMDA-registered manufacturers specify these for peripheral and coronary interventions where thermal stability exceeds 400°C.
- Biopsy Devices:Custom-lumen tubing integrates specimen collection channels with stylet guidance systems. United States pathology device OEMs source here for next-generation soft-tissue acquisition platforms requiring sub-millimeter cutting windows.
- Resistance Arms:Thermally stable positioning structures for robotic surgical systems.
- Surgical Instruments:Insulated handles and shafts for electrosurgical pencils and forceps.
Catheters command the largest revenue pool; biopsy applications are climbing the fastest.
End User:
Procurement authority and volume scale diverge sharply across the customer base.
- Medical Device Manufacturers:Catheter and endoscope OEMs dominate order books with multi-year supply agreements, captive quality audits, and dedicated extrusion line reservations. CDSCO-registered assembly operations in India increasingly source precision tubing for export-oriented production.
- Hospitals:Large academic medical centers in Germany and Japan specify polyimide-lined instrument channels for single-use endoscope programs.
- Clinics:Outpatient procedural volumes pull standard-grade tubing for disposable instrument kits.
- Research Laboratories:Preclinical device development drives small-batch custom orders with extended qualification timelines.
Medical Device Manufacturers absorb the heaviest volume; Research Laboratories show the steepest expansion trajectory.
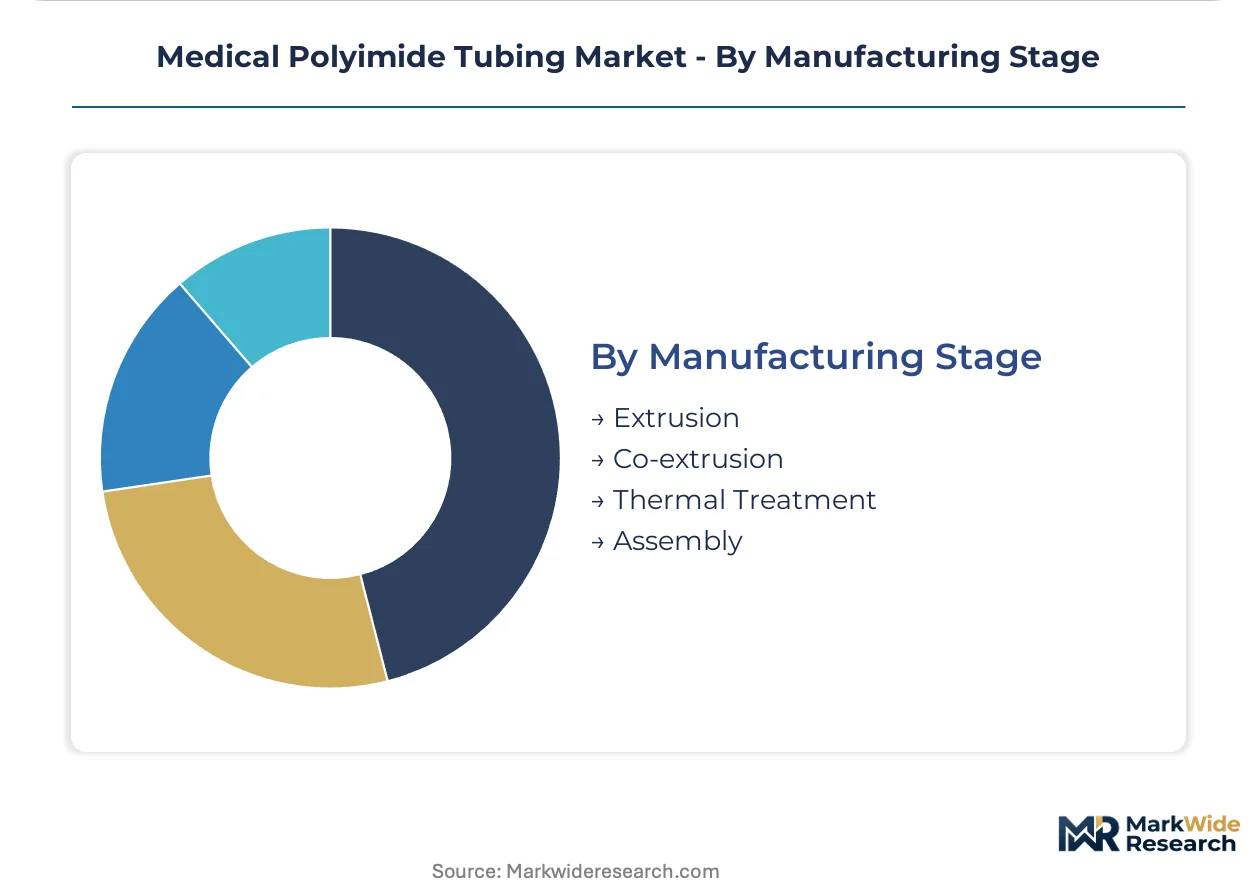
Manufacturing Stage:
Process capability separates commodity converters from qualified medical suppliers.
- Extrusion:Single-layer precision extrusion with wall thickness below 0.001 inch remains the foundational capability, with FDA-registered facilities in the United States and Japan holding preferred vendor status for Class II device supply.
- Co-extrusion:Multi-layer platforms bond dissimilar polymers for integrated lubricity or radiopaque marker bands. German converters lead here with in-house compounding tied to REACH-compliant catalyst systems.
- Thermal Treatment:Annealing and stress-relief processes stabilize dimensional tolerances.
- Assembly:Secondary tipping, flaring, and marker band swaging convert raw tubing into finished catheter sub-assemblies.
Extrusion locks in the highest throughput; co-extrusion gains share fastest as multi-layer designs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Puerto Rico concentrate catheter assembly operations, pulling precision polyimide tubing through bonded warehouse arrangements. These tax-advantaged manufacturing enclaves anchor North American supply chains while FDA-registered facilities in the United States maintain quality oversight.
United States
Minimally invasive procedure volumes in cardiac and neurovascular segments drive specification intensity for sub-millimeter tubing. FDA 21 CFR Part 820 quality system regulations mandate batch-level traceability, favoring suppliers with validated extrusion lines. Minneapolis and Boston medical device clusters host catheter OEMs that reserve dedicated capacity at preferred tubing converters.
Germany
EU MDR technical documentation requirements under Article 10 force material characterization upgrades for neurovascular device supply. REACH SVHC candidate list expansion is driving reformulation of catalyst systems in polyimide resin production. The Baden-Württemberg precision engineering corridor hosts converters with in-house compounding tied to compliant chemistries.
Japan
PMDA-registered manufacturers specify thin-walled polyimide for peripheral and coronary interventions requiring thermal stability above 400°C. METI industrial policy supports domestic catheter production through supply chain security initiatives. The Kanagawa and Osaka prefecture clusters concentrate electrosurgical device assembly with captive tubing finishing.
India
CDSCO manufacturing-linked incentives under the PLI scheme for medical devices attract catheter assembly investment for export markets. DGFT bonded warehousing provisions enable duty-free import of precision tubing with domestic secondary operations. Karnataka and Telangana emerging device parks are qualifying imported polyimide for finished catheter export.
Switzerland
Swissmedic regulatory alignment with EU MDR enables seamless market access for precision tubing qualified under European standards. The country's pharmaceutical and medtech clusters in Basel and Zurich specify high-reliability polyimide for robotic surgical instrument channels. Swiss converters leverage proximity to German resin suppliers while maintaining independent quality certifications.
Medical Polyimide Tubing Market Competitive Landscape
United States producers anchor one tier; Japanese and German specialists hold differentiated positions in electrosurgical and neurovascular grades. The supplier base concentrates around three strategic archetypes: vertically integrated resin-to-extrusion houses, precision micro-extrusion boutiques, and diversified industrial conglomerates with medical divisions. Consolidation pressure favors converters with in-house tipping and marker band swaging capabilities. Competitive moves center on co-extrusion technology licensing and geographic expansion into Costa Rican and Indian assembly zones.
Among North American fabricators, Zeus Industrial Products, Inc. and Nordson Corporation occupy positions as scale-oriented suppliers with integrated manufacturing footprints. Furukawa Electric represents the Asia-Pacific specialist archetype with regional supply chain proximity. These named entities exemplify the geographic and capability segmentation that defines competitive positioning, with each converter type serving distinct OEM procurement tiers based on validation depth and secondary operation breadth.
| Leading Market Players |
|---|
| Zeus Industrial Products, Inc. |
| Nordson Corporation |
| Teleflex Incorporated |
| Furukawa Electric |
| MicroLumen, Inc. |
| Putnam Plastics |
| HPC Medical Products |
| Duke Extrusion |
| Optima International AB |
| Others |
Supply & Pricing Matrix
REACH SVHC candidate list expansion gates qualified supply and premium-tier pricing access for European medical polyimide tubing converters. OEMs seeking MDR-compliant material traceability now face bifurcated sourcing economics where validated batch-level documentation commands substantial premiums over commodity extrusion.
Pricing Analysis
Lead-time-driven pricing stratification rewards expedited delivery with premiums while spot inventory liquidates at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and customization intensity. ISO 10993-18 chemical characterization costs are compressing margins at the custom tier. Research laboratories exhibit highest price sensitivity; catheter OEMs with captive line reservations show lowest.
Supply Chain Analysis
FDA 510(k) and EU MDR qualification gating concentrates approved supply among United States, German, and Japanese converters with validated extrusion lines. Pyromellitic dianhydride and 4,4'-oxydianiline feedstocks draw from Asian chemical producers. Single-source vulnerability in monomer supply exposes converters to freight volatility. Distribution runs through bonded warehouse arrangements serving Costa Rican and Indian assembly zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical polyimide tubing sits in a technology-transition phase as laser-ablated surface texturing displaces secondary PTFE coating processes. Device OEMs now specify integrated performance in single-component designs.
For Market Incumbents: Anticipate PEEK and liquid crystal polymer substitution threats in non-electrical catheter shafts by deepening co-extrusion capabilities for sensor-integrated architectures. Lock in preferred vendor status through captive quality audits and dedicated extrusion line reservations. Absorb ISO 10993-18 validation costs to filter out mid-scale competitors.
For New Entrants and Emerging Players: Capture white-space in India's CDSCO-registered catheter assembly corridors where PLI incentives attract export-oriented investment. Target single-use endoscope channel tubing outside traditional vascular applications. Lead with REACH-compliant catalyst formulations to bypass European market exclusion risks.
For Investors and Strategic Acquirers: FDA 510(k) predicate device drift requiring renewed biocompatibility data is the leading indicator that validation depth will separate acquireable assets from stranded capacity. Five-to-ten year viability hinges on backward integration into resin compounding or downstream assembly capabilities. Watch for micro-extrusion operator scarcity signals as capacity constraint indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-extrusion Technology Licensing | Multi-layer platforms bond dissimilar polymers for integrated sensor pathways in neurovascular catheters. |
| REACH-compliant Catalyst Reformulation | Alternative chemistries replace tin-based curing agents to maintain European market access under SVHC expansion. |
| Geographic Expansion into Indian Assembly Zones | CDSCO-registered operations in Karnataka and Telangana qualify imported tubing for finished catheter export. |
| Secondary Operations Integration | In-house tipping, flaring, and marker band swaging convert raw extrusion into finished catheter sub-assemblies. |
| Sensor-integrated Tubing Development | Embedded conductive traces enable smart catheter systems subject to EU AI Act compliance dimensions. |
Research Methodology
Independent corroboration across catheter OEM procurement directors, biomedical engineers at academic medical centers, and regulatory affairs specialists at notified bodies underwrites the qualitative findings in this study. Primary interviews with extrusion process technicians and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and customs trade data. Bottom-up tubing volume estimates triangulated against top-down catheter production forecasts.
Rate-of-change decomposition across the analysis window separates volume growth from mix-shift effects and pricing dynamics. Segmentation dimensions modeled include product type complexity, application dielectric requirements, end-user procurement authority, and manufacturing stage capability. CAGRs derived from regression against minimally invasive procedure migration rates and electrosurgical platform expansion trajectories. Forecast inputs incorporate PMDA-registered manufacturer specifications and METI supply chain security initiatives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to monomer supply concentration and evolving substantial equivalence standards. Model outputs reflect assumptions regarding REACH SVHC list expansion timing and ISO 10993-18 testing duration. A model refresh is warranted upon material change in FDA predicate device drift patterns or CDSCO PLI scheme modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
ETCO2 Masks Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
PPG Biosensors Market
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Polyethersulfone Dialyzer Market