
 Electronic Skin Patch Market | 2026-2036
Electronic Skin Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Skin Patch Market Foresight
Flexible hybrid electronics integration is rewriting the manufacturing economics of epidermal interfaces, replacing rigid silicon substrates with polyimide and silver nanowire composites that conform to skin topography. Abbott leverages vertical integration from glucose-sensing chemistry to cloud analytics, sustaining full-stack control over diabetic patient workflows. Dexcom, Inc. anchors the continuous glucose monitoring segment through proprietary factory calibration algorithms that eliminate fingerstick requirements. Medtronic competes across multiple therapeutic domains, extending its cardiac rhythm portfolio into patch-based ambulatory electrocardiography.
Electronic skin patches constitute thin, conformable devices incorporating biocompatible substrates, conductive traces, and transduction elements that interface directly with the integumentary system for physiological signal acquisition or active substance delivery, typically operating at sub-millimeter thicknesses with moisture-vapor transmission rates exceeding 500 g/m²/day to prevent dermal maceration during extended wear. Their primary commercial purpose centers on ambulatory health monitoring and closed-loop therapeutic intervention outside institutional settings. Wearable Sensors dominate current revenue pools due to established reimbursement for cardiac and metabolic indications, while Therapeutic Interfaces represent the fastest-expanding category as iontophoretic and microneedle delivery platforms advance through clinical validation. Flexible Electronics leads technology adoption through mature roll-to-roll manufacturing, whereas Nanoelectronics commands premium positioning where graphene and carbon nanotube electrodes enable multiplexed biomarker detection.
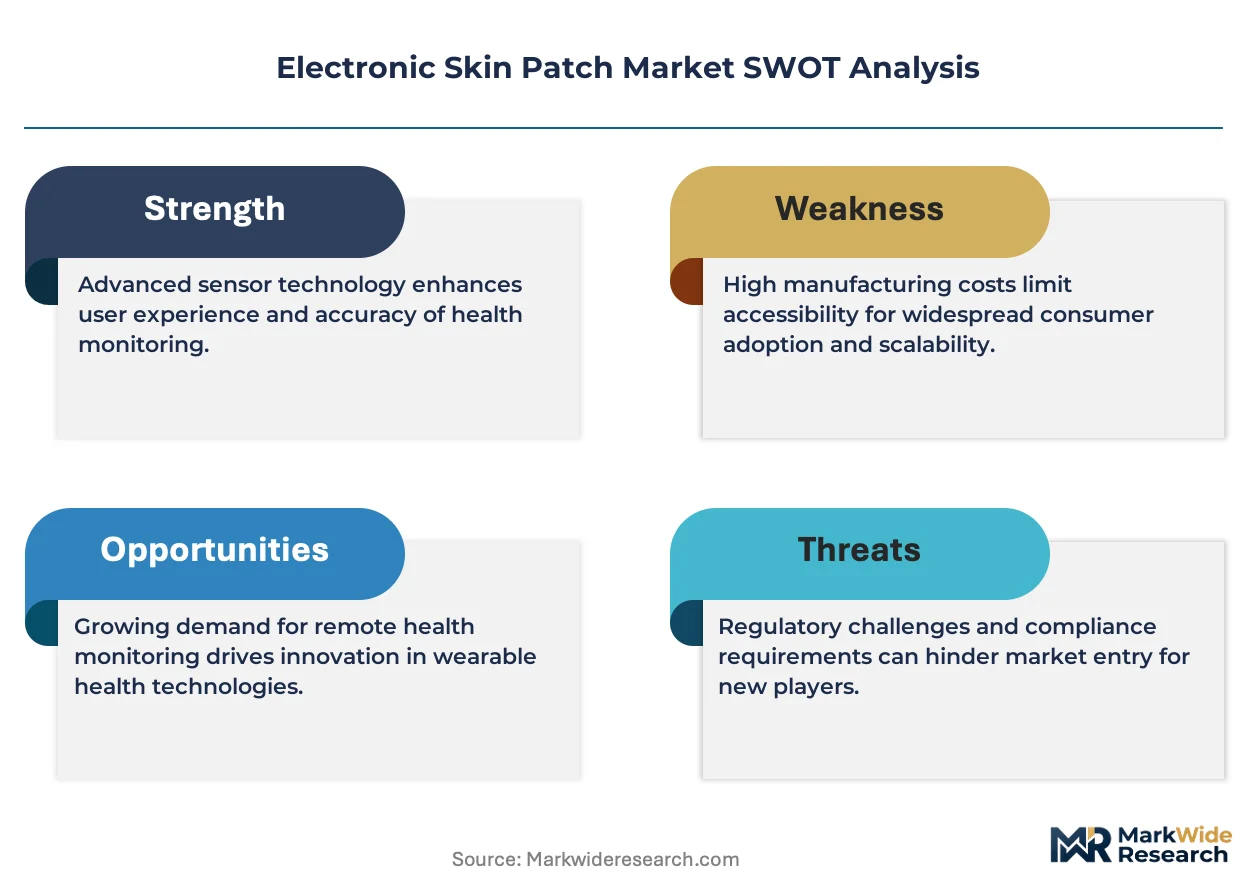
The FDA's software-as-a-medical-device framework and EU MDR classification rules for active implantable peripherals shape product development timelines and predicate device strategies for patch manufacturers seeking dual-territory approval. HIPAA data governance requirements and GDPR health data provisions constrain cloud architecture choices, forcing vendors to deploy edge computing or regional data residency models that increase infrastructure cost but unlock institutional procurement channels. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring as payors recalibrate fee schedules away from episodic clinic visits toward continuous digital biomarker streams.
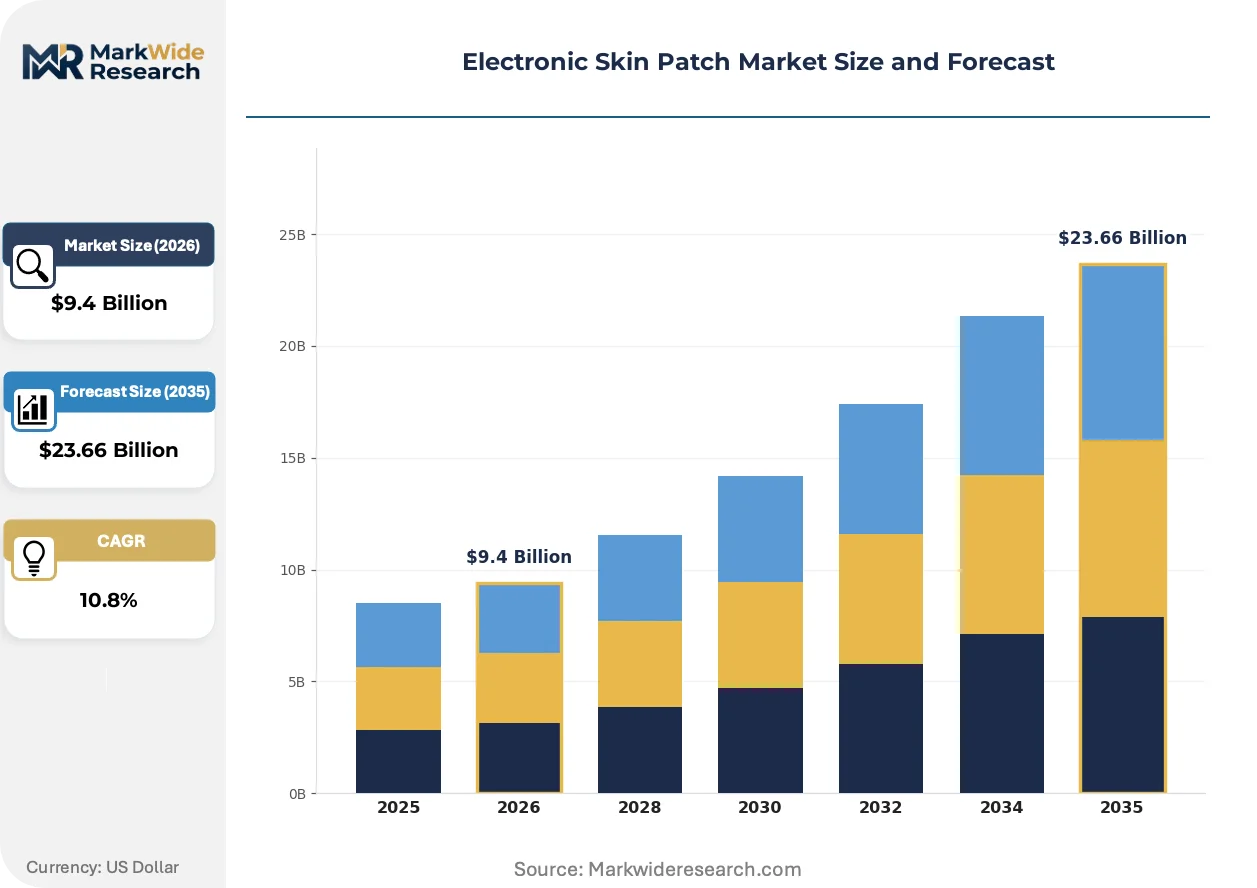
Market Dynamics
Flexible hybrid electronics manufacturing is compressing unit economics for conformable biosensors, enabling hospital systems to deploy continuous monitoring at outpatient scale rather than capital-intensive bedside equipment.
Growth Catalysts
- FDA Software-as-a-Medical-Device Pathway:The framework accelerates algorithm-driven patch clearances by treating analytics modules as discrete predicates, reducing predicate device search burdens for glucose and cardiac indications.
- Silver Nanowire-Polyimide Composites:These materials achieve sub-millimeter conformability with moisture-vapor transmission above 500 g/m²/day, solving dermal maceration barriers that previously limited wear duration.
- Germany Hospital System Expansion:Adhesive biosensor arrays are scaling across remote patient monitoring programs, with procurement concentrated in university hospital networks seeking to reduce readmission penalties.
Market Restraints
- GDPR Health Data Provisions:Cloud architecture constraints force regional data residency deployments, adding infrastructure cost that locks out smaller vendors from institutional procurement channels.
- Silver Nanowire Supply Concentration:Synthesis capacity clusters among East Asian chemical processors, exposing patch manufacturers to input volatility when electronics demand cycles tighten.
- Reimbursement Code Lag:Remote therapeutic monitoring fee schedules remain tethered to episodic clinic visit models, compressing margin realization for continuous biomarker streaming services.
Strategic Opportunities
- Iontophoretic Delivery Platforms:Therapeutic interfaces represent white space as microneedle and active transdermal systems advance through clinical validation for hormone and vaccine administration.
- Japan Preventive Healthcare Funding:METI subsidies for domestic wearable manufacturing create captive demand for epidermal monitoring devices in aging prefectures with physician shortage.
- Edge Computing Convergence:On-patch inference chips paired with low-power wide-area networks enable real-time arrhythmia detection without cloud latency, opening ambulatory cardiac monitoring to rural populations.
Industry Challenges
- Biocompatibility Certification Timelines:ISO 10993 cytotoxicity and sensitization testing for novel substrate chemistries extends development cycles by 18-24 months before predicate device alignment.
- Interoperability with Legacy EHR Systems:HL7 FHIR integration requires custom middleware development for each hospital network, fragmenting deployment economics and delaying revenue recognition.
- Roll-to-Roll Manufacturing Talent Scarcity:Process engineering expertise for high-throughput flexible electronics concentrates in display industry veterans, creating recruitment competition with OLED manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Skin Patch Market |
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $23.66 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Monitoring Systems, Diagnostic Devices, Therapeutic Interfaces Technology: Flexible Electronics, Stretchable Circuits, Nanoelectronics, Biocompatible Materials Application: Chronic Disease Management, Fitness Tracking, Pain Management, Post-operative Care End User: Hospitals, Clinics, Individual Consumers, Research Institutions |
| Companies Covered | Abbott, Dexcom, Inc., Medtronic, Insulet Corporation, Boston Scientific Corporation, VitalConnect, iRhythm Technologies, Biolinq Incorporated, GENTAG, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Skin Patch Market Shifts & Advancements
Convergence between materials science and clinical workflow integration is redefining how epidermal devices transition from pilot deployments to reimbursed standard-of-care.
Graphene and carbon nanotube electrodes are hybridizing multiplexed biomarker detection capabilities into single-patch architectures. Research hospitals in oncology and nephrology are piloting these platforms for simultaneous metabolite and electrolyte tracking. The technology is hybridizing premium positioning strategies, compressing the addressable market for single-analyte silicon-based alternatives.
EU MDR classification rules for active implantable peripherals are extending predicate device requirements to algorithm-driven patches. Manufacturers must now demonstrate clinical equivalence for software updates, forcing modular hardware architectures that isolate sensing elements from processing layers. Cardiac rhythm monitoring patches face the steepest compliance burden, with notified body backlogs extending clearance timelines.
Hospital procurement committees are consolidating vendor relationships around full-stack glucose monitoring ecosystems rather than discrete hardware purchases. Integrated platforms combining adhesive sensors, mobile applications, and cloud analytics are displacing point-solution contracts. This concentration is most visible in United States integrated delivery networks, where pharmacy benefit managers negotiate exclusive formulary placement for continuous monitoring systems.
Electronic Skin Patch Market Segmentation
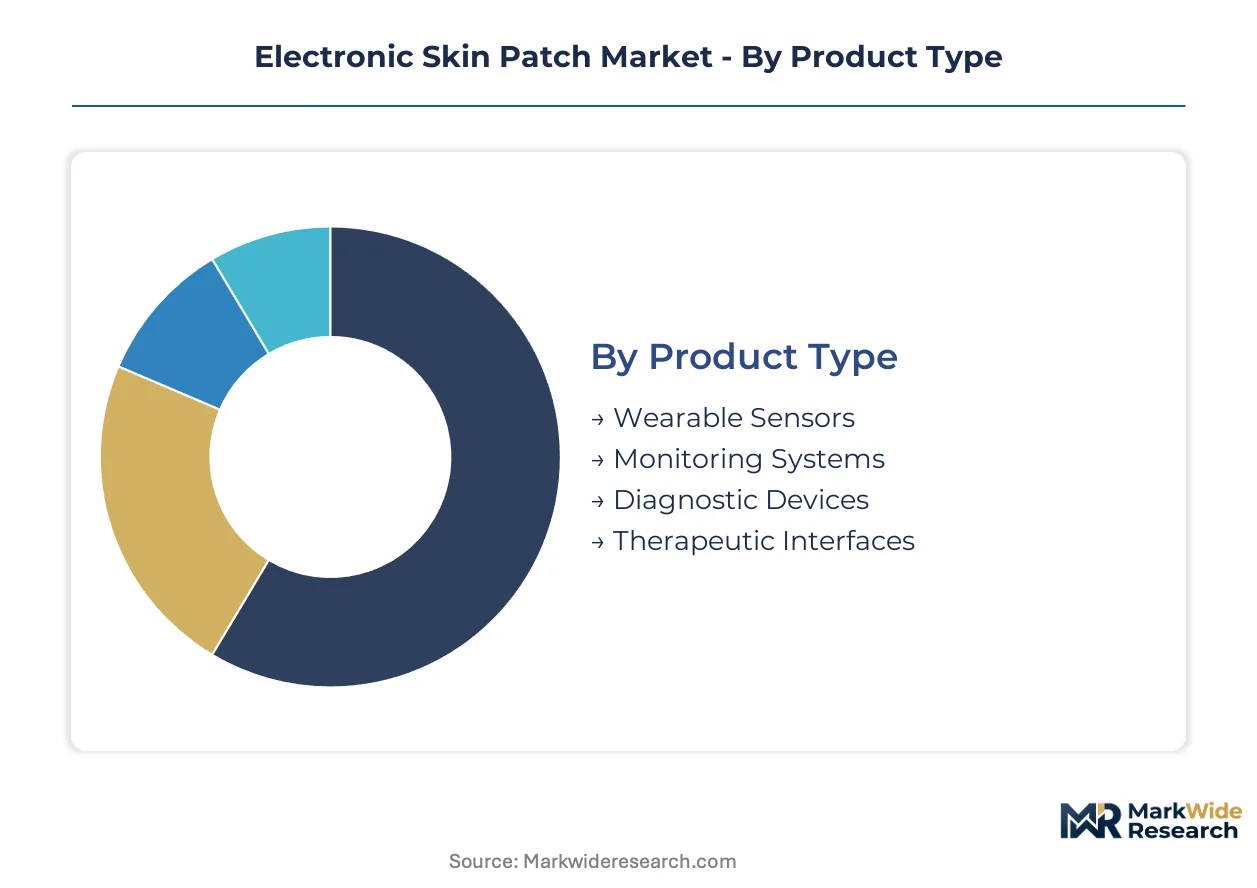
Electronic skin patch manufacturers configure service architectures around patch replacement cycles and data subscription tiers. Wear duration and sensor calibration requirements create distinct aftermarket revenue streams across each product category.
Product Type:
After-sales intensity varies sharply across product categories, with continuous monitoring systems demanding cloud analytics subscriptions and periodic adhesive replenishment that therapeutic patches rarely require.
- Wearable Sensors:These devices integrate biocompatible substrates with conductive traces for physiological signal acquisition, typically operating at sub-millimeter thicknesses. Hospital systems in Germany deploy adhesive biosensor arrays for remote patient monitoring, with procurement concentrated in university hospital networks seeking readmission penalty reductions. Abbott and Dexcom, Inc. dominate this segment through proprietary factory calibration algorithms.
- Therapeutic Interfaces:Iontophoretic and microneedle delivery platforms enable active substance delivery through the integumentary system. Japan's METI funding for preventive healthcare wearables drives domestic manufacturing scale for hormone and vaccine administration applications. These platforms represent white space as clinical validation advances.
- Monitoring Systems:Closed-loop architectures combining sensing with algorithm-driven alerts for cardiac rhythm or metabolic excursions.
- Diagnostic Devices:Single-use or limited-wear patches for acute event capture and clinical decision support.
By volume, Wearable Sensors leads. By growth pace, Therapeutic Interfaces is ahead.
Technology:
Cost tier stratification separates mature roll-to-roll manufacturing from premium nanomaterial platforms commanding multiplexed detection capabilities.
- Flexible Electronics:Roll-to-roll manufacturing of polyimide and silver nanowire composites achieves moisture-vapor transmission above 500 g/m²/day. Medtronic leverages this technology for patch-based ambulatory electrocardiography, with production economics enabling outpatient-scale deployment.
- Nanoelectronics:Graphene and carbon nanotube electrodes enable simultaneous metabolite and electrolyte tracking in single-patch architectures. Research hospitals in oncology and nephrology pilot these platforms, with premium positioning compressing addressable markets for silicon-based alternatives.
- Stretchable Circuits:Elastomeric substrates accommodating skin deformation during motion without signal degradation.
- Biocompatible Materials:ISO 10993-certified substrate chemistries resolving cytotoxicity and sensitization barriers.
Flexible Electronics commands installed base. Nanoelectronics claims the steepest expansion trajectory.
Application:
Customer type fragmentation splits procurement between institutional reimbursement channels and direct-to-consumer wellness spending.
- Chronic Disease Management:Continuous glucose monitoring and cardiac rhythm surveillance for diabetic and arrhythmia populations. The FDA's software-as-a-medical-device framework accelerates algorithm-driven patch clearances for glucose and cardiac indications.
- Post-operative Care:Wound monitoring and recovery tracking patches reducing clinic visit frequency. Germany's hospital system expansion targets readmission penalty reductions through adhesive biosensor arrays in surgical recovery protocols.
- Fitness Tracking:Consumer-grade hydration, lactate, and electrolyte monitoring for athletic optimization.
- Pain Management:TENS-integrated patches and iontophoretic analgesic delivery systems.
Chronic Disease Management generates the revenue base. Post-operative Care is gaining share fastest.
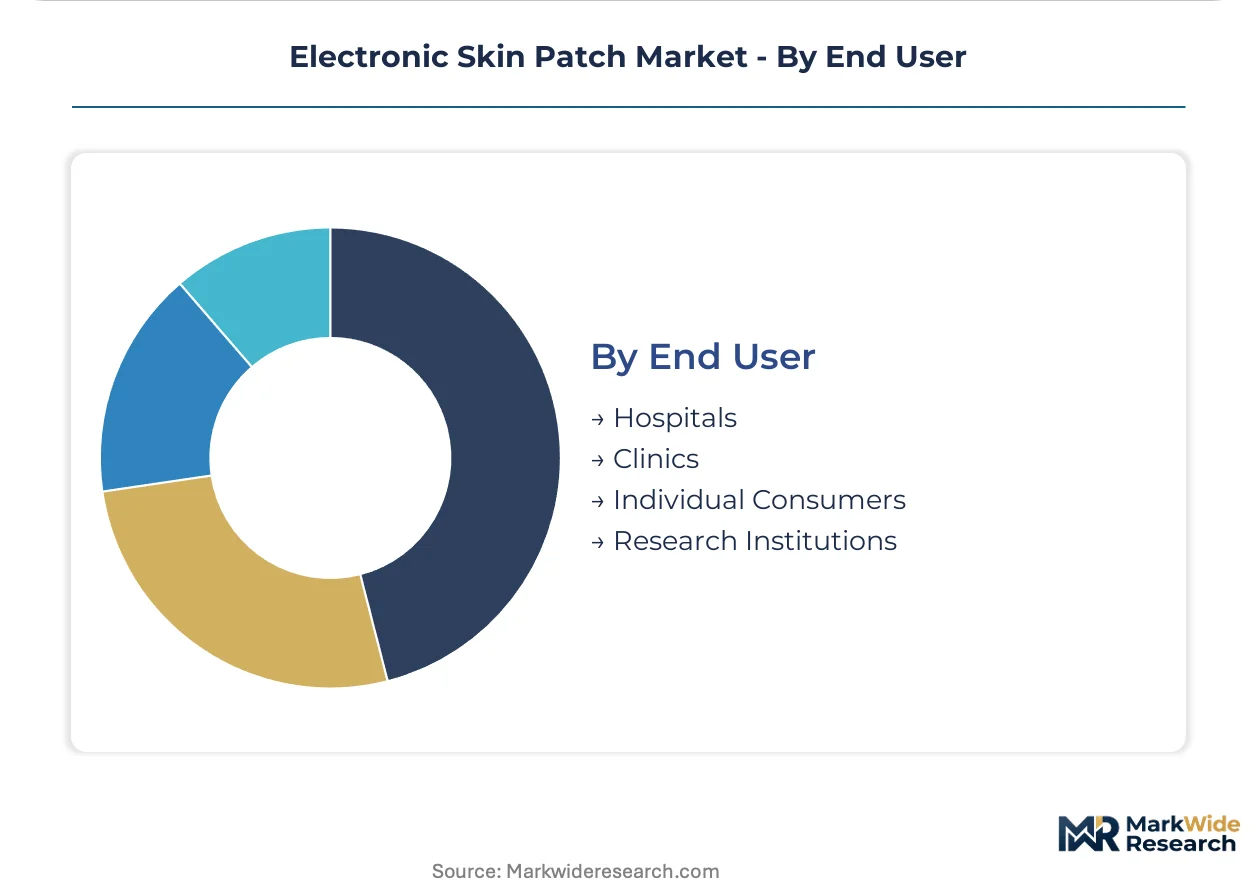
End User:
Supply concentration among display industry veterans creates recruitment competition affecting vendor service capabilities across institutional tiers.
- Hospitals:Integrated delivery networks in the United States consolidate vendor relationships around full-stack glucose monitoring ecosystems rather than discrete hardware purchases. Pharmacy benefit managers negotiate exclusive formulary placement for continuous monitoring systems.
- Clinics:Outpatient facilities requiring HL7 FHIR integration through custom middleware development for each network, fragmenting deployment economics.
- Individual Consumers:Direct-to-market fitness and wellness patch purchasers outside reimbursement channels.
- Research Institutions:Oncology and nephrology research hospitals piloting multiplexed biomarker detection platforms.
Hospitals anchor procurement volume. Research Institutions show the fastest adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German adhesive biosensor manufacturers export remote patient monitoring systems to United States integrated delivery networks, while Japanese patch producers supply METI-funded preventive healthcare programs across aging prefectures facing physician shortages.
United States
Hospital procurement committees consolidate vendor relationships around full-stack glucose monitoring ecosystems rather than discrete hardware purchases. The FDA's software-as-a-medical-device framework accelerates algorithm-driven patch clearances by treating analytics modules as discrete predicates. Greater Boston anchors cardiac rhythm monitoring patch development, with research hospitals piloting multiplexed biomarker detection platforms.
Germany
University hospital networks expand adhesive biosensor arrays across remote patient monitoring programs seeking readmission penalty reductions. EU MDR classification rules for active implantable peripherals extend predicate device requirements to algorithm-driven patches, forcing modular hardware architectures. Baden-Württemberg concentrates flexible hybrid electronics manufacturing talent from display industry veterans.
Japan
METI funding for preventive healthcare wearables drives domestic manufacturing scale for epidermal monitoring devices in aging prefectures with physician shortage. PMDA regulatory pathways align with software-as-a-medical-device frameworks for continuous glucose monitoring clearances. Kanto region hosts roll-to-roll manufacturing facilities producing silver nanowire-polyimide composites.
China
Silver nanowire synthesis capacity clusters among East Asian chemical processors, exposing patch manufacturers to input volatility when electronics demand cycles tighten. NMPA medical device classification rules govern adhesive biosensor clearances for cardiac and metabolic indications. Yangtze River Delta concentrates flexible electronics manufacturing infrastructure serving domestic hospital system procurement.
South Korea
Seoul Capital Area hospitals deploy edge computing convergence patches pairing on-patch inference chips with low-power wide-area networks for real-time arrhythmia detection. MFDS regulates software-as-a-medical-device frameworks for cloud-connected therapeutic interfaces. Busan-Ulsan corridor hosts biocompatible substrate chemistry facilities addressing ISO 10993 certification timelines.
Electronic Skin Patch Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. Hospital systems and pharmacy benefit managers favor full-stack vendors with captive cloud analytics, while research institutions source point-solution patches for pilot programs. Three archetypes dominate: vertically integrated glucose monitoring ecosystems, cardiac rhythm-focused device manufacturers, and flexible electronics substrate specialists. Competitive moves concentrate on strategic partnerships with hospital networks and technology licensing for roll-to-roll manufacturing processes.
Within the vertically integrated tier, Abbott and Dexcom, Inc. exemplify channel-controlling positioning through proprietary factory calibration algorithms and full-stack control over diabetic patient workflows. Medtronic occupies a diversified position spanning multiple therapeutic domains, extending cardiac rhythm portfolios into patch-based ambulatory electrocardiography. These three anchors represent distinct strategic postures: Abbott demonstrates backward integration from glucose-sensing chemistry to cloud analytics, Dexcom anchors continuous glucose monitoring through algorithm-driven patch clearances, and Medtronic leverages scale across cardiac and metabolic indications.
| Leading Market Players |
|---|
| Abbott |
| Dexcom, Inc. |
| Medtronic |
| Insulet Corporation |
| Boston Scientific Corporation |
| VitalConnect |
| iRhythm Technologies |
| Biolinq Incorporated |
| GENTAG, Inc. |
| Others |
Supply & Pricing Matrix
Shanghai-Rotterdam container freight corridors transmit silver nanowire input cost volatility into differentiated patch pricing tiers, with East Asian chemical processors commanding premium contract terms while European hospital procurement committees negotiate subscription-based glucose monitoring bundles that compress per-unit margins.
Pricing Analysis
Silver-indexed cost-plus contracts with quarterly price adjustments dominate raw material procurement for polyimide substrate manufacturers. Pricing stratifies across premium nanoelectrode patches, standard flexible electronics arrays, and economy-grade diagnostic disposables differentiated by ISO 10993 certification tier and cloud analytics bundling. Cost compression in the standard tier intensifies because hospital procurement committees consolidate vendor relationships around full-stack ecosystems. Research institutions show least price sensitivity for multiplexed biomarker detection platforms, while outpatient clinics face acute budget constraints for HL7 FHIR integration middleware.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for silver nanowire-dependent patch manufacturers. Synthesis capacity clusters in China, South Korea, and Japan, with Yangtze River Delta chemical processors feeding roll-to-roll manufacturing facilities in Baden-Württemberg and Kanto region. Polyimide substrate production draws from petrochemical feedstocks tethered to electronics demand cycles. Distribution runs through hospital procurement committees and pharmacy benefit manager formulary negotiations in integrated delivery networks, with direct-to-consumer wellness channels representing fragmented secondary volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electronic Skin Patch Market is recovering from reimbursement code lag cyclicality as remote therapeutic monitoring fee schedules gradually decouple from episodic clinic visit models, with Medicare Advantage plans piloting continuous biomarker streaming reimbursement.
For Market Incumbents: Harden cloud analytics subscription retention through proprietary factory calibration algorithm investments that increase patient workflow switching costs. Secure backward integration into silver nanowire-polyimide composite manufacturing to offset East Asian chemical processor concentration risk. Expand hospital system partnership density in Germany's university hospital networks before EU MDR notified body backlogs extend competitor clearance timelines. For New Entrants and Emerging Players: Pursue therapeutic interface white space in Japan's METI-funded preventive healthcare programs, where domestic manufacturing scale requirements create procurement preference for local patch producers. Target iontophoretic hormone delivery platforms in aging prefectures with physician shortage as the most penetrable application. Lead with edge computing convergence demonstrations that enable real-time arrhythmia detection without cloud latency to differentiate from established cardiac rhythm monitoring vendors. For Investors and Strategic Acquirers: Flexible electronics substrate specialists with ISO 10993 certification capabilities and existing roll-to-roll manufacturing talent represent the most defensible acquisition archetype in a five-to-ten year viability window. These assets command scarcity premiums as display industry veterans face recruitment competition from OLED manufacturers. Watch FDA software-as-a-medical-device framework expansion beyond glucose and cardiac indications as the signal indicating algorithm-driven patch valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Accelerates algorithm-driven patch clearances by treating analytics modules as discrete predicates. |
| Hospital System Partnership | Unlocks integrated delivery network procurement channels through pharmacy benefit manager formulary placement. |
| Backward Integration into Substrate Manufacturing | Captures polyimide and silver nanowire composite production economics from display industry talent pools. |
| Software Companion Development | Enables full-stack glucose monitoring ecosystems that displace point-solution hardware contracts. |
| Reimbursement Strategy | Aligns continuous biomarker streaming with remote therapeutic monitoring fee schedule evolution. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at patch manufacturers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up unit shipment estimates triangulated against top-down addressable population modeling across chronic disease management and post-operative care segments.
Calibration against historical glucose monitoring and cardiac rhythm patch adoption curves anchored volume projections across the analysis window. Segmentation dimensions modeled include product type, technology platform, application indication, and end-user procurement tier. CAGRs derived from slope-consistent growth trajectory fitting adjusted for reimbursement code lag effects. Industry-specific inputs incorporated silver nanowire supply capacity constraints and EU MDR clearance timeline extensions.
Sensitivities concentrate around FDA software-as-a-medical-device framework expansion pace, EU MDR notified body backlog resolution, and remote therapeutic monitoring reimbursement code finalization. Forecasts reflect documented assumptions regarding patient adherence rates and hospital procurement consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vein Finders Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Diabetes Devices Market
Medical Devices
Smart Stairlift Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Smart Vision Aids Market
Medical Devices
Gel Implants Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Incontinence Devices and Ostomy Market