
 Cryoablation System Market | 2026-2036
Cryoablation System Market Size, Share, and Industry Trends Forecast 2026-2036
Cryoablation System Market Insights
The EU Green Deal is rebalancing procurement criteria across European healthcare systems toward energy-efficient surgical platforms with reduced refrigerant footprints. Boston Scientific Corporation leverages its integrated electrophysiology portfolio to sustain catheter supply advantages in major cardiac centers. Medtronic anchors its position through proprietary cryoballoon technology that dominates pulmonary vein isolation procedures. IceCure Medical differentiates with percutaneous probe systems designed for interventional oncology applications outside cardiac care.
Cryoablation systems employ pressurized cryogens—typically nitrous oxide or argon—to generate controlled tissue necrosis through rapid freeze-thaw cycles, with probe tip temperatures reaching minus 40 to minus 60 degrees Celsius for precise ablation zone mapping. Cooling catheters command the largest revenue share due to recurring replacement cycles and disposable economics in cardiac electrophysiology labs. Transcatheter delivery modes are expanding fastest as interventional cardiologists shift toward minimally invasive atrial fibrillation protocols that reduce recovery times versus surgical alternatives.
The FDA maintains stringent 510(k) and PMA pathways for cryoablation devices, while the EU MDR demands expanded post-market surveillance and clinical follow-up data for Class III implantable instruments. ISO 13485 quality management certification shapes supplier qualification for original equipment manufacturers seeking access to regulated markets. Stakeholders must monitor evolving reimbursement codes for catheter ablation procedures across Medicare and major European health technology assessment bodies.
Market Dynamics
Catheter-based cardiac cryoablation platforms are consolidating procurement decisions inside specialized electrophysiology centers, compressing vendor access points and tightening technical specifications around integrated workstation ecosystems.
Growth Catalysts
- EU Green Deal procurement rebalancing:Healthcare systems across Germany, France, and Italy now prioritize energy-efficient surgical platforms with reduced refrigerant footprints, redirecting capital toward compliant cryoablation systems.
- Minimally invasive atrial fibrillation protocols:Interventional cardiologists in tertiary cardiac centers are abandoning surgical alternatives for transcatheter delivery modes that shorten patient recovery cycles.
- Post-market surveillance data requirements:The EU MDR's expanded clinical follow-up mandates for Class III devices are filtering out undercapitalized competitors and reinforcing positions of established cryoballoon manufacturers.
Market Restraints
- Pressurized cryogen supply concentration:Nitrous oxide and argon sourcing depends on a limited base of industrial gas suppliers concentrated in Central Europe, exposing electrophysiology labs to input cost volatility.
- 510(k) and PMA pathway stringency:The FDA's device approval timelines for novel probe geometries create multi-year commercialization gaps that freeze smaller developers out of the US market.
- Radiofrequency ablation substitution threat:Thermal competition from RF systems with shorter procedure times and lower per-case consumable costs pressures cryoablation expansion outside pulmonary vein isolation.
Strategic Opportunities
- Interventional oncology white space:Percutaneous probe systems for renal, lung, and liver tumor ablation remain underpenetrated in outpatient interventional radiology settings across Spain and Poland.
- ISO 13485 certification arbitrage:Contract manufacturers with quality management certification can capture OEM supply contracts as original device makers outsource non-core probe production.
- Integrated workstation convergence:Combining cryoablation with 3D electroanatomic mapping systems creates bundled procurement appeal for consolidating German electrophysiology centers seeking single-vendor relationships.
Industry Challenges
- Electrophysiologist training pipeline constraints:The specialized skill set for cryoballoon catheter navigation and ablation zone interpretation faces scarcity across European training programs, limiting procedure volume expansion.
- Legacy system integration friction:New cryoablation platforms must interface with existing patient monitoring networks and EMR architectures in established cardiac catheterization labs, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryoablation System Market |
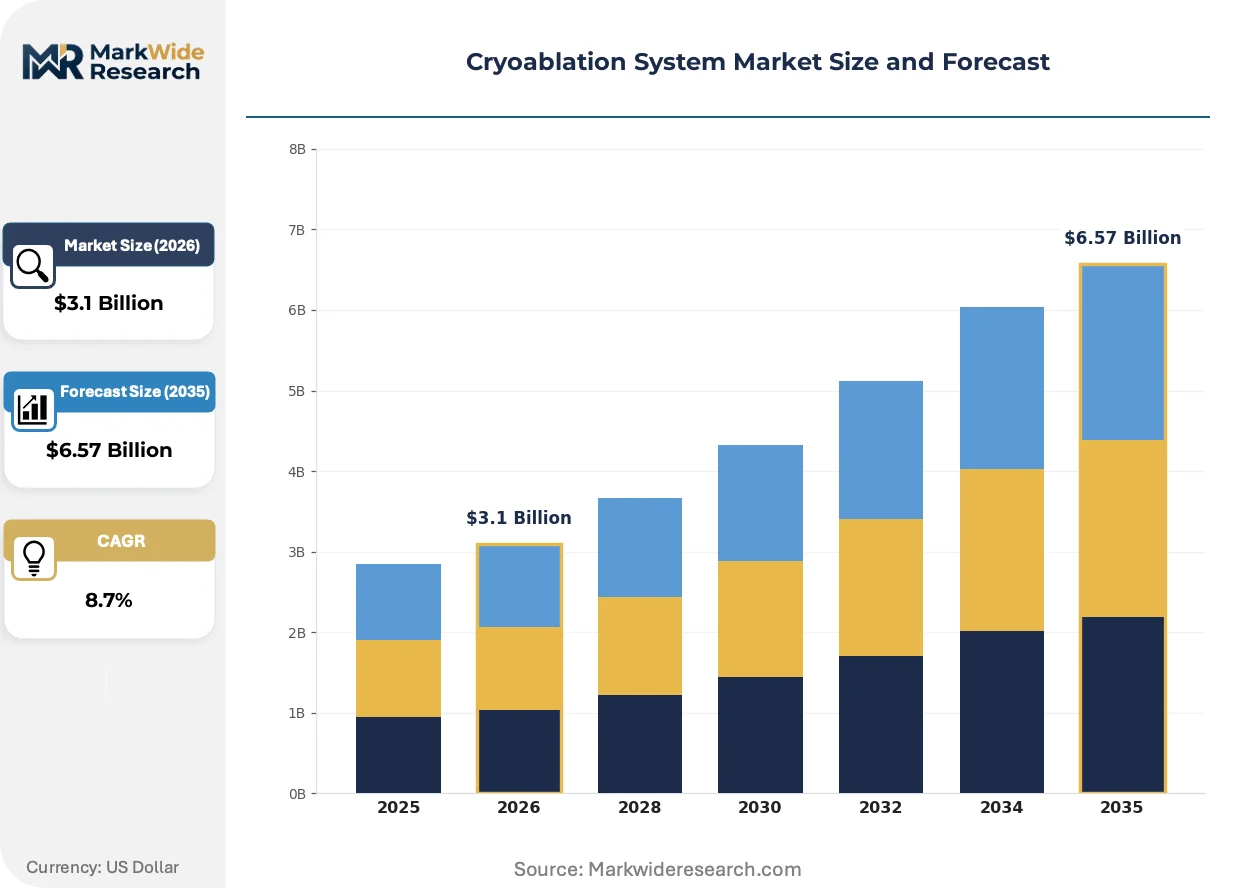
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Catheters, Cryoprobes, Cryoablation Systems, Accessories End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Cancer Treatment, Cardiac Ablation, Pain Management, Dermatology Delivery Mode: Intravenous, Intra-arterial, Percutaneous, Transcatheter |
| Companies Covered | Boston Scientific Corporation, Medtronic, MicroPort Scientific Corporation, CooperSurgical, AtriCure, CPSI Biotech, IceCure Medical, BVM Medical Limited, AngioDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryoablation System Market Trends and Innovations
Real-time tissue temperature monitoring and predictive ablation zone modeling are compressing the gap between procedural intention and clinical outcome, reshaping how electrophysiologists validate lesion completeness during cardiac interventions.
Cryoballoon catheter technology is absorbing computational ice formation modeling that maps thermal distribution across pulmonary vein ostia. Major cardiac centers in Germany and the Netherlands are adopting these enhanced platforms for complex atrial fibrillation cases. The structural consequence is that manual point-by-point cryoablation is absorbing procedural share only in anatomically variant cases, while standardized balloon designs capture routine isolation volumes.
The EU MDR's clinical evidence requirements for Class III cardiac devices are forcing manufacturers to maintain expanded post-market surveillance registries tracking long-term patient outcomes. This regulatory burden is compressing the competitive field to developers with sufficient capital reserves for multi-year follow-up studies. Cryoballoon systems with established safety databases are absorbing procurement preference in health technology assessment evaluations across France, Italy, and Belgium.
Hospital procurement committees are consolidating vendor relationships around integrated electrophysiology ecosystems rather than standalone device purchases. This behavioral shift is displacing point-product suppliers in favor of platform vendors offering catheter, mapping, and energy delivery compatibility. The concentration is most visible in German university hospitals where standardization across multiple catheterization labs reduces training overhead and inventory complexity.
Cryoablation System Market Segmentation
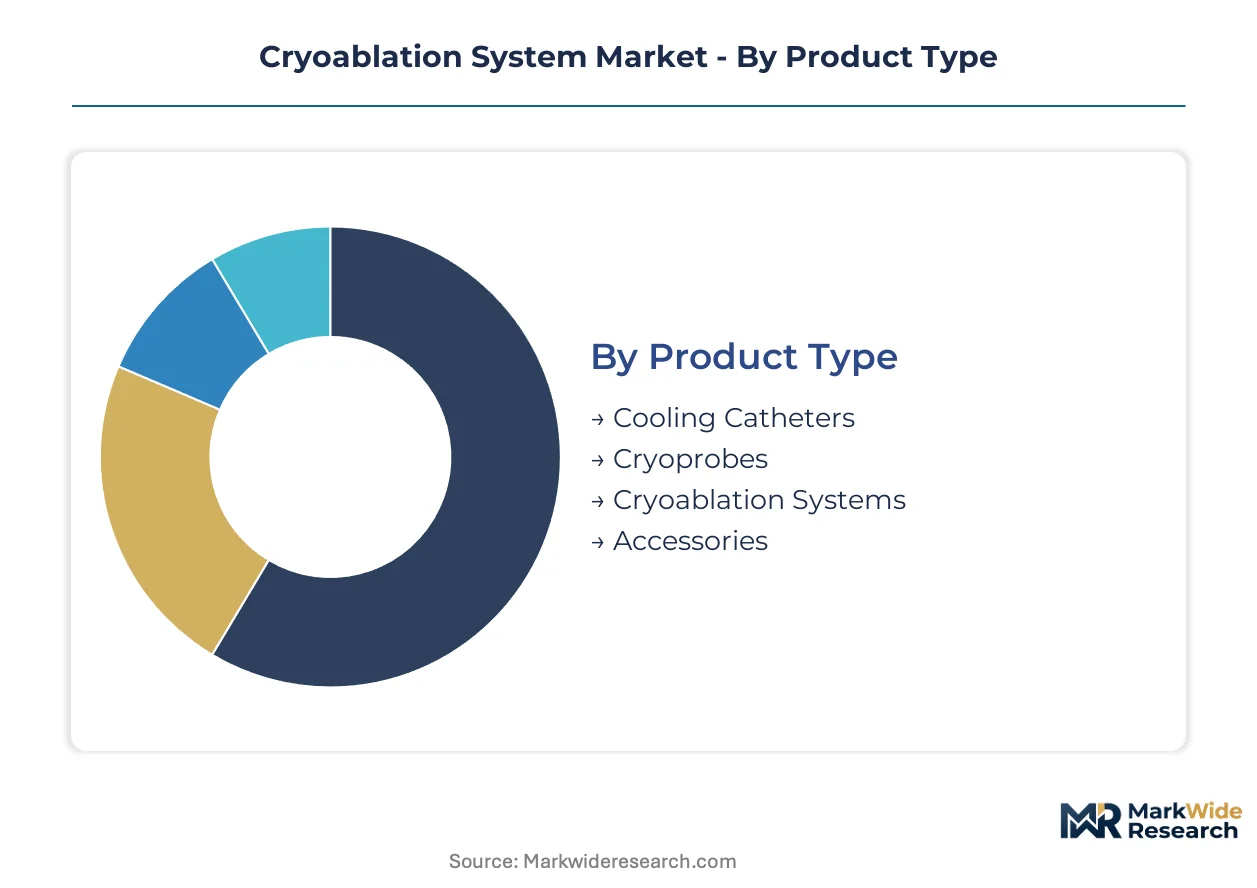
Cryoablation system segmentation reveals divergent economics across product categories, with disposable consumables driving recurring revenue against capital-intensive platform sales. Understanding these segment boundaries clarifies where procurement consolidation concentrates and where white-space opportunities persist for specialized entrants.
Product Type:
Cooling catheters command premium pricing through single-use economics, while cryoablation systems represent lumpy capital deployment with extended replacement cycles.
- Cooling Catheters:These disposable devices circulate pressurized cryogens through catheter lumens to achieve tip temperatures of minus 40 to minus 60 degrees Celsius. German electrophysiology centers are absorbing the highest volumes as pulmonary vein isolation procedures consolidate in tertiary cardiac hubs. The EU MDR's clinical evidence requirements for Class III devices are filtering procurement toward established cryoballoon manufacturers with established safety databases.
- Cryoprobes:Percutaneous probe systems deliver direct tissue contact freezing for interventional oncology applications outside cardiac care. Demand is concentrating in Spanish and Polish outpatient interventional radiology settings where renal, lung, and liver tumor ablation remains underpenetrated. IceCure Medical anchors this segment through specialized probe geometries designed for percutaneous access.
- Cryoablation Systems:Integrated workstation platforms combine cryogen delivery, temperature monitoring, and procedural navigation in capital-intensive installations.
- Accessories:Connecting tubing, pressure regulators, and disposable sheaths complete procedural setups with lower individual price points but steady replacement demand.
Today's leader: Cooling Catheters. Tomorrow's challenger: Cryoprobes.
End User:
Hospital procurement committees are consolidating vendor relationships around integrated electrophysiology ecosystems, compressing access points for standalone device suppliers.
- Hospitals:Tertiary cardiac centers in Germany and the Netherlands are standardizing cryoablation platforms across multiple catheterization labs to reduce training overhead and inventory complexity. These institutions absorb the highest procedure volumes for atrial fibrillation treatment through specialized electrophysiology departments.
- Ambulatory Surgical Centers:Outpatient settings in France and Belgium are adopting streamlined cryoablation protocols for lower-complexity cardiac cases with shorter recovery requirements. The EU Green Deal's energy-efficiency procurement criteria are redirecting capital toward compliant surgical platforms in these cost-sensitive environments.
- Specialty Clinics:Focused cardiac and oncology facilities concentrate expertise in high-volume procedural niches.
- Research Institutions:Academic medical centers maintain cryoablation capabilities for clinical trial enrollment and post-market surveillance studies mandated under EU MDR expanded follow-up requirements.
Hospitals capture current procurement concentration. Ambulatory Surgical Centers are climbing the fastest as minimally invasive protocols shift lower-acuity cases outpatient.
Application:
Cardiac ablation generates the steepest expansion trajectory as interventional cardiologists shift toward transcatheter delivery modes, while cancer treatment offers white-space penetration in interventional oncology.
- Cancer Treatment:Percutaneous cryoablation for renal, lung, and liver tumors employs probe-based systems distinct from cardiac catheter platforms. Spanish and Polish interventional radiology departments are expanding adoption as outpatient tumor ablation protocols mature.
- Cardiac Ablation:Pulmonary vein isolation for atrial fibrillation dominates cryoballoon utilization, with Medtronic's proprietary technology anchoring procedural standardization. German university hospitals are absorbing next-generation platforms with computational ice formation modeling for complex cases.
- Pain Management:Cryoneurolysis for chronic pain targets peripheral nerves with specialized probe geometries.
- Dermatology:Superficial cryoablation for skin lesions represents the most mature application with commodity competitive dynamics.
Cardiac Ablation leads current revenue concentration. Cancer Treatment represents the fastest-growing trajectory as interventional oncology white space converts to procedural volume.
Delivery Mode:
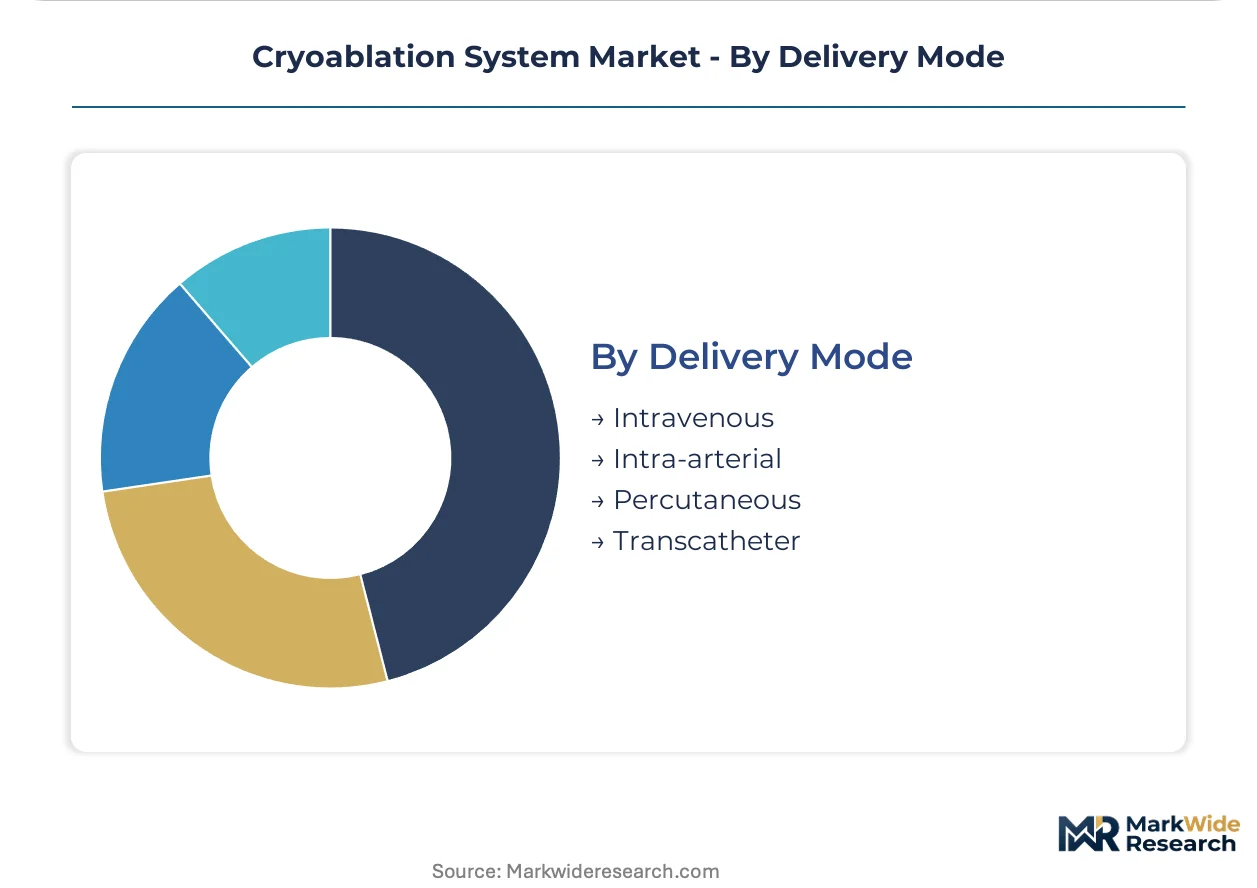
Transcatheter delivery is displacing surgical alternatives in atrial fibrillation treatment, while percutaneous access enables interventional oncology expansion outside cardiac care.
- Transcatheter:Cryoballoon catheters navigate vascular anatomy to achieve pulmonary vein isolation without thoracic surgery. Interventional cardiologists in German and Dutch tertiary centers are abandoning surgical alternatives for these minimally invasive protocols that compress patient recovery cycles.
- Percutaneous:Direct probe insertion through skin and tissue targets solid tumors in renal, hepatic, and pulmonary applications. This delivery mode is gaining share fastest in Spanish outpatient interventional radiology settings where tumor ablation protocols are standardizing.
- Intravenous:Vascular access through venous circulation supports specific cardiac anatomical approaches.
- Intra-arterial:Arterial catheterization enables selective organ targeting in specialized oncology applications.
Transcatheter delivery dominates cardiac volume. Percutaneous access is expanding most quickly as interventional oncology builds procedural infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryoablation technology originated in cardiac surgical suites across the United States and Germany during the 1990s, establishing clinical validation frameworks that now govern procurement standards worldwide. These founding markets continue to anchor procedural volume and regulatory precedent for device manufacturers.
Germany
Specialized electrophysiology centers in Berlin and Munich are consolidating procurement of integrated cryoablation workstations under the EU MDR's tightened clinical evidence requirements. The German Institute for Medical Documentation and Information enforces expanded post-market surveillance for Class III cardiac devices. University hospitals in Baden-Württemberg now standardize cryoballoon platforms across multiple catheterization labs to reduce training overhead.
United States
Tertiary cardiac centers in Cleveland and Boston absorb the highest volumes of catheter-based pulmonary vein isolation procedures for atrial fibrillation treatment. The FDA maintains stringent 510(k) and PMA pathways that create multi-year commercialization gaps for novel probe geometries. Major academic medical centers in Texas are expanding electrophysiology fellowship programs to address cryoballoon navigation skill scarcity.
France
Ambulatory surgical centers in Paris and Lyon are adopting streamlined cryoablation protocols for lower-complexity cardiac cases with shorter recovery requirements. The Haute Autorité de Santé evaluates health technology assessments that favor cryoballoon systems with established long-term safety databases. Procurement committees in Île-de-France prioritize energy-efficient surgical platforms aligned with EU Green Deal refrigerant footprint criteria.
Spain
Outpatient interventional radiology departments in Madrid and Barcelona are expanding percutaneous cryoablation for renal, lung, and liver tumor ablation. The Spanish Agency for Medicines and Health Products oversees device registration under harmonized EU MDR standards. Specialized oncology clinics in Catalonia are building procedural infrastructure for tumor ablation protocols previously confined to inpatient settings.
Netherlands
Cardiac centers in Amsterdam and Rotterdam are adopting next-generation cryoballoon platforms with computational ice formation modeling for complex atrial fibrillation cases. The Dutch Health and Youth Care Inspectorate monitors compliance with expanded clinical follow-up mandates for implantable instruments. University medical centers are consolidating vendor relationships around single-source electrophysiology ecosystems.
Cryoablation System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the cardiac electrophysiology value chain, with integrated workstation vendors capturing bundled procurement contracts while standalone catheter suppliers face pricing compression. The vendor base stratifies into three tiers: multinational platform developers with mapping system compatibility, specialized cryoballoon manufacturers with proprietary thermal distribution technology, and regional percutaneous probe suppliers serving interventional oncology niches. Dominant competitive moves include backward integration into cryogen supply partnerships and technology licensing agreements for temperature monitoring sensors.
Within the integrated platform tier, Boston Scientific Corporation and Medtronic occupy positions as archetypal full-system vendors, while IceCure Medical represents the specialized percutaneous probe segment. Boston Scientific Corporation leverages its electrophysiology portfolio breadth, Medtronic anchors cryoballoon standardization for pulmonary vein isolation, and IceCure Medical exemplifies focused differentiation outside cardiac care. These three entities collectively illustrate how competitive positioning fragments across procedural domains rather than consolidating under universal platform dominance.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| MicroPort Scientific Corporation |
| CooperSurgical |
| AtriCure |
| CPSI Biotech |
| IceCure Medical |
| BVM Medical Limited |
| AngioDynamics |
| Others |
Pricing and Supply Chain Analysis
Computational ice formation modeling in next-generation cryoballoon platforms is simultaneously elevating R&D amortization costs and concentrating procurement around integrated workstation vendors with captive cryogen supply partnerships. German university hospitals now absorb premium pricing for bundled electrophysiology ecosystems while Spanish outpatient clinics face compressed margins on standalone probe systems.
Pricing Analysis
Three-tier pricing structure across premium integrated workstations, standard catheter platforms, and economy probe systems governs procurement decisions. Price differentiation rests on ISO 13485 certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because industrial gas suppliers are passing through refrigerant cost volatility. Ambulatory surgical centers in France exhibit the highest price sensitivity, while German tertiary cardiac centers prioritize performance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Central European industrial gas suppliers concentrated in Germany and the Netherlands. Cryogen sourcing draws from a limited base of nitrous oxide and argon producers, with connecting tubing and pressure regulators as secondary dependencies. Tariff exposure on cryogen imports from non-EU sources threatens input cost stability. Distribution runs through specialized medical device distributors serving electrophysiology labs and interventional radiology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cryoablation system market compounds steadily as minimally invasive atrial fibrillation protocols displace surgical alternatives across European cardiac centers. Regulatory consolidation under EU MDR filters competition toward capitalized platform vendors.
For Market Incumbents: Extend cryoballoon technology leadership through backward integration into cryogen supply partnerships that neutralize input cost volatility. Deepen hospital system partnerships in Germany to lock out mapping system competitors before integrated workstation convergence completes. For New Entrants and Emerging Players: Enter via percutaneous probe systems for renal and liver tumor ablation in Spanish outpatient interventional radiology settings, where procedural infrastructure remains underbuilt. Pursue ISO 13485 certification arbitrage through contract manufacturing relationships with OEMs outsourcing non-core production. For Investors and Strategic Acquirers: Valuations sit cheapest among regional percutaneous probe suppliers with interventional oncology specialization outside cardiac care. The five-to-ten year viability thesis rests on cancer treatment application expansion outpacing cardiac market saturation. Watch health technology assessment body reimbursement decisions in France and Belgium as the signal for interventional oncology demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Pathway | Expanded post-market surveillance registries satisfy German Institute for Medical Documentation requirements. |
| Cryogen Supply Partnership | Captive sourcing agreements with Central European industrial gas producers neutralize refrigerant cost volatility. |
| Hospital System Partnership | Single-vendor relationships with Dutch university medical centers reduce training overhead across catheterization labs. |
| Software Companion Development | Real-time tissue temperature monitoring algorithms compress procedural intention-to-outcome gaps. |
| Reimbursement Strategy | Haute Autorité de Santé alignment secures favorable health technology assessment for cryoballoon systems. |
Research Methodology
Bottom-up electrophysiology lab modeling reconciled against top-down cryogen supply tracking forms the analytical core of this study. Primary interviews with interventional cardiologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers were validated against secondary sources including FDA 510(k) filings, EUDAMED device registrations, hospital procurement databases, and EU MDR guidance documents. Triangulation across these inputs ensures segmentation integrity.
Historical trendline analysis of catheter shipment volumes and cryoablation system installations established baseline growth patterns across the projection horizon. The forecast framework models product type, end user, application, and delivery mode dimensions with procedural volume and capital replacement cycle inputs. CAGRs were derived from weighted average growth across these segments, with cryoballoon adoption curves and interventional oncology penetration rates as key industry-specific variables.
Inputs from electrophysiology lab surveys and industrial gas supplier disclosures were available through the study window; gaps in long-term patient outcome registries introduce uncertainty bands around EU MDR clinical evidence requirements. Forecasts reflect assumptions about reimbursement stability and electrophysiologist training pipeline expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Intraosseous Infusion Device Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Blood Collection Devices Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
United States Diabetes Devices Market