
 Portal Hypertension Management Market | 2026-2036
Portal Hypertension Management Market Size, Share, and Industry Trends Forecast 2026-2036
Portal Hypertension Management Market Analytics
Hospital procurement channels are rewriting how device manufacturers access interventional suites. Cook Medical leverages its endovascular portfolio to sustain presence across academic medical centers performing transjugular intrahepatic portosystemic shunt procedures. Medtronic plc anchors its position through integrated vascular platforms that span diagnostic imaging through interventional delivery. W. L. Gore & Associates, Inc. differentiates via proprietary expanded polytetrafluoroethylene stent-graft technology optimized for portal venous anatomy.
Portal hypertension management encompasses the clinical and interventional strategies employed to reduce elevated pressure within the portal venous system, typically exceeding 5 mmHg above inferior vena cava pressure, thereby preventing complications such as variceal hemorrhage and ascites. The primary purpose centers on reducing portal pressure gradient below 12 mmHg to prevent bleeding events and improve survival in cirrhotic patients. Pharmacotherapy segments dominate current prescription volumes through non-selective beta-blockers and vasoconstrictor combinations, while transjugular intrahepatic portosystemic shunt procedures capture disproportionate value per procedure despite lower volumes. Endoscopic variceal ligation retains mature, high-frequency utilization in acute bleeding protocols across emergency departments.
The FDA's breakthrough devices program and EMA's priority medicines scheme collectively compress regulatory timelines for novel shunt configurations and pharmacologic combinations. ISO 13485 quality management standards and MDR technical documentation requirements shape manufacturing investments and market access barriers for interventional device portfolios. Stakeholders must monitor evolving reimbursement thresholds for prophylactic versus rescue procedures as payors recalibrate coverage logic around value-based intervention triggers.
Market Dynamics
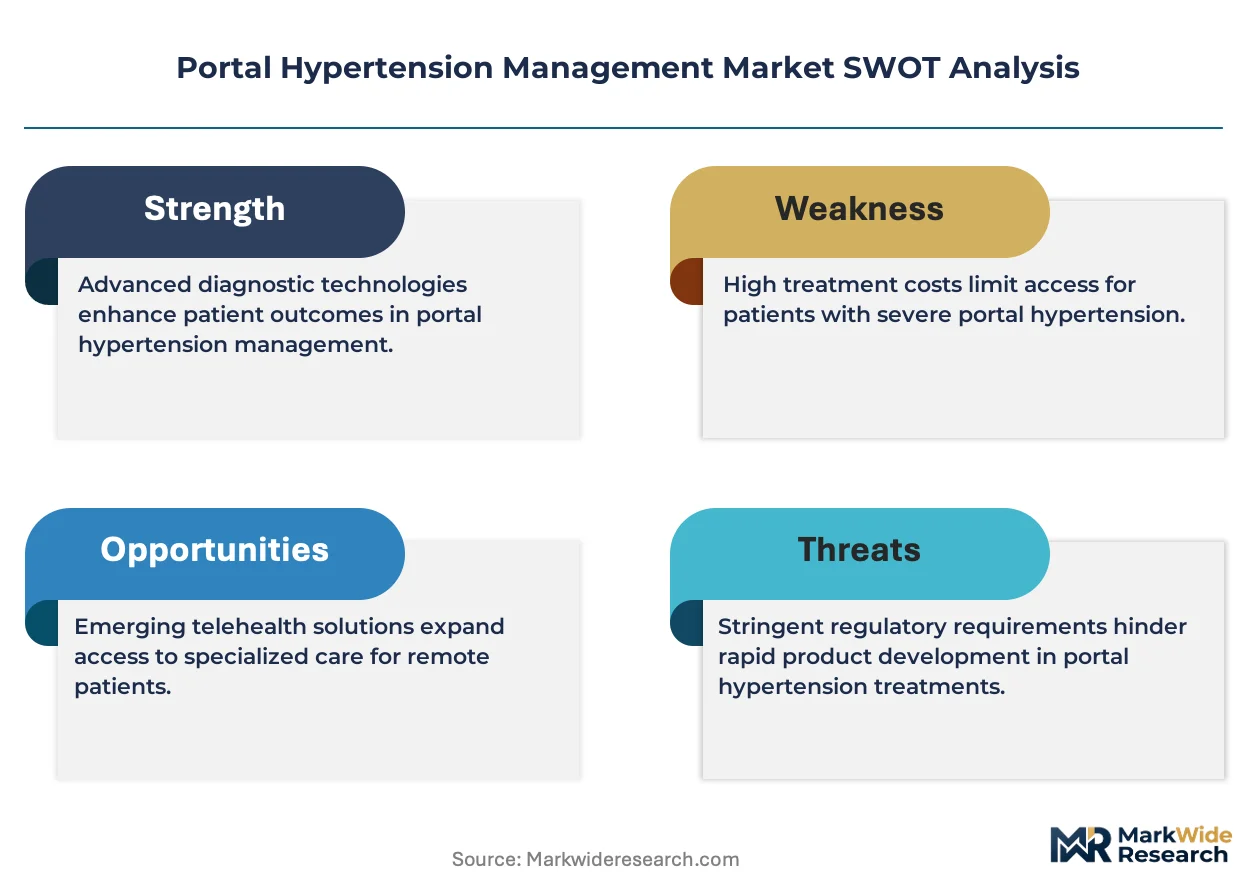
Hospital procurement consolidation is compressing vendor margins while elevating technical performance thresholds for transjugular intrahepatic portosystemic shunt devices, forcing manufacturers to bundle imaging compatibility and procedural training into core contracts.
Growth Catalysts
- FDA Breakthrough Devices Program:Accelerated review timelines for novel stent-graft configurations are compressing commercialization cycles for portal venous interventions, enabling earlier patient access to next-generation shunt technologies.
- Tertiary care center expansion:Academic medical centers in the United States are scaling interventional radiology suites dedicated to hepatobiliary procedures, concentrating high-value procedure volumes and technical expertise.
- Expanded polytetrafluoroethylene innovation:Advanced ePTFE membrane engineering is improving shunt patency rates and reducing thrombosis risk, driving device replacement cycles in established procedural protocols.
Market Restraints
- Biocompatible polymer supply concentration:Specialty fluoropolymer feedstock production clusters in Germany and Japan, exposing device manufacturers to geopolitical friction and input cost volatility.
- Reimbursement compression for prophylactic procedures:CMS coverage determinations in the United States are narrowing indications for elective shunt placement, restricting addressable procedure volumes.
- Endoscopic variceal ligation substitution:Mature banding techniques retain first-line protocol status for acute bleeding events, limiting TIPS penetration in emergency department pathways.
Strategic Opportunities
- Underpenetrated Indian market:Hepatology infrastructure expansion in Maharashtra and Tamil Nadu is creating procedural capacity for interventional portal hypertension management beyond pharmacotherapy-limited protocols.
- Artificial intelligence imaging convergence:Machine learning-powered portal venous pressure gradient prediction is enabling patient selection optimization and procedure planning automation.
- European MDR harmonization:Unified technical documentation requirements across EU member states are reducing redundant certification costs for stent-graft manufacturers seeking multi-country market access.
Industry Challenges
- Interventional radiology talent scarcity:Specialized training pathways for transjugular intrahepatic portosystemic shunt procedures remain limited, constraining procedural capacity expansion in community hospital settings.
- ISO 13485 compliance timeline compression:Quality management system recertification demands are diverting engineering resources from product development pipelines.
- Legacy electronic health record integration:Procedural documentation workflows for shunt interventions require custom middleware development to interface with entrenched hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portal Hypertension Management Market |
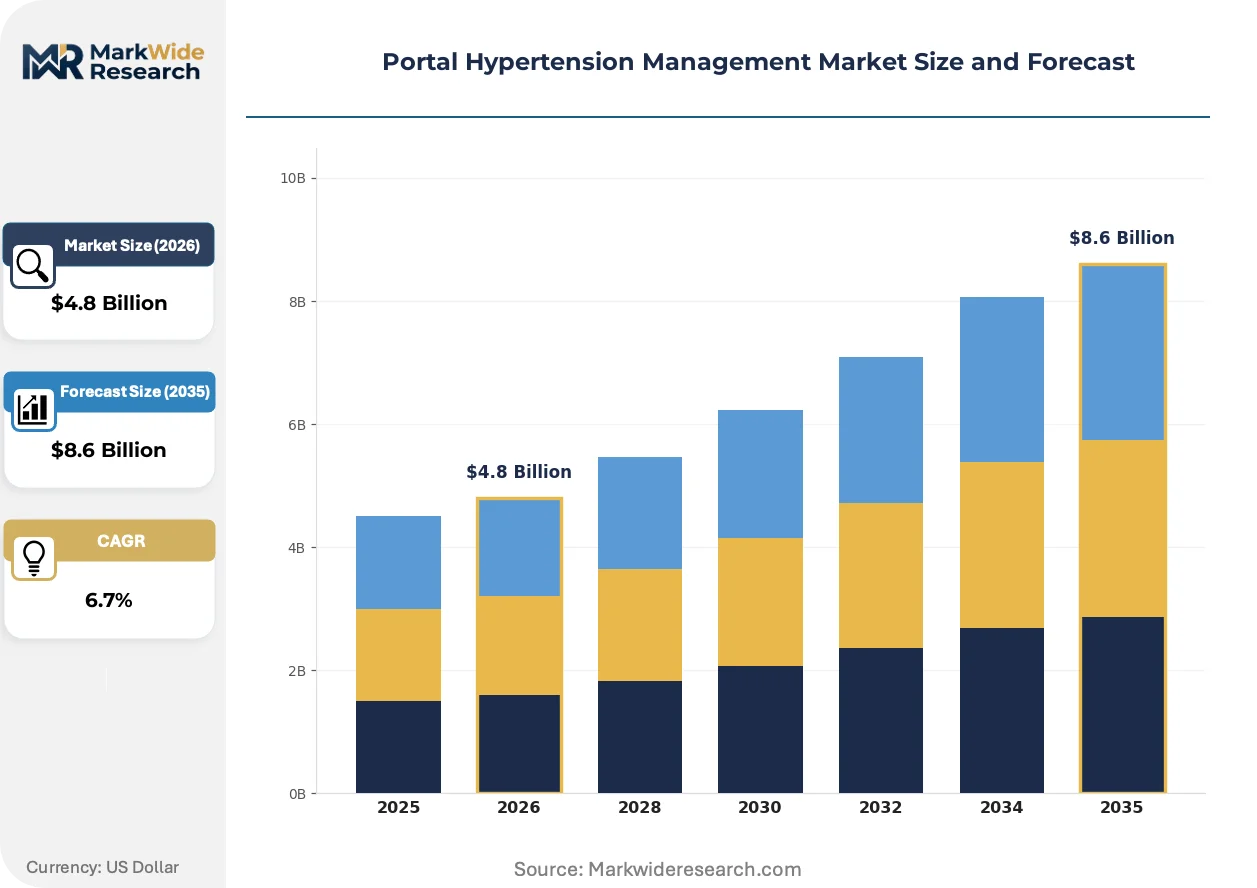
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopic Variceal Ligation, Transjugular Intrahepatic Portosystemic Shunt, Pharmacotherapy, Sclerotherapy Application: Chronic Liver Disease, Hepatic Encephalopathy, Gastrointestinal Bleeding, Cirrhosis End User: Hospitals, Specialty Clinics, Academic Institutions, Home Healthcare Delivery Mode: Intravenous, Oral, Subcutaneous, Transdermal |
| Companies Covered | Cook Medical, Gilead Sciences Inc., Novartis AG, Ono Pharmaceutical Co., Ltd., Sun Pharmaceutical Industries Ltd., W. L. Gore & Associates, Inc., Takeda Pharmaceutical Company, Intercept Pharmaceuticals, Inc., Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portal Hypertension Management Market Evolving Landscape
Digital workflow integration and materials science advances are redefining procedural economics in portal hypertension intervention, compressing the gap between diagnostic imaging and therapeutic delivery.
Bioresorbable stent technology is migrating from coronary vascular applications toward portal venous deployment, with early feasibility studies exploring magnesium alloy scaffolds that degrade post-patency establishment. Academic medical centers in Germany are piloting these implants in elective shunt procedures, evaluating thrombogenicity profiles against permanent metallic alternatives. The technology is migrating from permanent implant paradigms toward temporary scaffolding approaches that reduce long-term anticoagulation burden.
EMA's Medical Device Regulation is enforcing stricter clinical evidence requirements for Class III implantable devices, mandating post-market surveillance registries that track real-world patency and complication outcomes. Manufacturers must now sustain longitudinal data collection infrastructure spanning multiple member states, elevating compliance costs but improving safety signal detection. High-risk stent-graft categories face the steepest documentation burdens, with notified bodies in the Netherlands and Germany applying differential scrutiny levels.
Direct-to-hospital contracting is displacing traditional distributor intermediaries in large health system procurement, with integrated delivery networks negotiating multi-year supply agreements that bundle devices with procedural training and outcome guarantees. Interventional radiology department heads now participate directly in vendor selection committees, bypassing general purchasing hierarchies. This pattern is most pronounced in United States-based academic medical centers with captive insurance plans and value-based care contracts.
Portal Hypertension Management Market Segmentation
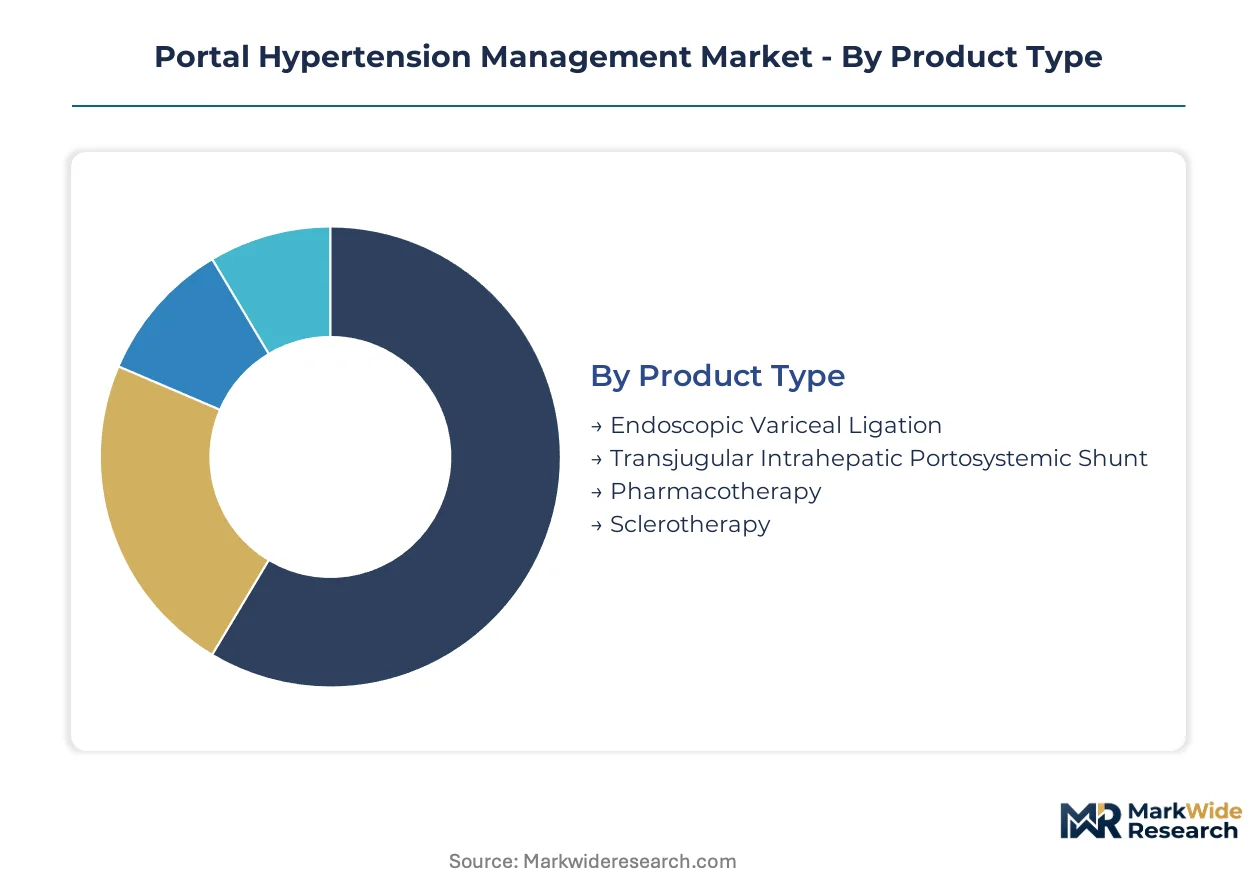
Portal hypertension management requires precise patient stratification to match intervention intensity with disease severity. Segmentation reveals how pharmacotherapy dominates prescription volumes while transjugular shunt procedures concentrate economic value. Understanding these divides enables targeted resource allocation across acute, chronic, and prophylactic care pathways.
Product Type:
Cost tier determines reimbursement intensity and procurement channel selection across intervention modalities.
- Pharmacotherapy:Non-selective beta-blockers and vasoconstrictor combinations constitute the foundational prescription layer. Volume concentrates in tertiary care discharge protocols across the United States, where prophylactic regimens face tightening CMS prior authorization requirements.
- Transjugular Intrahepatic Portosystemic Shunt:Fluoroscopy-guided stent-graft deployment reduces portal pressure gradient through portosystemic diversion. Academic medical centers in Germany and the United States drive adoption as interventional radiology suites expand dedicated hepatobiliary capacity.
- Endoscopic Variceal Ligation:Elastic band application via flexible endoscopy retains emergency department primacy for acute variceal hemorrhage.
- Sclerotherapy:Injection of sclerosant agents directly into variceal columns persists in resource-constrained settings where banding device availability remains limited.
Pharmacotherapy commands the established base. The steepest expansion runs through transjugular intrahepatic portosystemic shunt procedures.
Application:
Clinical indication severity shapes intervention selection algorithms and care setting requirements.
- Cirrhosis:Advanced hepatic fibrosis generates the primary portal hypertension disease burden requiring staged intervention escalation. United States hepatology practices drive diagnostic protocol standardization as compensated versus decompensated disease classification determines reimbursement eligibility.
- Gastrointestinal Bleeding:Acute variceal hemorrhage demands immediate intervention with mortality escalation beyond initial hours. Emergency department throughput pressures in Japan and Germany are accelerating protocol automation investments.
- Hepatic Encephalopathy:Neuropsychiatric complications from portosystemic shunting limit procedural candidacy and require post-intervention monitoring.
- Chronic Liver Disease:Pre-cirrhotic portal hypertension management focuses on etiology-specific treatment and surveillance intervals.
Cirrhosis anchors procedure volume concentration. Gastrointestinal bleeding applications are climbing the fastest as acute care infrastructure expands.
End User:
Customer type dictates capital intensity, staffing requirements, and contracting sophistication for device manufacturers.
- Hospitals:Integrated inpatient and interventional capabilities enable full-spectrum portal hypertension management from acute stabilization through elective shunt placement. United States health system consolidation is concentrating purchasing power among integrated delivery networks with captive insurance plans.
- Academic Institutions:Research-active centers generate clinical evidence for novel device configurations and train specialized interventional radiology fellows. German university hospitals lead European post-market surveillance registry participation under MDR requirements.
- Specialty Clinics:Outpatient hepatology practices manage stable patients on pharmacotherapy with periodic endoscopic surveillance.
- Home Healthcare:Oral beta-blocker administration and patient monitoring extend chronic management beyond facility walls.
Hospitals retain the dominant installed base. Academic institutions are gaining share fastest through research partnerships and training pipeline control.
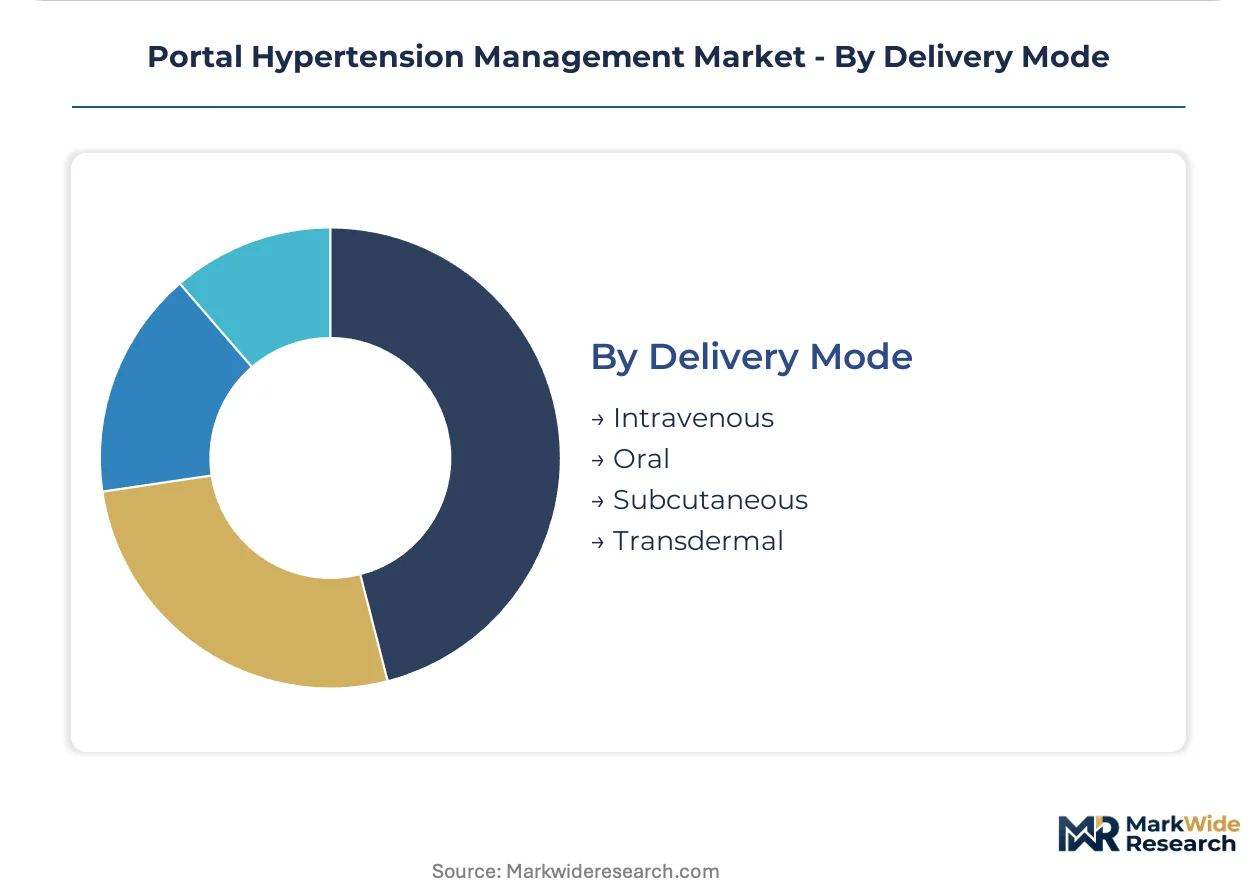
Delivery Mode:
Volume and margin profiles diverge sharply between chronic administration routes and acute procedural delivery.
- Oral:Chronic beta-blocker and diuretic administration enables outpatient disease management at scale. Prescription volume concentrates in United States Medicare Part D formularies where generic substitution pressures manufacturer margin structures.
- Intravenous:Acute vasoactive infusions require hospital-based administration for hemodynamic monitoring during active bleeding events. Japanese emergency medicine protocols standardize terlipressin and octreotide infusion algorithms.
- Subcutaneous:Emerging depot formulations seek to bridge acute and chronic administration convenience.
- Transdermal:Patch-based delivery remains experimental for portal hypertension pharmacotherapy with limited clinical validation.
Oral delivery commands the prescription volume base. Intravenous administration is expanding most quickly through emergency department protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States tertiary care networks while German academic centers extract value through bundled procedure training contracts. Japanese emergency medicine protocols standardize device specifications across metropolitan hospital systems. Indian hepatology infrastructure expansion in Maharashtra and Tamil Nadu is creating procedural capacity beyond pharmacotherapy-limited protocols.
United States
Integrated delivery networks with captive insurance plans negotiate multi-year supply agreements bundling devices with outcome guarantees. FDA breakthrough device designation compresses commercialization timelines for novel stent-graft configurations. Tertiary care centers in Boston and Houston drive procedure volumes for refractory variceal bleeding through dedicated interventional radiology suites.
Germany
University hospitals lead European post-market surveillance registry participation under MDR requirements for Class III implantable devices. EMA's Medical Device Regulation enforces stricter clinical evidence requirements with longitudinal data collection infrastructure. Academic medical centers in Munich and Heidelberg pilot bioresorbable magnesium alloy scaffolds in elective shunt procedures.
Japan
Emergency department throughput pressures accelerate protocol automation investments for acute variceal hemorrhage management. PMDA regulatory pathways align with international standards while maintaining distinct pharmacovigilance requirements. Metropolitan hospital systems in Tokyo and Osaka standardize terlipressin and octreotide infusion algorithms.
India
Hepatology infrastructure expansion creates procedural capacity for interventional portal hypertension management beyond pharmacotherapy. CDSCO regulatory harmonization with international standards reduces redundant certification burdens for multinational device manufacturers. Medical device clusters in Maharashtra and Tamil Nadu concentrate manufacturing investments for domestic and export markets.
United Kingdom
NHS procurement frameworks prioritize value-based intervention triggers for prophylactic versus rescue procedures. MHRA post-Brexit regulatory autonomy maintains alignment with MDR technical documentation requirements while streamlining national market access. London-based academic medical centers generate clinical evidence for novel device configurations through research-active interventional radiology departments.
Portal Hypertension Management Market Competitive Landscape
Endovascular device specialists and integrated pharmaceutical-device conglomerates split the market along intervention modality lines. The competitive structure reflects consolidated procurement power among United States health systems and fragmented hospital networks in emerging markets. Three archetypes dominate: stent-graft technology innovators, endovascular portfolio integrators, and hepatology-focused pharmaceutical developers. M&A activity concentrates on imaging compatibility assets and procedural training capabilities, while geographic expansion targets Indian and Southeast Asian hepatology infrastructure buildouts.
Among endovascular portfolio integrators, Cook Medical and Medtronic plc occupy positions spanning diagnostic imaging through interventional delivery systems. W. L. Gore & Associates, Inc. anchors the stent-graft technology tier through proprietary expanded polytetrafluoroethylene membrane engineering optimized for portal venous anatomy. These three companies exemplify how device manufacturers bundle imaging compatibility and procedural training into core hospital contracts to defend vendor relationships against procurement consolidation pressures.
| Leading Market Players |
|---|
| Cook Medical |
| Gilead Sciences Inc. |
| Novartis AG |
| Ono Pharmaceutical Co., Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| W. L. Gore & Associates, Inc. |
| Takeda Pharmaceutical Company |
| Intercept Pharmaceuticals, Inc. |
| Medtronic plc |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's intermodal cost dynamics amplify price differentiation between configured-to-order stent-graft systems and standard catheter kits, as German polymer feedstock concentration feeds into tiered procurement negotiations across United States integrated delivery networks.
Pricing Analysis
Customization-premium spreads separate patient-specific stent-graft configurations from standard ePTFE shunt kits. Three-tier pricing structure across premium, standard, and economy levels tracks FDA breakthrough designation status and procedural training bundling. Pricing pressure stems from GPO consolidation in United States academic medical centers. Community hospitals exhibit highest price sensitivity; tertiary care networks with captive insurance plans demonstrate lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with German fluoropolymer specialists and Japanese precision extrusion houses for ePTFE membrane production. Specialty polymer feedstock draws from Germany, Japan, and United States chemical clusters. Biocompatible fluoropolymer dependencies center on PTFE resin, nickel-titanium alloy wire, and radiopaque marker bands. Single-source vulnerability runs through German specialty polymer production. Distribution runs through direct-to-hospital contracting with integrated delivery networks displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Endoscopic variceal ligation substitution threatens transjugular shunt expansion, forcing incumbents to defend procedural value through outcome differentiation and training ecosystem control.
For Market Incumbents: Pre-empt banding protocol retention by embedding AI-powered pressure gradient prediction into stent-graft system workflows. Secure backward integration into ePTFE membrane production to offset German feedstock concentration. Counter endoscopic substitution through bundled outcome guarantees with United States integrated delivery networks. For New Entrants and Emerging Players: Maharashtra and Tamil Nadu hepatology infrastructure expansion offers procedural capacity entry points beyond pharmacotherapy-saturated Western markets. Target interventional radiology training pipeline gaps in Indian academic medical centers. Lead with cost-optimized shunt configurations compatible with existing C-arm fluoroscopy installations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with undermonetized hepatobiliary portfolios. Five-to-ten year viability hinges on MDR compliance infrastructure and post-market surveillance registry participation. Signal to watch: FDA breakthrough designation awards for bioresorbable shunt scaffolds.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses commercialization timelines for novel stent-graft configurations. |
| Hospital System Partnership | Direct contracting with integrated delivery networks bundles devices with procedural training. |
| CE Marking Pathway | MDR technical documentation requirements shape multi-country market access investments. |
| Reimbursement Strategy | CMS coverage determinations for prophylactic versus rescue procedures dictate addressable volumes. |
| Software Companion Development | Machine learning-powered portal venous pressure prediction enables patient selection optimization. |
Research Methodology
Cross-validation between interventional radiology department heads and hospital procurement managers anchors the qualitative findings. Primary interviews with hepatologists, biomedical engineers, GPO contracts managers, and regulatory affairs specialists combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EMA MDR technical documentation, and hospital procurement contract records. Bottom-up procedure volume modeling and top-down market sizing triangulate value estimates.
Calibration against historical TIPS procedure volumes and pharmacotherapy prescription trends informs the analytical framework across the analysis window. Segmentation dimensions include intervention modality, clinical indication severity, end-user facility type, and regional regulatory cluster. CAGRs derive from procedure volume elasticity to hepatology infrastructure expansion and device replacement cycle dynamics. Forecast inputs incorporate interventional radiology fellowship training pipeline capacity and MDR compliance timeline compression.
Practitioners should monitor reimbursement threshold revisions and bioresorbable scaffold clinical trial readouts for early signals. Forecasts reflect assumptions regarding regulatory pathway efficiency and training pipeline expansion. Patent cliff dynamics for pharmacotherapy agents and geopolitical friction in fluoropolymer feedstock supply represent revision triggers. Quarterly review of FDA breakthrough designation awards and CMS national coverage determinations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Stable Angina Management Market