
 Global Pericardiocentesis Procedures Market | 2026-2036
Global Pericardiocentesis Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pericardiocentesis Procedures Market Foresight
China is rewriting supply dynamics for pericardiocentesis devices through expanded catheter manufacturing zones in Jiangsu and Guangdong provinces. Medtronic plc leverages its integrated portfolio across drainage kits and monitoring systems to sustain market presence. Boston Scientific competes on echocardiography-guided technology leadership, while Cook Medical anchors its position through specialized needle and catheter designs for emergency interventions.
Pericardiocentesis denotes the percutaneous needle aspiration of fluid from the pericardial sac, typically performed under imaging guidance with 16-18 gauge needles and multi-sidehole catheters to relieve cardiac tamponade or obtain diagnostic samples. The procedure serves as a critical intervention in acute cardiology, oncology, and trauma settings where pericardial effusion threatens hemodynamic stability. Echocardiography-guided techniques dominate procedural volumes due to real-time visualization and bedside applicability, while drainage kits capture concentrated margin pools through bundled disposable economics. Ultrasound-guided methods represent the fastest-growing technique segment as point-of-care imaging expands beyond specialized cardiac centers into emergency departments.
FDA clearance pathways for Class II cardiac devices shape product development timelines and commercialization strategies for manufacturers entering the US market. The EMA's Medical Device Regulation imposes enhanced clinical evidence requirements on European suppliers, while China's NMPA accelerates review timelines for innovative pericardiocentesis technologies through its priority review channels. Stakeholders must monitor how reimbursement policy shifts toward outpatient and emergency department settings will redistribute procedural volumes and device procurement patterns across care delivery sites.
Market Dynamics
Point-of-care ultrasound adoption is compressing referral pathways for pericardiocentesis, shifting procedural control from specialized cardiac centers toward emergency medicine departments and altering device procurement hierarchies across health systems.
Growth Catalysts
- Emergency department expansion:Tertiary hospitals in the United States are embedding pericardiocentesis capabilities within emergency medicine workflows, creating dedicated device procurement streams for bedside drainage kits.
- MDR clinical evidence pathways:The EU Medical Device Regulation's enhanced requirements are accelerating differentiation toward manufacturers with robust clinical data packages, favoring established echocardiography-guided system suppliers.
- Oncology-related effusion volume:Rising cancer prevalence is expanding the addressable patient pool for diagnostic and therapeutic pericardiocentesis across academic medical centers.
Market Restraints
- Specialized needle supply concentration:Manufacturing of 16-18 gauge pericardiocentesis needles clusters among a limited supplier base in Jiangsu province, creating vulnerability to regional production disruptions.
- Reimbursement compression:CMS payment adjustments for inpatient cardiac procedures are constraining device budget allocations across US hospital systems.
- Catheter material cost volatility:Medical-grade polyurethane pricing fluctuations directly impact drainage kit margin structures for disposable manufacturers.
Strategic Opportunities
- Ambulatory surgery center penetration:Brazil's expanding ASC network for cardiac interventions represents an underdeveloped channel for outpatient pericardiocentesis device deployment.
- AI-guided needle navigation:Convergence of machine learning algorithms with real-time ultrasound imaging is enabling semi-automated procedural guidance for lower-skill operators.
- Japan's priority review channels:PMDA accelerated pathways for innovative cardiac devices offer streamlined market access for next-generation drainage technologies.
Industry Challenges
- Echocardiography certification bottlenecks:The limited pipeline of credentialed sonographers capable of guiding emergency pericardiocentesis is constraining procedural expansion outside specialized centers.
- Legacy EMR integration complexity:New point-of-care documentation systems face interoperability friction with established hospital information architectures, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pericardiocentesis Procedures Market |
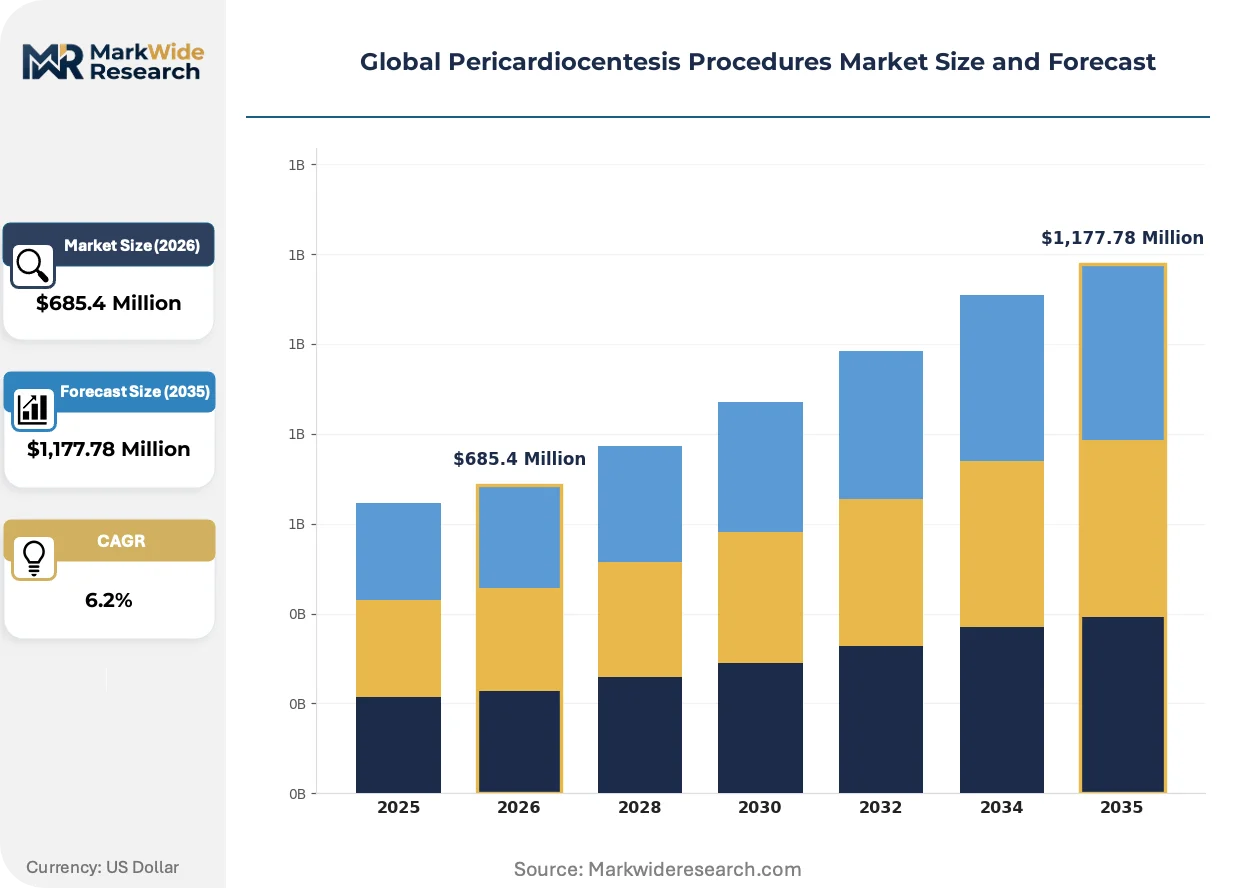
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technique: Echocardiography-Guided, Fluoroscopy-Guided, CT-Guided, Ultrasound-Guided Device Type: Needle, Catheter, Drainage Kit, Monitoring System End User: Hospitals, Outpatient Clinics, Research Institutions, Emergency Departments Application: Diagnostic, Therapeutic, Emergency Intervention, Palliative Care |
| Companies Covered | Medtronic plc, Cleveland Clinic, NewYork-Presbyterian Hospital, The Johns Hopkins Hospital, Apollo Hospitals Enterprise Ltd, Boston Scientific, Cook Medical, Buddhist Tzu Chi Medical Foundation, Mediclinic International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pericardiocentesis Procedures Market Shifts & Advancements
Digital integration across imaging and interventional platforms is redefining procedural workflows, with three distinct vectors reshaping how pericardiocentesis is performed, regulated, and procured.
Tele-echocardiography platforms are virtualizing specialist oversight for pericardiocentesis procedures performed in community hospitals and rural emergency departments. Cardiologists at academic medical centers now provide real-time remote guidance for bedside interventions, compressing the geographic distribution of procedural expertise. This virtualization is enabling smaller facilities to maintain pericardiocentesis capabilities without maintaining full-time interventional cardiology staffing.
The FDA's evolving guidance on minimally invasive cardiac devices is reshaping predicate device pathways for pericardiocentesis drainage kits. Manufacturers face expanded clinical data requirements for substantial equivalence determinations, extending development timelines by 12-18 months. US-based suppliers are responding by front-loading pivotal trials and strengthening post-market surveillance infrastructures to satisfy heightened scrutiny.
Hospital purchasing consortia are consolidating device procurement for cardiac interventions under centralized contracting mechanisms. Independent community hospitals are ceding sourcing autonomy to regional GPOs, which negotiate bundled pricing across drainage kits, needles, and monitoring accessories. This concentration is most visible in the southeastern United States, where multi-hospital systems are standardizing pericardiocentesis device specifications to capture volume discounts.
Global Pericardiocentesis Procedures Market Segmentation
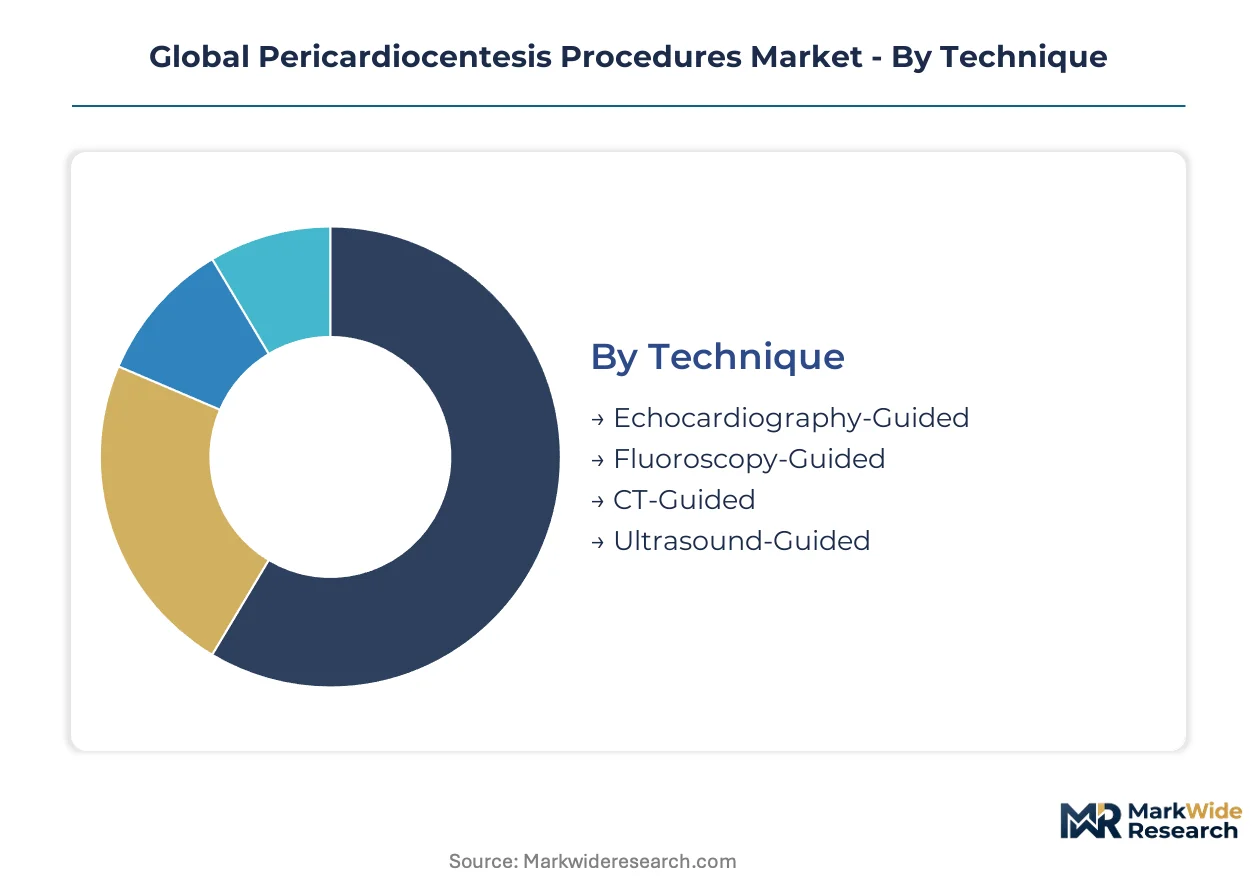
Pericardiocentesis device procurement patterns diverge sharply across clinical settings, with technique selection driving imaging equipment investments and device type determining disposable economics. Manufacturers must align portfolio breadth against these intersecting demand axes to capture procedural volume.
Technique:
Use-case spectrum spans bedside emergency intervention through precision-guided elective procedures, with imaging modality selection dictated by hemodynamic urgency and institutional capability.
- Echocardiography-Guided:Real-time cardiac visualization via transthoracic or transesophageal probes enables procedural execution at the bedside without radiation exposure. Tertiary care centers in the United States concentrate demand for integrated echocardiography-drainage systems as emergency departments assume procedural ownership from specialized cardiac units.
- Ultrasound-Guided:Point-of-care ultrasound devices with cardiac presets are displacing formal echocardiography suites in community hospital emergency departments, compressing referral pathways and expanding addressable operator pools.
- Fluoroscopy-Guided:Radiation-based guidance remains standard for complex effusions with loculated anatomy or when concomitant pericardial biopsy is required.
- CT-Guided:Computed tomography navigation serves posterior effusions and patients with distorted thoracic anatomy where acoustic windows are inadequate.
The dominant share belongs to Echocardiography-Guided, while Ultrasound-Guided is closing the gap fastest.
Device Type:
Cost tier stratification separates capital equipment investments from recurring disposable procurement, with bundled kit economics capturing concentrated margin pools.
- Drainage Kit:Pre-packaged assemblies combining needle, catheter, drainage bag, and connection tubing command premium pricing through procedural bundling. Hospital purchasing consortia in the southeastern United States negotiate standardized kit specifications across multi-hospital systems to extract volume discounts.
- Catheter:Multi-sidehole polyurethane or silicone catheters in 6-14 French sizes enable sustained pericardial drainage, with material selection impacting dwell time and complication profiles.
- Needle:16-18 gauge specialized pericardiocentesis needles with echogenic tips and depth markers cluster manufacturing in Jiangsu province supply zones.
- Monitoring System:Pressure transducers and continuous drainage monitors attach to catheter hubs, enabling tamponade resolution assessment without repeated echocardiography.
Drainage Kit captures the highest revenue per procedure, though Catheter replacement cycles generate the most predictable recurring revenue streams.
End User:
Customer type determines procurement authority structure, with centralized hospital purchasing contrasting against decentralized emergency department acquisition.
- Hospitals:Inpatient cardiac units and interventional suites maintain comprehensive device inventories across all technique modalities, governed by value analysis committees.
- Emergency Departments:Point-of-care capability expansion is redirecting procedural volumes and creating dedicated procurement streams for bedside drainage kits.
- Outpatient Clinics:Elective diagnostic pericardiocentesis in oncology and rheumatology settings favors scheduled fluoroscopy-guided procedures.
- Research Institutions:Academic medical centers drive protocol innovation and training curriculum development, with device selection influenced by publication and trial requirements.
Emergency Departments are expanding device procurement autonomy fastest, though Hospitals retain consolidated budget authority.
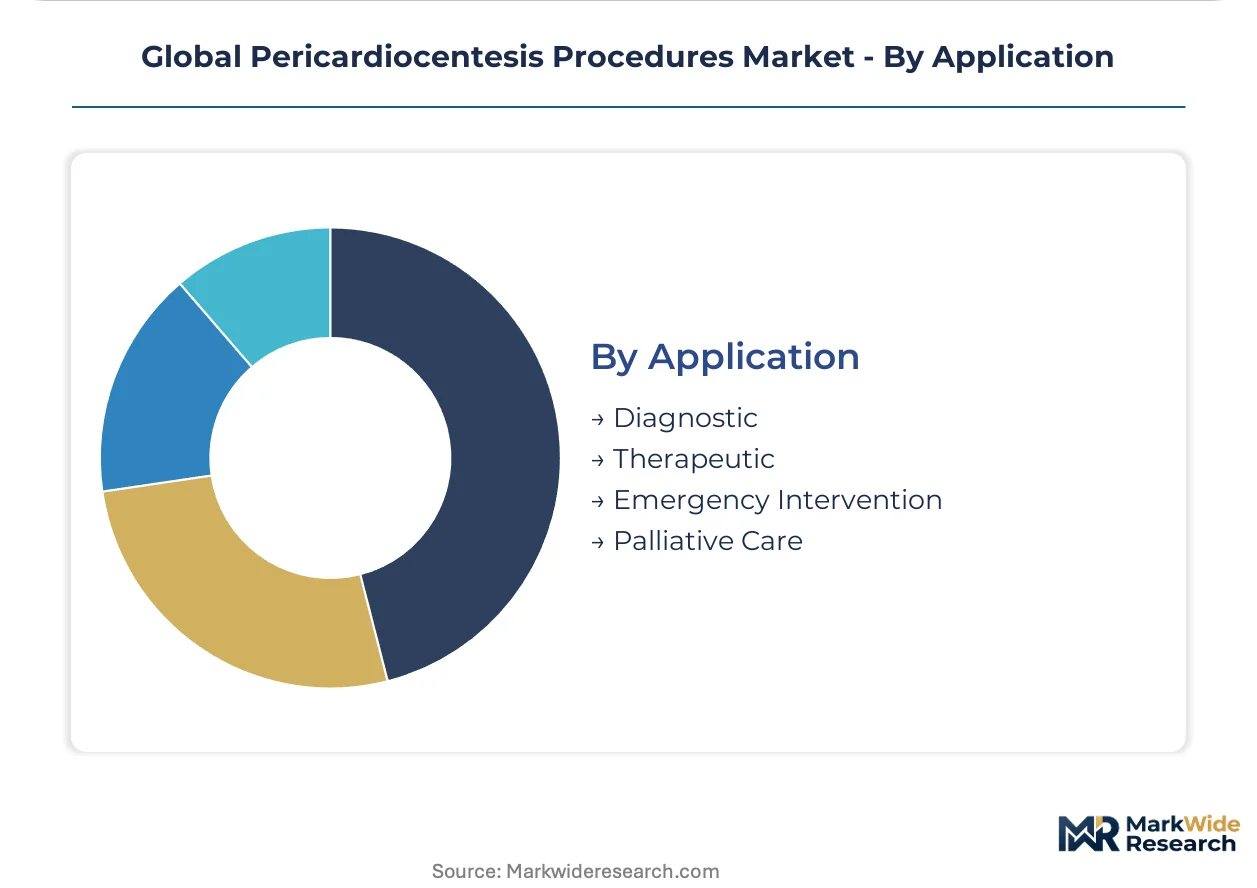
Application:
Clinical intent shapes urgency gradients and reimbursement pathways, from life-saving intervention through comfort-directed palliation.
- Emergency Intervention:Cardiac tamponade requiring immediate decompression commands highest device specification tolerance and premium pricing acceptance.
- Diagnostic:Fluid acquisition for cytology, microbiology, and immunohistochemistry drives procedure volume in oncology and infectious disease services.
- Therapeutic:Recurrent effusion management via catheter placement for prolonged drainage reduces repeat procedural burden.
- Palliative Care:Symptom-directed fluid removal in end-stage malignancy prioritizes patient comfort over diagnostic yield, influencing device selection toward simpler configurations.
Emergency Intervention commands premium device specifications, while Diagnostic applications generate the highest procedure frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for pericardiocentesis devices diverge sharply across geographies, with the United States emphasizing emergency department point-of-care deployment while Asian markets prioritize catheter manufacturing scale and cost-efficient drainage kit production.
United States
Tertiary care centers in the United States are scaling pericardiocentesis volumes to manage rising pericardial effusion cases, particularly in oncology and trauma settings. FDA clearance pathways for Class II cardiac devices shape product development timelines and commercialization strategies for manufacturers entering this market. Hospital purchasing consortia in the southeastern United States are consolidating device procurement under centralized contracting mechanisms to negotiate bundled pricing.
Germany
German hospital systems maintain comprehensive device inventories across all technique modalities, governed by value analysis committees with stringent quality benchmarks. The EMA's Medical Device Regulation imposes enhanced clinical evidence requirements on European suppliers, favoring established echocardiography-guided system suppliers with robust clinical data packages. Industrial clusters in Baden-Württemberg and Bavaria host specialized medical device engineering firms supporting component innovation.
China
China is rewriting supply dynamics for pericardiocentesis devices through expanded catheter manufacturing zones in Jiangsu and Guangdong provinces. The NMPA accelerates review timelines for innovative pericardiocentesis technologies through its priority review channels, streamlining market access for next-generation drainage technologies. Manufacturing of 16-18 gauge pericardiocentesis needles clusters among a limited supplier base in Jiangsu province, creating both scale advantages and vulnerability to regional production disruptions.
Japan
Japanese academic medical centers drive protocol innovation and training curriculum development, with device selection influenced by publication and trial requirements. METI and PMDA accelerated pathways for innovative cardiac devices offer streamlined market access for next-generation drainage technologies. The Kanto region around Tokyo concentrates demand for integrated echocardiography-drainage systems as emergency departments assume procedural ownership.
Brazil
Brazil's expanding ambulatory surgery center network for cardiac interventions represents an underdeveloped channel for outpatient pericardiocentesis device deployment. ANVISA regulatory frameworks govern device registration and commercialization timelines for international suppliers seeking market entry. São Paulo and Rio de Janeiro anchor demand concentration, with private hospital chains driving procurement standardization across southeastern states.
Global Pericardiocentesis Procedures Market Competitive Landscape
Capability concentration sits with integrated portfolio players; scale advantage sits with specialized catheter and needle manufacturers. The market structure reflects a tiered competitive environment where diversified medical technology conglomerates compete against focused interventional cardiology device specialists. Two strategic archetypes dominate: integrated full-line suppliers spanning drainage kits through monitoring systems, and specialized component manufacturers concentrating on needle and catheter engineering. Competitive moves center on M&A activity targeting point-of-care ultrasound compatibility and strategic partnerships with emergency medicine purchasing consortia.
Within the integrated portfolio tier, Medtronic plc and Boston Scientific occupy positions as archetypal full-line suppliers, while Cook Medical exemplifies the specialized interventional device specialist. Among hospital-based service providers, Cleveland Clinic and NewYork-Presbyterian Hospital represent institutional anchors that influence device selection through training curriculum and protocol standardization. Apollo Hospitals Enterprise Ltd sits within the emerging market expansion archetype, reflecting geographic diversification strategies targeting high-volume cardiac intervention markets in South Asia.
| Leading Market Players |
|---|
| Medtronic plc |
| Cleveland Clinic |
| NewYork-Presbyterian Hospital |
| The Johns Hopkins Hospital |
| Apollo Hospitals Enterprise Ltd |
| Boston Scientific |
| Cook Medical |
| Buddhist Tzu Chi Medical Foundation |
| Mediclinic International |
| Others |
Supply & Pricing Matrix
Jiangsu province's catheter manufacturing zones dictate downstream pricing power for drainage kit suppliers, with concentrated polyurethane processing capacity enabling tiered margin capture across emergency department procurement tiers.
Pricing Analysis
Long-term offtake agreements dominate hospital purchasing consortia negotiations, particularly across southeastern United States multi-hospital systems securing bundled drainage kit pricing. Price differentiation hinges on FDA clearance tier and echocardiography integration depth, with premium configurations commanding substantial brand premiums. Cost compression in standard-tier kits intensifies as Chinese manufacturers expand catheter export capacity. Emergency departments exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Extended payment terms from Jiangsu-based needle manufacturers to downstream kit assemblers compress working capital cycles across the procurement hierarchy. Supply concentrates in China, Germany, and the United States, with medical-grade polyurethane feedstock drawing from petrochemical complexes in Texas and Rotterdam. Single-source vulnerability clusters around 16-18 gauge needle production in Jiangsu province. Distribution runs through hospital purchasing consortia and group purchasing organizations, with regional GPOs consolidating sourcing autonomy from independent community hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
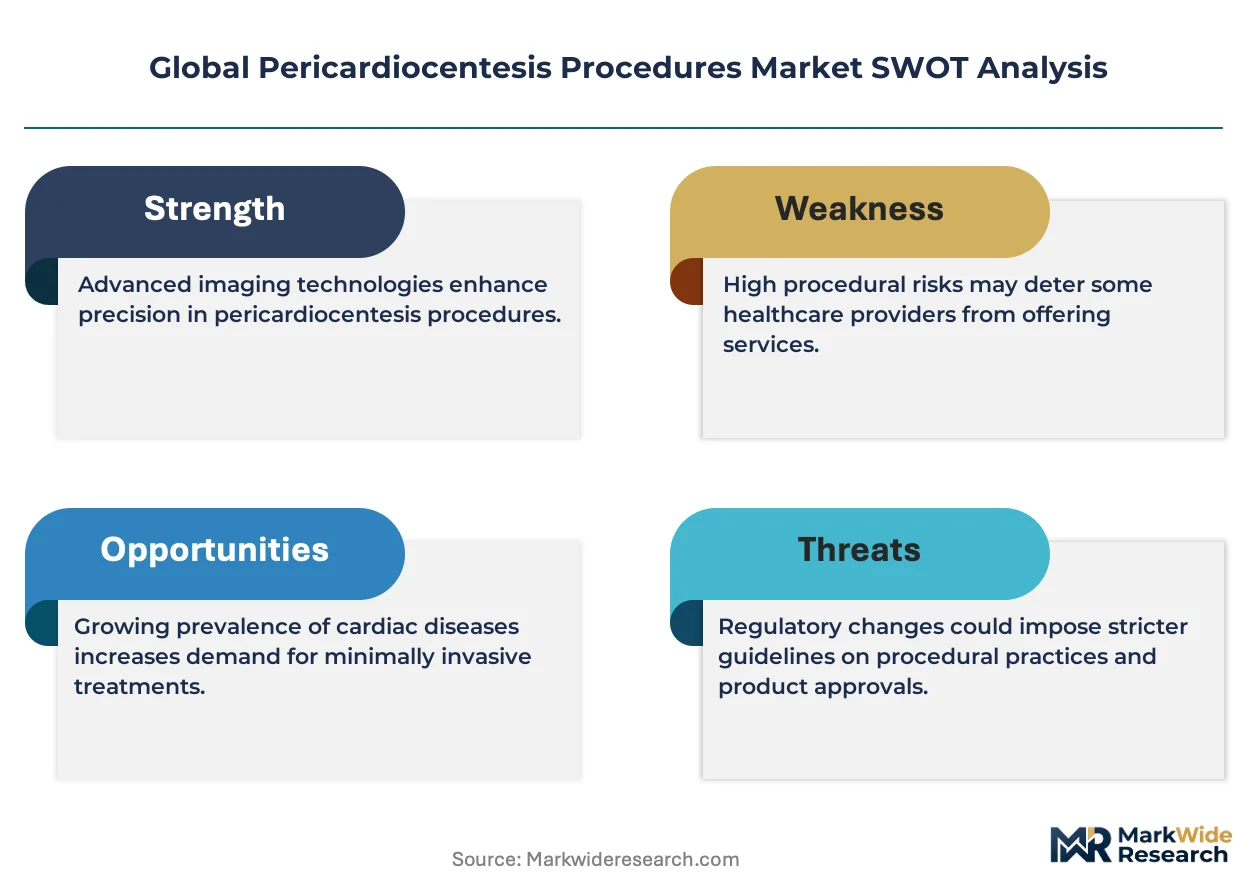
Point-of-care ultrasound adoption constitutes a high-growth disruption reshaping procedural control, with FDA guidance evolution on minimally invasive cardiac devices accelerating competitive repositioning across device categories.
For Market Incumbents: Harden echocardiography-guided system portfolios against ultrasound-guided displacement by embedding AI navigation capabilities and securing emergency department purchasing consortia relationships. Backward integration into catheter material processing mitigates polyurethane cost volatility exposure. Prioritize post-market surveillance infrastructure investments to satisfy FDA's expanded clinical data requirements for predicate device pathways. For New Entrants and Emerging Players: Pursue Brazil's ambulatory surgery center network as the most penetrable geographic white space, where ANVISA regulatory frameworks lag established market entry barriers. Target AI-guided needle navigation as the highest-velocity technology wedge, leveraging machine learning algorithm partnerships with point-of-care ultrasound manufacturers. Deploy reimbursement strategy specialization as the primary go-to-market angle, navigating CMS payment adjustments for outpatient cardiac procedures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated full-line suppliers with echocardiography-drainage system bundling capabilities over specialized component manufacturers. Long-term viability across the analysis window rests on capturing emergency department procurement autonomy shifts and tele-echocardiography platform integration. Monitor PMDA priority review channel utilization rates as the signal indicating next-generation drainage technology commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI Navigation Integration | Machine learning algorithms from ultrasound manufacturers enable semi-automated guidance for lower-skill operators. |
| Hospital System Partnership | Multi-hospital consortia in the southeastern United States consolidate bundled drainage kit procurement under centralized contracting. |
| FDA Submission Strategy | Front-loaded pivotal trials address expanded clinical data requirements for substantial equivalence determinations. |
| CE Marking Pathway | Robust clinical data packages satisfy EMA Medical Device Regulation enhanced evidence requirements. |
| Software Companion Development | Tele-echocardiography platforms virtualize specialist oversight for community hospital bedside interventions. |
Research Methodology
A spread of perspectives from interventional cardiologists, emergency medicine physicians, hospital purchasing committee members, GPO contracts managers, and biomedical engineers converged on the working assumptions. Primary interviews combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EMA medical device registration data. Bottom-up procedure volume estimates triangulated against top-down device shipment analysis.
Demand-supply balance modeling anchored quantitative projections across the analysis window, with segmentation across technique modality, device type, end-user setting, and application intent. CAGRs derived from procedure volume elasticity to oncology prevalence trends and emergency department capability expansion rates. Forecast inputs incorporated point-of-care ultrasound adoption curves and NMPA priority review channel throughput.
Sensitivities concentrate around reimbursement policy shifts toward outpatient settings and regional production disruptions in Jiangsu province needle manufacturing clusters. Forecasts reflect documented assumptions regarding regulatory pathway timelines and hospital capital expenditure cycles. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Global Vascular Plugs Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
Arteriovenous (Av) Fistula Needle Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
Global Aortic Endografts Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Integrated Cardiology Devices Market