
 Cardiac Arrhythmia Therapeutics Market | 2026-2036
Cardiac Arrhythmia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Arrhythmia Therapeutics Market Outlook
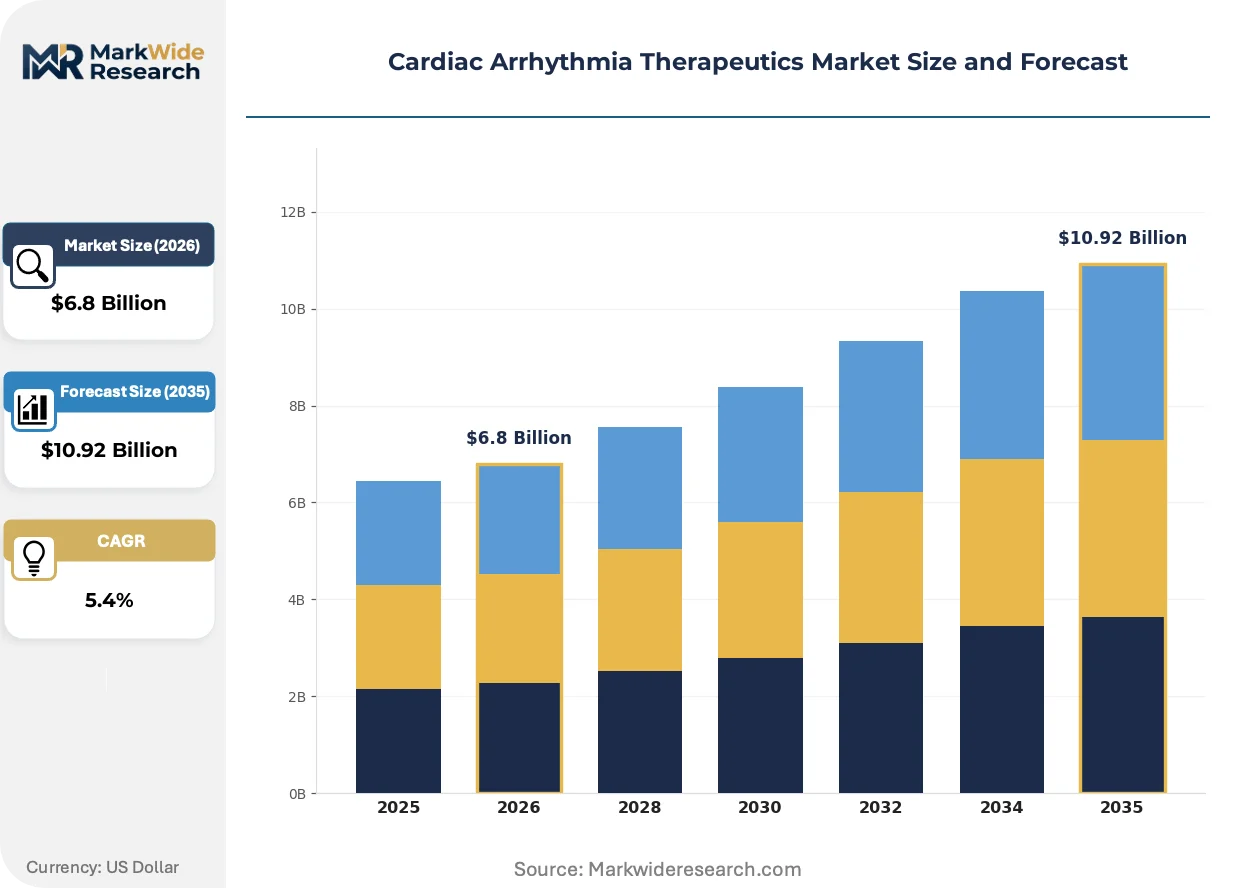
Catheter-based cryoablation technology is rewriting treatment protocols for atrial fibrillation by enabling durable pulmonary vein isolation with shorter learning curves than radiofrequency alternatives. Abbott Laboratories leverages its integrated mapping and ablation ecosystem to anchor electrophysiology lab workflows across North American hospital networks. Medtronic sustains R&D intensity in cryoballoon iterations, while Boston Scientific competes through differentiated pulsed field ablation platforms.
Cardiac arrhythmia therapeutics encompass pharmacological agents, interventional catheters, and implantable devices that restore normal cardiac rhythm through ion-channel modulation, targeted tissue destruction, or electrical pacing. Antiarrhythmic drugs function through sodium, potassium, or calcium channel blockade with specific Class I-IV mechanisms, while catheter ablation delivers thermal or electrical energy to arrhythmogenic substrates. Implantable devices capture the largest margin pool due to recurring generator replacement cycles and remote monitoring subscriptions. Catheter ablation represents the fastest-expanding segment as procedural volumes shift from antiarrhythmic drug dependence toward durable interventional solutions.
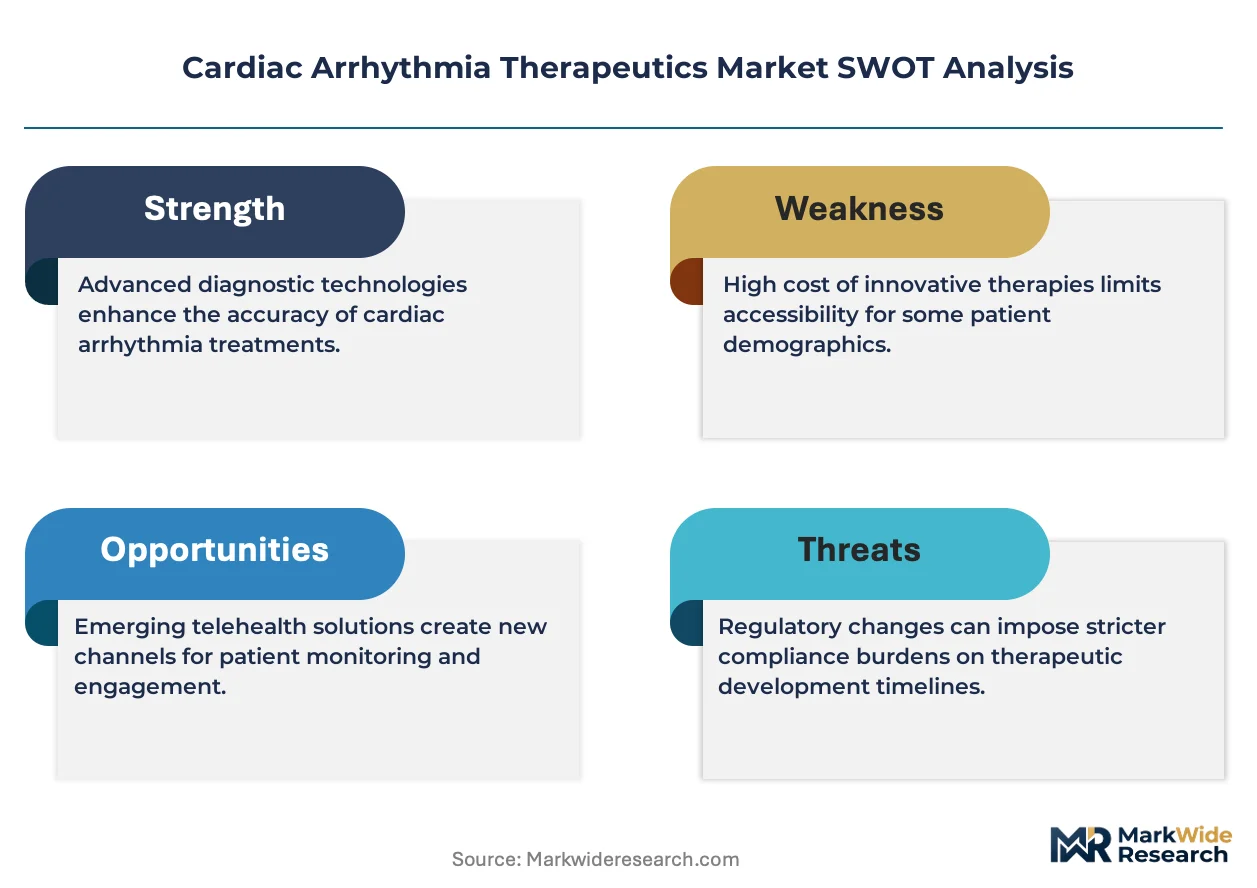
The FDA's breakthrough device program and the European Medicines Agency's PRIority MEdicines scheme jointly compress development timelines for next-generation ablation platforms. Japan's Pharmaceuticals and Medical Devices Agency maintains stringent post-market surveillance requirements that shape product reliability standards for devices entering Asian markets. Stakeholders must monitor how pulsed field ablation safety data influences regulatory labeling and reimbursement decisions across major health technology assessment bodies.
Market Dynamics
Pulsed field ablation technology is compressing the treatment paradigm for atrial fibrillation by delivering irreversible electroporation with reduced collateral thermal damage, forcing incumbent catheter manufacturers to accelerate platform transitions or cede electrophysiology lab share.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway compresses review timelines for novel ablation catheters, enabling earlier commercialization of next-generation energy modalities in United States hospital networks.
- Aging Demographics in Japan:The country's super-aged population structure expands the addressable patient pool for rhythm management procedures beyond current catheter lab capacity.
- Cryoballoon Learning Curve Efficiency:Pulmonary vein isolation using single-shot cryothermal energy reduces operator training duration compared to point-by-point radiofrequency techniques, accelerating adoption in community hospital settings.
Market Restraints
- Platinum-Iridium Electrode Supply Concentration:Mining and refining of catheter electrode materials concentrates in South African and Russian supply corridors, exposing manufacturers to geopolitical input volatility.
- CE Marking Under MDR:The European Union's Medical Device Regulation imposes extended clinical evidence requirements for legacy ablation systems, delaying market re-entry for updated product iterations.
- Antiarrhythmic Drug Substitution:Generic amiodarone and sotalol formulations retain formulary preference in cost-constrained health systems, limiting procedural migration toward interventional solutions.
Strategic Opportunities
- Underpenetrated Indian Electrophysiology Infrastructure:The country's catheter ablation procedural volume per capita remains one-tenth of Western benchmarks, creating expansion potential for training-consortium business models.
- Remote Monitoring Integration:Convergence of implantable loop recorders with cloud-based arrhythmia detection algorithms enables subscription revenue streams decoupled from device replacement cycles.
- Japan PMDA Sakigake Pathway:The regulator's priority review scheme for innovative medical devices accelerates approval timelines for first-in-class ablation technologies entering Asian markets.
Industry Challenges
- Electrophysiologist Training Pipeline:The specialized fellowship pathway produces fewer than four hundred new operators annually in the United States, constraining procedural volume expansion regardless of catheter availability.
- Generator Replacement Cycle Compression:Extended battery longevity in newer implantable cardioverter-defibrillator platforms elongates replacement intervals, pressuring recurring revenue models.
- Interoperability with Legacy Mapping Systems:New ablation catheters must maintain backward compatibility with installed base cartography hardware, adding firmware validation burden to product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Arrhythmia Therapeutics Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiarrhythmic Drugs, Catheter Ablation, Implantable Devices, Monitoring Systems End User: Hospitals, Specialty Clinics, Home Healthcare, Research Laboratories Delivery Mode: Oral, Injectable, Transdermal, Implantable Technology: Radiofrequency, Cryoablation, Electrical Stimulation, Electrophysiology |
| Companies Covered | Abbott Laboratories, Pfizer, Medtronic, Teva Pharmaceutical Industries, Sanofi, Johnson & Johnson MedTech, AtriCure, Novartis, Boston Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Arrhythmia Therapeutics Market Strategic Shifts
Energy delivery modalities for cardiac tissue modification are fragmenting across thermal, cryogenic, and electrical domains, with each approach optimizing for specific anatomical targets and complication risk profiles. This diversification is reshaping capital allocation across electrophysiology portfolios.
Radiofrequency ablation with contact-force sensing is hybridizing with impedance-based lesion assessment to create closed-loop energy titration systems. Academic medical centers in Germany and the Netherlands are deploying these integrated platforms for complex atrial flutter substrates. The technology is compressing the gap between operator experience levels by standardizing lesion creation endpoints.
The European Medicines Agency's PRIority MEdicines scheme is accelerating access to novel antiarrhythmic pharmacotherapies by enabling parallel scientific advice and accelerated assessment pathways. This regulatory tailwind is redirecting venture funding toward ion-channel modulators with improved safety margins compared to legacy Class III agents. Small-molecule developers targeting atrial-selective potassium channels are prioritizing European pivotal trial designs to leverage the scheme.
Hospital procurement committees are consolidating vendor relationships around integrated mapping-ablation ecosystems rather than maintaining multi-manufacturer catheter inventories. This concentration is displacing standalone device suppliers from electrophysiology lab contracts in United States integrated delivery networks. The shift is most pronounced in systems operating under bundled payment arrangements for atrial fibrillation ablation procedures.
Cardiac Arrhythmia Therapeutics Market Segmentation
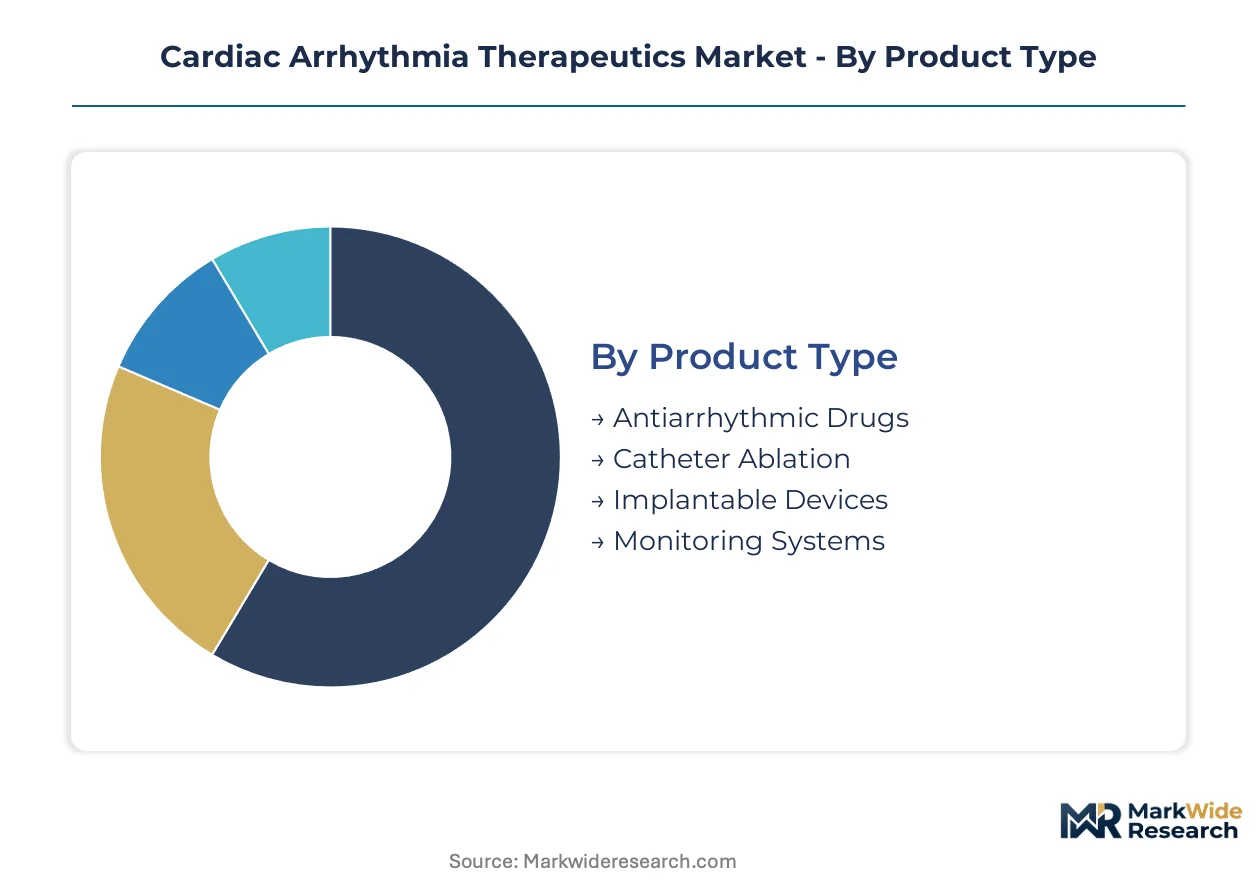
Cardiac arrhythmia therapeutics fragment across intervention intensity, from chronic pharmacological management to one-time catheter-based tissue destruction. Each segment carries distinct margin profiles, reimbursement pathways, and competitive dynamics that shape portfolio allocation decisions.
Product Type:
Clinical workflows span the spectrum from outpatient drug titration to inpatient electrophysiology lab procedures, with each modality optimizing for durability, reversibility, or cost containment.
- Antiarrhythmic Drugs:Small-molecule ion-channel modulators administered chronically to suppress arrhythmia recurrence through Class I-IV mechanisms. Demand concentrates in Germany and Japan where formulary structures favor step-care pharmacology before procedural escalation, though generic substitution compresses branded pricing power.
- Catheter Ablation:Minimally invasive delivery of thermal, cryogenic, or electrical energy to arrhythmogenic substrates via transvenous access. United States hospital networks are expanding lab capacity fastest, driven by favorable DRG reimbursement for atrial fibrillation procedures and shorter recovery trajectories versus repeat cardioversion.
- Implantable Devices:Pacemakers and implantable cardioverter-defibrillators providing rhythm restoration or termination through programmed electrical stimulation.
- Monitoring Systems:External and implantable diagnostic platforms capturing ambulatory electrocardiographic data for arrhythmia detection and burden quantification.
The dominant share belongs to Implantable Devices, while Catheter Ablation is closing the gap fastest.
End User:
Care setting determines capital intensity, staffing requirements, and reimbursement capture, with acute facilities commanding procedural revenue and outpatient sites managing chronic therapy.
- Hospitals:Integrated delivery networks housing electrophysiology labs, cardiac catheterization suites, and surgical backup for complication management. United States health systems are consolidating arrhythmia care into high-volume centers of excellence to meet accreditation standards and optimize outcomes data for bundled payment negotiations.
- Specialty Clinics:Dedicated cardiac rhythm management facilities offering device interrogation, medication management, and selective ablation services. Germany's office-based specialist sector is expanding fastest, enabled by statutory reimbursement for ambulatory electrophysiology procedures and proximity to aging suburban populations.
- Home Healthcare:Remote monitoring infrastructure and visiting nurse services supporting post-procedural recovery and chronic disease management.
- Research Laboratories:Academic and contract research sites conducting pivotal trials for novel antiarrhythmic modalities.
Hospitals retain the largest revenue concentration, though Specialty Clinics are expanding their procedural footprint most aggressively.
Delivery Mode:
Pharmacokinetic requirements and treatment duration dictate route selection, with chronic suppression favoring convenience and acute termination demanding rapid bioavailability.
- Oral:Tablet and capsule formulations enabling outpatient chronic administration of Class I-IV antiarrhythmics. Japan's aging population drives volume here, with PMDA-approved extended-release formulations improving adherence in polypharmacy regimens.
- Injectable:Intravenous agents for acute rhythm termination or peri-procedural management in monitored settings. United States emergency departments and electrophysiology labs represent the core demand cluster, with amiodarone and ibutilide retaining formulary dominance.
- Transdermal:Patch-based delivery systems for sustained antiarrhythmic absorption.
- Implantable:Drug-device combination products and reservoir-based systems integrated with pacing hardware.
Oral administration captures the highest prescription volume, while Injectable formats command the steepest expansion trajectory in procedural settings.
Technology:
Energy delivery mechanisms differentiate on tissue specificity, collateral damage risk, and procedural efficiency, with each platform targeting distinct anatomical substrates.
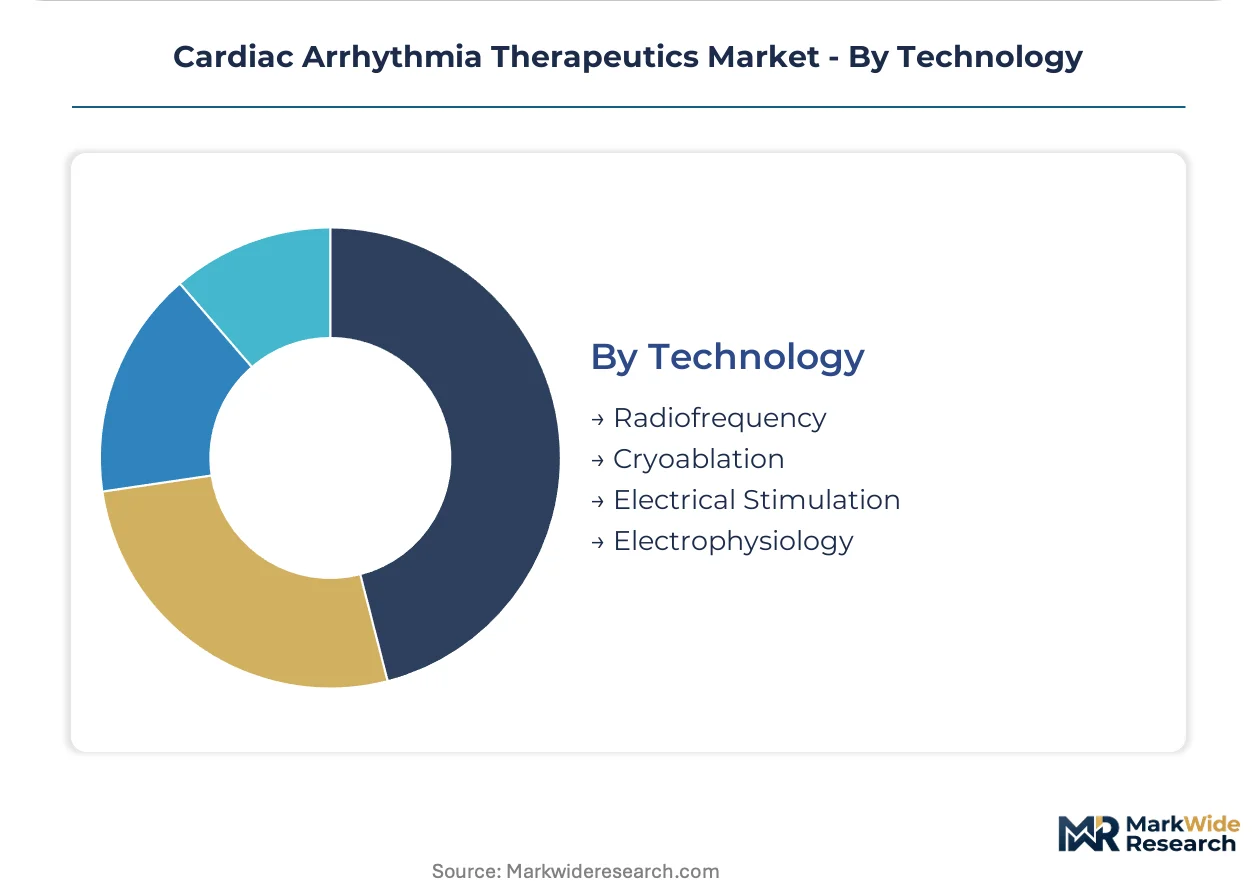
- Radiofrequency:Resistive heating via catheter-tip electrodes with contact-force sensing and impedance monitoring for lesion control. German academic medical centers are deploying next-generation closed-loop systems for complex atrial flutter, standardizing outcomes across operator experience levels.
- Cryoablation:Nitrous oxide-mediated cryothermal energy delivered through balloon or focal catheters for pulmonary vein isolation. United States community hospitals are adopting single-shot cryoballoon platforms fastest, drawn to shorter learning curves and reproducible lesion sets versus point-by-point techniques.
- Electrical Stimulation:Programmed pacing protocols and high-voltage shocks for arrhythmia termination via implantable or external devices.
- Electrophysiology:Three-dimensional mapping and diagnostic catheter systems for substrate characterization and procedural navigation.
Radiofrequency platforms hold the largest installed base, though Cryoablation is gaining share fastest in community hospital expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German catheter ablation system manufacturers export cryoballoon platforms to United States hospital networks, while Japanese implantable device producers supply cardiac rhythm management hardware across Asia-Pacific markets. Trade corridors concentrate high-value electrophysiology equipment flows between these three manufacturing hubs and their respective buyer geographies.
United States
FDA breakthrough device designations compress review timelines for pulsed field ablation catheters, accelerating commercialization of next-generation energy modalities. Hospital-based electrophysiology labs in Texas and Florida are expanding procedural capacity fastest, driven by favorable DRG reimbursement for atrial fibrillation interventions. The Cleveland Clinic and Mayo Clinic anchor multi-site training consortiums that standardize operator certification across community hospital networks.
Germany
Statutory reimbursement for ambulatory electrophysiology procedures enables office-based specialist expansion in suburban Munich and Hamburg corridors. EMA's PRIority MEdicines scheme accelerates access to novel antiarrhythmic pharmacotherapies through parallel scientific advice pathways. The Rhine-Ruhr medical technology cluster houses integrated mapping-ablation ecosystem manufacturers serving Benelux and Nordic export markets.
Japan
PMDA's Sakigake priority review scheme compresses approval timelines for first-in-class ablation technologies entering domestic markets. METI funding supports cryoballoon catheter production scale-up in the Kansai region to address super-aged population procedural demand. Osaka-based electrophysiology training centers are expanding fellowship pipelines to offset operator shortage constraints.
India
Central Drugs Standard Control Organization streamlined medical device registration pathways for ablation catheters under the 2017 Medical Device Rules. Maharashtra and Karnataka host the fastest-expanding private hospital electrophysiology lab networks, with Mumbai and Bangalore anchoring training-consortium partnerships with United States academic medical centers. Procedural volume per capita remains one-tenth of Western benchmarks, creating infrastructure expansion potential.
Switzerland
Swissmedic maintains stringent post-market surveillance requirements that shape product reliability standards for devices entering European markets. Basel and Zurich house pharmaceutical development operations targeting atrial-selective potassium channel modulators. The country's bilateral mutual recognition agreements with the European Union facilitate streamlined CE marking transitions for ablation platform manufacturers.
Cardiac Arrhythmia Therapeutics Market Competitive Environment
Channel-controlling players compete with product-specialist players across catheter ablation, implantable devices, and antiarrhythmic drug segments. The market structure concentrates around diversified medical technology conglomerates with integrated electrophysiology ecosystems, while mid-scale pharmaceutical developers occupy ion-channel modulator niches. Three archetypes dominate: full-stack platform vendors, component-specialist suppliers, and generic drug manufacturers. M&A activity targets mapping system interoperability capabilities, while geographic expansion focuses on underpenetrated Asian procedural markets.
Among diversified medical technology conglomerates, Abbott Laboratories, Medtronic, and Boston Scientific occupy positions as archetypal platform vendors with integrated mapping-ablation ecosystems. These entities exemplify the channel-control strategy through electrophysiology lab workflow anchoring. Johnson & Johnson MedTech and AtriCure represent the procedural solutions tier, while Pfizer, Novartis, Sanofi, and Teva Pharmaceutical Industries sit within the pharmaceutical developer archetype focused on chronic rhythm suppression therapies.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Pfizer |
| Medtronic |
| Teva Pharmaceutical Industries |
| Sanofi |
| Johnson & Johnson MedTech |
| AtriCure |
| Novartis |
| Boston Scientific |
| Others |
Value Chain & Pricing Dynamics
South African platinum-iridium mining corridors anchor electrode material costs for catheter ablation systems, concentrating margin capture with refiners and forcing device manufacturers to absorb volatility or pass through to hospital procurement committees. This upstream chokepoint shapes downstream pricing power across cryoballoon and pulsed field ablation platforms.
Pricing Analysis
Next-generation pulsed field ablation catheters command premium positioning against radiofrequency and cryothermal alternatives, with price differentiation driven by FDA breakthrough designation tier and operator training bundling. Three-tier pricing structure across premium, standard, and economy levels separates integrated mapping-ablation ecosystems from standalone catheter suppliers. Cost compression in standard-tier radiofrequency systems is intensifying because generic device competition and GPO contract consolidation. Community hospital networks exhibit highest price sensitivity, while academic medical centers prioritize outcomes data and workflow integration over per-procedure cost.
Supply Chain Analysis
US export controls on advanced semiconductor components for electrophysiology mapping systems limit hardware flows to Chinese and Russian hospital networks, reshaping supplier geographic priorities. Manufacturing concentrates in the United States, Germany, and Japan for catheter fabrication and mapping console assembly. Raw material dependencies span platinum-iridium electrodes, nitrous oxide cryogen canisters, and specialized catheter polymers. Single-source vulnerability runs through South African precious metal refining. Distribution runs through integrated delivery network procurement committees and specialized cardiac device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensive moats in cardiac arrhythmia therapeutics rest on regulatory entrenchment, where FDA breakthrough designations and PMDA Sakigake approvals create multi-year lead times for competitive platform replication.
For Market Incumbents: Pre-empt pulsed field ablation substitution by accelerating cryoballoon-to-PFA catheter compatibility within installed mapping ecosystems. Secure backward integration into electrode material refining to offset South African supply volatility. Channel control through electrophysiology lab workflow anchoring remains the priority lever against standalone device competitors. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated catheter ablation infrastructure through training-consortium partnerships with Mumbai and Bangalore hospital networks. Target ambulatory electrophysiology procedures in Germany's office-based specialist sector where statutory reimbursement enables faster adoption cycles. Lead with remote monitoring integration as a software-subscription wedge against hardware-incumbent pricing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mapping system specialists holding interoperability firmware capabilities. Five-to-ten year viability hinges on pulsed field ablation safety data maturation and subsequent reimbursement expansion. Watch FDA labeling decisions for irreversible electroporation platforms as the inflection signal for platform transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Pulsed Field Ablation FDA Submission | Breakthrough pathway compresses review timelines for next-generation energy modalities entering United States hospital networks. |
| CE Marking Pathway Under MDR | Extended clinical evidence requirements for legacy systems delay re-entry, favoring first-mover PFA platforms in European markets. |
| Hospital System Partnership | Integrated delivery network consolidation around single-vendor ecosystems displaces standalone catheter suppliers from procurement contracts. |
| Software Companion Development | Cloud-based arrhythmia detection algorithms enable recurring subscription revenue decoupled from hardware replacement cycles. |
| Reimbursement Strategy | DRG optimization for atrial fibrillation procedures drives procedural volume expansion in Texas and Florida hospital networks. |
Study Parameters
Initial hypotheses were tested against primary input from electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation. Sources included FDA 510(k) filings, PMDA approval databases, CMS Medicare procedure data, and hospital procurement records. Bottom-up procedural volume estimates triangulated with top-down market sizing across the analysis window.
Demand-supply balance modeling anchored forecasts, with segmentation across product type, end user, delivery mode, and energy delivery technology. CAGRs derived from procedural volume trajectories, reimbursement rate assumptions, and technology substitution curves. Forecast inputs incorporated electrophysiologist training pipeline constraints and generator replacement cycle elongation effects.
Sensitivities concentrate around pulsed field ablation safety data maturation, platinum-iridium supply disruptions, and electrophysiologist workforce expansion rates. Forecasts reflect documented assumptions on technology adoption curves and regulatory pathway timelines. Material shifts in FDA labeling for irreversible electroporation or PMDA Sakigake priority review criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Heart Transplant Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Tachycardia Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Endocarditis Therapeutics Market