
 Primary Biliary Cholangitis (PBC) Treatment Market | 2026-2036
Primary Biliary Cholangitis (PBC) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Biliary Cholangitis (PBC) Treatment Market Analytics
Second-line therapy eligibility criteria is reorganizing how prescribers sequence PBC pharmacotherapy across major markets. AbbVie leverages its immunology infrastructure to sustain hepatology specialist access in North America and Europe. Intercept Pharmaceuticals anchors the obeticholic acid segment through regulatory exclusivity and hepatology KOL relationships. Mirum Pharmaceuticals differentiates via its ileal bile acid transporter inhibitor portfolio, competing for treatment-resistant patient populations.
Primary biliary cholangitis treatment encompasses pharmaceutical interventions targeting autoimmune-mediated destruction of intrahepatic bile ducts, with ursodeoxycholic acid serving as the first-line standard at 13-15 mg/kg daily dosing to improve liver enzyme profiles and delay histological progression. The therapeutic objective centers on normalizing alkaline phosphatase and bilirubin levels to prevent cirrhosis and transplant need. Oral delivery mode dominates prescription volumes due to patient preference and chronic administration requirements, though infusion protocols persist for hospitalized decompensated cases. Ursodeoxycholic acid retains volume leadership as the established first-line standard, while obeticholic acid and emerging fibrate combinations capture the fastest expansion in second-line settings where alkaline phosphatase remains elevated.
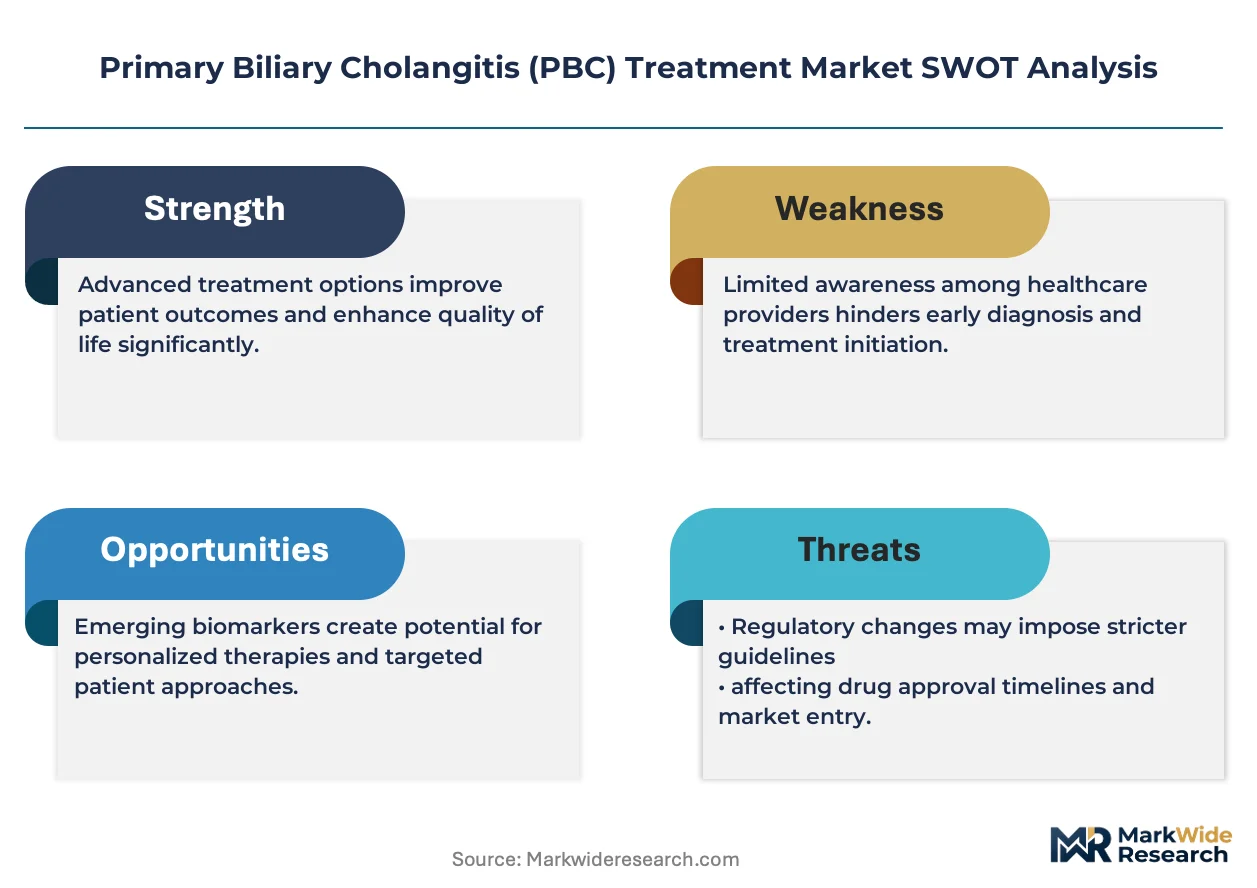
FDA orphan drug designations and EMA conditional marketing authorizations shape clinical trial investment and pricing flexibility for developers targeting treatment-resistant PBC populations. The Drug Enforcement Administration and state pharmacy boards additionally govern controlled-substance handling where applicable adjunct therapies intersect with scheduled compounds. Stakeholders must monitor how CMS national coverage determination reviews and European health technology assessment convergence will reshape reimbursement thresholds for novel mechanisms entering the PBC pipeline.
Market Dynamics
FDA and EMA accelerated approval pathways for orphan indications are restructuring competitive entry sequencing, enabling novel bile acid modulators to reach treatment-resistant patient populations ahead of traditional timelines.
Growth Catalysts
- Orphan drug incentives:FDA's seven-year exclusivity provisions and tax credits for clinical trial costs incentivize developers to pursue PBC indications despite limited prevalence.
- Hepatology clinic consolidation:Specialist referral networks in the United States concentrate prescriber influence, accelerating second-line therapy adoption through protocol standardization.
- Biomarker validation:Alkaline phosphatase normalization as a surrogate endpoint is compressing trial duration and enabling conditional approvals.
Market Restraints
- Input cost volatility:Bile acid derivative synthesis depends on sterol precursors subject to agricultural commodity fluctuations and pharmaceutical-grade extraction constraints.
- Regulatory friction:EMA conditional marketing authorizations impose post-approval efficacy commitments that extend commercial risk exposure beyond launch.
- Substitution threat:Fibrate combinations with ursodeoxycholic acid offer off-label alternatives that limit pricing power for novel mechanisms.
Strategic Opportunities
- Underpenetrated geographies:Japan's hepatology infrastructure under PMDA guidance presents whitespace for ileal bile acid transporter inhibitors as second-line standards.
- Regulatory tailwinds:CMS national coverage determination reviews for novel mechanisms may expand Medicare reimbursement beyond current prior authorization barriers.
- Technology convergence:Non-invasive fibrosis scoring algorithms combined with pharmacogenomic profiling enable personalized sequencing of bile acid therapies.
Industry Challenges
- Talent scarcity in hepatology commercialization:Rare disease expertise for PBC requires specialized medical science liaison capabilities that compete with broader immunology recruitment.
- Certification timeline compression:EMA health technology assessment convergence demands simultaneous evidence generation for multiple national pricing bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Biliary Cholangitis (PBC) Treatment Market |
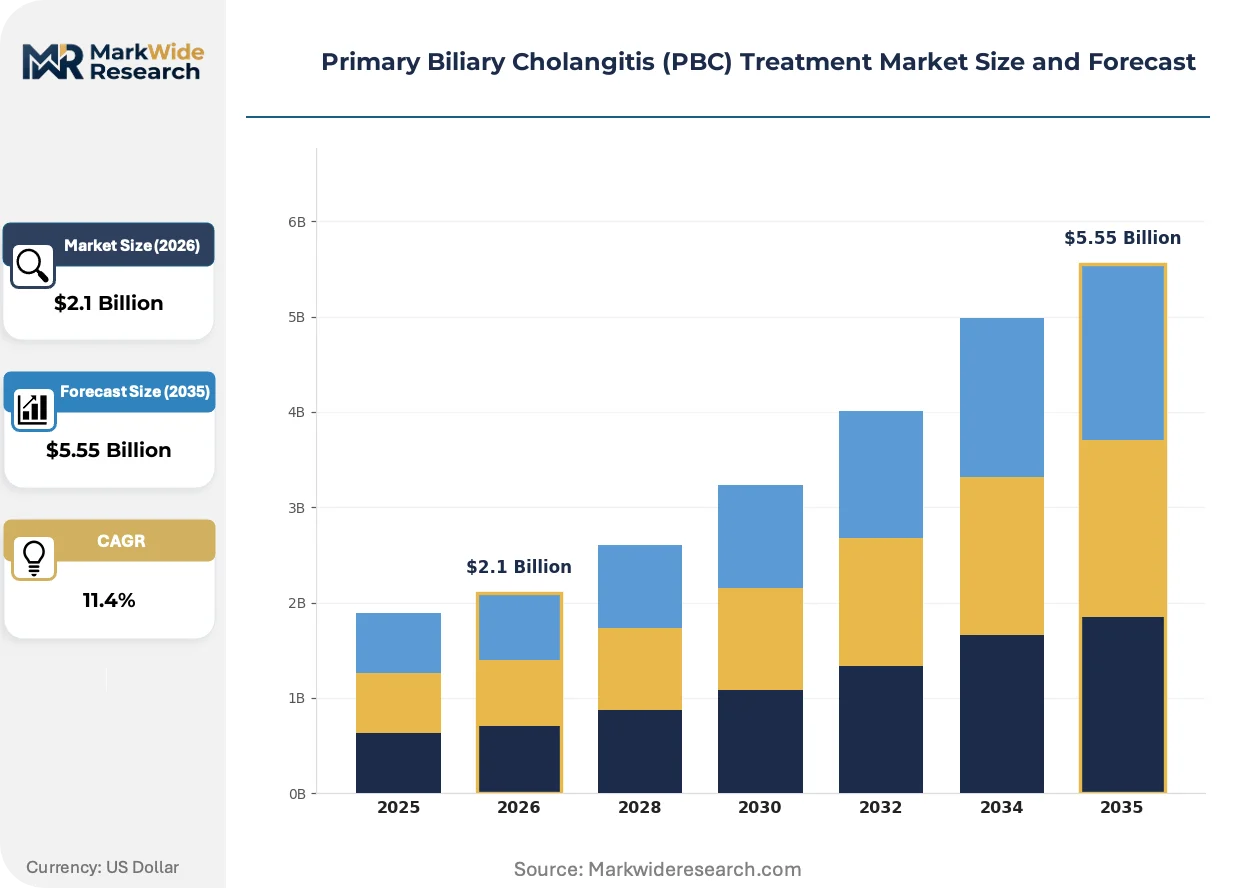
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ursodeoxycholic Acid, Obeticholic Acid, Fibrates, Others Delivery Mode: Oral, Injectable, Infusion, Others End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Indication: Chronic Liver Disease, Cholestatic Liver Disease, Autoimmune Disorders, Hepatic Failure |
| Companies Covered | AbbVie, Zydus Therapeutics, Intercept Pharmaceuticals, Mirum Pharmaceuticals, GSK (GlaxoSmithKline), Gilead Sciences, Teva Pharmaceutical Industries, Calliditas Therapeutics, Ipsen Biopharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Biliary Cholangitis (PBC) Treatment Market Evolving Landscape
Pharmaceutical intervention patterns in PBC are pivoting toward mechanism-based patient stratification, with prescriber protocols distinguishing responders from non-responders earlier in treatment sequencing.
FibroScan-based liver stiffness measurement is decomposing the traditional reliance on repeated biopsy for histological staging. Hepatology clinics in Germany and France deploy transient elastography at point-of-care to monitor treatment response without invasive procedures. This technology is decomposing the biopsy bottleneck that previously delayed second-line therapy initiation.
EMA's conditional marketing authorization framework for orphan indications compresses approval timelines while mandating post-marketing outcome studies. Developers must commit to long-term efficacy registries that extend evidence generation costs beyond launch. The obeticholic acid segment operates under these constraints, with renewal contingent on confirmed clinical benefit.
Specialist pharmacy distribution models are displacing traditional retail channels for PBC therapies. Accrediting bodies enforce cold-chain and patient counseling standards that concentrate fulfillment through limited networks. This channel consolidation is most pronounced in the United States, where prior authorization reform ties reimbursement to specialty pharmacy engagement.
Primary Biliary Cholangitis (PBC) Treatment Market Segmentation
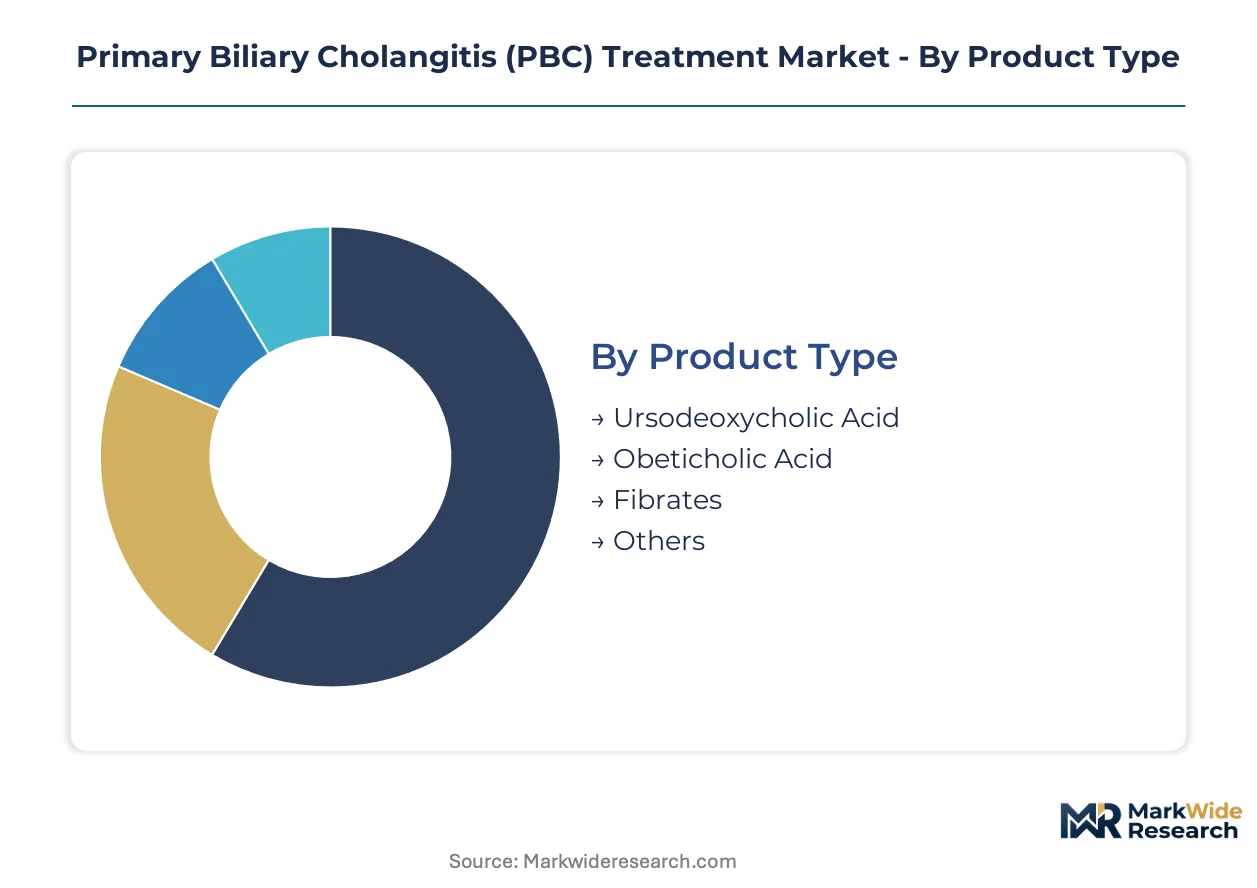
Mechanism-based patient stratification in PBC pharmacotherapy demands precise segmentation across therapeutic classes and care settings. Prescribers sequence treatments based on alkaline phosphatase response profiles, creating distinct commercial pockets within each category.
Product Type:
Margin pools concentrate in second-line therapies where prior authorization requirements and orphan drug pricing create premium capture opportunities.
- Ursodeoxycholic Acid:The established first-line standard administered at 13-15 mg/kg daily dosing to improve liver enzyme profiles and delay histological progression. Volume leadership in the United States and Germany sustains this segment through protocol standardization in hepatology referral networks, though generic competition compresses per-unit economics.
- Obeticholic Acid:A farnesoid X receptor agonist capturing premium positioning in treatment-resistant populations where alkaline phosphatase remains elevated despite first-line therapy. EMA conditional marketing authorization and FDA orphan exclusivity in North America and Europe enable pricing power, with hepatology KOL relationships driving formulary placement.
- Fibrates:Off-label combinations with ursodeoxycholic acid offer cost-sensitive alternatives that limit novel mechanism uptake in budget-constrained markets.
- Others:Emerging ileal bile acid transporter inhibitors and combination therapies under clinical investigation.
Ursodeoxycholic Acid holds installed capacity. Obeticholic Acid is rotating up the share rankings.
Delivery Mode:
Patient preference for chronic administration drives volume concentration toward routes minimizing clinical burden.
- Oral:Dominates prescription volumes through tablet and capsule formulations enabling self-administration at home. Hepatology clinics in the United States and France prioritize oral sequencing to maintain compliance in decompensated patients, with specialty pharmacy networks handling fulfillment under cold-chain standards where required.
- Injectable:Limited to clinical settings for acute exacerbations or hospitalized cases requiring rapid intervention.
- Infusion:Reserved for decompensated hepatic failure requiring inpatient monitoring.
- Others:Investigational depot formulations and transdermal approaches in early development.
Oral delivery holds installed capacity. Infusion protocols are rotating up the share rankings in acute care settings.
End User:
Care site economics determine reimbursement complexity and patient access speed.
- Hospitals:Anchor acute decompensation management and transplant evaluation pathways. Major academic medical centers in the United States and Germany concentrate second-line therapy initiation through integrated hepatology-nephrology protocols.
- Clinics:Hepatology specialist offices drive maintenance therapy decisions and biomarker monitoring via FibroScan deployment.
- Homecare Settings:Expanding for stable patients on established oral regimens with telemedicine oversight.
- Rehabilitation Centers:Limited role in post-transitional care for recovering patients.
Hospitals hold installed capacity. Clinics are rotating up the share rankings as point-of-care diagnostics expand.
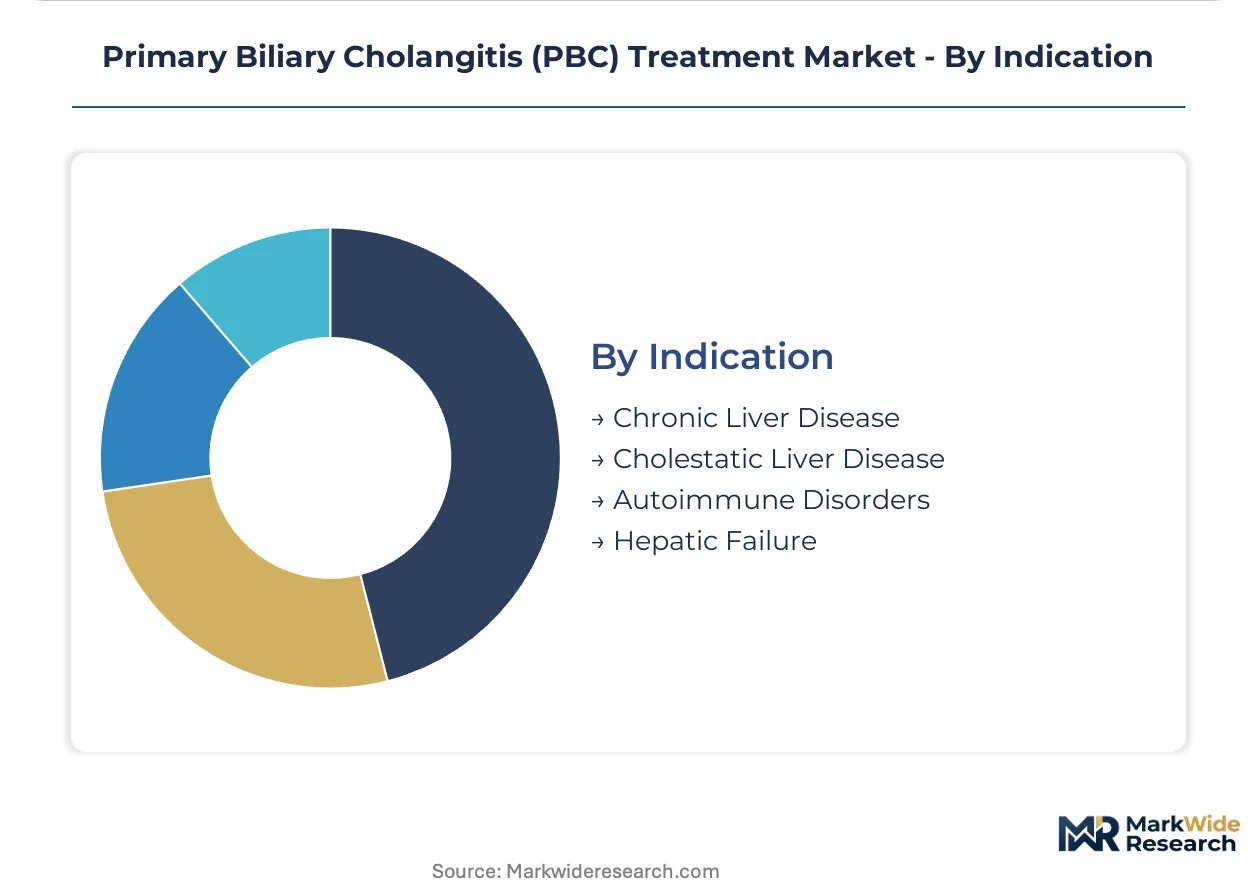
Indication:
Diagnostic coding specificity shapes prior authorization success and coverage determination speed.
- Chronic Liver Disease:Broad diagnostic category capturing longitudinal management of progressive fibrosis. Medicare coverage determinations in the United States and NHS England pathway guidelines concentrate prescribing authority for this indication within hepatology specialist networks.
- Cholestatic Liver Disease:Precise coding enabling orphan drug reimbursement and accelerated approval leverage.
- Autoimmune Disorders:Overlapping comorbidity profiles requiring immunology-hepatology coordination.
- Hepatic Failure:Acute escalation segment with highest per-patient cost burden.
Chronic Liver Disease holds installed capacity. Cholestatic Liver Disease is rotating up the share rankings as diagnostic specificity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for ursodeoxycholic acid raw materials shapes procurement strategies across major markets, while export-oriented API manufacturing clusters in Asia supply formulation sites in North America and Europe. Hepatology specialist density and reimbursement pathways determine where novel bile acid modulators achieve commercial traction first.
United States
Specialist referral networks concentrate prescriber influence within academic medical centers in Boston, Philadelphia, and the Research Triangle. FDA orphan drug exclusivity provisions accelerate market entry timelines for developers targeting treatment-resistant populations. The Mayo Clinic Rochester and Cleveland Clinic anchor second-line therapy protocol development through integrated hepatology-transplant programs.
Germany
FibroScan deployment in hepatology clinics enables non-invasive treatment monitoring that compresses second-line therapy initiation timelines. EMA conditional marketing authorization frameworks impose post-approval efficacy commitments that extend commercial risk exposure. The Rhine-Ruhr metropolitan region concentrates hepatology specialist practices with established ursodeoxycholic acid prescribing protocols.
Japan
PMDA guidance on orphan hepatology indications creates whitespace for ileal bile acid transporter inhibitors as second-line standards mature. Domestic pharmaceutical procurement prioritizes local clinical trial data for formulary inclusion decisions. The Kanto region surrounding Tokyo anchors hepatology research infrastructure and specialist training programs.
United Kingdom
NHS England pathway guidelines concentrate prescribing authority for chronic liver disease within designated hepatology specialist networks. NICE technology appraisals determine reimbursement thresholds for novel mechanisms entering the PBC pipeline. The Greater Manchester and London hepatology clusters drive biomarker validation studies for alkaline phosphatase normalization endpoints.
Switzerland
Swissmedic accelerated review pathways for orphan indications attract developers seeking concurrent EMA submission strategies. Premium pricing acceptance for hepatology therapies supports commercial viability despite limited prevalence. The Basel pharmaceutical cluster anchors regulatory strategy functions for bile acid modulator developers.
Primary Biliary Cholangitis (PBC) Treatment Market Competitive Landscape
Listed leaders compete with private specialists across hepatology commercialization capabilities, with publicly traded pharmaceutical companies leveraging immunology infrastructure against focused rare disease developers. The market structure concentrates around three to four entities with established hepatology specialist relationships, while mid-scale developers pursue conditional approval pathways. Strategic archetypes include diversified immunology majors, orphan-focused biotechs, and generic API suppliers. Competitive moves center on hepatology KOL network cultivation and regulatory exclusivity maintenance rather than manufacturing scale.
Within the orphan-focused tier, Intercept Pharmaceuticals and Mirum Pharmaceuticals exemplify developers pursuing conditional marketing authorization pathways for treatment-resistant populations. AbbVie anchors the diversified immunology major archetype, leveraging existing specialist access infrastructure across North American and European hepatology networks. GSK occupies a position bridging primary care and specialist channels through its established gastrointestinal portfolio.
| Leading Market Players |
|---|
| AbbVie |
| Zydus Therapeutics |
| Intercept Pharmaceuticals |
| Mirum Pharmaceuticals |
| GSK (GlaxoSmithKline) |
| Gilead Sciences |
| Teva Pharmaceutical Industries |
| Calliditas Therapeutics |
| Ipsen Biopharmaceuticals |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day API inventory buffers at European formulation sites concentrate pricing leverage among sterol precursor suppliers in China and India, with hepatology clinics absorbing premium markups for orphan-designated second-line therapies. This lead-time exposure shapes how manufacturers negotiate bile acid derivative contracts and how payers structure prior authorization tiers.
Pricing Analysis
Hospital procurement committees and specialty pharmacy networks anchor a three-tier pricing structure across premium, standard, and economy levels in the PBC treatment landscape. Orphan drug exclusivity provisions and conditional marketing authorizations drive premium capture for novel farnesoid X receptor agonists, while generic ursodeoxycholic acid faces cost compression from Indian API competition. Price differentiation hinges on FDA orphan designation status and hepatology KOL endorsement depth. Pricing pressure stems from fibrate off-label substitution in budget-constrained European markets. Cost-sensitive hospital systems exhibit highest price sensitivity; academic medical centers with transplant programs show lowest sensitivity due to protocol standardization.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for pharmaceutical-grade bile acid extracts, compressing margin buffers at formulation sites. Active pharmaceutical ingredient manufacturing concentrates in China, India, and Italy, with sterol precursor extraction drawing from agricultural commodity streams in Argentina and Spain. Supply chain risk centers on single-source vulnerability for high-purity cholic acid derivatives. Distribution runs through accredited specialty pharmacy networks in the United States and hospital central pharmacies in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA and EMA accelerated approval pathways for orphan hepatology indications are compressing development timelines and reshaping competitive entry sequencing, creating high-growth disruption for developers with biomarker validation capabilities.
For Market Incumbents: Shield formulary position by deepening hepatology KOL relationships and securing conditional renewal commitments ahead of post-marketing study readouts. Backward integration into sterol precursor supply buffers against API cost volatility from agricultural commodity swings. Prioritize regulatory exclusivity maintenance through pediatric investigation plan fulfillment and indication expansion submissions. For New Entrants and Emerging Players: Differentiate on ileal bile acid transporter mechanism novelty to capture treatment-resistant populations where alkaline phosphatase remains elevated. Target Japan's hepatology infrastructure under PMDA guidance as the most penetrable geography with limited incumbent presence. Pursue biomarker-driven trial designs enabling conditional approval leverage ahead of traditional competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across second-line therapy manufacturing as continuous processing replaces batch synthesis for bile acid modulators. Long-term viability favors developers with integrated hepatology commercial infrastructure spanning North America and Europe. Acquisition target archetype: orphan-focused biotechs with conditional marketing authorization and unresolved post-approval commitments. Signal to watch: CMS national coverage determination timing for novel mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Conditional Marketing Authorization Pathway | EMA framework compresses approval timelines while mandating post-marketing efficacy registries extending evidence costs. |
| Hepatology KOL Network Cultivation | Mayo Clinic Rochester and Cleveland Clinic relationships drive second-line protocol standardization across academic medical centers. |
| Specialty Pharmacy Distribution Partnership | Accredited cold-chain networks in the United States tie reimbursement to patient counseling standards and adherence monitoring. |
| Biomarker Validation Investment | Alkaline phosphatase normalization endpoints enable surrogate approval pathways reducing trial duration. |
| Orphan Drug Exclusivity Defense | FDA seven-year provisions block competitor entry for treatment-resistant PBC populations. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists converged on the working assumptions driving this analysis. Primary interviews with hepatology medical science liaisons and hospital procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare coverage determinations. Bottom-up prescription volume modeling and top-down epidemiology-based prevalence estimates underwent triangulation to anchor market sizing.
Segmentation dimensions modeled span treatment line positioning, oral versus parenteral delivery mode, hepatology clinic versus hospital site of care, and regional regulatory cluster typologies. CAGRs derived from log-linear trend fitting across patient flow projections and pricing elasticity assumptions. Forecast inputs incorporated orphan drug incentive uptake rates and conditional marketing authorization renewal probabilities.
Decision-makers should treat outputs as directional under stable regulatory incentive frameworks and biomarker validation continuity; material deviation in FDA orphan exclusivity interpretation or EMA post-approval commitment enforcement would warrant model refresh. Forecasts reflect assumptions regarding hepatology specialist network expansion and prior authorization reform momentum. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Global Liver Cancer Treatment Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Progressive Supranuclear Palsy (PSP) Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Global Thyroid Disorder Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Medical Foods for Orphan Diseases Market