
 Hermansky Pudlak Syndrome Therapeutics Market | 2026-2036
Hermansky Pudlak Syndrome Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Hermansky Pudlak Syndrome Therapeutics Market Foresight
Academic medical centers is collapsing as the dominant buyer archetype while specialty clinics and homecare settings capture larger prescription volumes. Genentech anchors its position through deep R&D intensity in rare disease biologics. Teva Pharmaceuticals competes on manufacturing scale across injectable delivery formats. Bristol-Myers Squibb differentiates through its immunology franchise and established hospital formularies.
Hermansky Pudlak Syndrome therapeutics comprise pharmaceutical and biologic interventions targeting the autosomal recessive disorder characterized by oculocutaneous albinism, bleeding diathesis, and progressive pulmonary fibrosis caused by mutations in HPS1-HPS10 genes; these therapies aim to manage hemorrhagic complications, slow interstitial lung disease progression, and address granulomatous colitis through systemic and localized drug delivery. Gene therapy segments occupy the highest margin pools as developers pursue curative approaches targeting underlying lysosomal trafficking defects. Enzyme replacement therapy segments sustain steady clinical adoption where approved pathways exist for related lysosomal storage disorders. Small molecule agents segments navigate earlier-stage pipelines with focus on pulmonary fibrosis and platelet function modulation.
The FDA Orphan Drug Act and Rare Disease Accelerated Approval pathways shape development economics and commercial exclusivity structures for HPS drug candidates. The EMA's orphan designation framework and PRIME eligibility scheme influence parallel regulatory strategies for European market access. Stakeholders must monitor clinical trial readouts in pulmonary fibrosis modification and gene therapy durability to recalibrate portfolio priorities and partnership timelines.
Market Dynamics
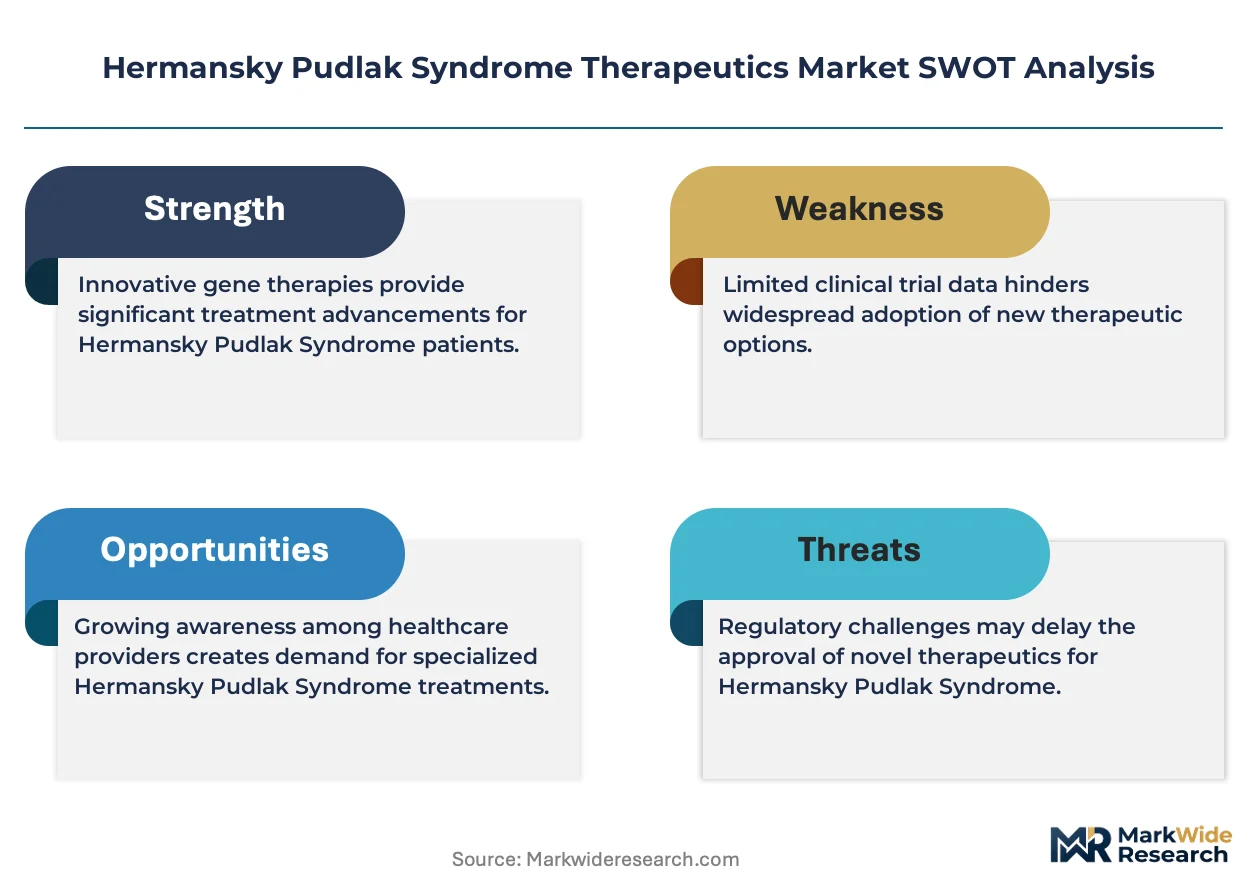
The FDA's Orphan Drug Act incentives and EMA's parallel designation frameworks are compressing development timelines for HPS therapeutics, while gene therapy durability questions and pulmonary fibrosis trial readouts force portfolio recalibration across developers.
Growth Catalysts
- Rare Disease Accelerated Approval:The FDA's pathway compresses Phase II-to-approval timelines for HPS pulmonary fibrosis candidates, enabling earlier revenue recognition for sponsors with surrogate endpoint strategies.
- Specialty Clinic Expansion:Dedicated HPS treatment protocols at academic medical center affiliates concentrate prescriber expertise and streamline patient identification across the United States.
- Lysosomal Trafficking Biology:Advances in understanding AP-3 complex dysfunction enable rational drug design for platelet dense granule biogenesis defects underlying HPS bleeding diathesis.
Market Restraints
- Gene Therapy Manufacturing Bottlenecks:AAV vector production capacity constraints limit batch sizes for HPS1-HPS10 targeting programs, extending patient enrollment windows.
- Small Molecule Attrition:Pulmonary fibrosis candidates targeting TGF-β pathways face high Phase II failure rates due to heterogeneous disease progression in HPS subtypes.
- Reimbursement Complexity:Medicare's National Coverage Determination variability across MAC jurisdictions creates prior authorization friction for infused biologics in rare indications.
Strategic Opportunities
- Home Infusion Infrastructure:Specialty pharmacy networks capable of managing bleeding disorder prophylaxis enable site-of-care migration from hospital outpatient departments.
- Companion Diagnostic Integration:HPS subtype genotyping platforms create prescribing decision support tools that segment addressable populations for targeted therapies.
- European PRIME Eligibility:EMA's scheme provides scientific advice and accelerated assessment pathways that compress regulatory review timelines for HPS candidates with pulmonary endpoints.
Industry Challenges
- Patient Recruitment Density:Ultra-rare prevalence across HPS1-HPS10 subtypes necessitates multi-national trial designs with complex logistics coordination.
- Longitudinal Outcome Measurement:Pulmonary function decline assessment requires standardized six-minute walk test protocols across sites with variable expertise in interstitial lung disease.
- Gene Therapy Durability Surveillance:Extended follow-up commitments for integrating vector safety monitoring strain post-marketing study infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hermansky Pudlak Syndrome Therapeutics Market |
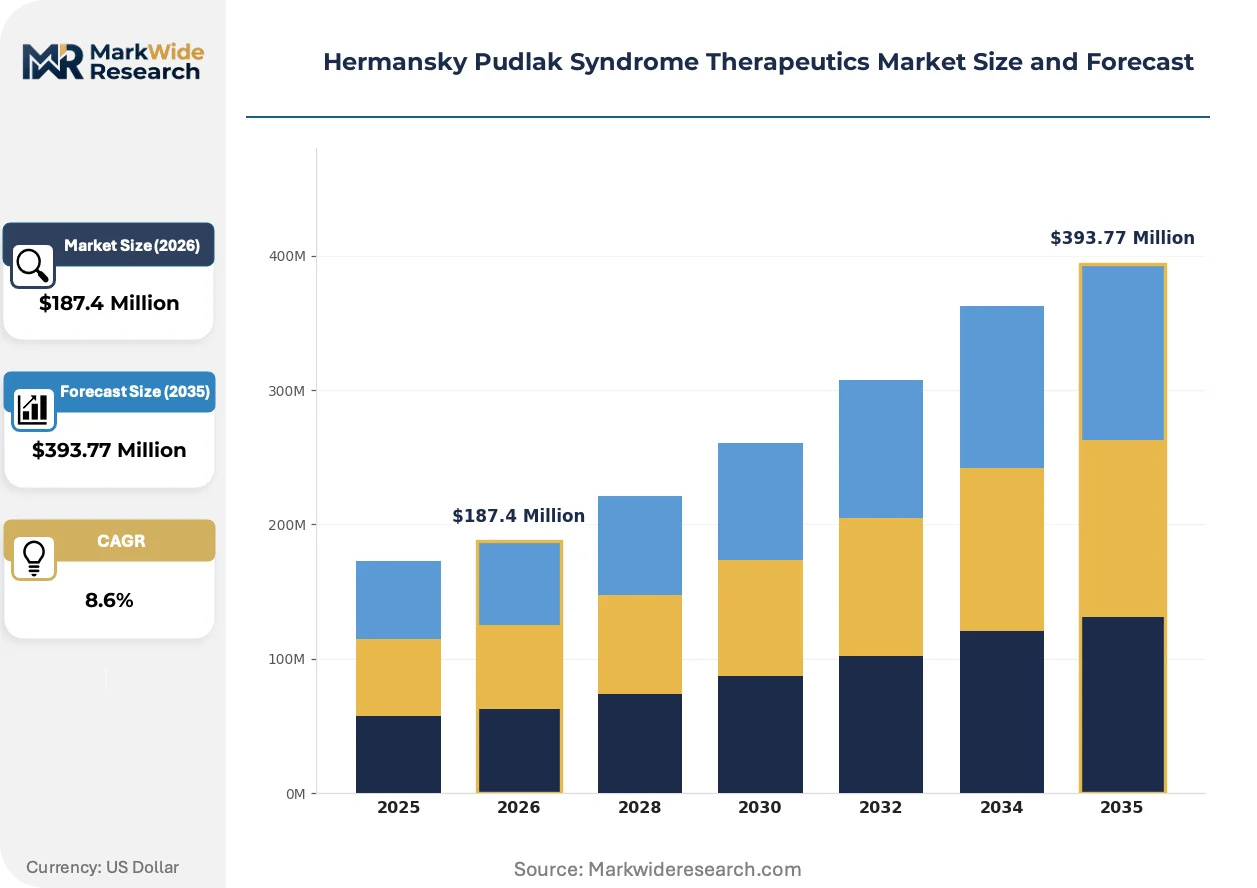
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Enzyme Replacement Therapy, Small Molecule Agents, Supportive Care Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Application: Management of Symptoms, Disease Modification, Psychological Support, Genetic Counseling |
| Companies Covered | Sagent Pharma, Teva Pharmaceuticals, American Regent, Genentech, Ferring Pharmaceuticals, Dr. Reddy's, Sun Pharma, Bristol-Myers Squibb, Gland Pharma Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hermansky Pudlak Syndrome Therapeutics Market Shifts & Advancements
Gene therapy platform maturation and regulatory pathway refinement are compressing development economics for curative HPS interventions, while care delivery models fragment across institutional and home-based settings.
AAV-mediated HPS1 and HPS4 gene transfer approaches are fragmenting the therapeutic landscape previously dominated by supportive care protocols. Academic medical centers with established gene therapy infrastructure are prioritizing these candidates in formulary reviews. The technology is fragmenting prescriber relationships between hematology, pulmonology, and medical genetics specialists competing to manage longitudinal care.
EMA's PRIME eligibility scheme and FDA's Rare Disease Accelerated Approval pathway are creating divergent evidentiary standards for pulmonary fibrosis endpoints. Developers face strategic choices between surrogate biomarker acceptance and hard clinical outcome requirements. European regulators are demanding more robust natural history data, compressing sponsor investment in prospective registries.
Specialty pharmacy distribution is displacing hospital outpatient departments as the dominant channel for bleeding disorder prophylaxis. Payers are mandating site-of-care optimization that shifts infusion administration to home health nursing networks. This channel migration is most visible in United States commercial plans with dedicated rare disease pharmacy benefit managers.
Hermansky Pudlak Syndrome Therapeutics Market Segmentation
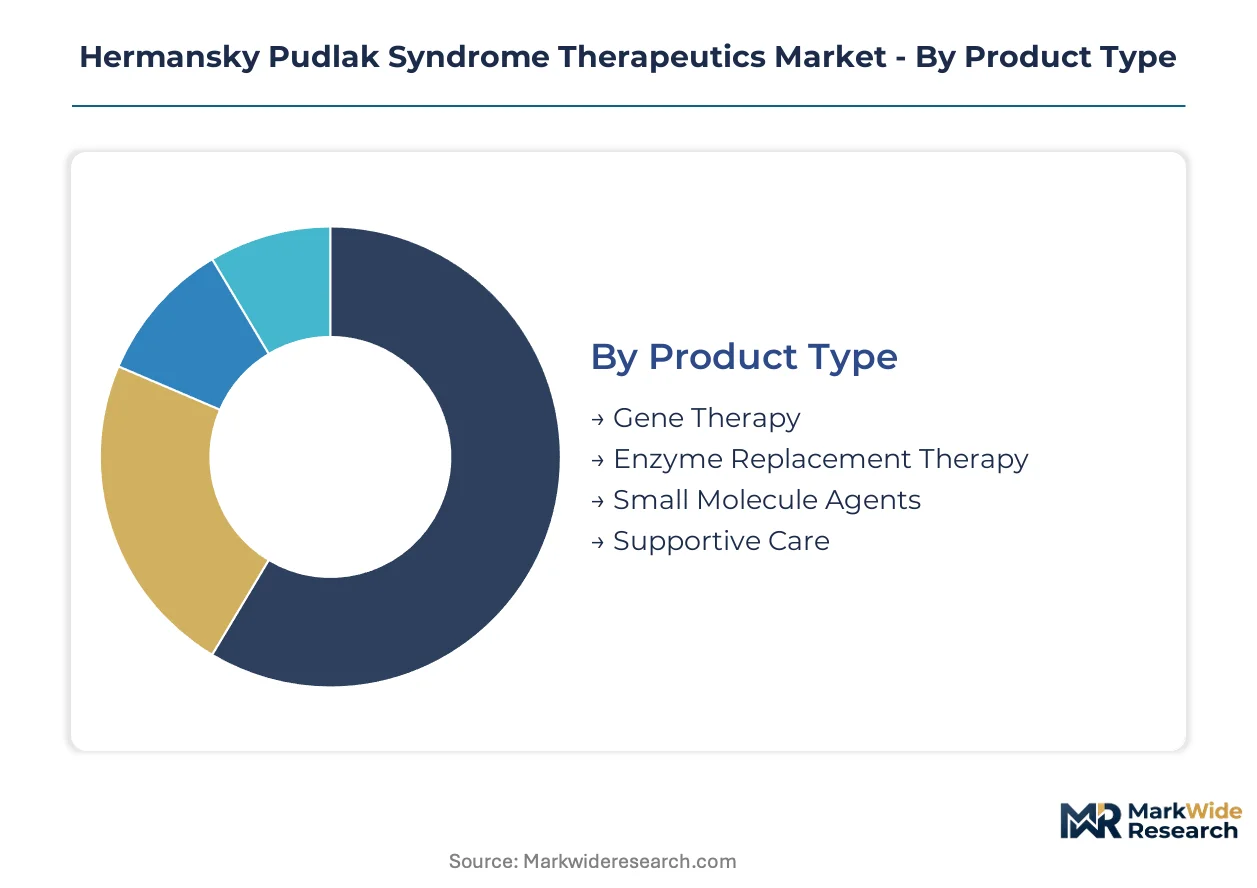
Segmentation in HPS therapeutics reveals how curative technologies command premium positioning against chronic management protocols. Product type and delivery mode decisions directly shape reimbursement negotiations and prescriber training investments across treatment centers.
Product Type:
Domestic development concentrates gene therapy platforms in United States and European biotech clusters, while small molecule pipelines distribute more broadly across contract research organizations globally.
- Gene Therapy:AAV-mediated HPS1 and HPS4 gene transfer approaches target underlying lysosomal trafficking defects with single-administration curative intent. United States academic medical centers with established gene therapy infrastructure anchor early adoption, though manufacturing capacity constraints limit batch scale and extend enrollment timelines.
- Enzyme Replacement Therapy:Systemic protein supplementation addresses related lysosomal storage disorder pathways where approved mechanisms exist, requiring chronic intravenous administration. Specialty clinics with infusion capabilities concentrate demand in metropolitan United States markets with dedicated rare disease nursing staff.
- Small Molecule Agents:Pulmonary fibrosis and platelet function modulators navigate earlier-stage clinical pipelines with oral delivery advantages.
- Supportive Care:Chronic bleeding prophylaxis and respiratory symptom management protocols retain substantial prescription volume in resource-constrained settings.
Gene Therapy holds the largest share; momentum sits with Small Molecule Agents as pulmonary fibrosis trials advance.
Delivery Mode:
Cost tier stratification separates hospital-based infusion from home-administered alternatives, with reimbursement differentials driving channel migration decisions.
- Intravenous:Hospital outpatient departments and specialty infusion centers administer biologic therapies requiring vascular access and adverse event monitoring. United States Medicare site-of-care policies increasingly shift volume to lower-cost ambulatory settings, compressing hospital margins.
- Subcutaneous:Self-administration training enables home-based prophylaxis for bleeding disorders, reducing treatment burden for dispersed HPS populations. Specialty pharmacy networks in the United States capture distribution margin through patient support programs.
- Oral:Small molecule pulmonary fibrosis candidates prioritize tablet formulations for patient compliance and pharmacy benefit coverage.
- Inhalation:Localized lung delivery targets interstitial disease progression with reduced systemic exposure.
Intravenous dominates current revenue; Subcutaneous is climbing the fastest as home infusion infrastructure matures.
End User:
Customer type fragmentation reflects prescriber expertise concentration versus care decentralization pressures across the United States healthcare system.
- Specialty Clinics:Academic medical center affiliates with dedicated HPS treatment protocols concentrate diagnostic expertise and longitudinal care coordination. These sites anchor gene therapy trial enrollment and post-marketing surveillance in major United States metropolitan areas.
- Hospitals:Emergency departments and inpatient units manage acute hemorrhagic complications requiring immediate hemostatic intervention. Urban tertiary centers with hematology-oncology services capture high-acuity episodes.
- Homecare Settings:Nursing networks administer subcutaneous prophylaxis under payer site-of-care optimization mandates.
- Research Institutions:Natural history registries and gene therapy clinical trial sites generate evidence for regulatory submissions.
Hospitals retain the largest patient volume; Specialty Clinics are gaining share fastest as care protocols standardize.
Application:
Application segmentation tracks the shift from symptomatic management toward disease-modifying interventions with differentiated evidentiary requirements.
- Disease Modification:Pulmonary fibrosis progression delay and gene therapy curative approaches require rigorous endpoint validation through forced vital capacity and six-minute walk test protocols. United States FDA Rare Disease Accelerated Approval pathways accept surrogate biomarkers, compressing development timelines.
- Management of Symptoms:Chronic bleeding prophylaxis and respiratory support address immediate quality-of-life impairments across all HPS subtypes. Community hematologists and pulmonologists in the United States drive prescription volume for established therapies.
- Psychological Support:Oculocutaneous albinism-related visual impairment counseling addresses patient and family adaptation needs.
- Genetic Counseling:Preconception and family planning services for autosomal recessive inheritance patterns.
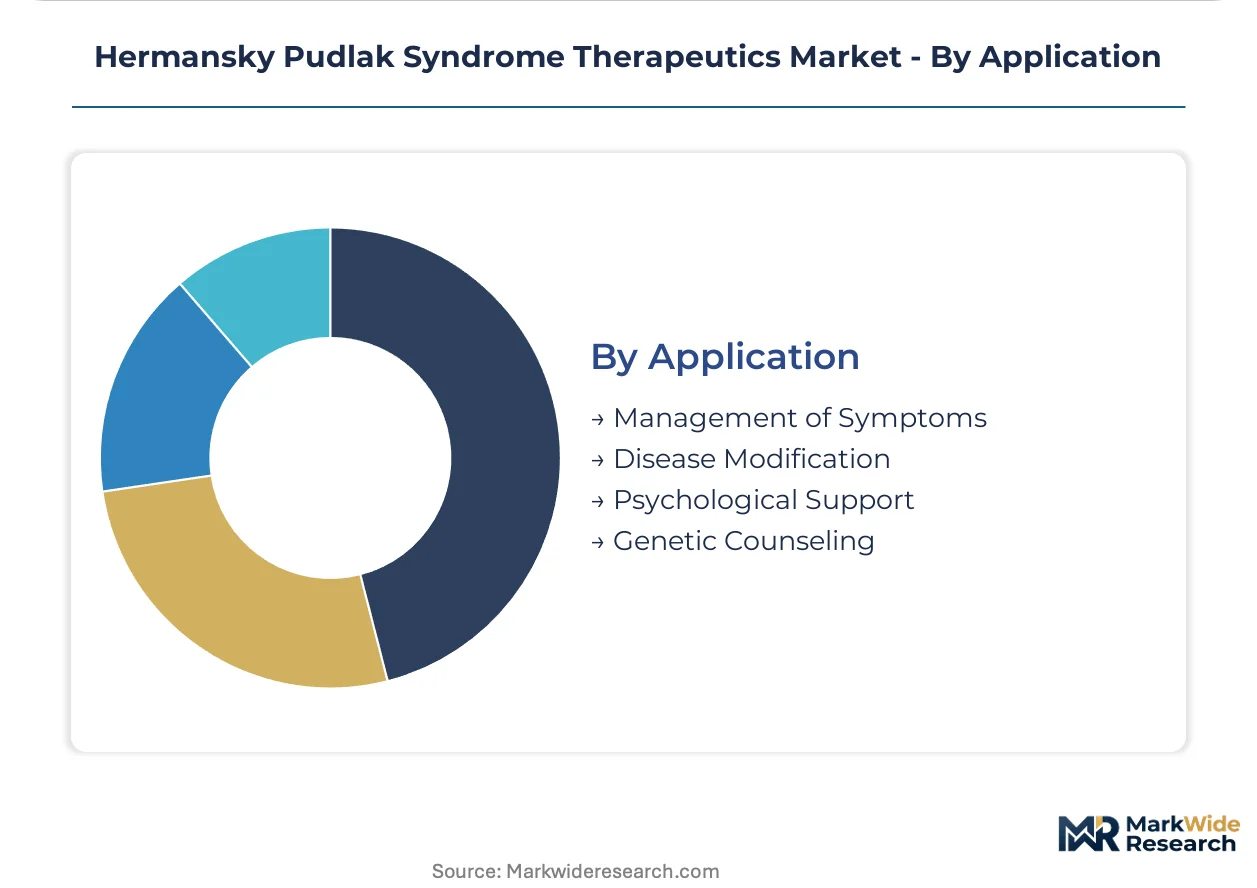
Management of Symptoms holds the largest share; Disease Modification shows steepest expansion trajectory as pipeline candidates advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy manufacturing capacity clusters in United States biotech corridors and Swiss pharmaceutical basins, while patient recruitment networks extend across national boundaries through academic medical center partnerships.
United States
Academic medical centers in Boston and New York anchor gene therapy trial infrastructure for HPS subtypes. The FDA's Orphan Drug Act provides tax credits and market exclusivity incentives that compress development economics. Specialty pharmacy networks in California and Texas expand home infusion capabilities for bleeding disorder prophylaxis.
Germany
Reference centers for rare lung diseases in Heidelberg and Munich concentrate pulmonary fibrosis expertise for HPS interstitial disease. The EMA's PRIME eligibility scheme accelerates scientific advice timelines for developers targeting lysosomal trafficking defects. Baden-Württemberg hosts contract manufacturing organizations supporting AAV vector production for European trials.
Switzerland
Basel-based biotech clusters pursue gene therapy platforms for HPS1 and HPS4 correction. Swissmedic maintains aligned review procedures with EMA that streamline orphan designation pathways. Zurich university hospitals coordinate natural history registry data collection across German-speaking regions.
United Kingdom
London's Royal Free Hospital and Manchester University NHS Foundation Trust maintain dedicated HPS treatment protocols. The MHRA's Innovative Licensing and Access Pathway supports early patient access for pulmonary fibrosis candidates with surrogate endpoints. Cambridge cell therapy manufacturing facilities supply clinical-grade vectors for national trial networks.
Japan
PMDA's Sakigake designation system accelerates review timelines for HPS therapeutics addressing unmet pulmonary needs. Tokyo and Osaka academic hospitals anchor Asia-Pacific patient identification for multinational gene therapy studies. The Ministry of Health's rare disease subsidy program reduces patient cost burden for imported biologics.
Hermansky Pudlak Syndrome Therapeutics Market Competitive Landscape
Concentration sits with established rare disease biologic developers and generic injectable manufacturers competing across different value chain segments. The market structure separates into three tiers: gene therapy platform specialists commanding premium development economics, large-cap pharmaceutical companies leveraging manufacturing scale, and mid-tier generic houses competing on cost for supportive care products. Strategic moves center on gene therapy manufacturing partnerships and specialty pharmacy distribution alliances that secure patient access pathways.
Within the rare disease biologic tier, Genentech anchors development intensity through deep research commitments in lysosomal trafficking biology. Teva Pharmaceuticals occupies a position at the scale-driven end, competing across injectable delivery formats with established manufacturing infrastructure. Bristol-Myers Squibb sits within the immunology franchise segment, leveraging hospital formulary relationships that facilitate prescriber access for complex biologics.
| Leading Market Players |
|---|
| Sagent Pharma |
| Teva Pharmaceuticals |
| American Regent |
| Genentech |
| Ferring Pharmaceuticals |
| Dr. Reddy's |
| Sun Pharma |
| Bristol-Myers Squibb |
| Gland Pharma Limited |
| Others |
Supply & Pricing Matrix
FDA Orphan Drug Act tax credits and market exclusivity provisions simultaneously gate supply qualification for HPS therapeutics and stratify price differentiation across curative versus chronic management tiers. Developers must navigate manufacturing scale thresholds to access premium pricing corridors reserved for gene therapy platforms.
Pricing Analysis
FDA Rare Disease Accelerated Approval dictates the pricing tier structure across HPS therapeutics, establishing three-tier pricing stratification across premium gene therapy, standard biologic infusion, and economy supportive care levels. Price differentiation rests on certification intensity and manufacturing complexity, with AAV vector production costs anchoring premium tiers. Cost compression in the small molecule pulmonary fibrosis segment intensifies as Phase II attrition erodes development premiums. Community hematologists exhibit highest price sensitivity, while academic medical center gene therapy programs demonstrate lowest sensitivity due to bundled reimbursement mechanisms.
Supply Chain Analysis
AAV vector manufacturing capacity chokepoints in Massachusetts and North Carolina biotech corridors tether HPS gene therapy supply to concentrated viral production infrastructure. Raw material dependencies span plasmid DNA, HEK293 cell lines, and specialized chromatography resins sourced from United States, Switzerland, and Germany. Single-source vulnerability runs through contract manufacturing organizations with established gene therapy suites. Distribution runs through specialty pharmacy networks capable of cold-chain management for biologic therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HPS therapeutics sits at a platform-economics inflection where gene therapy durability data and companion diagnostic interoperability will reshape competitive boundaries and partnership structures across the value chain.
For Market Incumbents: Consolidate manufacturing partnerships with AAV vector producers in Boston and Research Triangle Park to secure batch capacity ahead of competitor enrollment windows. Deepen backward integration into plasmid DNA supply through captive supplier agreements, as raw material constraints threaten margin compression for outsourced production models. For New Entrants and Emerging Players: EMA PRIME eligibility fast-tracks provide regulatory acceleration pathways for pulmonary fibrosis candidates with surrogate endpoint strategies. Target home infusion infrastructure gaps in Texas and Florida metropolitan markets where specialty pharmacy networks remain underdeveloped. Lead with subcutaneous delivery formulations to bypass hospital outpatient department formulary control. For Investors and Strategic Acquirers: FDA gene therapy durability surveillance requirements reshape the acquisition landscape toward platforms with established post-marketing study infrastructure. Five-to-ten year viability favors developers with integrated companion diagnostic capabilities and natural history registry relationships. Watch for pulmonary function biomarker validation readouts as inflection indicators for accelerated approval pathway viability.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | AAV vector capacity expansion in United States biotech corridors compresses patient enrollment timelines for HPS1-HPS4 programs. |
| Companion Diagnostic Development | HPS subtype genotyping platforms enable prescriber decision support and segment addressable populations for targeted therapies. |
| Specialty Pharmacy Network Expansion | Home infusion capabilities in California and Texas markets capture site-of-care migration mandated by commercial payer optimization. |
| Natural History Registry Investment | Prospective data collection across academic medical centers satisfies EMA demands for robust baseline progression metrics. |
| Regulatory Pathway Diversification | Parallel FDA and EMA submissions leverage Rare Disease Accelerated Approval and PRIME eligibility to compress review timelines. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings across the HPS therapeutics landscape. Conversations with gene therapy development executives, regulatory affairs leads at rare disease biotechs, hospital formulary directors, and payer access specialists informed pipeline prioritization assessments. Secondary sources encompassed FDA Orphan Drug designations, EMA PRIME eligibility decisions, ClinicalTrials.gov protocol specifications, and Medicare National Coverage Determination documents. Bottom-up patient population estimates and top-down revenue triangulation reconciled market sizing outputs.
Sensitivity analysis across enrollment timeline assumptions and manufacturing cost scenarios shaped the analytical framework. Segmentation dimensions modeled encompassed product type, delivery mode, end user archetype, and application intent across the projection horizon. CAGRs derived from longitudinal therapy adoption curves and pricing evolution patterns. Gene therapy durability surveillance commitments and pulmonary fibrosis biomarker validation trajectories served as key forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory incentive structures; material deviation in FDA Orphan Drug Act provisions or EMA scientific advice timelines would warrant model refresh. Practitioners should keep alternative scenarios live as gene therapy manufacturing capacity expansion and pulmonary endpoint validation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Global Alopecia Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Glioma Therapeutics Market