
 Europe Plasma Fractionation Market | 2026-2036
Europe Plasma Fractionation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plasma Fractionation Market Foresight
CE marking under the EU Medical Device Regulation is unwinding the competitive landscape for plasma-derived therapeutics. Grifols S.A. leverages its integrated plasma collection network across Southern Europe to secure raw material supply. CSL Ltd. anchors its position through high-purity albumin manufacturing capabilities. Octapharma AG competes aggressively in coagulation factor concentrates with specialized production lines.
Plasma fractionation separates blood plasma into therapeutic proteins through ethanol precipitation, chromatography, and viral inactivation steps yielding immunoglobulin with protein purity exceeding 95%. The process serves critical therapeutic areas including primary immunodeficiency, hemophilia, and neurological autoimmune disorders. Immunoglobulin commands the largest revenue pool due to expanding neurology and immunology indications across European hospital systems. Albumin maintains steady demand from critical care and surgical applications in mature Western European markets. Coagulation factors represent the fastest-expanding category driven by prophylactic hemophilia treatment protocols in specialized European treatment centers.
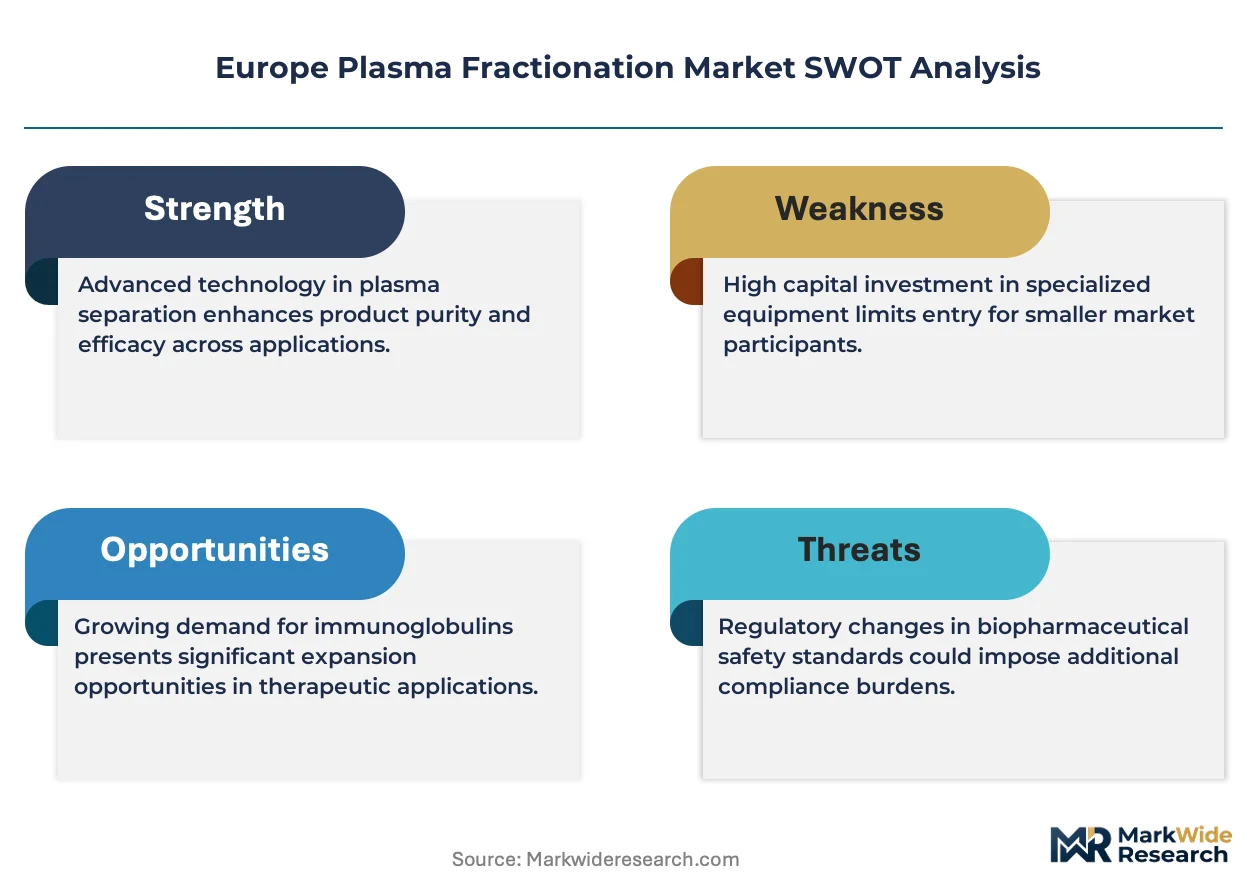
EMA's centralized marketing authorization procedures and the EU's MDR framework govern plasma product quality, traceability, and post-market surveillance requirements across member states. ECHA's REACH regulations and the F-Gas Regulation additionally constrain solvent use and cold-chain logistics configurations for fractionation facilities. France's ANSM and Germany's regional competent authorities enforce national pharmacovigilance standards that exceed baseline EU requirements. Stakeholders must monitor evolving plasma sourcing regulations and MDR transition timelines to align capacity investments with compliance deadlines.
Market Dynamics
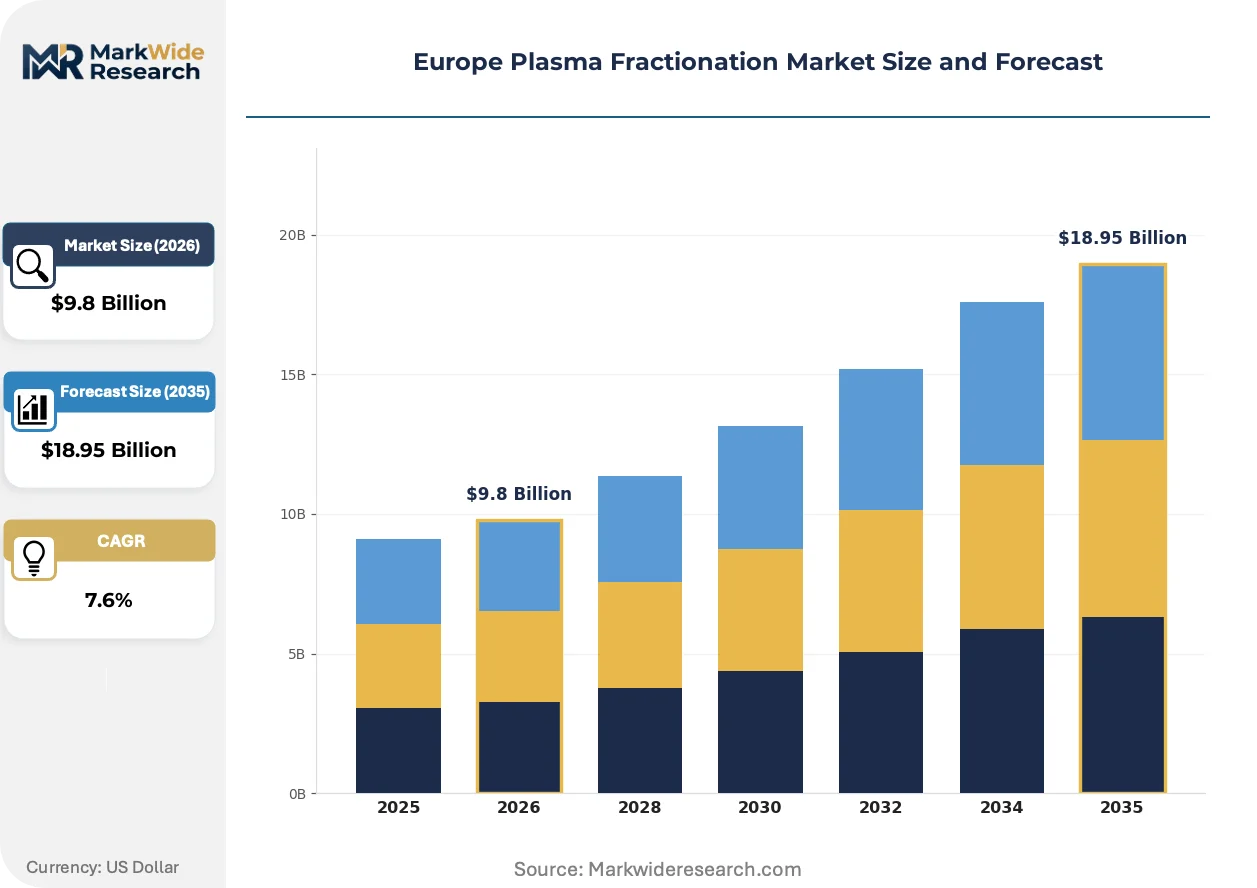
The EU Medical Device Regulation is compressing approval timelines for plasma-derived therapeutics while simultaneously elevating compliance costs, forcing fractionators to restructure quality systems around centralized EMA oversight and traceability mandates.
Growth Catalysts
- Prophylactic hemophilia protocols:Specialized treatment centers across Germany, France, and Italy are expanding prophylactic coagulation factor administration, driving volume demand for high-purity concentrates.
- EMA centralized authorization:Streamlined marketing authorization procedures accelerate cross-border product availability, reducing time-to-market for novel immunoglobulin formulations.
- Neurology indication expansion:Chronic inflammatory demyelinating polyneuropathy and multifocal motor neuropathy protocols in hospital networks are widening immunoglobulin utilization beyond traditional immunodeficiency bases.
Market Restraints
- Plasma collection concentration:Southern Europe dominates EU-sourced plasma volume, creating geographic dependency risk for fractionators without diversified collection infrastructure.
- Ethanol and solvent cost volatility:ECHA REACH compliance costs and energy-intensive cold-chain requirements constrain margin flexibility at production facilities.
- Recombinant factor substitution:Engineered coagulation proteins from biotech manufacturers threaten albumin and plasma-derived factor market positions in prophylactic segments.
Strategic Opportunities
- Eastern European hospital network penetration:Poland, Hungary, and Czech Republic specialist centers remain underpenetrated for immunoglobulin neurology protocols relative to Western European saturation levels.
- Chromatography-ethanol hybrid purification:Converging precision separation technologies enable higher-yield immunoglobulin extraction with reduced viral inactivation cycle times.
- EU Green Deal cold-chain incentives:Decarbonization subsidies for pharmaceutical logistics infrastructure support sustainable plasma product distribution network expansion.
Industry Challenges
- MDR technical documentation capacity:Fractionators face acute shortages of regulatory affairs specialists capable of compiling clinical evaluation reports and post-market surveillance systems under tightened EU deadlines.
- Legacy fractionation facility retrofitting:Viral inactivation suite upgrades to satisfy enhanced EMA pharmacovigilance standards require capital deployment without immediate volume returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plasma Fractionation Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoglobulin, Albumin, Coagulation Factors, Protease Inhibitors Application: Neurology, Hematology, Immunology, Infectious Diseases End User: Hospitals, Blood Banks, Diagnostic Laboratories, Research Institutes Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Pharmacies |
| Companies Covered | Kedrion S.p.A, Bio Products Laboratory, Grifols S.A, Biotest AG, Sanquin, CSL Ltd., Laboratoire Français du Fractionnement et des Biotechnologies, Prothya Biosolutions Netherlands BV, Octapharma AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plasma Fractionation Market Shifts & Advancements
Continuous processing technologies and precision analytics are displacing batch-oriented fractionation workflows, enabling real-time quality monitoring and yield optimization across European manufacturing networks.
Capto adhere chromatography resin is decomposing traditional ethanol precipitation sequences in immunoglobulin purification lines. Fractionators in Germany and Switzerland are adopting this resin at accelerated replacement cycles. The technology is decomposing capital-intensive tank farm requirements while compressing batch-to-batch variability in high-purity output specifications.
EU F-Gas Regulation phase-down mandates are forcing refrigeration system retrofits at plasma storage and distribution nodes. Industrial consequence includes accelerated adoption of natural refrigerant architectures and ammonia-based cold-chain infrastructure. Fractionation facilities in France and Spain face the most compressed compliance timelines due to older hydrofluorocarbon-dependent installations.
Hospital pharmacy consolidation across national health systems is concentrating procurement authority into centralized tendering bodies. Specialized hemophilia treatment centers and university hospital networks are losing direct supplier negotiation autonomy to regional purchasing cooperatives. This pattern is most visible in Italy's Azienda Sanitaria Locale restructuring and Germany's Krankenhausversorgung regionalization.
Europe Plasma Fractionation Market Segmentation
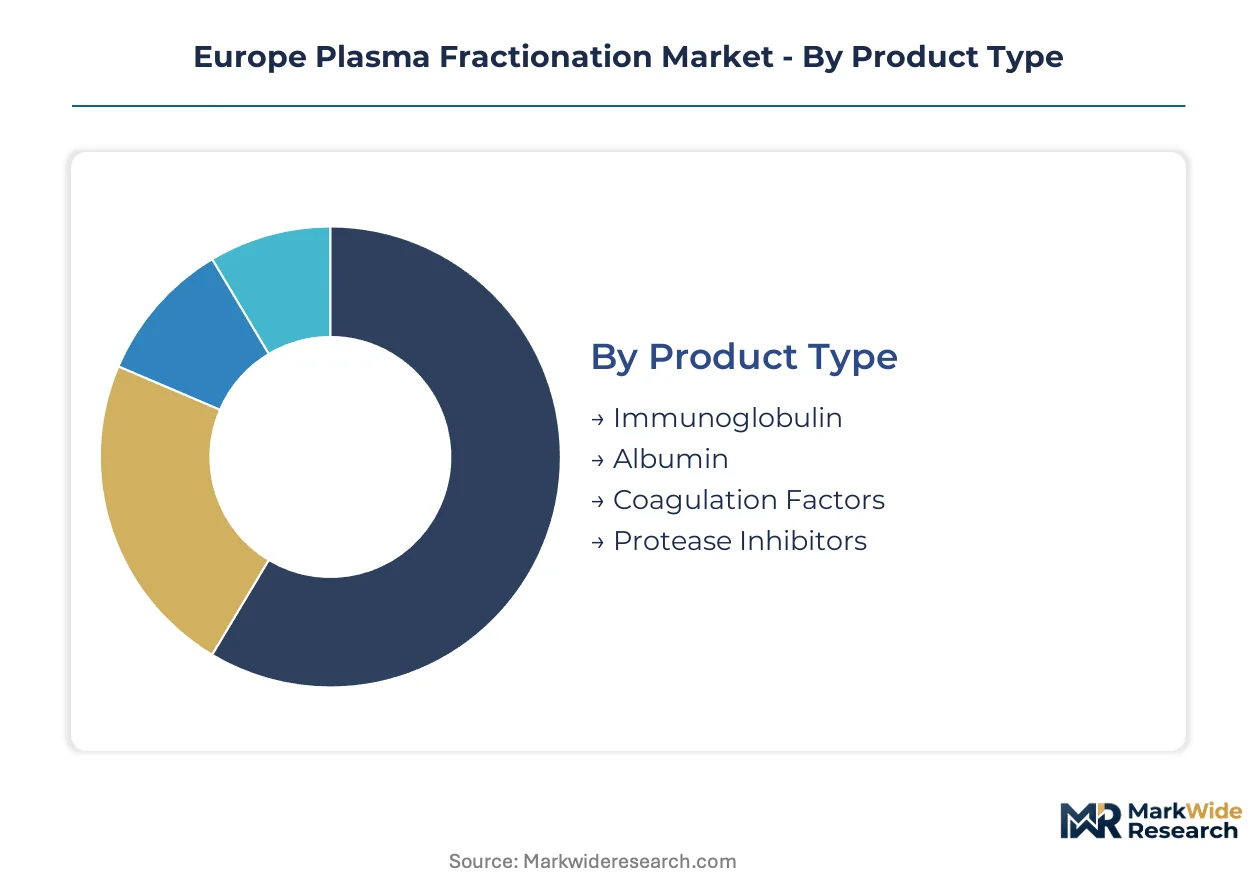
Plasma fractionation segments channel through distinct procurement hierarchies across European health systems. Hospital pharmacy consolidation and tendering centralization reshape how each product category reaches end-users.
Product Type:
Channel mix varies sharply by product type, with immunoglobulin and albumin flowing predominantly through direct hospital contracts while coagulation factors split between specialized hemophilia centers and distributor networks.
- Immunoglobulin:Polyclonal antibody concentrates with protein purity exceeding 95% serve primary immunodeficiency and expanding neurology indications. German and French hospital networks concentrate demand for chronic inflammatory demyelinating polyneuropathy protocols, with EMA centralized authorization accelerating cross-border availability of high-dose formulations.
- Albumin:Heat-treated plasma protein maintains 96-98% purity specifications for critical care volume expansion and surgical applications. Western European mature markets anchor steady consumption, while perioperative protocols in Italian and Spanish university hospitals sustain replacement demand against recombinant alternatives.
- Coagulation Factors:High-purity concentrates VIII and IX drive prophylactic hemophilia treatment expansion across specialized European centers.
- Protease Inhibitors:Alpha-1 antitrypsin and C1 esterase inhibitor products address hereditary angioedema and emphysema populations through targeted specialty pharmacy distribution.
Immunoglobulin dominates installed base. Coagulation factors represent where expansion concentrates fastest.
Application:
Cost tier stratification separates neurology and immunology as premium-reimbursed categories from infectious disease applications facing generic pressure.
- Neurology:Intravenous immunoglobulin protocols for multifocal motor neuropathy and myasthenia gravis command premium pricing tiers. French and German specialist centers drive protocol adoption, with hospital pharmacy committees scrutinizing cost-per-quality-adjusted-life-year metrics against plasma-derived alternatives.
- Hematology:Hemophilia prophylaxis and von Willebrand disease management anchor coagulation factor consumption. Italian hemophilia treatment centers and German comprehensive care facilities concentrate prophylactic protocol penetration, with recombinant substitution threatening plasma-derived share in standard-severity segments.
- Immunology:Primary immunodeficiency replacement therapy sustains baseline immunoglobulin demand through chronic administration regimens.
- Infectious Diseases:Hepatitis B immunoglobulin and tetanus prophylaxis applications face volume pressure from vaccine substitution and cost containment protocols.
Hematology commands the highest per-patient revenue intensity. Neurology is climbing the fastest as indication expansion outpaces traditional immunodeficiency growth.
End User:
Customer type determines contracting complexity, with hospitals negotiating frame agreements while blood banks and laboratories operate under separate procurement frameworks.
- Hospitals:University medical centers and specialized hemophilia treatment facilities concentrate plasma product consumption through centralized pharmacy operations. Germany's Krankenhausversorgung regionalization and Italy's Azienda Sanitaria Locale consolidation shift negotiation leverage toward regional purchasing cooperatives.
- Blood Banks:National transfusion services in France and Spain maintain strategic plasma reserves and fractionation partnerships for domestic supply security.
- Diagnostic Laboratories:Control plasma and calibrator products support coagulation testing quality assurance through specialized distributor channels.
- Research Institutes:Academic and contract research organizations procure small-volume specialty fractions for assay development and biomarker studies.
Hospitals dominate installed base. Blood banks represent where volume security investments concentrate.
Distribution Channel:
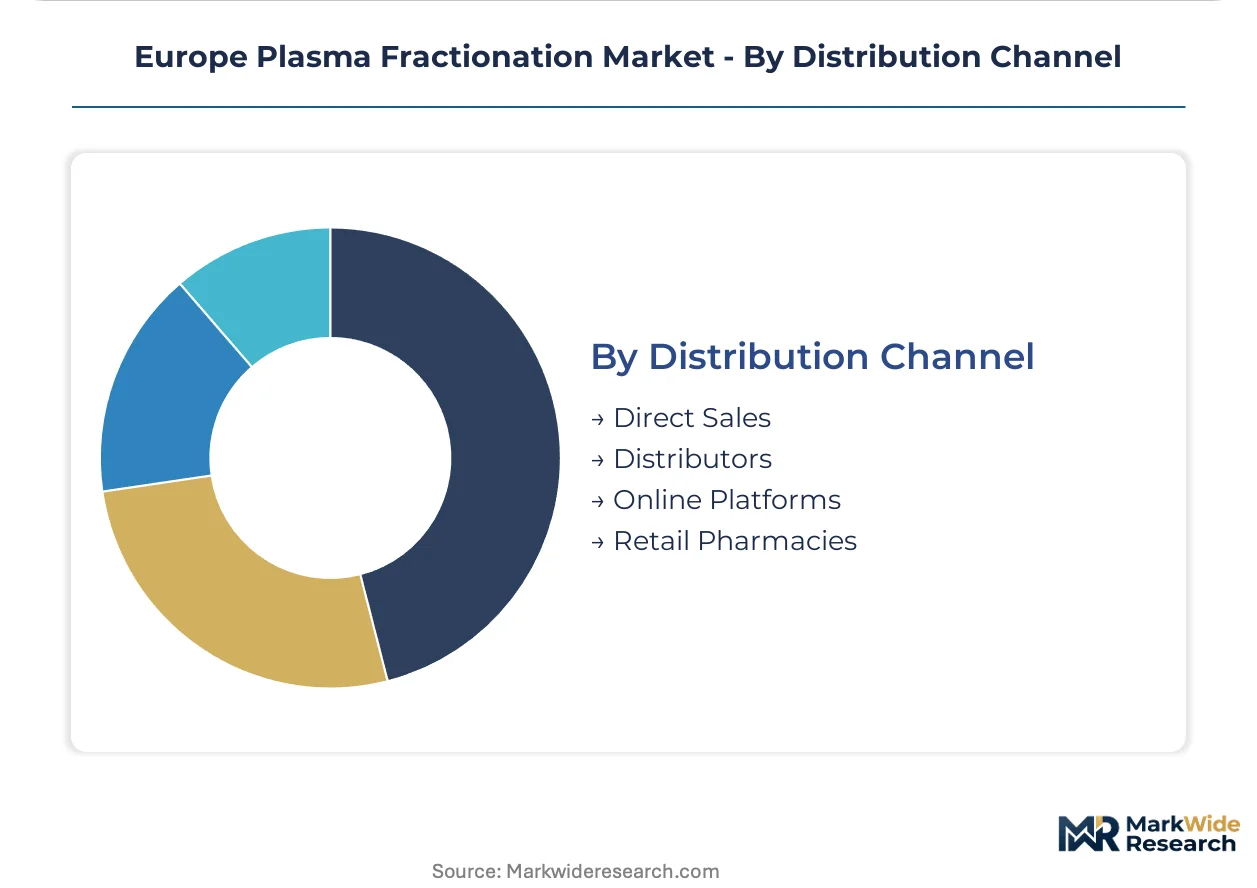
Geography and product temperature sensitivity shape channel selection, with cold-chain requirements favoring direct logistics over fragmented retail networks.
- Direct Sales:Manufacturer-to-hospital contracts dominate immunoglobulin and albumin flow for high-volume accounts. Grifols, CSL, and Octapharma maintain dedicated field forces for key account management across German, French, and Italian hospital networks.
- Distributors:Regional pharmaceutical wholesalers handle mid-tier hospital and blood bank accounts with established cold-chain capabilities. Southern European markets retain higher distributor dependency due to fragmented hospital scale.
- Online Platforms:Limited to research-grade products and diagnostic controls exempt from prescription distribution restrictions.
- Retail Pharmacies:Minimal plasma fractionation presence restricted to emergency coagulation factor access and patient self-infusion training programs.
Direct sales dominates installed base. Distributor partnerships represent where network expansion concentrates in underpenetrated Eastern European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement centralization concentrates buyer power across Western European networks, while Eastern European specialist centers remain fragmented entry points for neurology protocol expansion.
Germany
Krankenhausversorgung regionalization consolidates immunoglobulin purchasing into multi-hospital cooperatives. The Federal Institute for Drugs and Medical Devices enforces pharmacovigilance standards exceeding baseline EU MDR requirements. Bavarian hemophilia treatment centers in Munich and Nuremberg anchor prophylactic coagulation factor consumption.
France
ANSM oversight tightens plasma-derived product traceability mandates for hospital networks. The national health insurance system reimburses chronic inflammatory demyelinating polyneuropathy protocols at premium tiers. Paris and Lyon university hospitals concentrate neurology indication adoption through centralized pharmacy committees.
Italy
Azienda Sanitaria Locale restructuring shifts tendering authority from individual hospitals to regional purchasing bodies. EMA centralized authorization accelerates cross-border availability of high-dose immunoglobulin formulations. Lombardy and Emilia-Romagna specialist centers drive hematology protocol penetration.
Spain
National transfusion services maintain strategic plasma reserves through domestic fractionation partnerships. F-Gas Regulation phase-down mandates force refrigeration retrofits at Barcelona and Madrid storage facilities. Andalusian hospital networks expand albumin utilization for critical care applications.
Poland
Specialist hemophilia centers in Warsaw and Krakow remain underpenetrated for prophylactic coagulation factor protocols relative to Western European saturation. The national pharmaceutical regulator aligns post-market surveillance with tightening EMA pharmacovigilance standards. Regional hospital networks present expansion vectors for immunoglobulin neurology indications.
Europe Plasma Fractionation Market Competitive Landscape
Player mix skews toward integrated plasma collectors with captive fractionation capacity, creating supply-side consolidation around raw material security. Three archetypes dominate: vertically integrated multinationals controlling collection-to-distribution chains, national champions serving domestic health systems through state partnerships, and specialized fractionators focusing on high-purity coagulation factor niches. Competitive moves concentrate on M&A for plasma center networks and capacity expansion for viral inactivation suite upgrades.
Among integrated multinationals, Grifols S.A. and CSL Ltd. occupy positions exemplifying collection infrastructure dominance across Southern and Western European markets. Octapharma AG sits within the specialized tier, representing concentrated expertise in coagulation factor manufacturing. Biotest AG and Kedrion S.p.A. exemplify regional champions anchored to national health system procurement frameworks. Sanquin and Laboratoire Français du Fractionnement et des Biotechnologies represent state-affiliated structures with protected domestic market positions.
| Leading Market Players |
|---|
| Kedrion S.p.A |
| Bio Products Laboratory |
| Grifols S.A |
| Biotest AG |
| Sanquin |
| CSL Ltd. |
| Laboratoire Français du Fractionnement et des Biotechnologies |
| Prothya Biosolutions Netherlands BV |
| Octapharma AG |
| Others |
Supply & Pricing Matrix
Long-term plasma supply offtake agreements with indexed pricing clauses lock in both raw material security and cost visibility for fractionators operating under EU MDR compliance timelines. These contracts tie immunoglobulin and albumin pricing to ethanol cost indices and energy benchmarks, insulating producers from ECHA REACH solvent price volatility while committing buyers to minimum volume thresholds.
Pricing Analysis
Cost-plus contracts with ethanol and energy indexation dominate plasma fractionation pricing structures across European hospital networks. Three-tier pricing stratifies across premium viral-inactivated immunoglobulin, standard albumin formulations, and economy-grade coagulation factor concentrates, with differentiation driven by protein purity certification and cold-chain reliability grades. Cost compression in standard-tier segments intensifies as regional purchasing cooperatives consolidate tendering authority in Germany and Italy. Specialized hemophilia treatment centers exhibit lowest price sensitivity due to clinical protocol rigidity, while general hospital pharmacies face acute budget pressure from neurology indication expansion.
Supply Chain Analysis
Port congestion at Barcelona and Rotterdam disrupts chromatography resin inbound flows from Swiss and German specialty chemical suppliers, elevating working capital requirements for fractionation facilities. Plasma collection concentrates in Spain, Italy, and Poland, while purification consumables draw from Switzerland, Germany, and Belgium. Single-source vulnerability sits with Capto adhere resin supply from Cytiva's manufacturing footprint. Distribution runs through manufacturer-direct hospital contracts for high-volume accounts, with regional pharmaceutical wholesalers serving mid-tier blood bank and specialty pharmacy networks across Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma fractionation market fragmentation creates entry niches as hospital pharmacy consolidation fragments supplier relationships and neurology protocol expansion outpaces incumbent immunoglobulin capacity allocation.
For Market Incumbents: Shield market position by securing captive plasma collection networks in underpenetrated Eastern European geographies and accelerating viral inactivation suite upgrades ahead of tightened EMA pharmacovigilance deadlines. Recombinant factor substitution from engineered protein manufacturers threatens plasma-derived coagulation factor margins, demanding backward integration into high-purity albumin production to defend margin architecture. For New Entrants and Emerging Players: Post-market surveillance service gaps where incumbents under-serve smaller hospital networks present white-space opportunities for specialized regulatory affairs outsourcing and MDR technical documentation support. Poland and Czech Republic hemophilia treatment centers offer the most penetrable geography for prophylactic coagulation factor protocols, accessible through partnerships with regional purchasing cooperatives rather than direct manufacturer competition. For Investors and Strategic Acquirers: National champions with state-affiliated plasma collection monopolies and protected domestic procurement relationships represent the highest-conviction acquisition archetype for long-term viability within a 5-10 year regulatory window. Monitor EMA centralized authorization approval velocity for novel immunoglobulin formulations as the critical inflection signal for capacity utilization and pricing power recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Secures raw material supply security against Southern Europe geographic concentration risk. |
| Viral Inactivation Suite Upgrade | Aligns manufacturing capacity with tightened EMA pharmacovigilance and MDR traceability mandates. |
| Chromatography-Ethanol Hybrid Process Adoption | Enables higher-yield immunoglobulin extraction with reduced batch-to-batch variability specifications. |
| Eastern European Hospital Network Partnership | Captures neurology protocol expansion in underpenetrated Polish and Czech specialist centers. |
| Natural Refrigerant Cold-Chain Retrofit | Secures EU Green Deal subsidy eligibility while satisfying F-Gas Regulation phase-down compliance. |
Research Methodology
Initial hypotheses were tested against primary input from plasma fractionation plant managers, hospital pharmacy directors, regulatory affairs specialists at EMA centralized authorization holders, and blood bank procurement leads, then refined through secondary validation against EMA marketing authorization databases, ANSM pharmacovigilance reports, EU MDR technical documentation filings, and national health insurance reimbursement tariff schedules. Bottom-up volume modeling triangulated with top-down market sizing across product type, application, end user, and distribution channel segmentation dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within immunoglobulin, albumin, and coagulation factor categories. The analytical framework models patient population growth, protocol penetration rates, and substitution dynamics between plasma-derived and recombinant alternatives. CAGRs were derived from segmented growth rate aggregation weighted by baseline revenue contribution, with plasma collection yield assumptions and viral inactivation capacity expansion timelines serving as critical forecast sensitivity inputs.
Material uncertainties — EMA MDR transition deadline extensions, ethanol cost index volatility, and recombinant factor substitution velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory compliance timelines and hospital procurement centralization trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Bio-Identical Hormones Replacement Therapy Market
Biopharmaceuticals
Canada Generic Drug Market