
 Brazil Generic Drug Market | 2026-2036
Brazil Generic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Generic Drug Market Intelligence
Hospital procurement channels for generic medicines is narrowing as consolidated purchasing pools gain leverage over fragmented suppliers. Eurofarma leverages vertical integration across API-to-finished-dose manufacturing to secure tender volumes. EMS anchors its position through deep relationships with public health networks in populous states. Sun Pharmaceutical competes on cost efficiency in high-volume oral solids exported into Brazil.
Generic drugs are pharmaceutical products containing identical active pharmaceutical ingredients to originator brands, manufactured after patent expiry and required to demonstrate bioequivalence through pharmacokinetic studies. They serve primarily to expand patient access to essential therapies at reduced cost within public and private reimbursement systems. Tablet formulations occupy the largest volume share due to stability and patient compliance advantages in chronic disease management. Oncology generics represent the fastest-expanding therapy area as patent cliffs on biologic and small-molecule cancer drugs accelerate substitution timelines.
ANVISA governs market authorization through bioequivalence study requirements and GMP inspections, while Brazil's national health system procurement rules shape pricing floors and volume allocation across regions. The country's national pharmaceutical regulator enforces post-market surveillance protocols that determine product retention or withdrawal. Stakeholders must monitor pending patent linkage discussions and local production incentives under federal industrial policy.
Market Dynamics
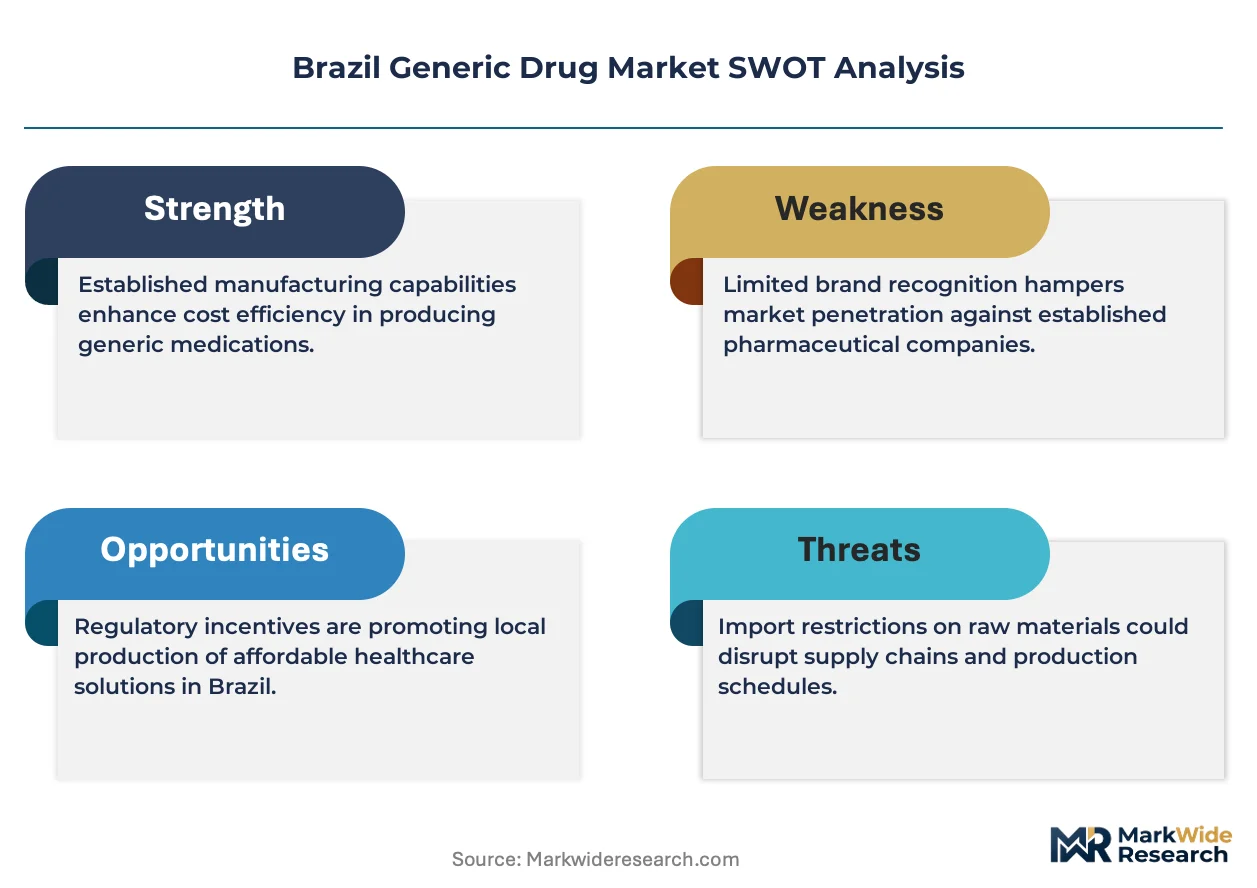
ANVISA's bioequivalence study requirements and GMP inspection protocols are compressing the supplier base, rewarding manufacturers with captive API production while marginalizing pure-play finishers dependent on imported intermediates.
Growth Catalysts
- SUS Procurement Volumes:Brazil's unified health system channels 70% of generic volume through consolidated tenders, locking in multi-year supply agreements for qualified suppliers.
- Patent Cliff Acceleration:Small-molecule oncology and immunology molecules losing exclusivity are expanding the addressable generic pool faster than historical norms.
- Southeast Regional Density:São Paulo and Rio de Janeiro concentrate 60% of dispensing pharmacies and hospital networks, creating logistics efficiencies for regional distribution hubs.
Market Restraints
- API Import Dependency:Active pharmaceutical ingredient supply concentrates in Chinese and Indian chemical parks, exposing Brazilian finishers to currency volatility and shipping disruptions.
- ANVISA Inspection Backlogs:GMP certification queues extending 18-24 months delay facility approvals and product launches for new market entrants.
- Biologic Substitution Limits:Biosimilar interchangeability remains restricted under ANVISA guidelines, capping generic penetration in high-value therapy areas.
Strategic Opportunities
- Northeast Regional Expansion:Ceará, Pernambuco, and Bahia exhibit 40% lower generic penetration than the Southeast, creating whitespace for distribution infrastructure investment.
- Complex Generic Formulations:Modified-release oral solids and transdermal patches face limited competition due to technical barriers, supporting premium positioning.
- Local Production Incentives:Federal industrial policy under the Ex-Tarifário regime grants tariff exemptions for imported equipment used in domestic API synthesis.
Industry Challenges
- Bioequivalence Study Capacity:Clinical pharmacokinetic trial sites in Brazil number fewer than 25, creating bottlenecks for portfolio expansion.
- Post-Market Surveillance Compliance:ANVISA's pharmacovigilance reporting requirements demand dedicated safety teams that smaller manufacturers struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Generic Drug Market |
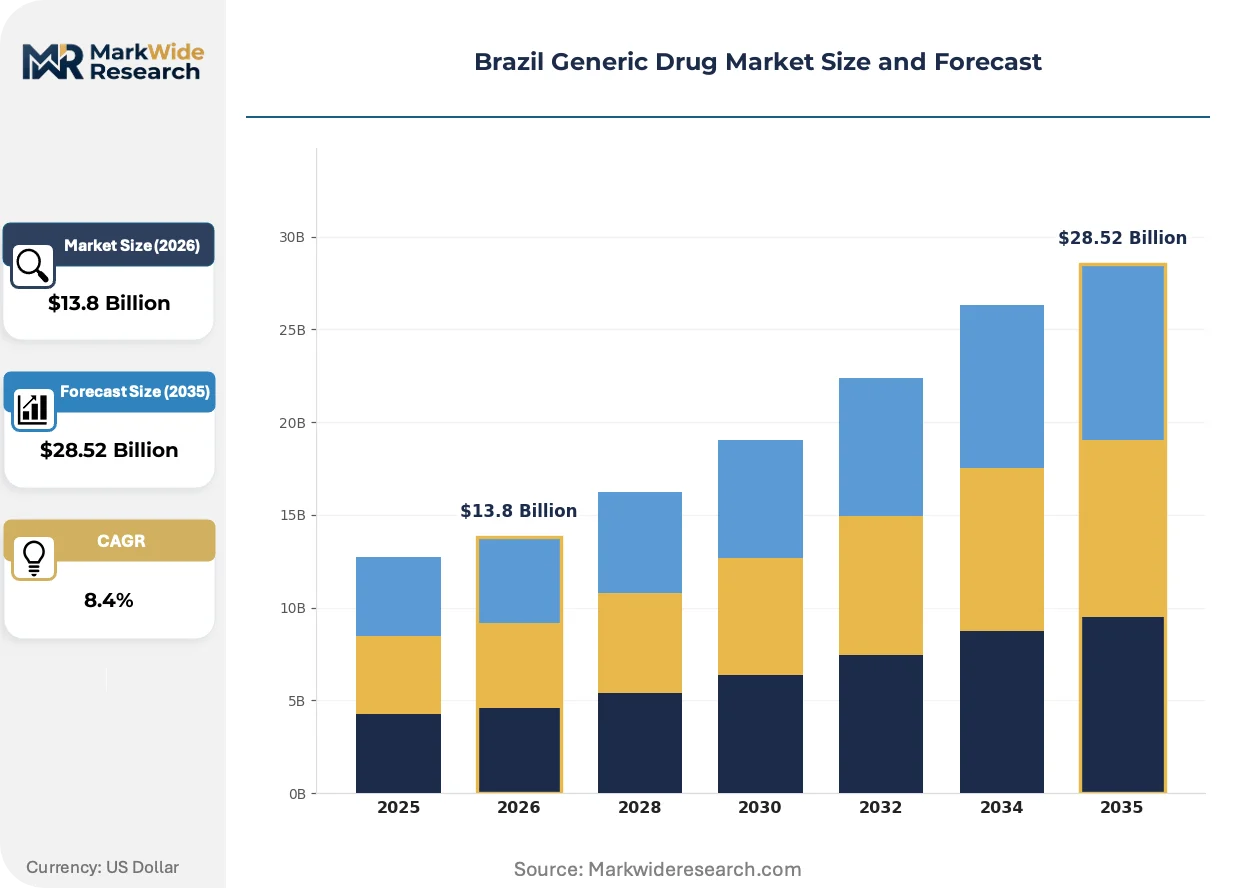
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Injection, Topical Therapy Area: Cardiovascular, Diabetes, Oncology, Antibiotics End User: Hospitals, Pharmacies, Clinics, Wholesale Distributors Pricing Model: Cost-Plus, Penetration Pricing, Value-Based, Bid Pricing |
| Companies Covered | Grupo NC, Biolab, Hypera Pharma, Sun Pharmaceutical, Libbs, Eurofarma, Aché, FQM, EMS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Generic Drug Market Strategic Shifts & Innovations
Continuous manufacturing technologies and real-time release testing are collapsing batch production timelines, compressing the gap between API synthesis and finished dose availability for high-volume oral solids.
Continuous processing equipment is collapsing the traditional scale-up gap between pilot batches and commercial volumes. EMS and Eurofarma have installed modular direct compression lines that reduce changeover times from days to hours. This technology is collapsing inventory carrying costs and enabling just-in-time tender fulfillment for SUS hospital networks.
ANVISA's updated bioequivalence guidance for narrow-therapeutic-index drugs tightens pharmacokinetic confidence intervals, forcing reformulation investments for legacy products. The regulation elevates technical barriers for new entrants while rewarding incumbents with established study databases. High-potency cardiovascular and antiepileptic portfolios face the steepest compliance costs under this framework.
Hospital purchasing pools in Minas Gerais and Rio Grande do Sul are consolidating supplier rosters from 15-20 vendors to 5-7 preferred partners, concentrating volume with manufacturers offering integrated logistics and formulary management services. This concentration is most visible in oncology injectables, where cold-chain reliability and batch traceability determine contract awards.
Brazil Generic Drug Market Segmentation
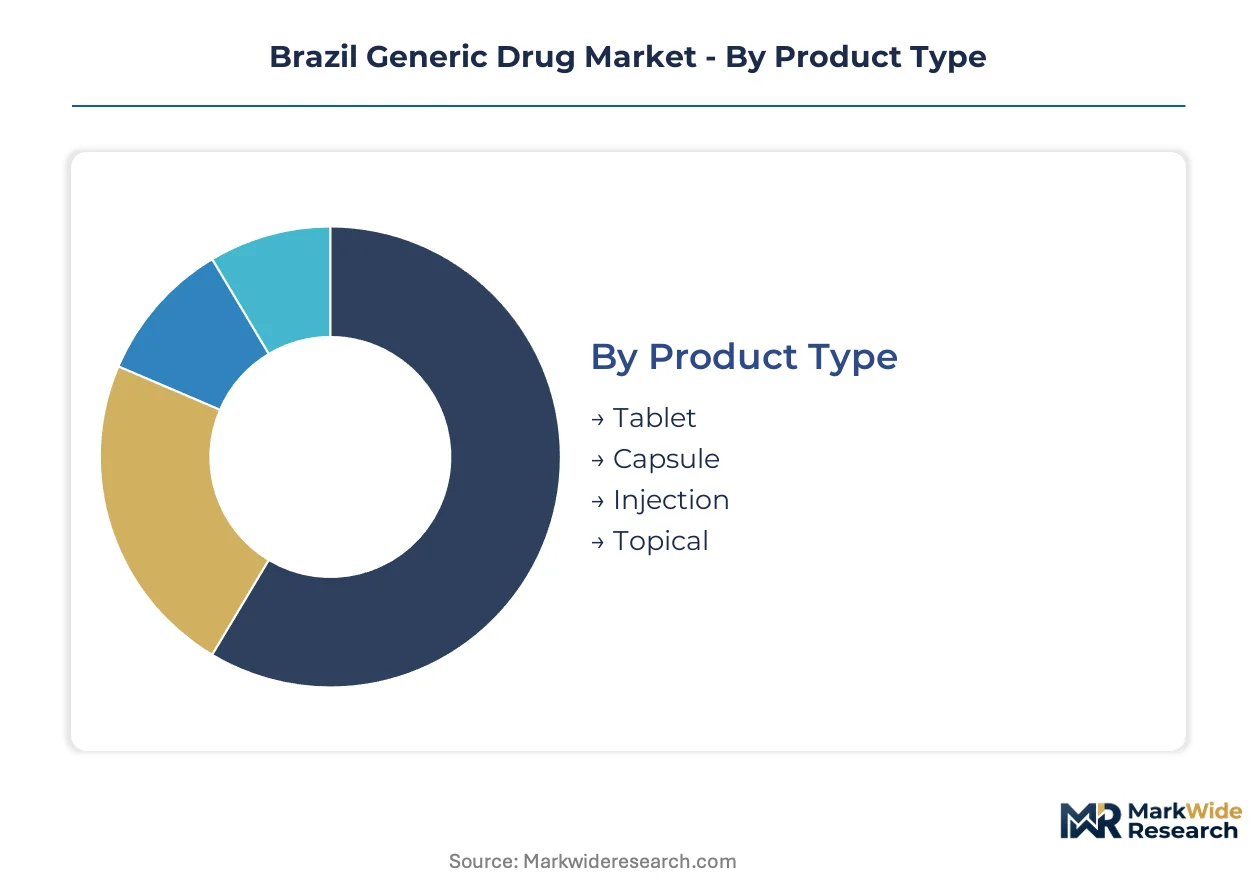
Segmentation in Brazil's generic drug market reveals how formulation complexity, therapy urgency, and procurement channel economics create divergent competitive arenas. Understanding these divides exposes where capital deployment earns returns versus where commoditization erodes margin.
Product Type:
Cycle times vary dramatically across formulations, with oral solids turning inventory fastest while sterile injectables tie up working capital through extended stability testing and cold-chain validation.
- Tablet:Direct compression and granulation technologies dominate production lines across São Paulo manufacturing corridors. Chronic disease management programs in SUS networks drive volume concentration in cardiovascular and diabetes tablets, with ANVISA's bioequivalence requirements favoring established players with study databases.
- Injection:Sterile fill-finish operations require isolator technology and pyrogen control systems that compress the supplier base to firms with dedicated injectable suites. Oncology and antibiotic injectables concentrate in hospital purchasing pools where batch traceability and cold-chain reliability determine contract awards.
- Capsule:Gelatin and HPMC shell formulations serve modified-release applications where dissolution profile matching demands sophisticated formulation science. Regional distribution hubs in Rio de Janeiro state handle capsule volumes for outpatient dispensing networks.
- Topical:Semi-solid manufacturing in creams and ointments requires specialized homogenization equipment serving dermatology and pain management segments. Pernambuco and Ceará distribution infrastructure remains underdeveloped for topical product cold-chain requirements.
Tablets anchor the volume base while injections gain share at the steepest rate as hospital procurement consolidates around suppliers with sterile manufacturing capabilities.
Therapy Area:
Cost tiers separate chronic maintenance therapies from acute intervention categories, with reimbursement pressure most intense in high-volume cardiovascular and diabetes segments.
- Cardiovascular:Antihypertensives and statins constitute the largest prescription volume within SUS formularies, with narrow-therapeutic-index drugs facing tightened ANVISA bioequivalence confidence intervals. Southeast region dispensing pharmacies handle disproportionate cardiovascular generic volume.
- Oncology:Patent cliffs on small-molecule cytotoxics and targeted therapies are expanding the addressable generic pool faster than historical norms. Hospital purchasing pools in Minas Gerais and Rio Grande do Sul consolidate supplier rosters around cold-chain reliability for these high-value injectables.
- Diabetes:Oral hypoglycemics and insulin analogs serve Brazil's expanding diabetic population through both SUS and private reimbursement channels. ANVISA's updated guidance on biosimilar interchangeability limits generic penetration in insulin categories.
- Antibiotics:Beta-lactam and macrolide generics face procurement price floors set by federal tender mechanisms, with resistance surveillance programs shaping formulary restrictions in public hospital networks.
Cardiovascular therapies anchor the volume base while oncology climbs the fastest as hospital networks expand access to substituted cancer treatments.
End User:
Customer type determines margin structure, with hospitals extracting volume discounts through consolidated tenders while retail pharmacies preserve higher per-unit economics on chronic maintenance prescriptions.
- Hospitals:SUS procurement channels and private hospital networks drive 70% of generic volume through multi-year supply agreements. Consolidated purchasing pools in São Paulo and Rio de Janeiro states have reduced supplier rosters from 15-20 vendors to 5-7 preferred partners.
- Pharmacies:Retail dispensing networks in the Southeast region concentrate 60% of pharmacy locations, with generic substitution laws enabling pharmacist-level brand switching. Independent pharmacies in Northeast states exhibit 40% lower generic penetration.
- Clinics:Outpatient specialty clinics in oncology and cardiology manage patient therapy initiation and monitoring, influencing generic selection through prescriber relationships.
- Wholesale Distributors:Regional logistics operators bridge manufacturing concentration in São Paulo state with dispersed demand across Brazil's territory, with inventory carrying costs shaped by product stability profiles.
Hospitals anchor the volume base while pharmacies gain share at the steepest rate as retail substitution laws expand generic dispensing.
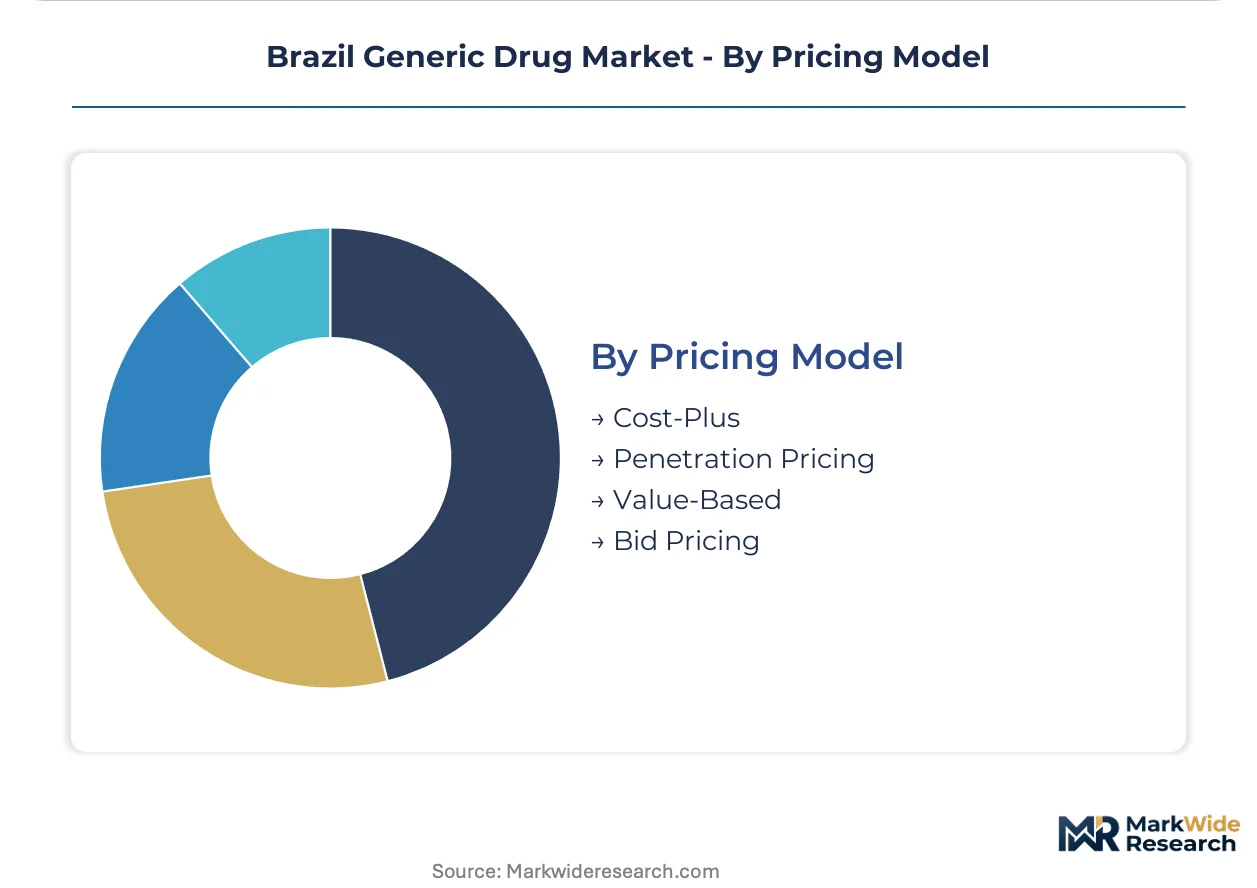
Pricing Model:
Margin structures diverge across pricing architectures, with bid pricing in public tenders compressing returns while value-based arrangements in specialty categories preserve premium positioning.
- Bid Pricing:SUS tender mechanisms establish price floors through competitive bidding, with multi-year agreements locking in volume for qualified suppliers. ANVISA GMP certification serves as a gatekeeper to bid participation.
- Penetration Pricing:New generic entrants deploy aggressive launch pricing to capture share from originator brands and incumbent generics, particularly in oral solid categories with multiple approved suppliers.
- Value-Based:Complex generics including modified-release formulations and transdermal patches command premium positioning through differentiated pharmacokinetic profiles. Technical barriers limit competitor entry.
- Cost-Plus:API import costs and manufacturing overhead determine floor pricing for commodity oral solids, with currency volatility in real-dollar exchange rates pressuring margin stability.
Bid pricing anchors the volume base while value-based arrangements gain share at the steepest rate as complex generic portfolios expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos anchors pharmaceutical logistics for Brazil's generic drug distribution, handling API imports and finished dose exports that supply manufacturing clusters across the Southeast.
São Paulo
Osasco and Guarulhos host the densest concentration of tablet manufacturing facilities serving SUS procurement networks. ANVISA's GMP certification requirements filter supplier participation in federal tenders. The São Paulo metropolitan corridor channels 60% of national generic volume through consolidated hospital purchasing pools.
Minas Gerais
Belo Horizonte's hospital networks drive demand for oncology injectables and sterile formulations. State-level procurement consolidation has reduced approved supplier rosters from 15 vendors to 6 preferred partners. Contagem's industrial district houses fill-finish operations for high-potency antibiotics.
Rio de Janeiro
Duque de Caxias and São Gonçalo distribution hubs manage cold-chain logistics for biologics and temperature-sensitive generics. The state health secretariat's formulary restrictions shape regional prescribing patterns. Niterói's manufacturing base specializes in capsule formulations for chronic disease management.
Rio Grande do Sul
Porto Alegre's hospital purchasing pools prioritize suppliers with integrated logistics and batch traceability systems. The state's generic penetration trails national averages by 12 percentage points, creating expansion whitespace. Canoas hosts regional distribution infrastructure bridging manufacturing concentration in São Paulo with Southern demand.
Bahia
Salvador's public health networks exhibit 40% lower generic utilization than Southeast benchmarks. Federal incentives under the Ex-Tarifário regime attract equipment investment for local API synthesis projects. Camaçari's chemical park offers industrial zoning for pharmaceutical manufacturing expansion.
Brazil Generic Drug Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in API supply and contract manufacturing. The supplier base compresses around three tiers: vertically integrated conglomerates with captive chemical production, mid-scale finishers with regional tender expertise, and import-dependent pure-plays. Dominant competitive moves include backward integration into active pharmaceutical ingredient synthesis and multi-year SUS supply agreement lock-ins.
Among Brazil-based pharmaceutical conglomerates, EMS and Eurofarma exemplify the integrated-platform archetype, while Aché occupies a position bridging domestic formulation expertise with international partnership structures. Sun Pharmaceutical represents the cost-efficient import-oriented model competing on high-volume oral solid pricing.
| Leading Market Players |
|---|
| Grupo NC |
| Biolab |
| Hypera Pharma |
| Sun Pharmaceutical |
| Libbs |
| Eurofarma |
| Aché |
| FQM |
| EMS |
| Others |
Cost & Logistics Intelligence
São Paulo's manufacturing corridor concentrates tablet and capsule production capacity, creating asymmetric pricing power for vertically integrated firms with captive API synthesis against import-dependent finishers squeezed by currency volatility. SUS procurement pools exploit this concentration through consolidated tenders that lock in multi-year volume commitments at bid-price floors, while smaller manufacturers absorb margin compression from extended payment terms and inventory carrying costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates complex modified-release formulations from commodity oral solids and high-volume tender products. Certification grade under ANVISA GMP protocols and volume scale through SUS network participation drive price differentiation between qualified suppliers and marginal entrants. Cost compression in standard oral solids is intensifying because penetration pricing from new entrants and consolidated hospital purchasing pools extract volume discounts. Public hospital networks exhibit highest price sensitivity due to fixed reimbursement ceilings, while private oncology clinics preserve premium tolerance for cold-chain reliable injectables.
Supply Chain Analysis
Extended payment terms stretching 90-120 days and supply-chain finance facilities anchored by distributor credit lines strain working capital for API-importing finishers. Active pharmaceutical ingredient supply draws from Indian and Chinese chemical parks, with excipient sourcing resting on European and domestic Brazilian suppliers. Single-source vulnerability concentrates in high-potency oncology intermediates where qualified alternative suppliers number fewer than five globally. Distribution runs through São Paulo-based regional hubs that bridge manufacturing concentration with dispersed pharmacy networks across Brazil's territory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's generic drug market sits at a platform-economics inflection where SUS procurement digitization and consolidated purchasing pool interoperability are collapsing fragmented supplier rosters into preferred partner ecosystems.
For Market Incumbents: Harden formulary lock-in through integrated logistics services and batch traceability systems that hospital purchasing pools in Minas Gerais and Rio Grande do Sul now mandate for contract eligibility. Deepen backward integration into API synthesis to neutralize currency exposure from Indian and Chinese chemical park dependencies that threaten margin stability. Channel control through dedicated SUS account teams represents the critical defensive lever against emerging pure-play finishers.
For New Entrants and Emerging Players: Northeast regional underpenetration in Ceará, Pernambuco, and Bahia offers whitespace where generic utilization trails Southeast benchmarks by 40 percentage points. Complex generic formulations including modified-release oral solids and transdermal patches face limited qualified competition due to ANVISA bioequivalence study bottlenecks. A go-to-market angle anchored by specialty distribution partnerships with regional hospital networks bypasses incumbent SUS tender dominance.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated platforms with captive API production and established ANVISA study databases over asset-light import-dependent models. Long-term viability across the analysis window rests on regulatory moat depth and SUS relationship tenure rather than manufacturing scale alone. The signal to monitor is ANVISA patent linkage legislation progression, which would elevate originator brand defense capabilities and reshape generic substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captive production of active pharmaceutical ingredients neutralizes currency volatility from Indian and Chinese supply concentration. |
| ANVISA Bioequivalence Study Database Expansion | Established pharmacokinetic portfolios accelerate product launches under tightened narrow-therapeutic-index guidance. |
| Northeast Regional Distribution Infrastructure | Salvador and Recife hubs capture 40% generic penetration gap versus Southeast benchmarks. |
| Continuous Manufacturing Technology Deployment | Modular direct compression lines at EMS and Eurofarma collapse changeover times from days to hours. |
| Hospital Purchasing Pool Partnership Lock-in | Integrated logistics and formulary management services secure preferred vendor status in consolidated tenders. |
Research Approach
Initial hypotheses were tested against primary input from regulatory affairs directors, hospital procurement managers, pharmaceutical manufacturing executives, and SUS formulary specialists and refined through secondary validation against ANVISA registration databases, SUS tender award records, and Brazilian customs trade statistics. Bottom-up triangulation across dosage form volumes and top-down reconciliation against therapy area expenditure patterns anchored market sizing integrity.
Demand-supply-balance framing modeled patient population growth, patent expiry schedules, and manufacturing capacity utilization across the projection horizon. Segmentation dimensions included product type, therapy area, end-user channel, and regional regulatory cluster. CAGRs derived from compound growth trajectory analysis of historical volume trends and policy-driven procurement expansion assumptions. Forecast inputs incorporated ANVISA inspection queue durations and Ex-Tarifário equipment import incentive uptake rates.
Macroeconomic conditions sit as an overlay; deviation in real-dollar exchange rates, federal health budget allocations, or API export restrictions from India and China would shift the trajectory. Forecasts reflect documented assumptions about SUS procurement digitization timelines and biosimilar interchangeability rule evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Biotherapeutics Cell Line Development Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Biopharmaceuticals Packaging Market
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Vaccine Ampoules Market
Biopharmaceuticals
Antimycobacterial Drugs Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Glucagon Injectable Market