
 Immunotoxins Market | 2026-2036
Immunotoxins Market Size, Share, and Industry Trends Forecast 2026-2036
Immunotoxins Market Analysis
Oncology is recalibrating its therapeutic hierarchy as immunotoxins gain priority in refractory leukemia protocols. ImmunoGen leverages its payload-linker expertise to sustain manufacturing partnerships across North American and European supply chains. Roche anchors its position through deep clinical trial networks in hematologic oncology, while Creative Biolabs competes by offering contract development services for emerging biotech entrants seeking rapid proof-of-concept data.
Immunotoxins constitute chimeric proteins engineered by fusing antibody fragments with catalytic toxin domains, typically achieving molecular weights between 50-70 kDa to optimize tumor penetration while minimizing systemic toxicity; their primary commercial purpose centers on selective elimination of malignant or pathogenic cell populations without collateral damage to healthy tissue. Conjugates command the dominant value share due to complex manufacturing requirements and extended development timelines that create defensible margin pools. Targeted delivery systems represent the fastest-expanding technology segment as nanoparticle encapsulation and conditional release mechanisms address historical limitations in therapeutic index. Cancer treatment applications absorb the majority of clinical investment, though autoimmune disorders are attracting exploratory protocols as understanding of B-cell depletion mechanisms broadens.
FDA oversees immunotoxin approval through its Center for Drug Evaluation and Research, while EMA applies its Advanced Therapy Medicinal Products framework to novel conjugate submissions; both agencies require extensive immunogenicity profiling that shapes preclinical development costs and timeline planning. ISO 10993 biocompatibility standards govern device components in combination products, adding compliance layers for delivery system innovators. Stakeholders must monitor evolving biosimilar guidance from FDA and EMA, as patent cliffs on pioneer conjugates will test regulatory clarity around analytical similarity standards for complex protein-toxin constructs.
Market Dynamics
FDA and EMA accelerated approval pathways are compressing development timelines for antibody-drug conjugates, forcing manufacturers to restructure clinical trial designs and preclinical validation protocols around faster regulatory feedback loops.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:The streamlined pathway reduces review periods for novel conjugates, enabling European biotech firms to reach pivotal trials faster than conventional biologics routes permit.
- Hematologic oncology infusion centers:Specialized administration facilities in the United States, Germany, and Japan are expanding capacity to handle immunotoxin protocols, creating pull-through demand for qualified manufacturing slots.
- Conditional release mechanisms:Nanoparticle encapsulation technologies now enable tumor-microenvironment activation, broadening the therapeutic index for previously shelved toxin payloads.
Market Restraints
- Recombinant protein production bottlenecks:Mammalian cell culture capacity constraints in contract manufacturing organizations limit batch throughput for fusion protein constructs.
- Immunogenicity profiling costs:FDA and EMA requirements for extensive anti-drug antibody monitoring inflate preclinical development expenditures before first-in-human dosing.
- Plasma-derived toxin supply concentration:Catalytic domain sourcing depends on a narrow supplier base in Switzerland and Denmark, exposing pipelines to raw material availability risks.
Strategic Opportunities
- Autoimmune disorder protocols:B-cell depletion mechanisms validated in oncology are transferring to lupus and rheumatoid arthritis indications, opening addressable populations beyond cancer.
- Japan's regenerative medicine incentives:METI funding streams for advanced biologics manufacturing support local production partnerships for Asia-Pacific market access.
- Biosimilar analytical similarity standards:Evolving FDA and EMA guidance on complex protein-toxin constructs will define first-mover advantage for reference product sponsors navigating patent cliffs.
Industry Challenges
- Payload-linker chemistry expertise scarcity:The specialized skill set bridging medicinal chemistry and bioconjugation commands premium compensation, constraining team expansion at emerging developers.
- ISO 10993 biocompatibility testing timelines:Device component validation for combination products adds six to nine months to regulatory submission preparation.
- Legacy cold chain infrastructure gaps:Many hospital networks lack validated storage and handling protocols for temperature-sensitive biologics, complicating site qualification for multi-center trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunotoxins Market |
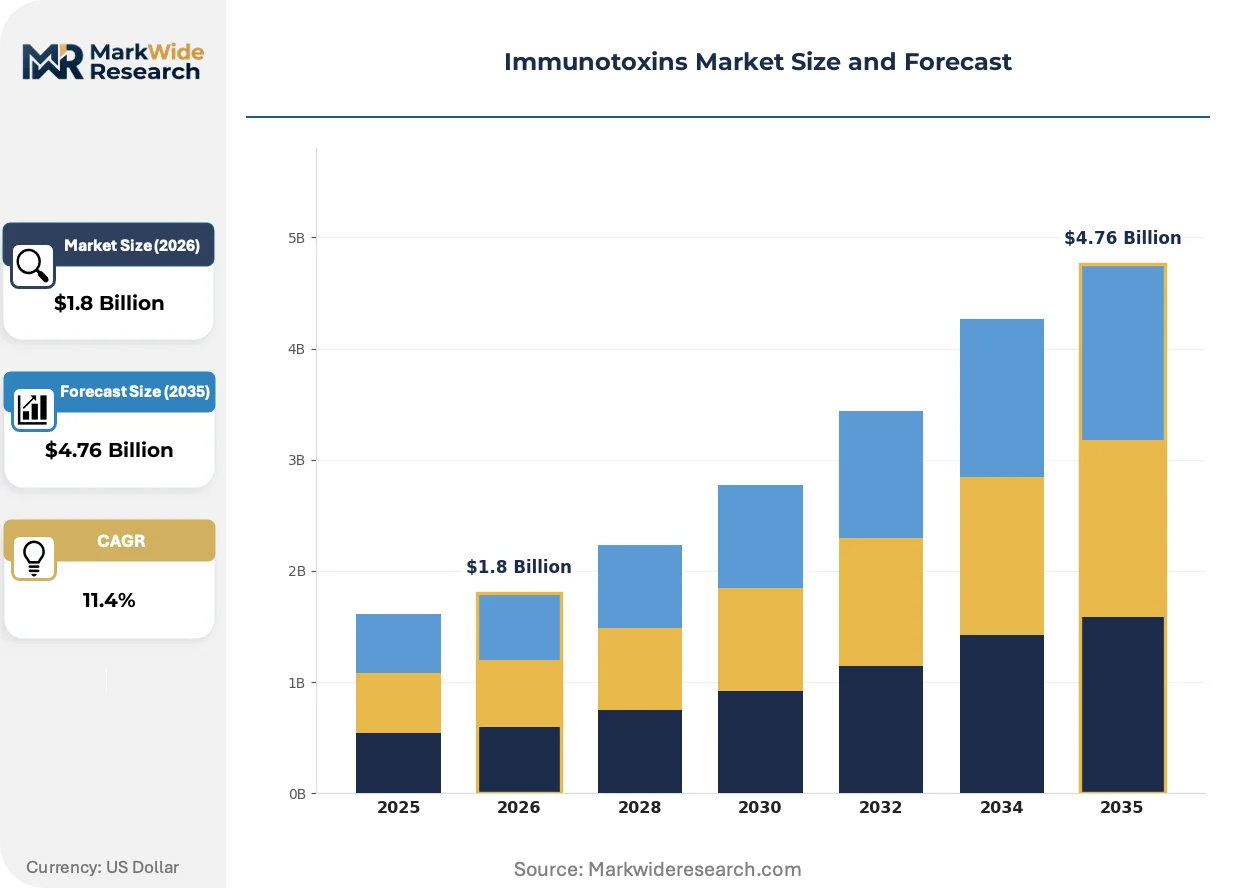
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Recombinant Proteins, Conjugates, Biocontrol Agents Application: Cancer Treatment, Infectious Disease Management, Autoimmune Disorders, Gene Therapy End User: Hospitals, Clinics, Research Laboratories, Pharmaceutical Companies Technology: Targeted Delivery Systems, Transfection Methods, Nanotechnology, Hybridoma Technology |
| Companies Covered | Genmab, ImmunoGen, Amgen, Roche, AstraZeneca, Merck KGaA, Creative Biolabs, Thermo Fisher Scientific, ADC Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunotoxins Market Emerging Trajectories
Antibody engineering and toxin payload optimization are converging to redefine therapeutic index calculations, while regulatory frameworks adapt to the unique immunogenicity profiles of chimeric protein constructs.
Site-specific conjugation chemistry is unifying antibody and toxin components through engineered cysteine residues and enzymatic ligation systems. Oncology departments are adopting these platforms for hematologic malignancy protocols previously resistant to conventional chemotherapy. The technology is unifying manufacturing quality metrics across North American and European supply chains, reducing batch-to-batch variability that previously triggered regulatory holds.
EMA's Advanced Therapy Medicinal Products framework is recalibrating European development strategies for novel conjugate submissions. The regulation mandates extensive immunogenicity profiling that shapes preclinical cost structures and timeline planning. Hematologic oncology applications absorb the majority of pathway utilization, with sponsors restructuring CMC packages to align with ATMP quality expectations.
Hospital procurement departments are consolidating immunotoxin purchasing through specialized infusion center networks rather than broad pharmacy formularies. The channel shift concentrates volume with sites demonstrating validated cold chain handling and adverse event monitoring capabilities. Germany and Japan exhibit the most pronounced consolidation, where reimbursement frameworks explicitly favor accredited administration facilities over general oncology wards.
Immunotoxins Market Segmentation
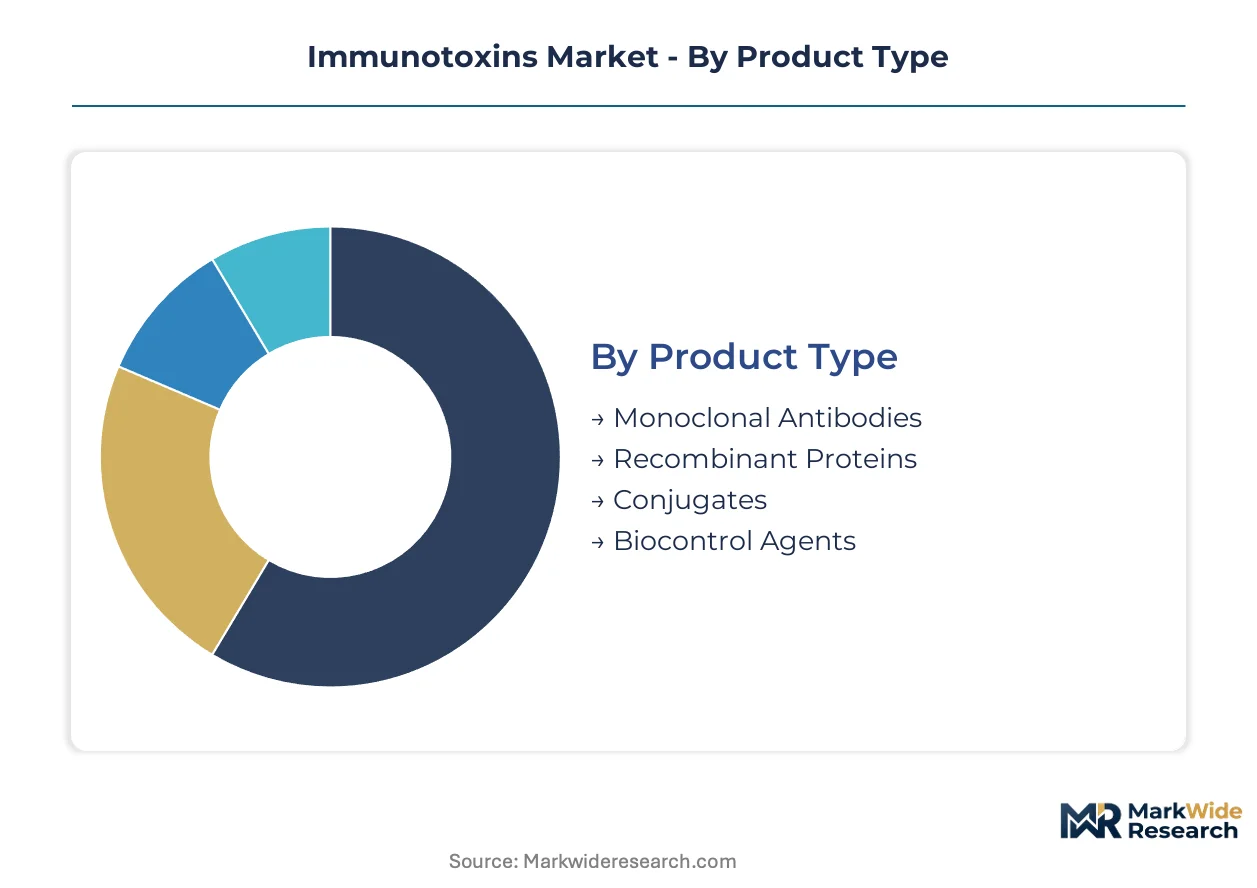
Immunotoxin procurement decisions pivot on manufacturing complexity, therapeutic specificity, and administration infrastructure requirements. Buyers weigh payload-linker chemistry sophistication against cold chain logistics capabilities when selecting product categories for hospital formulary inclusion.
Product Type:
Cost tier determines access patterns, with complex conjugates commanding premium procurement budgets while simpler recombinant formats penetrate price-sensitive channels.
- Conjugates:These chimeric constructs fuse antibody fragments with catalytic toxin domains through engineered linker chemistries, achieving molecular weights of 50-70 kDa for optimized tumor penetration. Demand concentrates in United States and German hematologic oncology centers where specialized infusion facilities manage the narrow therapeutic index. Manufacturing partnerships with mammalian cell culture specialists create supply bottlenecks that limit batch throughput.
- Monoclonal Antibodies:Unconjugated antibody platforms serve as targeting moieties for subsequent toxin attachment or function through immune-mediated cytotoxicity. Japanese hospital networks favor these formats for protocol flexibility in combination regimens. The segment benefits from established cold chain distribution networks that reduce site qualification burdens for multi-center trials.
- Recombinant Proteins:Fusion protein constructs produced through bacterial or yeast expression systems offer simplified manufacturing economics.
- Biocontrol Agents:Plant-derived and microbial toxin variants find application in agricultural and environmental pathogen control.
Volume sits with Conjugates; growth tilts toward Recombinant Proteins as expression platform improvements compress production costs.
Application:
Clinical validation depth shapes reimbursement pathways, with oncology indications attracting concentrated investment while emerging therapeutic areas await proof-of-concept milestones.
- Cancer Treatment:Hematologic malignancies absorb the majority of immunotoxin protocols, with acute lymphoblastic leukemia and hairy cell leukemia demonstrating durable complete response rates. United States academic medical centers anchor demand through specialized CAR-T and immunotoxin combination studies. FDA accelerated approval pathways compress development timelines for refractory patient populations.
- Autoimmune Disorders:B-cell depletion mechanisms validated in oncology are transferring to lupus and rheumatoid arthritis indications. German rheumatology clinics are pioneering exploratory protocols for systemic lupus erythematosus. The expansion depends on demonstrating acceptable immunogenicity profiles in chronic administration settings.
- Infectious Disease Management:Antibody-toxin conjugates target drug-resistant bacterial and viral pathogens.
- Gene Therapy:Immunotoxins enable selective depletion of transduced cell populations in ex vivo gene editing workflows.
Clinical investment clusters in Cancer Treatment; pipeline momentum is building fastest in Autoimmune Disorders as mechanism understanding broadens.
End User:
Administration complexity filters customer segments, with infusion center capabilities determining which institutions qualify for immunotoxin protocols.
- Hospitals:Specialized oncology wards and infusion centers in the United States, Germany, and Japan administer the majority of immunotoxin doses. These facilities maintain validated cold chain infrastructure and adverse event monitoring protocols required by EMA and FDA risk management frameworks. Reimbursement structures explicitly favor accredited administration sites over general hospital pharmacies.
- Research Laboratories:Academic and contract research organizations drive preclinical validation and early-phase clinical investigation. Swiss and Danish research clusters concentrate catalytic domain sourcing relationships for toxin payload development. These institutions shape immunogenicity profiling standards that inform regulatory submission strategies.
- Clinics:Outpatient oncology clinics with infusion capabilities are expanding participation in community-based trial networks.
- Pharmaceutical Companies:Sponsor organizations internalize manufacturing partnerships and regulatory strategy functions.
Procurement volume concentrates with Hospitals; capability expansion is proceeding most rapidly in Research Laboratories as preclinical investment intensifies.
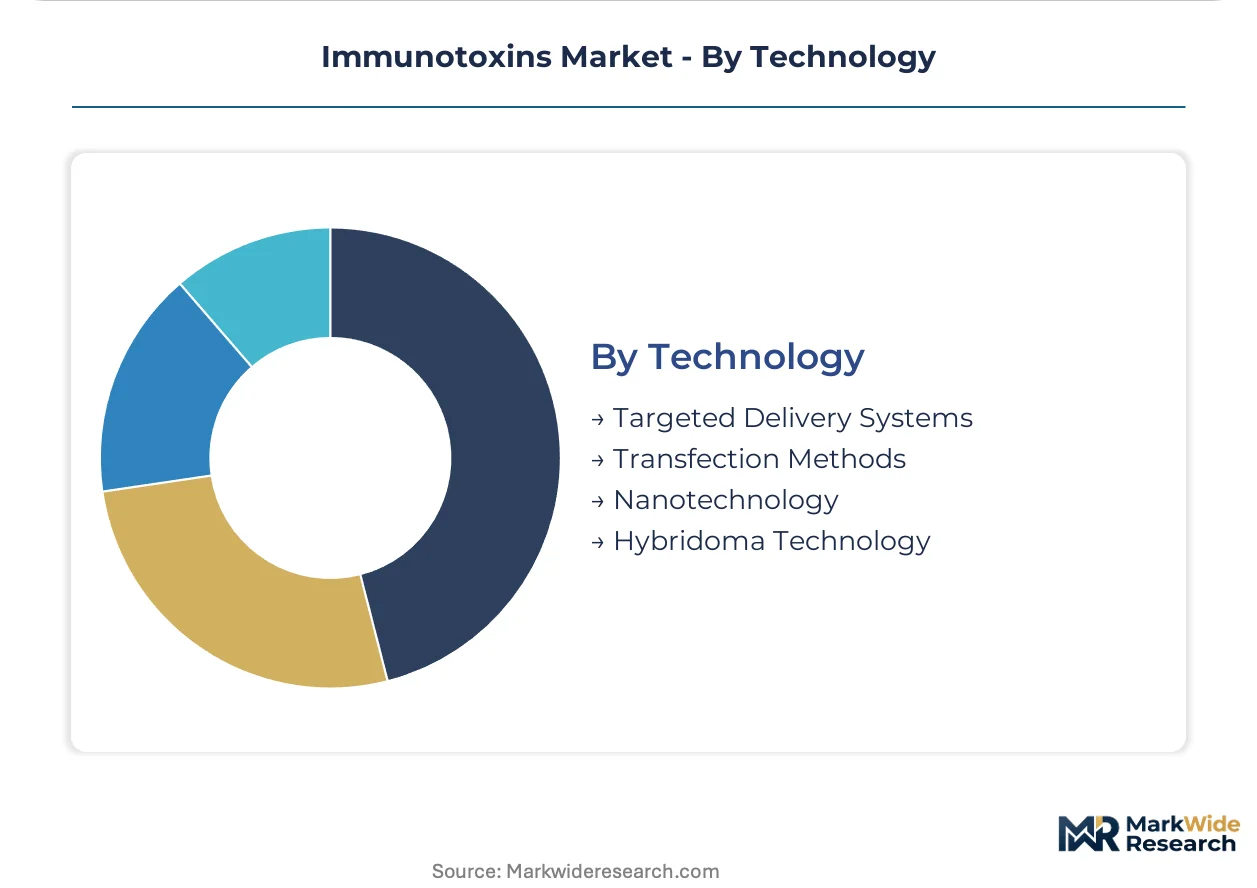
Technology:
Intellectual property concentration around payload-linker and delivery innovations is reshaping competitive positioning among platform developers.
- Targeted Delivery Systems:Nanoparticle encapsulation and conditional release mechanisms enable tumor-microenvironment activation of previously shelved toxin payloads. Japanese METI funding streams support local manufacturing partnerships for these advanced formats. The technology addresses historical therapeutic index limitations that constrained first-generation immunotoxin adoption.
- Nanotechnology:Liposomal and polymeric carrier systems improve pharmacokinetic profiles and reduce immunogenicity. German precision medicine initiatives are accelerating clinical translation of these platforms. Scale-up challenges in sterile manufacturing remain a binding constraint on commercial supply.
- Hybridoma Technology:Murine and humanized antibody production through hybridoma fusion remains foundational for target validation.
- Transfection Methods:Viral and non-viral gene delivery approaches enable transient immunotoxin expression in cellular therapies.
Development investment clusters in Targeted Delivery Systems; technology maturation is advancing most quickly in Nanotechnology as manufacturing protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones in Massachusetts and Basel-Stadt concentrate immunotoxin development through tax-advantaged R&D facilities and accelerated regulatory consultation programs.
United States
FDA accelerated approval pathways compress development timelines for antibody-drug conjugates targeting refractory hematologic malignancies. The Center for Drug Evaluation and Research mandates extensive immunogenicity profiling that shapes preclinical cost structures. Greater Boston anchors demand through academic medical centers expanding specialized infusion center capacity for CAR-T and immunotoxin combination protocols.
Germany
EMA's Advanced Therapy Medicinal Products framework reduces review periods for novel conjugates, enabling faster pivotal trial initiation than conventional biologics routes permit. The country's national pharmaceutical regulator applies ISO 10993 biocompatibility standards to device components in combination products. The Rhine-Main cluster concentrates manufacturing partnerships with mammalian cell culture specialists serving European supply chains.
Japan
METI funding streams for advanced biologics manufacturing support local production partnerships targeting Asia-Pacific market access. PMDA oversight aligns with EMA quality expectations for complex protein-toxin constructs. The Kanto region hosts specialized infusion centers qualifying for reimbursement frameworks that explicitly favor accredited administration facilities over general oncology wards.
Switzerland
Swissmedic maintains alignment with EMA guidance while offering direct scientific advice pathways for novel conjugate submissions. Catalytic domain sourcing for toxin payloads concentrates in Basel and Zurich research clusters. The country's central pharmaceutical regulator requires anti-drug antibody monitoring protocols that inform global preclinical development standards.
United Kingdom
MHRA post-Brexit recognition agreements with FDA and EMA preserve streamlined approval pathways for immunotoxin developers. The national medicines regulator emphasizes quality manufacturing standards for biologics that mirror European expectations. The Golden Triangle research corridor drives preclinical validation through contract research organizations specializing in immunogenicity profiling.
Immunotoxins Market Vendor Landscape
Top-tier vendors anchor conjugate development through payload-linker expertise and deep clinical trial networks, while mid-tier contract developers compete on rapid proof-of-concept timelines for emerging biotech entrants. The vendor base stratifies across integrated pharmaceutical conglomerates, specialized bioconjugation service providers, and research tool suppliers. Three archetypes dominate: platform technology licensors, end-to-end development partners, and manufacturing-focused contract organizations. Competitive moves concentrate on strategic partnerships for mammalian cell culture capacity and technology licensing for site-specific conjugation chemistries.
Among North American and European developers, ImmunoGen, Roche, and Creative Biolabs occupy distinct positions within the competitive structure. ImmunoGen exemplifies the platform technology archetype through sustained manufacturing partnerships leveraging payload-linker expertise. Roche represents integrated pharmaceutical scale with established hematologic oncology clinical networks. Creative Biolabs sits within the contract development tier, offering services that enable emerging biotech entrants to compress proof-of-concept timelines. These three entities collectively illustrate how competitive positioning fragments across technology ownership, clinical infrastructure, and service provision models.
| Leading Market Players |
|---|
| Genmab |
| ImmunoGen |
| Amgen |
| Roche |
| AstraZeneca |
| Merck KGaA |
| Creative Biolabs |
| Thermo Fisher Scientific |
| ADC Therapeutics |
| Others |
Supply Flow & Price Mechanics
ISO 10993 biocompatibility certification gates both qualified supply and premium-tier pricing access for combination product developers, with device component validation costs filtering manufacturers into distinct cost tiers and contract manufacturing slots.
Pricing Analysis
Lead-time-driven pricing stratifies across contract manufacturing tiers, with mammalian cell culture slots commanding premium rates for expedited batch turnaround while spot inventory of recombinant protein constructs trades at discounted clearing levels. Three-tier pricing structure across premium, standard, and economy levels reflects payload-linker chemistry sophistication and ISO certification tier, with FDA master file status anchoring the top tier. Cost compression in standard-grade fusion proteins is intensifying because bacterial expression platform improvements expand supplier pools. Academic medical centers demonstrate highest price sensitivity due to formulary budget constraints, while specialized infusion networks absorb premium tier increases through bundled reimbursement frameworks.
Supply Chain Analysis
Direct-to-biotech-sponsor channels handle development-stage demand through contract manufacturing organizations, with hospital procurement departments consolidating volume through accredited infusion center networks. Catalytic domain sourcing concentrates in Switzerland and Denmark, with mammalian cell culture capacity anchoring in United States and Germany. Raw material dependencies span recombinant toxin payloads, engineered linker chemistries, and pharmaceutical-grade monoclonal antibodies. Single-source vulnerability in plasma-derived catalytic domains exposes pipelines to raw material availability disruptions. Distribution runs through cold chain logistics specialists validated for temperature-sensitive biologics handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream integration into mammalian cell culture capacity represents the critical lever in this vertical-integration race, with control over batch throughput determining competitive positioning in qualified manufacturing slots.
For Market Incumbents: Lock in payload-linker chemistry expertise through exclusive licensing arrangements with academic research clusters, defending against emerging biotech entrants armed with novel site-specific conjugation platforms. Expand captive mammalian cell culture capacity in Rhine-Main and Greater Boston clusters to secure batch allocation priority as contract manufacturing bottlenecks intensify.
For New Entrants and Emerging Players: Contract research organizations in the Golden Triangle corridor offer the most penetrable channel partnership for rapid proof-of-concept generation, enabling compressed timeline entry against established platform licensors. Target autoimmune disorder protocols as the whitespace indication with lowest competitive density and fastest reimbursement pathway expansion.
For Investors and Strategic Acquirers: First FDA accelerated approval for a novel autoimmune immunotoxin is the leading indicator that mechanism translation from oncology has reached investable inflection. Platform technology licensors with established payload-linker IP estates represent the priority acquisition archetype over asset-specific developers. Monitor EMA ATMP pathway utilization rates as the signal for European market access timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive mammalian cell culture capacity secures batch allocation priority against contract manufacturing bottlenecks. |
| Regulatory Approval Pathway | FDA accelerated approval compresses development timelines for refractory hematologic malignancy indications. |
| Licensing Agreement | Payload-linker IP licensing from ImmunoGen enables emerging developers to access validated toxin chemistry platforms. |
| Clinical Trial Advancement | CAR-T and immunotoxin combination studies at academic medical centers generate pivotal trial data for refractory populations. |
| Pipeline Diversification | Autoimmune disorder protocol expansion transfers validated B-cell depletion mechanisms to lupus and rheumatoid arthritis. |
Methodological Framework
Multi-period observation of FDA and EMA submission trajectories, clinical trial activation rates, and infusion center capacity expansion anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Input-output matrices mapped conjugate manufacturing throughput, payload-linker chemistry adoption curves, and regional reimbursement framework evolution across the projection horizon. Segmentation dimensions spanned product type, application, end user, and technology platform, with patient population subgroups and regional regulatory clusters as cross-cutting analytical layers. CAGRs derived from fitted growth curves applied to validated baseline estimates, with immunogenicity profiling cost trajectories and cold chain infrastructure buildout rates as key forecast inputs.
Caveats apply where accelerated approval pathway utilization shifts, biosimilar guidance clarity delays, or plasma-derived toxin supply disruptions could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Triclabendazole Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
Drug Discovery Outsourcing Market