
 Tuberculosis Biomarkers Market | 2026-2036
Tuberculosis Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Tuberculosis Biomarkers Market Analytics
Specialized molecular biologists is rotating from academic centers into commercial assay development, easing bottlenecks in PCR and LAMP test validation. F. Hoffmann-La Roche leverages its GeneXpert installed base to sustain recurring cartridge revenue across endemic markets. QIAGEN anchors sample-prep automation workflows that laboratories adopt prior to downstream TB detection. Danaher Corporation competes through integrated liquid-handling platforms that reduce manual nucleic acid extraction steps.
Tuberculosis biomarkers comprise measurable biological indicators—cytokines, antibodies, nucleic acid signatures, or volatile organic compounds—detected in blood, sputum, or urine specimens to indicate Mycobacterium tuberculosis infection or disease progression. These indicators serve primarily to distinguish active disease from latent infection, monitor treatment response, and identify drug-resistant strains when conventional microscopy proves insufficient. Molecular diagnostics leads product type revenue owing to higher per-test pricing and WHO endorsement of nucleic acid amplification technologies. PCR-based platforms dominate technology deployment in centralized laboratories, while LAMP gains traction in point-of-care settings where infrastructure constraints limit complex instrumentation. Drug development applications represent the fastest-expanding segment as pharmaceutical sponsors require validated biomarker endpoints for adaptive clinical trial designs.
FDA enforces analytical validation standards for in vitro diagnostic devices used in U.S. TB screening programs, while WHO prequalification governs procurement eligibility for low- and middle-income country tenders. EMA's In Vitro Diagnostic Regulation imposes post-market surveillance obligations that reshape European assay development priorities. Stakeholders must monitor evolving WHO target product profiles for next-generation biomarker tests, as these specifications determine which technologies qualify for volume procurement commitments and associated market access.
Market Dynamics
WHO prequalification pathways are compressing technology transfer timelines, forcing assay developers to align R&D roadmaps with procurement eligibility criteria rather than autonomous commercialization cycles.
Growth Catalysts
- PEPFAR procurement frameworks:These mechanisms accelerate volume commitments for nucleic acid amplification platforms across sub-Saharan African laboratories, creating predictable demand visibility for cartridge manufacturers.
- India's Revised National Tuberculosis Control Programme:The mandate for biomarker-based confirmation of all presumptive cases generates institutional demand pull that outpaces discretionary healthcare spending in comparable economies.
- LAMP technology maturation:Loop-mediated isothermal amplification reduces cold-chain dependencies, enabling deployment in peripheral health facilities where PCR infrastructure remains prohibitive.
Market Restraints
- Reagent supply concentration:Polymerase and reverse transcriptase production clusters in contract manufacturers serving broad diagnostic portfolios, exposing TB-specific assay developers to allocation rationing during pandemic response periods.
- EMA post-market surveillance obligations:The In Vitro Diagnostic Regulation imposes continuous performance monitoring costs that disproportionately burden mid-scale developers lacking integrated quality management systems.
- Sputum-based specimen limitations:Pediatric and extrapulmonary TB cases frequently yield inadequate sample volumes, constraining molecular test sensitivity in patient populations with highest unmet diagnostic need.
Strategic Opportunities
- Volatile organic compound breath analysis:Point-of-care biosensors detecting Mycobacterium tuberculosis metabolic byproducts circumvent specimen collection logistics entirely, opening access to community screening programs.
- Adaptive clinical trial biomarker endpoints:Pharmaceutical sponsors require validated surrogate markers for treatment response, creating service revenue streams for laboratories with longitudinal sample biobanking capabilities.
- Sample-prep automation integration:Pre-analytical workflow standardization reduces technician-to-technician variability, positioning automated nucleic acid extraction platforms as mandatory infrastructure investments preceding detection technology selection.
Industry Challenges
- Molecular biologist talent scarcity:Commercial assay development competes with academic research centers for specialized PCR and LAMP validation expertise, extending product development timelines.
- WHO target product profile compliance:Evolving specifications for sensitivity, specificity, and time-to-result require iterative redesign cycles that strain fixed R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tuberculosis Biomarkers Market |
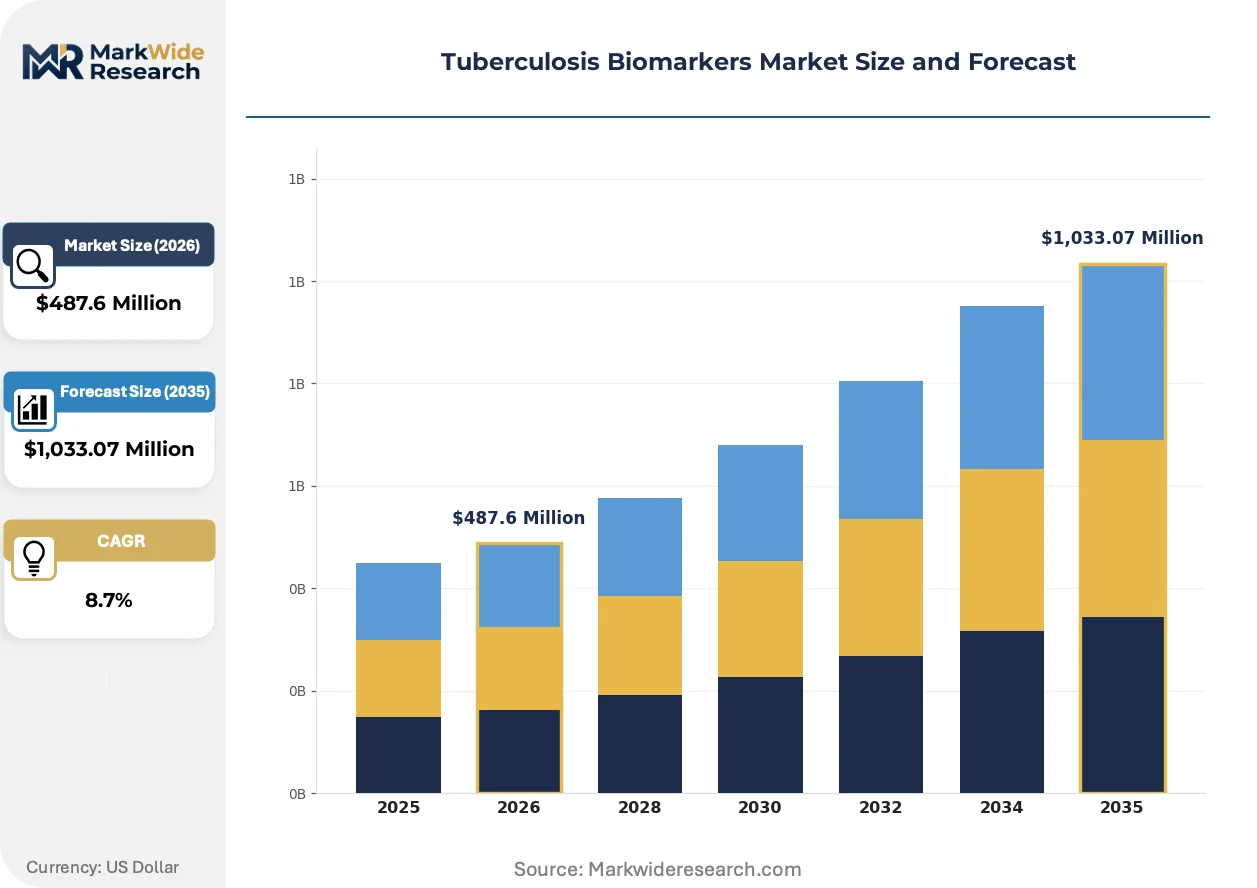
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Tests, Sputum Tests, Urine Tests, Molecular Diagnostics Technology: PCR, ELISA, GeneXpert, LAMP Application: Diagnostics, Research, Drug Development, Vaccine Development End User: Hospitals, Laboratories, Research Institutions, Clinics |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche, QIAGEN, Danaher Corporation, bioMérieux, Thermo Fisher Scientific, Becton Dickinson, Hologic, Oxford Immunotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tuberculosis Biomarkers Market Evolving Landscape
Next-generation detection modalities are fragmenting the centralized-laboratory monopoly on TB diagnosis, redistributing analytical capability toward point-of-care settings and non-traditional specimen types.
CRISPR-based diagnostics is displacing conventional nucleic acid amplification in early feasibility studies. Research consortia in South Africa and Brazil are validating SHERLOCK and DETECTR platforms for rifampicin resistance screening. The technology compresses equipment footprints to handheld dimensions, enabling deployment in mobile clinic configurations previously restricted to microscopy.
FDA's analytical validation standards for in vitro diagnostic devices used in U.S. TB screening programs are tightening evidentiary requirements for predicate device comparisons. Manufacturers must now demonstrate clinical performance across diverse population demographics rather than homogeneous reference cohorts. This regulatory friction is accelerating investment in decentralized clinical trial networks spanning multiple high-burden countries.
Diagnostic laboratories in high-burden countries are unbundling after-sales service contracts from instrument procurement, preferring subscription-based reagent supply agreements with embedded technical support. This purchasing pattern shift compresses upfront capital requirements while locking buyers into multi-year consumable commitments. The model is most visible in Indian state-level laboratory networks, where consolidated tenders now specify total cost-per-test rather than capital expenditure ceilings.
Tuberculosis Biomarkers Market Segmentation
Biomarker selection determines specimen logistics, equipment investment, and reimbursement pathways across TB control programs. Segmentation reveals where molecular platforms displace conventional microscopy and which customer types drive platform selection decisions.
Product Type:
Molecular diagnostics face substitution pressure from emerging breath-based detection, while sputum and blood tests defend entrenched positions in national screening protocols.
- Blood Tests:Interferon-gamma release assays and serological antibody panels detect latent infection through peripheral venipuncture. Indian state health departments procure Quantiferon-TB Gold in bulk for high-risk population screening, though IGRA indeterminate rates in immunocompromised patients constrain universal deployment.
- Sputum Tests:Acid-fast bacilli smear microscopy and culture-based confirmation remain the diagnostic backbone in resource-constrained settings. WHO endorsement of Xpert MTB/RIF as initial test in key populations is accelerating sputum-based molecular conversion in South African and Kenyan reference laboratories.
- Urine Tests:Lipoarabinomannan antigen detection offers non-sputum alternative for HIV-coinfected adults with advanced immunosuppression.
- Molecular Diagnostics:Nucleic acid amplification platforms command premium pricing through integrated rifampicin resistance detection.
Sputum tests anchor the volume base while molecular diagnostics gains share at the steepest rate.
Technology:
Cost tiers separate centralized laboratory platforms from point-of-care alternatives, with procurement budgets determining technology lock-in across health system tiers.
- PCR:Polymerase chain reaction delivers highest analytical sensitivity for paucibacillary specimens through thermal cycling instrumentation. Centralized laboratories in Brazil and Indonesia maintain PCR workflows for drug susceptibility testing, though cold-chain reagent storage limits peripheral deployment.
- GeneXpert:Cartridge-based integrated sample processing eliminates separate nucleic acid extraction steps. PEPFAR procurement frameworks in Nigeria and Ethiopia specify GeneXpert as the standard-of-care for presumptive TB diagnosis, creating locked-in consumable demand.
- ELISA:Enzyme-linked immunosorbent assay formats support cytokine biomarker quantification in research settings.
- LAMP:Loop-mediated isothermal amplification operates at constant temperature without thermal cyclers.
GeneXpert commands the installed base while LAMP expands most quickly into peripheral health posts.
Application:
Customer maturity separates regulated diagnostic use from exploratory research applications, with pharmaceutical sponsorship driving biomarker endpoint validation.
- Diagnostics:Clinical confirmation of active disease and treatment monitoring generates recurring test volume through national program procurement. India's Revised National Tuberculosis Control Programme mandates biomarker-based confirmation for all presumptive cases, institutionalizing demand independent of private healthcare utilization.
- Drug Development:Adaptive clinical trial designs require validated surrogate biomarkers for early efficacy signals. TB Alliance and pharmaceutical sponsors contract specialized laboratories for longitudinal sample biobanking and pharmacodynamic marker analysis.
- Research:Academic consortia investigate novel antigen targets and host transcriptomic signatures.
- Vaccine Development:Immunogenicity assessment and correlates-of-protection studies support candidate evaluation.
Diagnostics anchors the volume base while drug development climbs the fastest as trial complexity intensifies.
End User:
Specimen throughput and technical staffing determine platform selection across facility types, with national reference laboratories consolidating complex testing.
- Laboratories:National reference centers and state-level facilities process high-throughput screening and drug susceptibility confirmation. South African NHLS laboratories maintain automated liquid culture and molecular line probe assay capacity for multidrug-resistant TB surveillance.
- Hospitals:Inpatient settings require rapid turnaround for isolation decisions and treatment initiation. Tertiary hospitals in urban India deploy GeneXpert near intensive care units to accelerate diagnosis in critically ill patients with suspected disseminated TB.
- Clinics:Primary health centers with limited infrastructure favor single-test platforms.
- Research Institutions:Academic medical centers and consortia conduct biomarker discovery and validation studies.
Laboratories anchor the volume base while clinics gain share at the steepest rate through point-of-care decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
WHO prequalification pathways anchor procurement eligibility across endemic regions, with national tuberculosis programs in India, South Africa, Brazil, and Nigeria driving platform selection decisions through consolidated tender specifications.
India
The Revised National Tuberculosis Control Programme mandates biomarker-based confirmation for all presumptive cases, institutionalizing demand through state-level laboratory networks. CDSCO regulates in vitro diagnostic device registration under the Medical Devices Rules, requiring local clinical validation studies. Maharashtra and Gujarat host the densest concentrations of diagnostic laboratories adopting automated sample-prep workflows.
South Africa
The National Health Laboratory Service maintains centralized molecular capacity for multidrug-resistant TB surveillance across nine provinces. The South African Health Products Regulatory Authority enforces quality standards for nucleic acid amplification platforms deployed in public health facilities. Durban and Johannesburg anchor the country's reference laboratory network, processing high-throughput screening for the KwaZulu-Natal and Gauteng provincial programs.
Brazil
ANVISA governs diagnostic device registration through Resolution RDC 687, requiring post-market surveillance for TB detection assays used in the Unified Health System. São Paulo and Rio de Janeiro concentrate the country's molecular diagnostic infrastructure, with state reference laboratories validating LAMP platforms for peripheral health post deployment.
Nigeria
PEPFAR procurement frameworks specify GeneXpert as standard-of-care for presumptive TB diagnosis across sub-Saharan African laboratories, creating locked-in consumable demand. The National Agency for Food and Drug Administration and Control regulates medical device importation and distribution. Lagos and Abuja host the primary reference laboratories coordinating decentralized testing networks.
United States
FDA enforces analytical validation standards for in vitro diagnostic devices used in TB screening programs, tightening evidentiary requirements for predicate device comparisons. The CDC's Division of Tuberculosis Elimination coordinates laboratory response networks. Atlanta and Seattle concentrate academic medical centers conducting biomarker discovery research for pharmaceutical trial endpoints.
Tuberculosis Biomarkers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with consolidated instrument manufacturers competing against emerging point-of-care specialists. The market structure fragments across three tiers: multinational conglomerates with integrated diagnostic portfolios, mid-scale assay developers focused on TB-specific test menus, and research-stage innovators advancing CRISPR-based detection modalities. Dominant competitive moves include strategic partnerships with national procurement programs and technology licensing agreements that accelerate WHO prequalification timelines.
Among Swiss-German diagnostic conglomerates, F. Hoffmann-La Roche and QIAGEN exemplify the integrated-platform archetype, anchoring installed-base strategies that lock laboratories into recurring consumable revenue streams. Danaher Corporation occupies a position representing the diversified life sciences conglomerate model, competing through liquid-handling automation that reduces manual nucleic acid extraction steps. These three players collectively represent the premium-tier vector where sample-prep integration and regulatory compliance capabilities determine procurement eligibility.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| QIAGEN |
| Danaher Corporation |
| bioMérieux |
| Thermo Fisher Scientific |
| Becton Dickinson |
| Hologic |
| Oxford Immunotec |
| Others |
Value Network & Pricing Analysis
Subscription-based reagent supply agreements with embedded technical support lock Indian state-level laboratory networks into multi-year consumable commitments while compressing upfront capital requirements. This contract structure secures predictable cartridge revenue for manufacturers and price visibility for procurement officers managing total cost-per-test budgets under the Revised National Tuberculosis Control Programme.
Pricing Analysis
Price spreads between centralized PCR platforms and point-of-care LAMP systems exceed threefold across Indian and Nigerian procurement tenders. Three-tier pricing structure across premium, standard, and economy levels separates GeneXpert cartridge contracts from ELISA bulk orders and research-grade cytokine panels. Cost compression in the economy tier intensifies as PEPFAR frameworks standardize around nucleic acid amplification specifications. National reference laboratories exhibit lowest price sensitivity due to WHO prequalification compliance requirements, while primary health centers prioritize per-test economics over analytical sensitivity.
Supply Chain Analysis
Polymerase and reverse transcriptase production clusters in contract manufacturers serving broad diagnostic portfolios expose TB-specific assay developers to allocation rationing during pandemic response periods. Reagent supply draws from concentrated production hubs in Germany, the United States, and Singapore, with cold-chain logistics resting on specialized freight networks. Single-source vulnerability in enzyme manufacturing creates bottlenecks when respiratory virus surges trigger cross-portfolio demand spikes. Distribution runs through national procurement frameworks that consolidate volume commitments across sub-Saharan African and South Asian laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent molecular diagnostic platforms face substitution pressure from CRISPR-based detection modalities that compress equipment footprints to handheld dimensions. Breath-based volatile organic compound analysis represents the most credible near-term substitute threat to sputum-dependent molecular workflows.
For Market Incumbents: Consolidate installed-base loyalty through backward integration into automated sample-prep workflows that laboratories adopt prior to detection technology selection. Deepen cartridge revenue lock-in by embedding technical support subscriptions within multi-year reagent supply agreements. Defend against SHERLOCK and DETECTR platform encroachment by accelerating WHO prequalification timelines for next-generation rifampicin resistance screening assays.
For New Entrants and Emerging Players: Anchor in peripheral health facilities where LAMP infrastructure constraints exclude PCR deployment and WHO target product profile compliance remains achievable. Target pediatric and extrapulmonary TB diagnostic white space where sputum-based specimen limitations constrain incumbent molecular sensitivity. Pursue pharmaceutical sponsor partnerships for adaptive clinical trial biomarker endpoint validation as the fastest path to recurring service revenue.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors point-of-care specialists with CRISPR validation capabilities over centralized-platform incumbents. Long-term viability hinges on exposure to breath-based detection modalities and volatile organic compound biosensor development. Watch WHO target product profile specification releases as the critical inflection signal for procurement eligibility shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Acceleration | Compresses technology transfer timelines for cartridge manufacturers seeking PEPFAR procurement eligibility. |
| Sample-Prep Automation Integration | Positions liquid-handling platforms as mandatory infrastructure preceding detection technology selection. |
| Pharmaceutical Sponsor Partnership | Creates longitudinal biobanking revenue streams for laboratories validating adaptive trial biomarker endpoints. |
| Point-of-Care LAMP Deployment | Enables peripheral health post access where cold-chain dependencies exclude PCR infrastructure. |
| CRISPR Diagnostic Validation | Displaces conventional nucleic acid amplification in mobile clinic configurations previously restricted to microscopy. |
Research Methodology
Desk research of WHO prequalification databases, FDA 510(k) filings, and national tuberculosis program tender documents preceded structured interviews with molecular diagnostic R&D directors, laboratory procurement managers, and regulatory affairs specialists across India, South Africa, and Brazil. Primary fieldwork with assay developers and centralized laboratory network administrators was cross-validated against EMA In Vitro Diagnostic Regulation guidance documents and PEPFAR procurement framework specifications. Bottom-up test volume modeling and top-down market sizing were triangulated to constrain projection variance.
Variance decomposition across product type, technology platform, application segment, and end-user facility tier informed the analytical framework over the projection horizon. CAGRs were derived from segmented test volume trajectories and per-test pricing dynamics rather than aggregate market extrapolation. Modeled inputs incorporated WHO target product profile evolution, CDSCO registration pathway timelines, and pharmaceutical sponsor biomarker endpoint adoption curves.
Material uncertainties — regulatory specification changes, pandemic-induced reagent allocation disruptions, and CRISPR platform clinical validation timelines — sit outside the modeled envelope. Forecasts reflect assumptions about procurement framework continuity and technology transfer acceleration that may require revision. Practitioners should keep alternative scenarios live as WHO detection sensitivity thresholds and endemic country laboratory infrastructure investments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
Recombinant Protein Therapeutics CDMO Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Spain Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Anti-Tumor Drugs Market