
 Cancer Drug Market | 2026-2036
Cancer Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Drug Market Insights
Modular combination regimens is hardening as the dominant packaging logic for cancer drug portfolios, replacing standalone monotherapy positioning. Roche leverages its diagnostics-to-therapeutics linkage to anchor bundled testing-and-treatment workflows. Bristol-Myers Squibb competes through sustained investment in checkpoint inhibitor combinations. AstraZeneca differentiates via antibody-drug conjugate specialization across solid tumor categories.
Cancer drugs comprise pharmaceutical agents engineered to selectively kill, arrest, or modulate malignant cell proliferation through mechanisms including DNA intercalation, kinase inhibition, immune checkpoint blockade, or hormone receptor antagonism, with formulations ranging from small-molecule tablets to biologic infusions requiring cold-chain distribution. Immunotherapy now occupies the fastest-expanding margin pool as PD-1/PD-L1 inhibitors displace cytotoxic chemotherapy in first-line settings across multiple tumor types. Targeted therapy leads in revenue concentration where biomarker-defined patient subsets command premium positioning, while chemotherapy sustains volume foundation in resource-constrained care environments.
FDA accelerated approval pathways, EMA adaptive licensing frameworks, and NMPA priority review channels collectively compress development timelines while elevating post-market evidence requirements. These regulatory architectures shape demand by rewarding biomarker-defined subpopulations and penalizing broad-label indications lacking survival benefit. Stakeholders must monitor evolving evidentiary standards for confirmatory trials and the shifting geography of biosimilar substitution pressure.
Market Dynamics
Precision-matched therapy portfolios are forcing pharmaceutical manufacturers to restructure R&D allocation around biomarker-defined patient subsets rather than broad tumor-type indications, compressing addressable populations while elevating pricing power per treated patient.
Growth Catalysts
- FDA Accelerated Approval:The pathway rewards early efficacy signals in defined biomarker populations, enabling commercialization 12-18 months ahead of traditional timelines. Post-market confirmatory trial obligations create sustained revenue capture windows.
- Companion Diagnostic Integration:Testing-to-treatment bundling hardens as the standard care pathway in oncology clinics, locking in therapy selection at the point of diagnosis and reducing switching.
- China NMPA Priority Review:Domestic innovators and multinationals filing in Shanghai and Beijing gain compressed review timelines for novel oncology mechanisms, accelerating patient access and revenue recognition.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for cytotoxic chemotherapies concentrates in Indian and Chinese contract manufacturers, creating single-source vulnerability for generic infusion therapies.
- Biomarker Test Fragmentation:Laboratory-developed tests and FDA-approved companion diagnostics operate under divergent evidentiary standards, complicating reimbursement and creating prescribing friction.
- Biosimilar Substitution Pressure:EMA and national health technology assessment bodies in Germany and France mandate automatic substitution for off-patent biologics, eroding originator maintenance revenue.
Strategic Opportunities
- Radioligand Therapy Convergence:The pairing of tumor-targeting ligands with therapeutic radioisotopes opens solid tumor categories previously resistant to antibody-drug conjugates, with Lu-177 and Ac-225 supply chains as the constraining variable.
- Community Oncology Infusion:Site-of-care migration from hospital outpatient departments to independent community clinics in the United States reduces 340B pricing exposure and captures margin from buy-and-bill arrangements.
- Japan PMDA Sakigake Designation:First-in-Japan development incentives reward early regulatory engagement, creating a viable launch sequence ahead of FDA and EMA filings for Asia-Pacific market establishment.
Industry Challenges
- Translational Biology Talent Scarcity:The gap between preclinical target validation and clinical biomarker strategy requires hybrid skill sets spanning computational pathology and immuno-oncology, with limited supply in Boston and San Francisco talent pools.
- Cold-Chain Distribution Complexity:Cell therapies requiring liquid nitrogen storage and chain-of-identity tracking demand capital-intensive infrastructure that conflicts with traditional pharmaceutical logistics networks.
- Confirmatory Trial Execution Risk:FDA-mandated post-approval studies face enrollment competition and protocol amendment delays, threatening accelerated approval withdrawals and revenue cliff exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Drug Market |
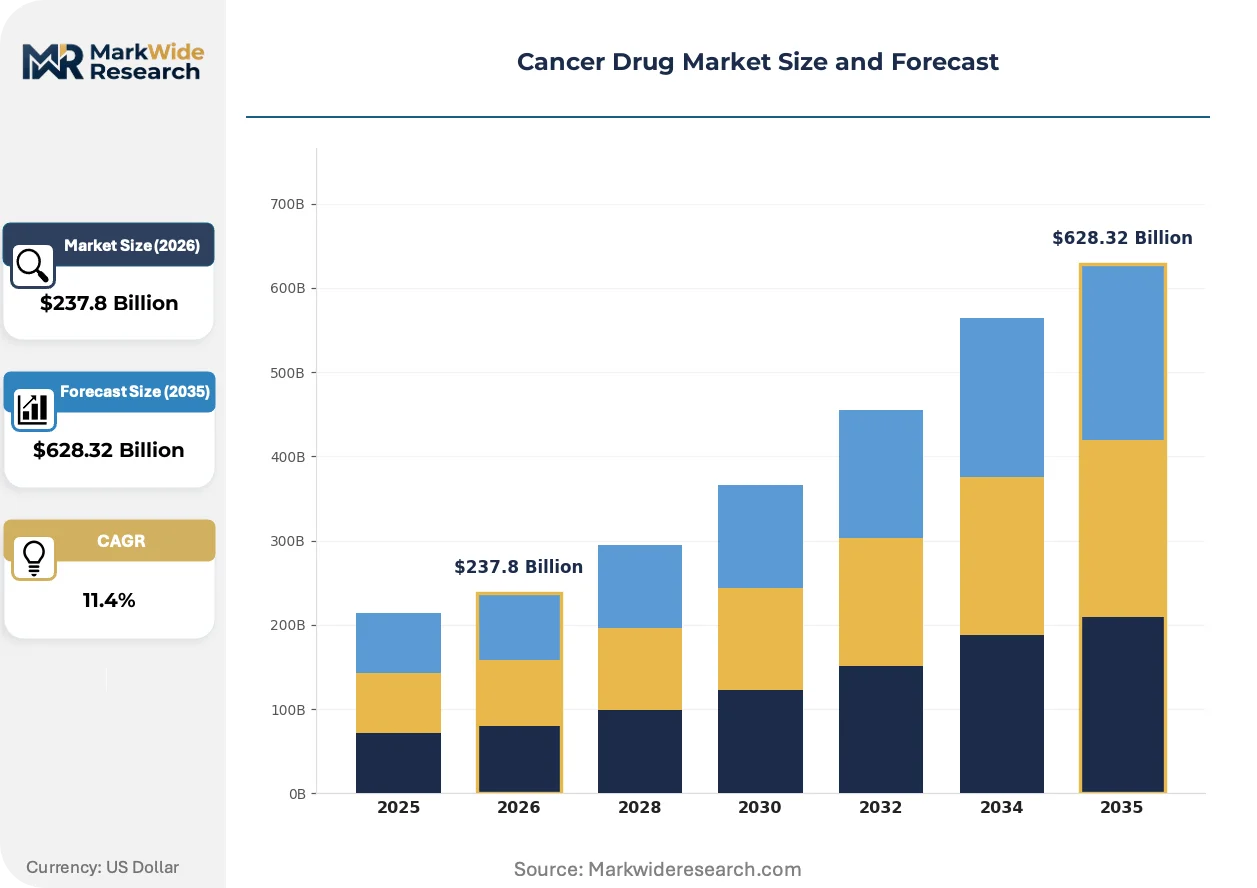
| Market Size in 2026 | $237.8 Billion |
| Market Size in 2035 | $628.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy End User: Oncology Clinics, Hospitals, Research Laboratories, Specialty Pharmacies Administration Route: Oral, Intravenous, Subcutaneous, Topical Indication: Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer |
| Companies Covered | Roche, Novartis, Merck & Co., Pfizer, Bristol-Myers Squibb, AstraZeneca, AbbVie, Eli Lilly and Company, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Drug Market Trends and Innovations
Antibody-drug conjugate engineering is compressing the therapeutic index gap that previously limited cytotoxic payload delivery, enabling dose escalation in solid tumors while sparing hematologic toxicity.
Payload-linker technology is consolidating around site-specific conjugation methods that replace stochastic cysteine or lysine attachment with engineered cysteine residues or enzymatic ligation. Roche, AstraZeneca, and Daiichi Sankyo have advanced proprietary platforms into Phase III programs across breast, lung, and gastric malignancies. This consolidation is compressing the competitive moat available to second-generation entrants lacking differentiated linker stability or bystander-killing profiles.
EMA's adaptive licensing framework is enabling staggered evidence generation where conditional marketing authorization precedes full approval, with Germany's Federal Joint Committee (G-BA) and France's Haute Autorité de Santé integrating early access into health technology assessment timelines. Oncology manufacturers now structure European launch sequences around this staggered evidentiary pathway, prioritizing Germany and France for initial commercialization while building real-world evidence registries.
Hospital pharmacy procurement in the United States is consolidating through group purchasing organization aggregation and specialty pharmacy carve-outs, with three national GPOs now controlling formulary placement for infused oncology therapies. Community oncology practices are responding through vertical integration into dispensing, capturing margin from oral oncolytics and supportive care agents while reducing dependence on buy-and-bill revenue from hospital-affiliated infusion centers.
Cancer Drug Market Segmentation
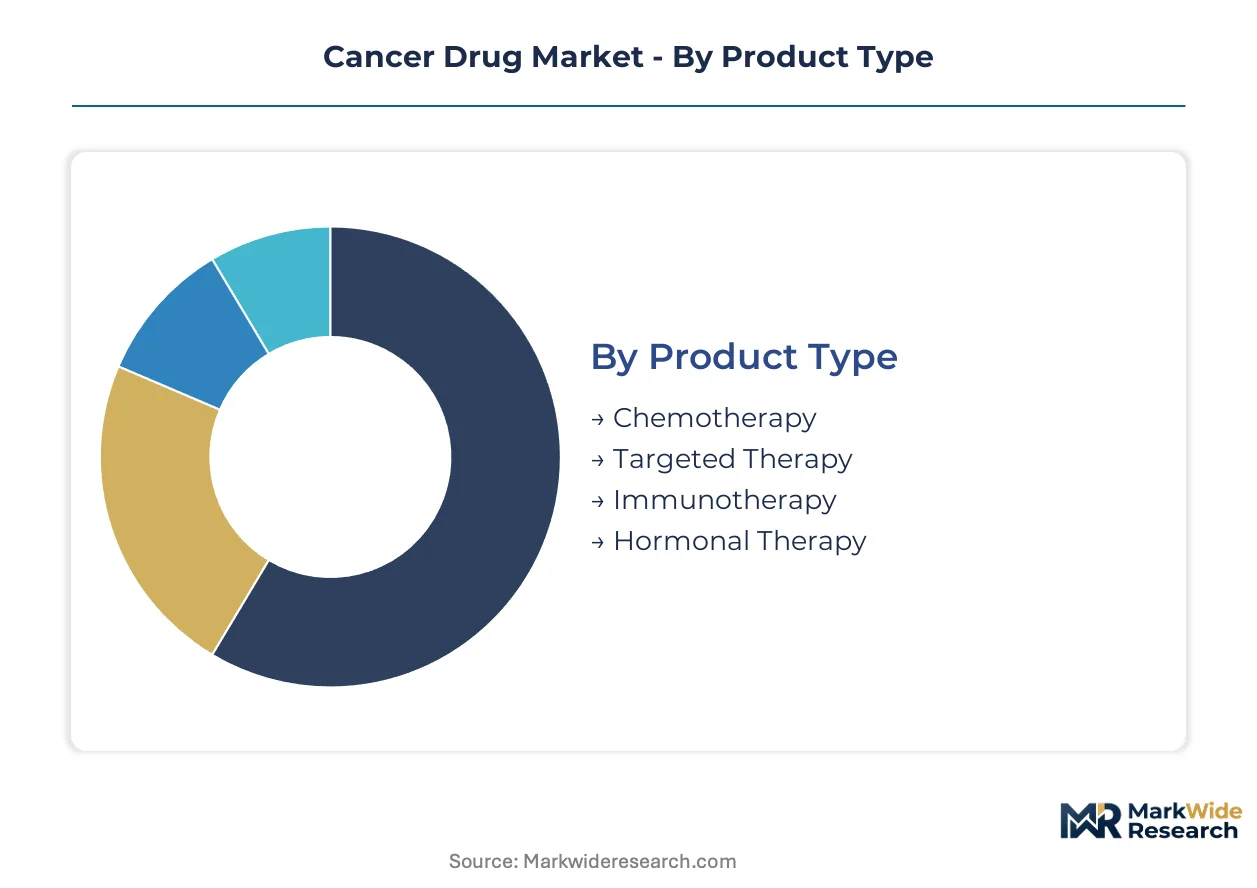
Cancer drug segmentation reflects divergent reimbursement pathways, site-of-care economics, and biomarker testing infrastructure. Manufacturers configure portfolio architectures around administration logistics and prescriber workflow integration rather than molecular mechanism alone.
Product Type:
Buyer differentiation centers on evidence requirements for formulary placement and companion diagnostic bundling obligations.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways command premium positioning through durable response data in melanoma and non-small cell lung cancer. United States oncology clinics drive demand concentration as FDA accelerated approvals compress time-to-reimbursement for biomarker-defined populations.
- Targeted Therapy:Kinase inhibitors and monoclonal antibodies engineered against specific oncogenic drivers require parallel diagnostic adoption. China's NMPA priority review channels accelerate patient access for EGFR and ALK inhibitors in lung cancer, though test penetration lags in tier-2 cities.
- Chemotherapy:Cytotoxic agents sustain volume foundation in resource-constrained environments and combination regimens.
- Hormonal Therapy:Androgen and estrogen receptor antagonists serve prostate and breast cancer maintenance settings with oral convenience.
Chemotherapy leads volumes today; immunotherapy is gaining share fastest.
End User:
Site-of-care migration and procurement consolidation reshape customer economics and distribution requirements.
- Oncology Clinics:Independent community practices capture dispensing margin from oral oncolytics while reducing 340B exposure. United States site-of-care shifts favor infusion-capable clinics with in-house pharmacy operations.
- Hospitals:Academic medical centers anchor Phase I trial enrollment and complex combination protocols. Germany's university hospitals concentrate CAR-T administration through specialized cellular therapy units.
- Specialty Pharmacies:Hub models manage prior authorization and patient adherence for high-cost oral agents.
- Research Laboratories:Preclinical and clinical trial supply chains demand distinct cold-chain and documentation standards.
Hospitals lead volumes today; oncology clinics are expanding most quickly.
Administration Route:
Route selection determines supply chain infrastructure, prescriber training burden, and patient compliance architecture.
- Intravenous:Infusion-dependent biologics require hospital or clinic infrastructure with nursing supervision. United States buy-and-bill arrangements concentrate revenue recognition at hospital outpatient departments.
- Oral:Small-molecule inhibitors enable home administration with specialty pharmacy coordination. Japan's community pharmacy network supports direct patient dispensing with pharmacist-managed adherence monitoring.
- Subcutaneous:Self-administered formulations reduce clinic burden for maintenance therapy.
- Topical:Localized delivery limits systemic exposure for skin malignancies and palliative lesions.
Intravenous leads volumes today; oral formulations show steepest expansion trajectory.
Indication:
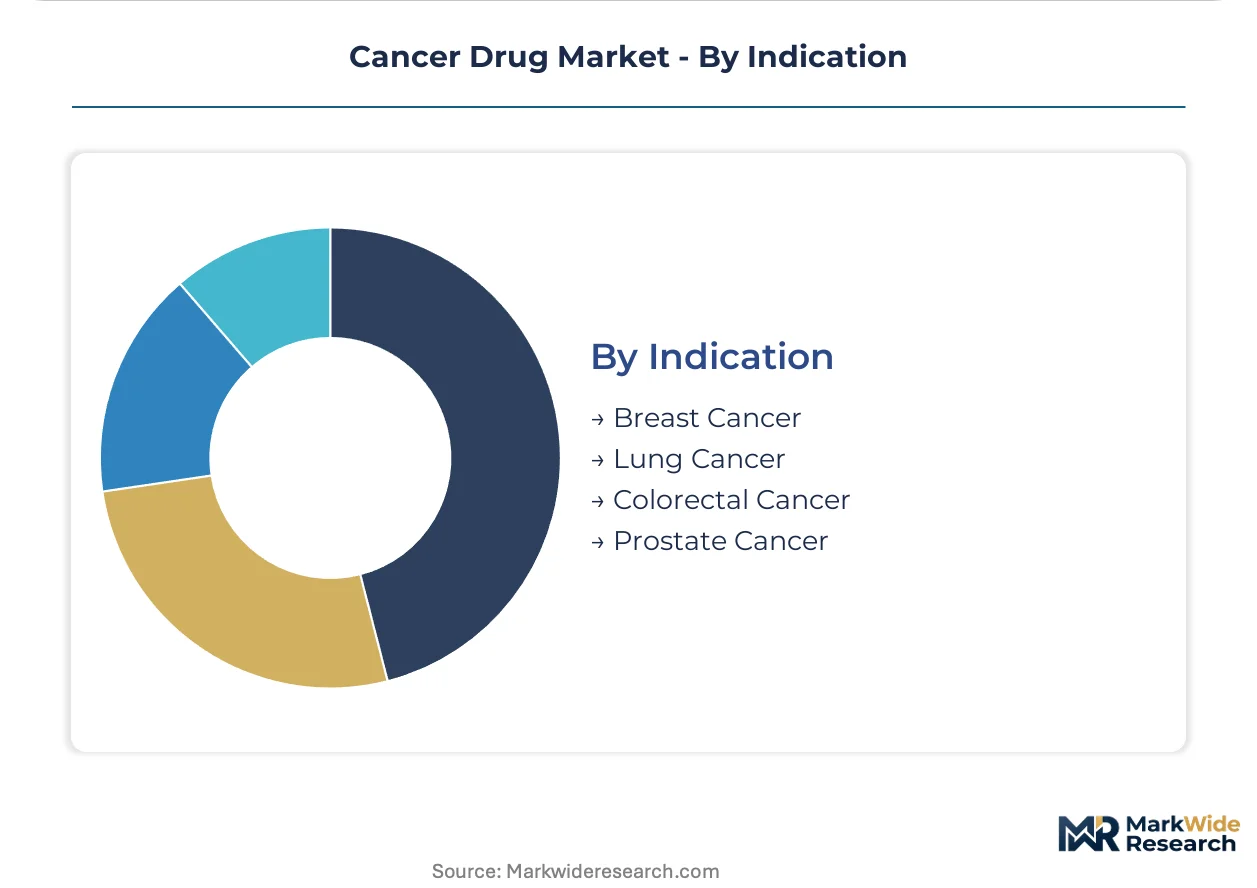
Tumor-specific epidemiology and screening penetration create divergent addressable populations and competitive intensity.
- Lung Cancer:Leading oncology mortality drives concentrated R&D investment across histologies and biomarker subsets. China's high smoking prevalence and CT screening expansion generate volume concentration in Shanghai and Beijing treatment centers.
- Breast Cancer:Established screening infrastructure and HER2-targeted therapy history create mature competitive dynamics. Germany's mammography programs ensure early-stage detection amenable to adjuvant therapy.
- Colorectal Cancer:MSI-high subpopulation opens immunotherapy access in mismatch repair-deficient patients.
- Prostate Cancer:Androgen signaling pathway evolution sustains sequential therapy opportunities.
Lung cancer leads volumes today; colorectal cancer is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cancer drug industry traces its modern commercial roots to Swiss and German chemical synthesis operations of the mid-twentieth century, where nitrogen mustard derivatives first established cytotoxic chemotherapy as a therapeutic category. Basel and Leverkusen became early centers of alkylating agent production before US biotechnology clusters redefined oncology toward targeted monoclonal antibodies and kinase inhibitors.
United States
FDA accelerated approval pathways compress development timelines for biomarker-defined populations, with 12-18 month commercialization advantages rewarding early efficacy signals. The Inflation Reduction Act's Medicare price negotiation provisions reshape revenue projections for oncology therapies losing exclusivity. Boston and San Francisco anchor translational biology talent pools where hybrid computational pathology and immuno-oncology skill sets concentrate.
Germany
The Federal Joint Committee (G-BA) integrates EMA adaptive licensing frameworks into health technology assessment timelines, enabling staggered evidence generation for conditional marketing authorizations. University hospitals concentrate CAR-T administration through specialized cellular therapy units in Berlin, Munich, and Heidelberg. Mannheim and Ludwigshafen host active pharmaceutical ingredient manufacturing for cytotoxic chemotherapies.
China
NMPA priority review channels accelerate patient access for novel oncology mechanisms, with Shanghai and Beijing treatment centers driving volume concentration. CT screening expansion and high smoking prevalence generate lung cancer addressable populations exceeding other tumor types. Domestic innovators filing in Shanghai and Beijing gain compressed review timelines alongside multinational entrants.
Japan
PMDA Sakigake designation rewards first-in-Japan development incentives, creating viable launch sequences ahead of FDA and EMA filings for Asia-Pacific market establishment. Tokyo and Osaka anchor community pharmacy networks supporting direct patient dispensing with pharmacist-managed adherence monitoring. The Kanto region concentrates Phase I trial enrollment for combination protocols.
Switzerland
Swissmedic maintains alignment with EMA centralized procedures while offering national flexibility for radioligand therapy approvals. Basel anchors diagnostics-to-therapeutics linkage capabilities, with bundled testing-and-treatment workflows hardening as standard care pathways. The country's contract manufacturing infrastructure supports cold-chain distribution for biologic infusions requiring liquid nitrogen storage.
Cancer Drug Market Competitive Landscape
Premium-margin players sit above commodity-margin players across biomarker-defined patient subsets versus broad-label indications, with pricing power concentrating where companion diagnostic integration locks therapy selection at diagnosis. The vendor base stratifies into three tiers: integrated diagnostics-therapeutics conglomerates, checkpoint inhibitor combination specialists, and antibody-drug conjugate engineering boutiques. Dominant competitive moves include companion diagnostic bundling obligations and site-of-care migration from hospital outpatient departments to community infusion clinics.
Within the integrated diagnostics-therapeutics tier, Roche and AstraZeneca exemplify divergent platform strategies, with the former anchoring bundled testing-and-treatment workflows and the latter occupying antibody-drug conjugate specialization across solid tumor categories. Bristol-Myers Squibb sits within the checkpoint inhibitor combination specialists, representing sustained investment in PD-1/PD-L1 pathway blockade. These three entities collectively illustrate how proprietary platform consolidation compresses competitive moats available to second-generation entrants lacking differentiated linker stability or bystander-killing profiles.
| Leading Market Players |
|---|
| Roche |
| Novartis |
| Merck & Co. |
| Pfizer |
| Bristol-Myers Squibb |
| AstraZeneca |
| AbbVie |
| Eli Lilly and Company |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Active pharmaceutical ingredient manufacturing costs for cytotoxic chemotherapies flow from Indian and Chinese contract manufacturers through tiered pricing structures, with originator biologics commanding premium positioning against eroding generic infusion therapies in European markets.
Pricing Analysis
Value-based pricing stratification across premium, standard, and economy tiers separates checkpoint inhibitors with companion diagnostic bundling from commoditized cytotoxic agents. Price differentiation rests on biomarker-defined patient eligibility and FDA accelerated approval status. Pricing pressure stems from EMA-mandated automatic substitution for off-patent biologics in Germany and France. Hospital pharmacy procurement through group purchasing organizations exhibits highest price sensitivity; oncology clinics with captive dispensing operations demonstrate lowest.
Supply Chain Analysis
Certification gating through FDA, EMA, and NMPA approval pathways fragments global distribution networks for biologic infusions requiring cold-chain integrity. API manufacturing concentrates in India, China, and Switzerland for cytotoxic and biologic categories. Supply chains draw from Lu-177 and Ac-225 radioisotope sources, monoclonal antibody cell lines, and synthetic small-molecule precursors. Single-source vulnerability in Indian generic API production poses structural risk. Distribution runs through hospital outpatient departments, community infusion clinics, and specialty pharmacy hub models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cancer drug market represents a late-cycle quality story as precision-matched therapy portfolios shift demand toward biomarker-validated premium therapeutics with durable response data.
For Market Incumbents: Hedge against biosimilar substitution pressure by deepening companion diagnostic bundling obligations that lock therapy selection at diagnosis. Anchor defensive positioning through backward integration into radioligand therapy isotope supply chains, capturing margin from Lu-177 and Ac-225 distribution constraints.
For New Entrants and Emerging Players: Enter via site-of-care migration to community oncology infusion clinics in the United States, where 340B pricing exposure reduction creates margin capture opportunities. Target radioligand therapy convergence in solid tumors previously resistant to antibody-drug conjugates, leveraging Japan PMDA Sakigake designation for Asia-Pacific market establishment ahead of FDA filings.
For Investors and Strategic Acquirers: Consolidation pressure builds where confirmatory trial execution risk threatens accelerated approval withdrawals and revenue cliff exposure. Five-to-ten-year viability favors antibody-drug conjugate engineering boutiques with proprietary linker platforms. Watch FDA post-market study enrollment competition as inflection signal for portfolio impairment.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Locks therapy selection at diagnosis through bundled testing-and-treatment workflows in oncology clinics. |
| Radioligand Therapy Scale-Up | Opens solid tumor categories via Lu-177 and Ac-225 supply chain capture in Basel and Mannheim hubs. |
| Community Infusion Site Migration | Reduces 340B pricing exposure while capturing margin from buy-and-bill arrangements outside hospital systems. |
| EMA Adaptive Licensing Pathway | Enables staggered evidence generation with conditional marketing authorization preceding full G-BA assessment. |
| Cell Therapy Cold-Chain Infrastructure | Resolves distribution complexity for liquid nitrogen storage and chain-of-identity tracking requirements. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases; and customs trade data — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across patient population segments, administration routes, and regional regulatory clusters generated volume and value outputs over the projection horizon. CAGRs were derived from modeled adoption curves for immunotherapy, targeted therapy, and chemotherapy categories, incorporating NMPA priority review timelines and biosimilar substitution elasticity assumptions.
Inputs from clinical trial registries and payer access databases were available through the study window; gaps in real-world evidence generation for confirmatory trials introduce uncertainty bands around accelerated approval sustainability. Deviation in FDA post-market study completion rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
HIV Drugs Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Vaccine Adjuvants Market
Biopharmaceuticals
Tamiflu (Oseltamivir Phosphate) Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Discovery Bioanalysis Market